
 Global Microbial Products Market | 2026-2036
Global Microbial Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbial Products Market Foresight
Pharmaceutical-grade microbial products is bifurcating the competitive landscape as buyers separate GMP-certified suppliers from commodity producers. Novozymes A/S leverages its enzyme manufacturing scale to dominate industrial biotechnology segments. Thermo Fisher Scientific Inc. anchors its position through upstream control over cell culture media and reagent supply chains. BASF SE differentiates via specialty microbial strains for agricultural and nutritional applications.
Microbial products encompass metabolites, biomass, and derivatives generated through controlled fermentation or cultivation of bacteria, fungi, algae, and other microorganisms, typically requiring cell densities exceeding 10^9 CFU per milliliter for therapeutic-grade outputs. These products serve as active ingredients in therapeutics, soil amendments, biocatalysts, and environmental remediation systems where synthetic chemistry proves uneconomical or non-biodegradable. Enzymes and probiotics capture the deepest margin pools due to recurring formulation demand and patent-protected strain libraries. Biopesticides represent the fastest-growing application segment as residue-conscious food manufacturers pressure crop producers to replace synthetic agrochemicals. Bioremediation agents remain structurally underdeveloped outside OECD-funded environmental cleanup programs.
FDA, EMA, and CDSCO collectively tighten purity and potency standards for microbial-derived pharmaceuticals, forcing manufacturers to validate strain identity through whole-genome sequencing before market authorization. The EU Green Deal and REACH frameworks restrict petrochemical inputs in agriculture and wastewater treatment, expanding addressable demand for certified biofertilizers and bioremediation agents. Stakeholders must monitor evolving strain patent landscapes and regulator-specific GMP annexes to avoid supply interruptions during facility qualification.
Market Dynamics
Strain patent cliffs and GMP certification bottlenecks are concentrating supply power among vertically integrated fermentation houses, forcing mid-tier manufacturers into toll-manufacturing relationships or exit.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon coolants in industrial refrigeration redirects capital toward enzyme-based biocatalytic processes that operate at ambient temperatures.
- Biologics pipeline expansion:Contract development organizations in India and Germany are commissioning multi-thousand-liter microbial fermentation capacity to supply monoclonal antibody precursors and vaccine adjuvants.
- CRISPR-edited strain libraries:Precision genome engineering compresses product development cycles for specialty enzymes, enabling faster regulatory submission timelines at FDA and EMA.
Market Restraints
- Glucose and nitrogen feedstock volatility:Corn syrup and yeast extract prices swing with agricultural commodity cycles, compressing margins for commodity enzyme producers without long-term supply contracts.
- Chinese fermentation capacity dominance:Concentration of industrial-scale bioreactor infrastructure in Shandong and Jiangsu provinces creates single-source vulnerability for global enzyme and amino acid supply chains.
- Whole-genome sequencing validation mandates:FDA and EMA now require complete genomic characterization of production strains, adding six to twelve months to facility qualification timelines.
Strategic Opportunities
- India's PLI scheme for biotechnology:Production-linked incentives covering microbial enzyme and active pharmaceutical ingredient manufacturing attract greenfield investment in Maharashtra and Telangana.
- Bioremediation for per- and polyfluoroalkyl substances:Engineered bacterial consortia capable of degrading PFAS compounds represent unaddressed demand from US Department of Defense cleanup budgets and European wastewater utilities.
- Precision fermentation-meets-cellular agriculture convergence:Dairy protein and collagen producers are licensing microbial chassis originally developed for pharmaceutical applications, opening food-grade capacity utilization.
Industry Challenges
- PhD-level fermentation scientist scarcity:Talent pipelines in metabolic engineering and bioprocess scale-up lag capacity expansion, particularly in emerging manufacturing clusters.
- Multi-product facility changeover complexity:GMP-validated cleanrooms require extensive cleaning validation between therapeutic-grade and industrial-grade production campaigns, constraining asset utilization.
- Strain licensing disputes:CRISPR patent thickets and academic technology transfer negotiations delay commercial access to high-yielding microbial platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbial Products Market |
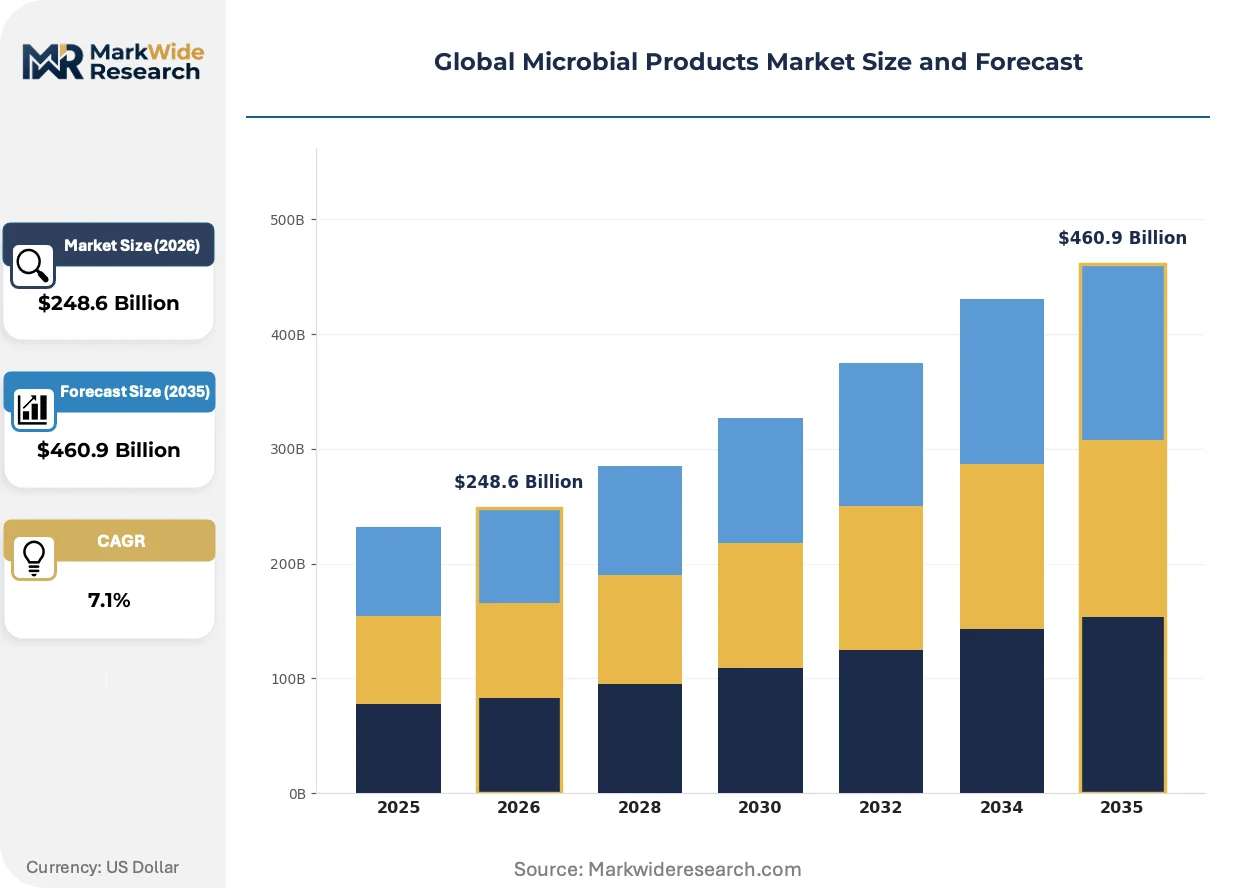
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $460.9 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Biofertilizers, Biopesticides, Enzymes, Bioremediation Agents Application: Agriculture, Wastewater Treatment, Food & Beverage, Pharmaceuticals, Animal Feed End User: Crop Producers, Water Treatment Plants, Food Manufacturers, Pharmaceutical Companies, Livestock Farms Form: Liquid, Powder, Granules, Pellets, Capsules |
| Companies Covered | Novozymes A/S, Thermo Fisher Scientific Inc., BASF SE, Merck KGaA, bioMérieux SA, Lallemand Inc., Bayer AG, Valent BioSciences LLC, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbial Products Market Shifts & Advancements
Continuous processing architectures and real-time metabolite monitoring are displacing batch fermentation as the default manufacturing paradigm, compressing capital intensity per kilogram of output.
Synthetic biology platforms are bifurcating the enzyme market into catalog-standard products and bespoke engineered variants. Specialty chemical manufacturers now specify amino acid substitutions for thermal stability or solvent tolerance. Pharmaceutical formulators commission unique glycosylation patterns for half-life extension. The technology is bifurcating supplier tiers, separating strain-owning innovators from toll manufacturers.
REACH authorization requirements for persistent organic pollutants are tightening discharge standards across European chemical parks. Industrial wastewater treatment operators must demonstrate biodegradability of process streams. Bioaugmentation with specialized bacterial consortia satisfies compliance while avoiding capital-intensive physical-chemical treatment upgrades. German and Dutch integrated chemical sites lead adoption, with BASF and DSM facilities serving as reference installations.
Certification-driven procurement now governs agricultural microbial inputs. Food manufacturers audit crop suppliers for residue compliance, propagating requirements backward to biofertilizer and biopesticide vendors. CDSCO and FSSAI in India have harmonized strain registration protocols, reducing dual-track regulatory burden for exporters. Brazilian and Argentine soybean producers increasingly specify ANVISA-registered biologicals to maintain EU and Japanese grain export eligibility.
Global Microbial Products Market Segmentation
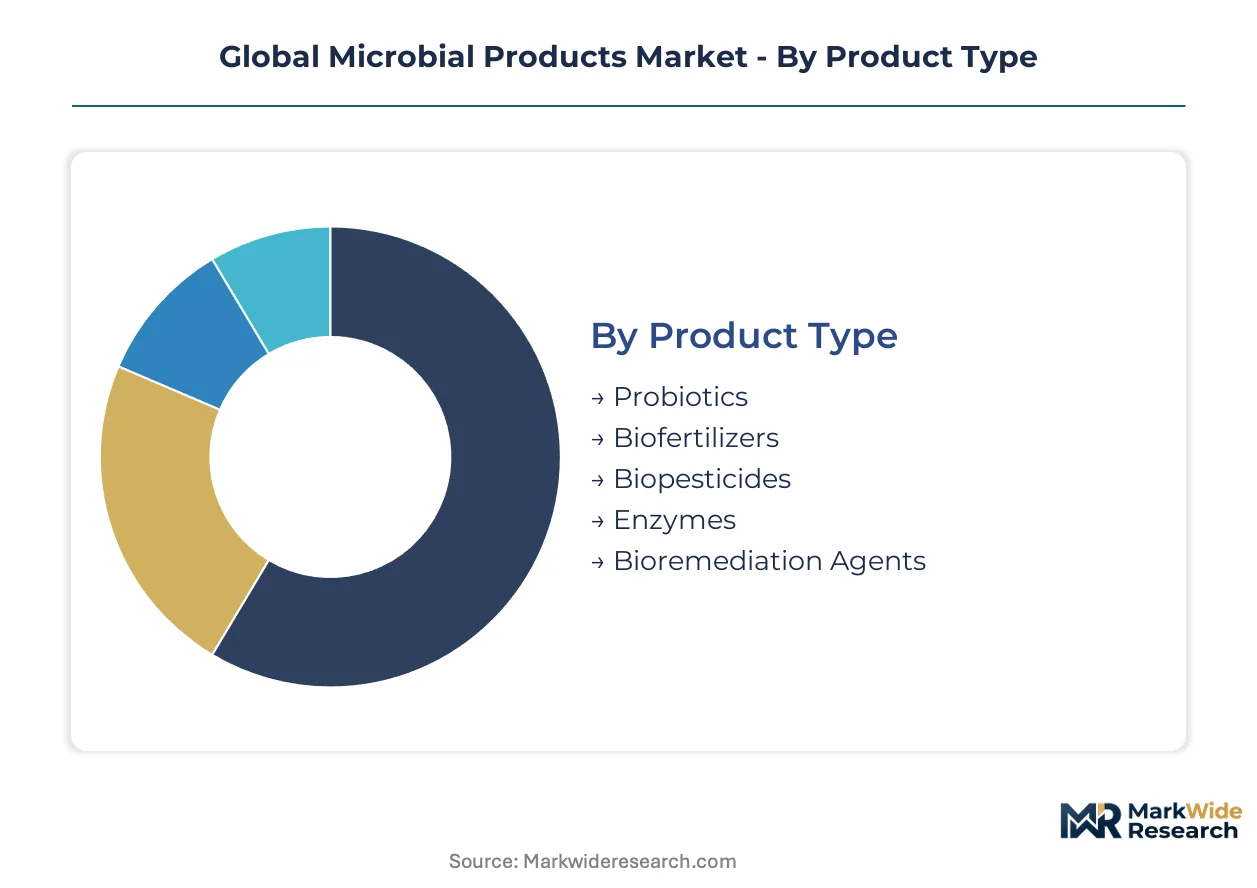
Segmentation in microbial products determines regulatory pathway complexity, margin structure, and channel access. Pharmaceutical-grade outputs command GMP-certified supply chains, while agricultural applications flow through distributor networks with certification audits. Understanding these segment boundaries protects against capacity misallocation and compliance failures.
Product Type:
Channel-mix varies sharply across product types, with enzymes and probiotics dominating direct B2B pharmaceutical contracts while biofertilizers and biopesticides move through agricultural distribution cooperatives.
- Enzymes:Protein catalysts derived from bacterial or fungal fermentation, typically produced at industrial scale exceeding 10,000 liters per batch. Pharmaceutical formulators in Germany and India commission bespoke glycosylation variants for half-life extension in biologics. FDA and EMA whole-genome sequencing mandates for production strains compress supplier lists to vertically integrated fermentation houses.
- Probiotics:Live microbial preparations requiring cell viability above 10^9 CFU per gram through shelf life. Dairy and supplement manufacturers in the US and France drive formulation demand, with CDSCO and FSSAI harmonization in India reducing dual-track registration burdens for exporters.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing inoculants applied to seed or soil. Soybean producers in Brazil specify ANVISA-registered strains to maintain EU grain export eligibility.
- Biopesticides:Microbial agents targeting agricultural pests through competition, antibiosis, or parasitism. Residue-conscious food manufacturers pressure crop producers to replace synthetic agrochemicals.
- Bioremediation Agents:Engineered bacterial consortia degrading pollutants in soil and water. US Department of Defense cleanup budgets and European wastewater utilities represent concentrated demand pockets.
By volume, enzymes lead. By growth pace, biopesticides are expanding most quickly.
Application:
Cost-tier stratification separates therapeutic applications with GMP overhead from agricultural and environmental uses where commodity pricing dominates.
- Pharmaceuticals:Microbial-derived active ingredients and biologics requiring strain identity validation through whole-genome sequencing. Contract development organizations in India and Germany commission multi-thousand-liter fermentation capacity.
- Agriculture:Soil amendments and crop protection inputs where certification-driven procurement governs vendor selection. EU Green Deal restrictions on petrochemical fertilizers expand addressable demand.
- Wastewater Treatment:Bioaugmentation with specialized consortia satisfying REACH biodegradability requirements. German and Dutch integrated chemical sites lead adoption.
- Food & Beverage:Fermentation-derived ingredients and probiotic fortification. Precision fermentation-meets-cellular agriculture convergence opens food-grade capacity utilization.
- Animal Feed:Gut health promoters and nutrient digestibility enhancers. Livestock farms in feed-conversion-efficiency programs drive recurring demand.
Pharmaceuticals capture the deepest margin pools. Wastewater treatment is climbing the fastest as discharge standards tighten.
End User:
Customer-type concentration shapes sales force deployment, with pharmaceutical companies requiring technical service depth and crop producers demanding distributor proximity.
- Pharmaceutical Companies:Buyers of microbial-derived biologics and active ingredients with mandatory GMP certification. Strain patent cliffs and facility qualification bottlenecks concentrate supply power among integrated fermentation houses.
- Crop Producers:End-users of biofertilizers and biopesticides audited by downstream food manufacturers for residue compliance.
- Water Treatment Plants:Municipal and industrial operators deploying bioremediation agents for persistent pollutant degradation.
- Food Manufacturers:Formulators of probiotic-enhanced dairy and supplement products with strain-specific health claims.
- Livestock Farms:Operations seeking feed conversion efficiency through microbial gut health promoters.
Pharmaceutical companies dominate value capture. Water treatment plants are gaining share fastest on regulatory compliance spending.
Form:
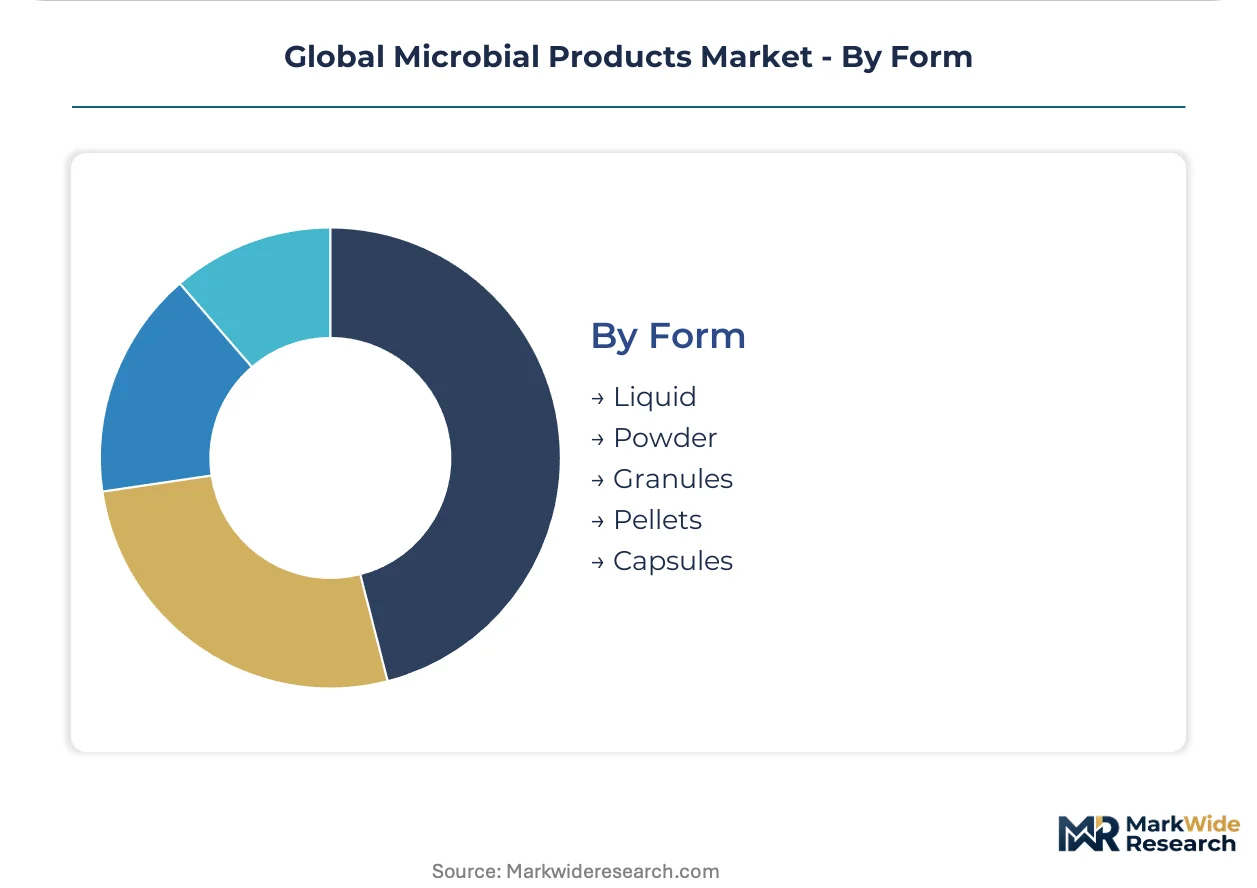
Supply concentration clusters around liquid and powder outputs, with specialized solid forms requiring additional formulation investment.
- Liquid:Ready-to-use suspensions and concentrates dominating industrial enzyme and bioremediation agent delivery. Ambient-temperature biocatalytic processes avoid F-Gas-regulated refrigeration.
- Powder:Spray-dried preparations with extended stability for probiotics and feed additives. India's PLI scheme attracts greenfield spray-drying investment in Maharashtra.
- Granules:Dust-free carriers for agricultural soil application. Brazilian soybean producers specify flowable formulations for mechanized planting.
- Pellets:Compressed forms for controlled-release nutrient delivery. Specialty biofertilizer applications in precision agriculture.
- Capsules:Unit-dose delivery for pharmaceutical and supplement probiotics. CDSCO registration protocols govern enteric coating specifications.
Liquid forms lead by volume. Capsules are expanding most quickly on pharmaceutical pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in three distinct geographies, with regulatory divergence creating arbitrage opportunities for manufacturers qualifying under multiple jurisdictions. CDSCO, FDA, and EMA each impose strain validation protocols that extend facility timelines by six to twelve months.
United States
Defense cleanup budgets and pharmaceutical pipeline expansion drive bioremediation agent and biologics precursor procurement. EPA discharge standards for PFAS degradation push wastewater utilities toward engineered bacterial consortia. The Boston-Cambridge corridor anchors contract fermentation capacity serving monoclonal antibody manufacturers.
Germany
REACH authorization requirements for persistent organic pollutants accelerate bioaugmentation adoption at integrated chemical sites. EMA whole-genome sequencing mandates for production strains compress supplier lists to vertically integrated houses. The Rhine-Ruhr and Ludwigshafen clusters host reference installations for industrial wastewater bioaugmentation.
China
Industrial-scale bioreactor infrastructure in Shandong and Jiangsu provinces supplies global enzyme and amino acid demand. NMPA alignment with ICH guidelines streamlines microbial-derived pharmaceutical approvals for domestic innovators. Concentrated fermentation capacity creates single-source vulnerability for international buyers.
India
PLI scheme incentives covering microbial enzyme and active pharmaceutical ingredient manufacturing attract greenfield investment. CDSCO-FSSAI harmonization reduces dual-track registration burdens for probiotic exporters. Maharashtra and Telangana host expanding multi-thousand-liter fermentation capacity commissioned by contract development organizations.
Brazil
Soybean producers specify ANVISA-registered biofertilizers and biopesticides to maintain EU and Japanese grain export eligibility. Residue-conscious food manufacturers audit crop suppliers, propagating certification requirements backward to microbial input vendors. The Mato Grosso and Rio Grande do Sul agricultural belts concentrate bioinput demand.
Global Microbial Products Market Competitive Landscape
Concentration sits with vertically integrated fermentation houses possessing GMP-certified capacity and proprietary strain libraries. Mid-tier manufacturers face toll-manufacturing relationships or exit as patent cliffs and facility qualification bottlenecks intensify. Two archetypes dominate: enzyme specialists leveraging manufacturing scale, and diversified life science conglomerates controlling upstream reagent supply chains. Competitive moves center on capacity expansion in India and Germany, plus precision fermentation technology licensing.
Among Danish and American biotechnology leaders, Novozymes A/S and Thermo Fisher Scientific Inc. occupy positions reflecting divergent strategic anchors. Novozymes exemplifies the manufacturing-scale archetype, while Thermo Fisher represents upstream supply chain control. German chemical conglomerates BASF SE and Bayer AG sit within the diversified industrial biotechnology tier, leveraging specialty strain development for agricultural applications. Merck KGaA and bioMérieux SA anchor the pharmaceutical-grade diagnostics and reagent segment, with Lallemand Inc. representing the probiotics and fermentation-derived nutrition specialization.
| Leading Market Players |
|---|
| Novozymes A/S |
| Thermo Fisher Scientific Inc. |
| BASF SE |
| Merck KGaA |
| bioMérieux SA |
| Lallemand Inc. |
| Bayer AG |
| Valent BioSciences LLC |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Enzyme-based biocatalytic processes replacing hydrofluorocarbon-dependent refrigeration simultaneously relocate production toward ambient-temperature fermentation clusters in India and Germany while compressing energy cost components in unit economics. This substitution dynamic reconfigures both geographic supply priorities and margin structures across therapeutic-grade and industrial-grade output tiers.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across the microbial products landscape. Three-tier pricing structure across GMP-certified premium, technical-grade standard, and commodity economy levels separates pharmaceutical formulators from agricultural distributors. Cost compression in commodity enzyme tiers is intensifying because glucose and nitrogen feedstock volatility swings with agricultural cycles. Pharmaceutical companies demonstrate the lowest price sensitivity due to regulatory compliance mandates, while crop producers in distributor networks exhibit acute sensitivity to per-hectare input costs.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for strain libraries and specialized culture media. Supply concentrates in China, India, and Germany, with industrial-scale bioreactor infrastructure in Shandong and Jiangsu provinces feeding global enzyme demand. The supply chain draws from corn syrup, yeast extract, and precision-engineered bacterial consortia as critical inputs. Single-source vulnerability from Chinese fermentation capacity dominance poses structural risk. Distribution runs through vertically integrated fermentation houses for pharmaceutical-grade outputs and agricultural cooperatives for soil amendment products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against synthetic chemistry substitution as petrochemical feedstock pricing volatility and REACH authorization requirements create competitive pressure from bio-based alternatives.
For Market Incumbents: Fortify proprietary strain libraries through CRISPR-edited platform investments and captive supply of cell culture media to lock in upstream control. Secure GMP-certified capacity expansion in Maharashtra and Telangana ahead of CDSCO facility qualification bottlenecks. Patent cliff exposure on high-yielding production strains demands accelerated whole-genome sequencing validation to compress regulatory timelines. For New Entrants and Emerging Players: Anchor in bioremediation agent development for PFAS degradation, where US Department of Defense cleanup budgets and European wastewater utility procurement remain structurally underdeveloped. Precision fermentation technology licensing from pharmaceutical chassis owners opens food-grade capacity utilization with lower regulatory barriers than therapeutic-grade entry. Direct technical service relationships with industrial wastewater operators bypass entrenched distributor networks. For Investors and Strategic Acquirers: EMA and FDA alignment on whole-genome sequencing mandates reshapes the acquisition landscape toward vertically integrated fermentation houses with validated strain identity protocols. Five-to-ten year viability favors platforms combining synthetic biology capabilities with GMP-certified manufacturing infrastructure. Monitor CDSCO facility approval timelines as inflection indicator for supply concentration shifts in contract manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Edited Strain Library Expansion | Precision genome engineering compresses FDA and EMA submission timelines for specialty enzymes. |
| GMP-Certified Capacity Buildout in India | PLI scheme incentives in Maharashtra attract greenfield multi-thousand-liter fermentation investment. |
| Precision Fermentation Technology Licensing | Dairy protein producers license pharmaceutical-grade microbial chassis for food-grade capacity utilization. |
| Long-Term Feedstock Supply Agreement | Corn syrup and yeast extract contracts insulate margin structures from agricultural commodity cycles. |
| Bioremediation Agent Regulatory Approval Pathway | Engineered bacterial consortia for PFAS degradation access US Department of Defense cleanup budgets. |
Research Methodology
A spread of perspectives from fermentation scientists, regulatory affairs leads at CDSCO and EMA, contract manufacturing executives, and agricultural distributor procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submission databases, CDSCO strain registration protocols, and customs trade data on fermentation equipment imports. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Segmentation dimensions modeled include product type, application vertical, end-user category, and geographic regulatory cluster across the analysis window. CAGRs derived from historical capacity utilization trends, patent expiration schedules, and regulatory implementation timelines. Industry-specific forecast inputs incorporated PLI scheme disbursement trajectories and REACH authorization phase-down schedules for persistent organic pollutants.
Underlying assumptions cover sustained EMA-FDA alignment on whole-genome sequencing mandates, with deviation risk concentrated in feedstock commodity price volatility and Chinese export license restrictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Global Starter Culture Market