
 Microbiomes Market | 2026-2036
Microbiomes Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiomes Market Insights
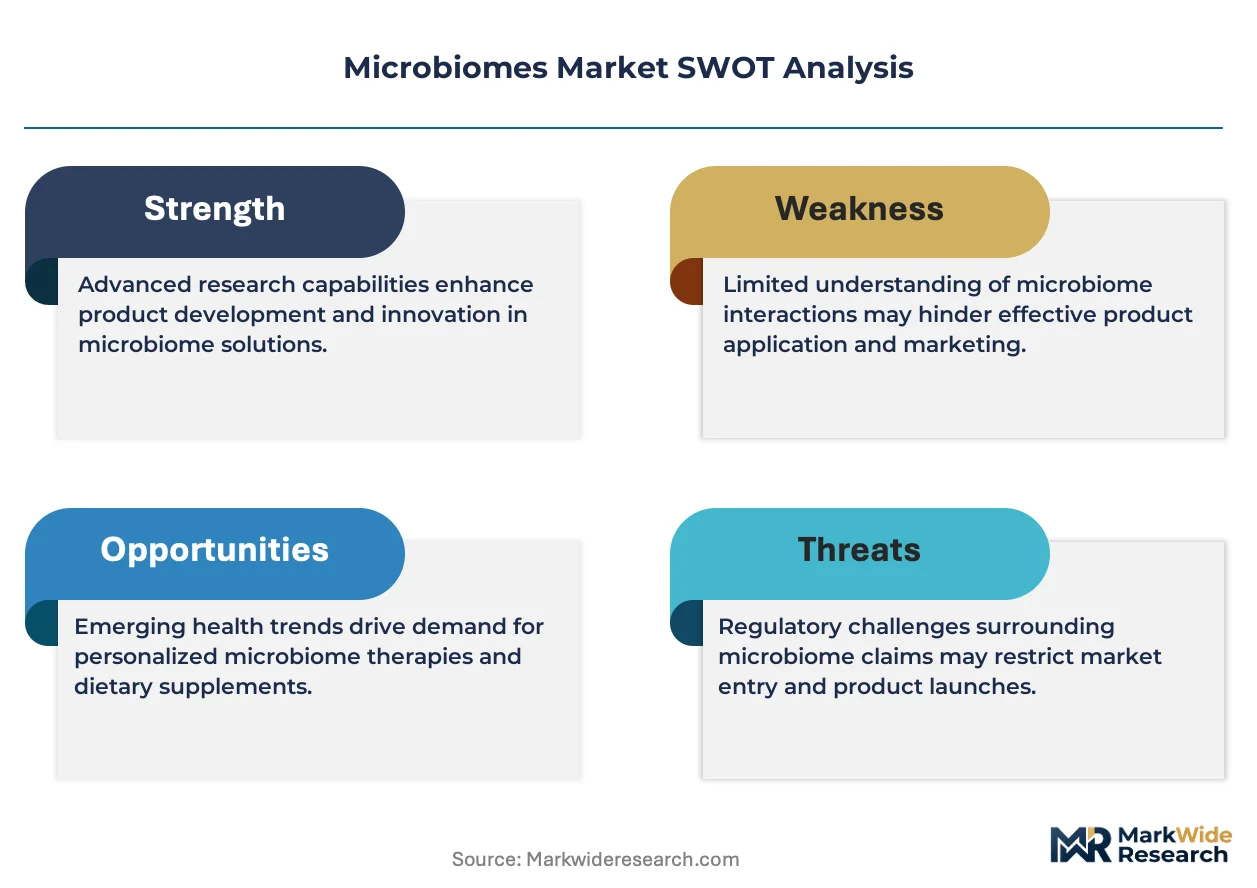
Good Manufacturing Practice certification for live biotherapeutic products is redrawing competitive boundaries in microbiome therapeutics. Seres Therapeutics leverages end-to-end manufacturing control to sustain pipeline momentum. Vedanta Biosciences anchors its position through rationally designed bacterial consortia. 4D pharma competes via proprietary MicroRx platform discovery capabilities.
Microbiomes comprise complex communities of bacteria, archaea, fungi, and viruses colonizing host environments, with human gut microbiota alone harboring over 1,000 species whose metabolic outputs influence immune modulation and nutrient processing. Probiotics dominate current revenue as established consumer and clinical formats, while metagenomics sequencing drives fastest growth by enabling strain-level characterization of previously unculturable organisms. Healthcare applications command premium margins due to regulatory rigor and reimbursement potential, whereas agriculture segments expand through soil inoculant adoption.
FDA's emerging guidance on live biotherapeutic products and EMA's qualification pathway for microbiome biomarkers shape trial design and market access timelines. The EU Green Deal's farm-to-fork sustainability targets indirectly boost agricultural microbiome inputs by restricting chemical fertilizer dependence. Stakeholders must monitor regulatory convergence between food-grade probiotic claims and pharmaceutical-grade therapeutic standards.
Market Dynamics
Live biotherapeutic manufacturing certification is compressing competitive timelines as FDA and EMA accelerate qualification pathways, forcing developers to secure end-to-end GMP control before clinical readouts rather than after.
Growth Catalysts
- FDA Live Biotherapeutic Guidance:The agency's emerging framework for microbiome-based drugs is compressing IND-to-approval timelines by clarifying CMC requirements for complex consortia products.
- EU Green Deal Farm-to-Fork Targets:Chemical fertilizer reduction mandates across member states are pulling agricultural microbiome inputs into mainstream crop management protocols.
- Metagenomics Sequencing:Strain-level characterization of unculturable organisms is opening previously inaccessible therapeutic targets for rational consortium design.
Market Restraints
- Donor Material Variability:Fecal microbiota sourcing constraints create batch-to-batch inconsistency that complicates CMC dossiers for FMT-derived products.
- Cold Chain Infrastructure Gaps:Live biotherapeutic stability requirements expose distribution networks in lower-tier healthcare systems to potency loss risks.
- Reimbursement Uncertainty:Payer categorization disputes between food-grade supplements and pharmaceutical therapeutics delay formulary placement for prescription microbiome products.
Strategic Opportunities
- Immuno-oncology Combination Protocols:Checkpoint inhibitor non-responder populations represent addressable white space for microbiome modulation adjunct therapy.
- India CDSCO Fast-Track Pathway:The regulator's accelerated approval track for unmet-need biologics offers reduced clinical data requirements for first-in-class live therapeutics.
- Soil Carbon Credit Markets:Agricultural microbiome inoculants that demonstrably enhance carbon sequestration qualify for emerging environmental credit monetization schemes.
Industry Challenges
- Consortia Stability Modeling:Predictive frameworks for multi-strain community dynamics in vivo remain underdeveloped, forcing empirical formulation iteration.
- Pharmaceutical-Grade Manufacturing Talent:GMP expertise scarcity at the intersection of live culture handling and biologics production constrains pipeline expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiomes Market |
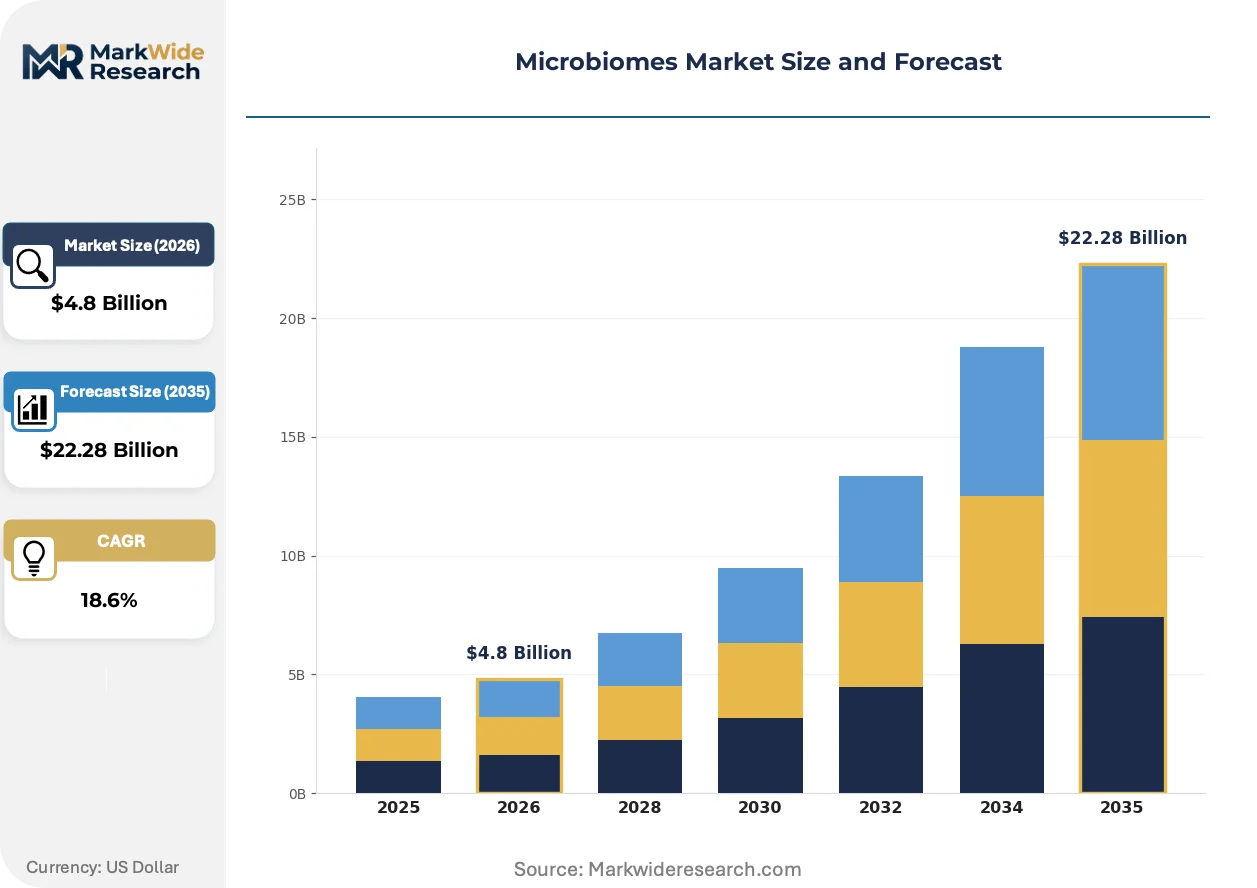
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Postbiotics Application: Healthcare, Agriculture, Food & Beverage, Animal Nutrition End User: Hospitals, Research Institutions, Food Manufacturers, Farmers Technology: Genomics, Metagenomics, Bioinformatics, Sequencing |
| Companies Covered | Seres Therapeutics, 4D pharma, Vedanta Biosciences, Ferring B.V., Finch Therapeutics Group, Enterome, Microbiotica, OpenBiome, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiomes Market Trends and Innovations
Microbiome therapeutics are pivoting from empirical fecal transfer toward precision-engineered bacterial consortia, with manufacturing and analytical capabilities now determining competitive position more than discovery biology.
Single-cell sequencing combined with machine learning strain selection is miniaturizing the discovery-to-candidate timeline by enabling direct functional profiling of individual bacteria without cultivation bottlenecks. Academic medical centers in the United States are adopting these platforms for patient stratification in oncology trials. The technology is compressing the traditional 18-24 month strain characterization cycle into 6-9 month workflows.
EMA's qualification pathway for microbiome biomarkers is formalizing surrogate endpoint acceptance for inflammatory indications, reducing Phase 3 duration requirements for developers targeting ulcerative colitis and Crohn's disease. The framework incentivizes prospective biomarker validation alongside clinical development rather than post-hoc analysis. European trials are increasingly incorporating these qualified endpoints into adaptive designs.
Hospital formulary committees are unbundling microbiome therapeutics from traditional infectious disease procurement categories, creating standalone evaluation tracks that assess live biotherapeutics on distinct value metrics including antibiotic-sparing potential. This reclassification is visible most acutely in United States academic medical centers managing recurrent C. difficile populations. Specialty pharmacy distribution channels are capturing volume that previously flowed through wholesale distributors.
Microbiomes Market Segmentation
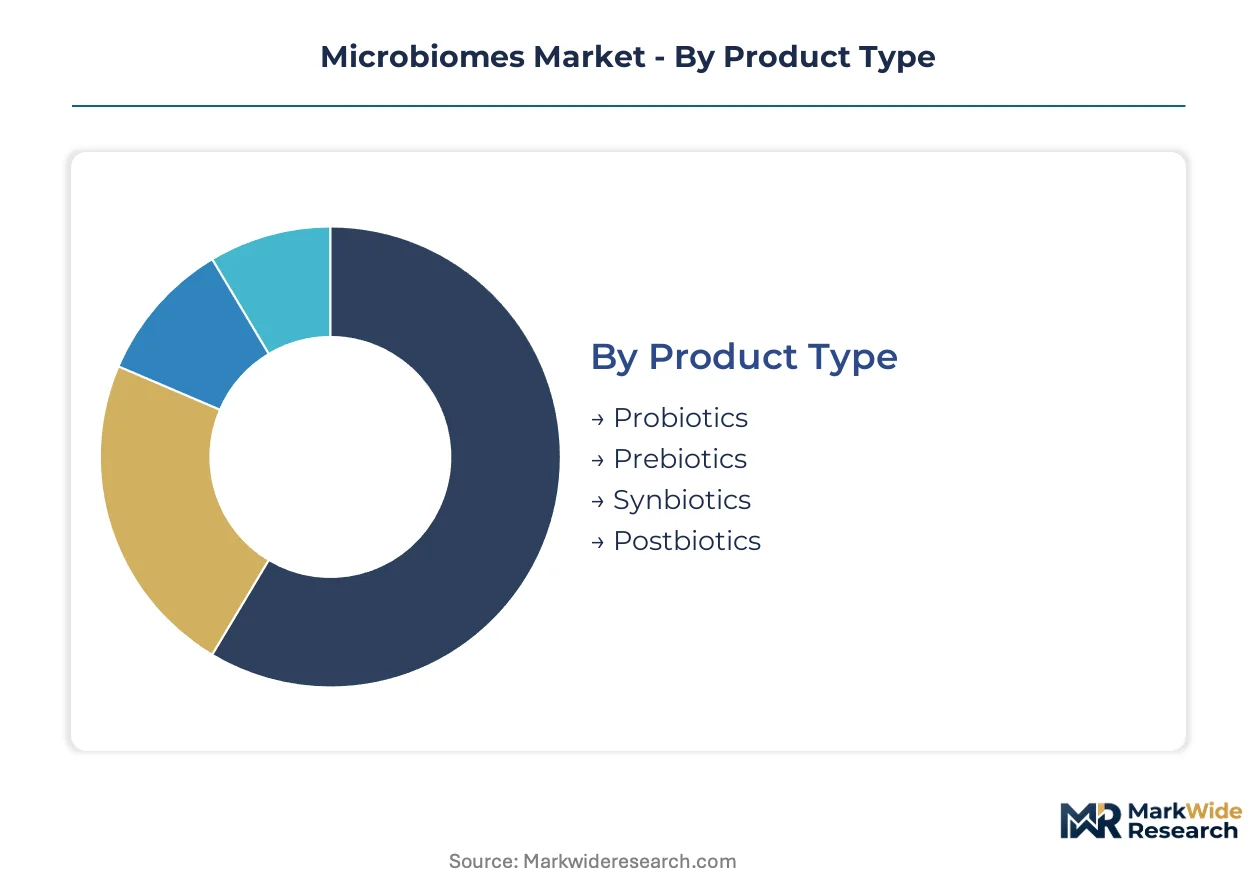
Microbiome market segmentation reveals divergent competitive dynamics across product formats and end-use environments. Substitution pressures vary sharply between established consumer formats and emerging pharmaceutical-grade offerings. Technology platforms increasingly determine segment boundaries rather than traditional application categories.
Product Type:
Prebiotics face intensifying substitution pressure from precision postbiotics that bypass upstream colonization variability entirely.
- Probiotics:Live microbial cultures delivered in dietary supplement, functional food, or clinical formats dominate current revenue through established manufacturing infrastructure and consumer familiarity. Hospital formulary placement in United States academic medical centers anchors prescription-grade demand, though reimbursement categorization disputes constrain pharmaceutical expansion.
- Prebiotics:Non-digestible substrates that selectively nourish beneficial gut bacteria occupy mid-tier pricing through oligosaccharide and fiber-based formulations. EU Green Deal farm-to-fork targets are pulling agricultural prebiotic applications into mainstream crop management as chemical fertilizer restrictions tighten across member states.
- Synbiotics:Combined probiotic-prebiotic formulations designed for synergistic colonization support.
- Postbiotics:Inactivated microbial cells or metabolites that deliver immunomodulatory benefits without live culture handling requirements.
Probiotics retain volume leadership; postbiotics hold the steepest expansion curve.
Application:
Margin structures stratify sharply between regulated healthcare environments and price-sensitive agricultural deployment.
- Healthcare:Therapeutic and preventive applications targeting gastrointestinal, metabolic, and immune-mediated conditions command premium pricing through FDA live biotherapeutic guidance and EMA qualification pathways. Clinical validation requirements compress competitive timelines to developers with end-to-end GMP manufacturing control.
- Agriculture:Soil inoculants, crop biostimulants, and livestock feed additives expand through sustainability mandates restricting synthetic input dependence. Soil carbon credit markets in North America and Europe are creating new monetization pathways for inoculants demonstrating measurable carbon sequestration.
- Food & Beverage:Functional ingredient integration into fermented products and fortified formulations.
- Animal Nutrition:Gut health optimization for poultry, swine, and aquaculture production systems.
Healthcare captures value concentration; agriculture delivers volume scaling.
End User:
Procurement authority is fragmenting across institutional buyers with incompatible technical specifications and validation requirements.
- Hospitals:Academic medical centers in the United States are unbundling microbiome therapeutics from infectious disease procurement categories, creating standalone evaluation tracks assessing antibiotic-sparing potential. Specialty pharmacy distribution channels are capturing volume previously flowing through wholesale distributors.
- Research Institutions:Universities and contract research organizations drive metagenomics platform adoption for strain-level characterization of unculturable organisms. Single-cell sequencing combined with machine learning is compressing discovery-to-candidate timelines.
- Food Manufacturers:Industrial-scale fermentation and formulation integration for consumer product development.
- Farmers:Direct procurement of agricultural inoculants through cooperative and retail channels.
Hospitals anchor therapeutic value; research institutions drive technology adoption velocity.
Technology:
Platform maturity is displacing empirical discovery as the primary competitive determinant across all product categories.
- Genomics:Strain-level genome sequencing enables rational consortium design and intellectual property protection for live biotherapeutic developers. Seres Therapeutics and Vedanta Biosciences leverage proprietary genomic databases to sustain pipeline differentiation.
- Metagenomics:Community-level sequencing of unculturable organisms is expanding accessible therapeutic targets beyond traditional probiotic strain collections. The technology is compressing traditional 18-24 month characterization cycles into 6-9 month workflows.
- Bioinformatics:Computational pipelines for multi-omics data integration and predictive microbiome modeling.
- Sequencing:Instrument platforms and reagent systems enabling cost-per-base reduction and throughput scaling.
Genomics secures commercial defensibility; metagenomics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA live biotherapeutic guidance and EMA qualification pathways are compressing clinical timelines in developed markets, while India's CDSCO fast-track mechanism offers alternative regulatory velocity for first-in-class developers.
United States
Academic medical centers in Boston and San Francisco anchor prescription-grade demand through standalone formulary evaluation tracks. FDA's emerging live biotherapeutic framework clarifies CMC requirements for complex consortia products. Seres Therapeutics and Finch Therapeutics Group concentrate pipeline development in Cambridge, Massachusetts, leveraging end-to-end GMP manufacturing control.
Germany
EMA's qualification pathway for microbiome biomarkers reduces Phase 3 duration for developers targeting inflammatory bowel disease. The EU Green Deal's farm-to-fork targets pull agricultural microbiome inputs into mainstream crop management as chemical fertilizer restrictions tighten. Heidelberg and Munich clusters host metagenomics platform adoption for strain-level characterization workflows.
China
NMPA's evolving biologics framework accommodates live therapeutic products through accelerated review channels for unmet-need indications. Dual carbon goals create demand pull for soil inoculants demonstrating measurable carbon sequestration. Yangtze River Delta biotech parks in Shanghai and Suzhou concentrate manufacturing infrastructure for precision-engineered bacterial consortia.
India
CDSCO's fast-track pathway for unmet-need biologics reduces clinical data requirements for first-in-class live therapeutics. Domestic fermentation capacity expansion supports contract manufacturing demand from Western developers. Hyderabad and Bengaluru clusters anchor bioinformatics and multi-omics data integration service provision.
Switzerland
Swissmedic's alignment with EMA qualification pathways enables parallel European market access for developers establishing headquarters in Basel and Zurich. Precision medicine infrastructure supports patient stratification platforms for oncology trial enrollment. The country's pharmaceutical-grade manufacturing talent pool addresses GMP expertise scarcity at the live culture handling intersection.
Microbiomes Market Competitive Landscape
Player mix skews toward integrated therapeutics developers with captive manufacturing capabilities, creating tiered competitive structure between GMP-certified operators and discovery-stage platforms. Two strategic archetypes dominate: end-to-end manufacturers controlling consortium production from strain banking through fill-finish, and platform-anchored discovery houses licensing strain collections. Consolidation pressure intensifies as FDA and EMA timelines compress, forcing partnership decisions before clinical readouts.
Within the integrated therapeutics tier, Seres Therapeutics and Vedanta Biosciences exemplify divergent approaches to pipeline sustainability. Seres leverages end-to-end manufacturing control as a competitive moat, while Vedanta anchors position through rationally designed bacterial consortia. 4D pharma occupies a discovery-platform position, competing via proprietary screening capabilities rather than captive production infrastructure.
| Leading Market Players |
|---|
| Seres Therapeutics |
| 4D pharma |
| Vedanta Biosciences |
| Ferring B.V. |
| Finch Therapeutics Group |
| Enterome |
| Microbiotica |
| OpenBiome |
| International Flavors & Fragrances Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive fermentation capacity in Massachusetts and Basel anchors price floors for pharmaceutical-grade live biotherapeutics, while contract manufacturing in Hyderabad and Shanghai creates downward pressure on preclinical-stage consortia. Scale economies at the GMP-live culture intersection compress margins for developers without end-to-end strain banking through fill-finish control.
Pricing Analysis
Certification level (FDA live biotherapeutic guidance versus food-grade probiotic standards) creates the primary spread between prescription and consumer tiers. Three-tier pricing structure across pharmaceutical-grade, clinical-grade, and dietary supplement levels reflects GMP compliance depth and cold chain assurance. Pricing pressure stems from EMA qualification pathway acceleration compressing clinical development timelines. Hospital formulary committees exhibit lowest price sensitivity due to antibiotic-sparing value metrics, while agricultural inoculant buyers face highest sensitivity tied to commodity crop economics.
Supply Chain Analysis
Strain banking lead times extending 18-24 months for characterized consortia tether inventory strategy to pipeline stage gates. Supply concentrates in the United States, Germany, and Switzerland for GMP-certified live biotherapeutic production, with India and China anchoring contract fermentation for preclinical materials. Raw material dependencies center on cryopreservation media, anaerobic culture vessels, and specialized containment packaging. Single-source vulnerability runs through qualified strain depositaries holding master cell banks. Distribution runs through specialty pharmacy channels for prescription products and agricultural cooperative networks for soil inoculants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA live biotherapeutic guidance and EMA qualification pathways constitute a regulatory inflection compressing IND-to-approval timelines by half, rewarding developers with pre-positioned GMP infrastructure.
For Market Incumbents: Secure end-to-end manufacturing control through captive strain banking and fill-finish capacity before clinical readouts force partnership decisions under duress. Defend position by deepening GMP-live culture expertise scarcity at the biologics-fermentation intersection, while monitoring metagenomics platform entrants threatening rational consortium design advantages. For New Entrants and Emerging Players: Differentiate on India CDSCO fast-track pathway velocity for first-in-class live therapeutics targeting unmet-need indications with reduced clinical data requirements. White-space availability concentrates in immuno-oncology checkpoint inhibitor non-responder populations and soil carbon credit-qualifying agricultural inoculants. Go-to-market execution should anchor through academic medical center investigator-initiated trials building prescriber familiarity ahead of formulary negotiations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated therapeutics developers with captive GMP manufacturing over platform-anchored discovery houses lacking production infrastructure. Long-term viability hinges on pipeline sustainability through biomarker-qualified endpoints and manufacturing moats. Watch for EMA microbiome biomarker qualification expansion into metabolic indications as signal for Phase 3 duration compression opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Certification | FDA live biotherapeutic guidance clarifies CMC requirements for complex consortia products entering Phase 1. |
| Biomarker Qualification Pathway | EMA qualification reduces Phase 3 duration for ulcerative colitis and Crohn's disease indications. |
| Academic Medical Center Partnership | Standalone formulary evaluation tracks in Boston and San Francisco anchor prescription-grade demand. |
| Soil Carbon Credit Monetization | EU Green Deal farm-to-fork targets create environmental credit pathways for sequestration-demonstrating inoculants. |
| Single-Cell Sequencing Integration | Machine learning strain selection compresses discovery-to-candidate timelines from 18-24 months to 6-9 months. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up strain-level pipeline tracking and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled span product type (probiotics, prebiotics, synbiotics, postbiotics), application (healthcare, agriculture, food and beverage, animal nutrition), end user (hospitals, research institutions, food manufacturers, farmers), and technology platform (genomics, metagenomics, bioinformatics, sequencing). CAGRs derived from fitted growth curves across the projection horizon incorporate regulatory approval velocity, manufacturing capacity expansion, and reimbursement categorization resolution as microbiome-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside FDA live biotherapeutic guidance finalization or EMA biomarker qualification expansion would require recalibration. Forecasts reflect assumptions regarding cold chain infrastructure penetration and payer categorization convergence between food-grade and pharmaceutical-grade standards. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Automated Microbial Detection Systems Market