
 Microbial Coagulants Market | 2026-2036
Microbial Coagulants Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Coagulants Market Foresight
Food-grade enzyme certification is unwinding legacy supply arrangements across the microbial coagulants industry. DSM leverages its fermentation technology leadership to anchor European cheese enzyme supply. Chr. Hansen specializes in dairy culture and coagulant integration, sustaining premium positioning with large dairy cooperatives. Novozymes competes through broad enzymatic portfolios that extend beyond dairy into adjacent food processing segments.
Microbial coagulants comprise purified enzymes, principally fermentation-produced chymosin and fungal acid proteases, synthesized via submerged fermentation of genetically modified Aspergillus oryzae or Kluyveromyces lactis host strains at titers typically exceeding one gram per liter. These biocatalysts cleave kappa-casein at the Phe105-Met106 bond to induce milk clotting for cheese manufacturing, water treatment flocculation, and textile sizing recovery. The enzyme segment leads product type value generation due to superior specificity and lower dosage requirements versus polysaccharide alternatives, while water treatment applications exhibit the fastest trajectory as municipalities retrofit chemical-dependent plants with biological clarification systems. Liquid formulations dominate form-level procurement for industrial-scale dosing, though powder and granular variants occupy niche positions in remote or seasonal processing facilities lacking refrigerated distribution.
EMA guidelines on food enzyme safety evaluations and the EU Green Deal's chemical substitution mandates are tightening approval pathways and redirecting procurement toward biologically derived clarification agents. The EPA's National Pollutant Discharge Elimination System and evolving state-level water quality standards in the US are accelerating municipal adoption of enzymatic coagulation over aluminum sulfate. Stakeholders must monitor regulatory divergence between jurisdictions as approval timelines and purity thresholds fragment competitive access across the Atlantic basin.
Market Dynamics
EU food labeling regulations are forcing cheese manufacturers across Europe to abandon animal-derived rennet in favor of fermentation-produced chymosin, rewiring procurement patterns and supplier relationships throughout the dairy enzyme supply chain.
Growth Catalysts
- EMA Food Enzyme Safety Evaluations:The European Medicines Agency's tightened approval pathways for food-grade enzymes are accelerating manufacturer qualification of microbial coagulants as compliant alternatives to animal-sourced rennet.
- Water Treatment Biological Clarification:Municipalities retrofitting aluminum sulfate-dependent plants with enzymatic coagulation systems are opening new volume demand outside traditional dairy applications.
- Fungal Acid Protease Production Scale-Up:Submerged fermentation titers exceeding one gram per liter from Aspergillus oryzae host strains are reducing unit economics and expanding addressable market access.
Market Restraints
- Host Strain Supply Concentration:Dependence on genetically modified Aspergillus oryzae and Kluyveromyces lactis strains concentrates technical risk among a limited base of specialized fermentation suppliers.
- Regulatory Divergence Friction:Divergent purity thresholds and approval timelines between EMA guidelines and EPA National Pollutant Discharge Elimination System standards fragment competitive access across the Atlantic basin.
- Polysaccharide Coagulant Substitution:Lower-cost polysaccharide alternatives retain share in price-sensitive water treatment and textile applications where specificity requirements are less stringent.
Strategic Opportunities
- Asia-Pacific Dairy Modernization:Emerging cheese production clusters in China and India present untapped demand for fermentation-produced chymosin as local dairy processing scales to meet domestic consumption growth.
- EU Green Deal Chemical Substitution Mandates:The European Union's binding targets for biological clarification agents in municipal water treatment are creating regulatory-tagged procurement preferences for enzymatic coagulants.
- Precision Fermentation Convergence:Integration of synthetic biology tools with existing submerged fermentation infrastructure is enabling next-generation host strain development with improved enzyme yield and specificity profiles.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Qualified bioprocess engineers capable of optimizing submerged fermentation at industrial scale remain concentrated among a narrow pool of specialized technical personnel.
- Food-Grade Certification Timeline Compression:Extended EMA safety evaluation periods and evolving purity documentation requirements are lengthening time-to-market for new microbial coagulant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Coagulants Market |
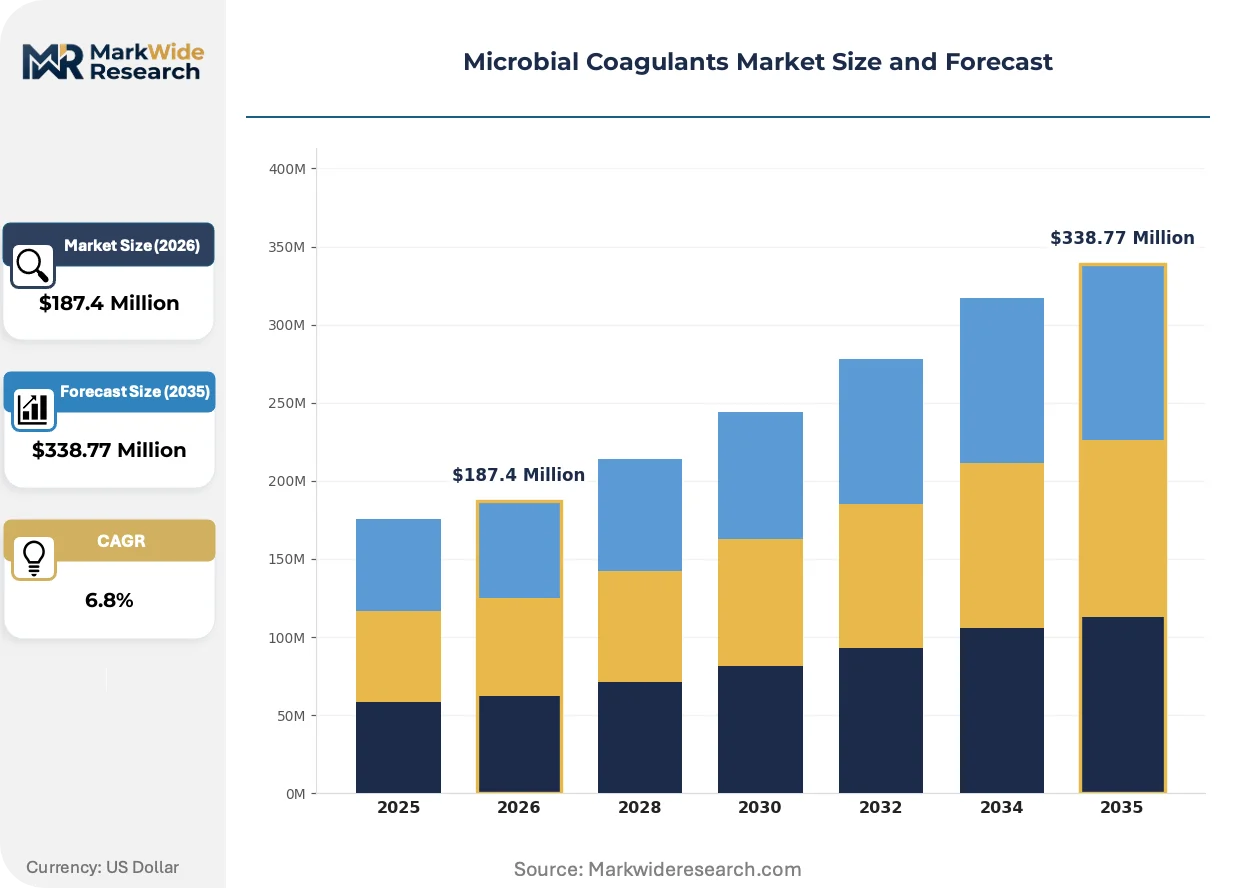
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitosan, Proteins, Polysaccharides, Enzymes Application: Water Treatment, Food Processing, Textile Industry, Paper Production End User: Municipalities, Food Manufacturers, Textile Producers, Pulp & Paper Companies Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | DSM, DuPont, Chr. Hansen, Sacco System, CSK Food Enrichment, Meito Sangyo, Amano Enzyme, Novozymes, Lallemand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Coagulants Market Shifts & Advancements
Fermentation technology maturation and regulatory chemistry substitution mandates are converging to reshape competitive positioning across dairy, water treatment, and industrial enzyme applications. Three developments dominate the current transformation trajectory.
Liquid formulation delivery systems optimized for automated industrial dosing are displacing powder and granular variants in continental European cheese manufacturing. Large dairy cooperatives in Germany, France, and Italy are standardizing on refrigerated liquid supply chains that enable precise metered addition and reduce handling contamination risk. This shift is compressing margins for suppliers lacking cold-chain distribution capabilities.
REACH chemical restriction schedules and the EU Green Deal's binding substitution targets are accelerating municipal procurement of biological clarification agents over aluminum sulfate in water treatment. French and German municipalities are retrofitting chemical-dependent plants with enzymatic coagulation systems to meet discharge standards. Water treatment applications now exhibit the fastest adoption trajectory across all microbial coagulant end-uses.
Large dairy cooperatives are consolidating enzyme procurement under integrated supply agreements that bundle coagulants with dairy cultures and starter systems. DSM and Chr. Hansen are capturing these relationships through fermentation technology leadership and culture-coagulant integration expertise. This concentration is visible across German, French, and Italian procurement clusters where volume scale drives supplier selection criteria.
Microbial Coagulants Market Segmentation
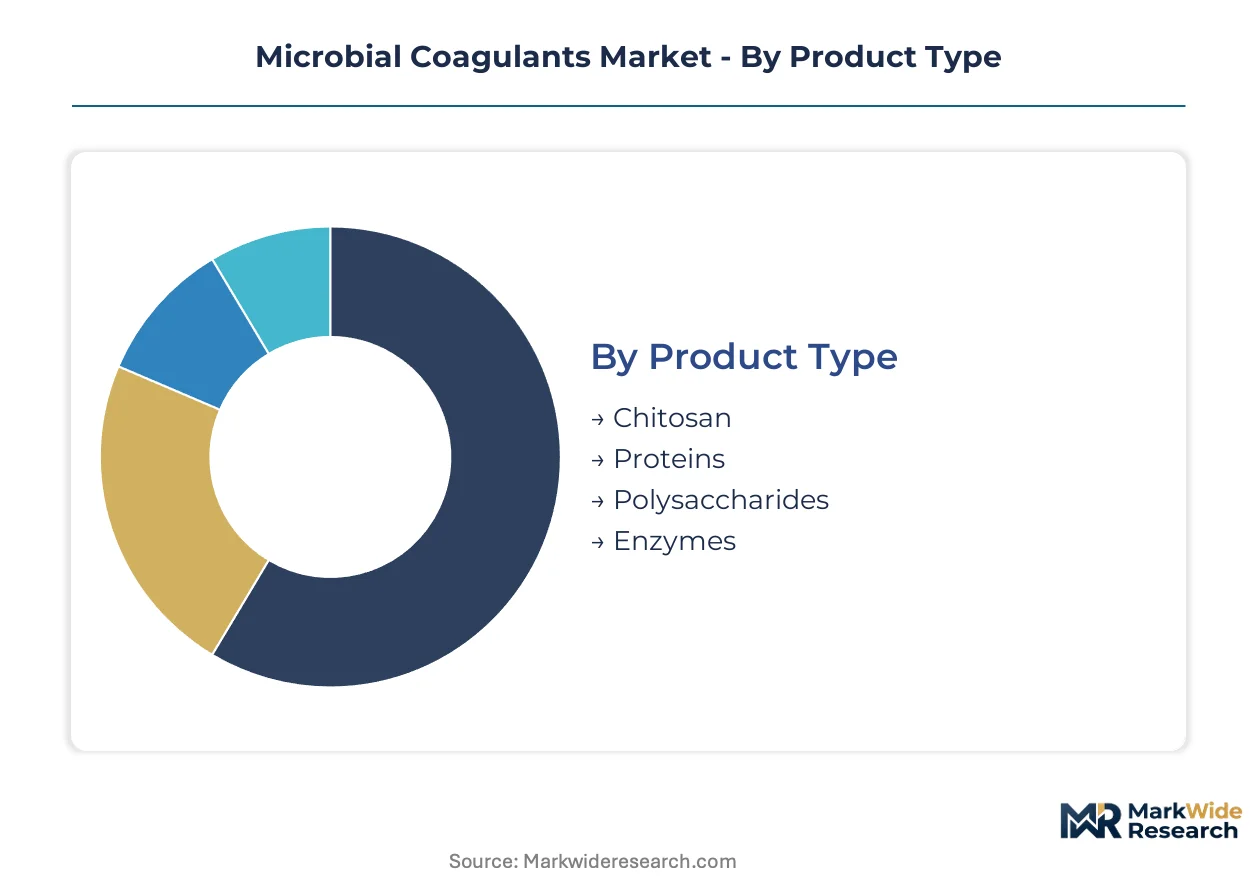
Segmentation in microbial coagulants reveals divergent supply chain configurations across dairy, water treatment, and industrial applications. Each category carries distinct technical specifications, regulatory pathways, and geographic procurement patterns that reshape competitive positioning.
Product Type:
Enzymes dominate export-led supply chains through European fermentation hubs, while polysaccharides and proteins concentrate in domestic Asian manufacturing for regional water treatment markets.
- Enzymes:Fermentation-produced chymosin and fungal acid proteases synthesized via submerged fermentation of genetically modified Aspergillus oryzae or Kluyveromyces lactis host strains. German, French, and Italian dairy cooperatives drive concentrated procurement for cheese manufacturing as EMA food enzyme safety evaluations tighten approval pathways.
- Polysaccharides:Lower-cost alternatives derived from plant and microbial sources with broader specificity profiles. Chinese and Indian municipalities favor domestic polysaccharide sourcing for price-sensitive water treatment applications where enzymatic precision is not required.
- Chitosan:Deacetylated chitin from crustacean shells or fungal biomass, primarily serving Asian textile and paper markets with regional supply chains anchored in coastal processing clusters.
- Proteins:Animal-derived and plant-based coagulant proteins retaining niche positions in traditional cheese-making regions with established cold-chain distribution.
Enzymes holds the largest share; momentum sits with polysaccharides.
Application:
Water treatment applications command the steepest expansion trajectory as municipalities retrofit chemical-dependent infrastructure, while food processing maintains volume concentration in established dairy economies.
- Water Treatment:Municipal biological clarification systems replacing aluminum sulfate with enzymatic coagulation. French and German municipalities lead retrofitting under EU Green Deal chemical substitution mandates, with EPA National Pollutant Discharge Elimination System standards accelerating parallel adoption in US states.
- Food Processing:Cheese manufacturing dominates through fermentation-produced chymosin deployment. Germany, France, and Italy concentrate procurement as EU food labeling regulations force abandonment of animal-derived rennet.
- Textile Industry:Sizing recovery and dye effluent treatment applications concentrated in Asian manufacturing hubs with established enzymatic processing infrastructure.
- Paper Production:Fiber retention and wastewater clarification in pulp and paper mills, with procurement patterns tied to regional forestry economies and effluent discharge regulations.
Food Processing retains volume leadership; Water Treatment is climbing the fastest.
End User:
Municipal procurement operates through public tender systems with extended qualification timelines, while food manufacturers negotiate integrated supply agreements bundling coagulants with starter cultures.
- Municipalities:Public water treatment authorities retrofitting aluminum sulfate plants with enzymatic coagulation systems. French and German municipal procurement clusters drive continental European demand under binding biological clarification targets.
- Food Manufacturers:Large dairy cooperatives in Germany, France, and Italy consolidating enzyme procurement under integrated agreements. DSM and Chr. Hansen capture these relationships through fermentation technology leadership and culture-coagulant integration.
- Textile Producers:Asian manufacturing facilities optimizing sizing recovery and effluent treatment with regionally sourced enzymatic and polysaccharide alternatives.
- Pulp & Paper Companies:Forestry-integrated mills in Nordic and North American markets adopting biological clarification for process water recycling and discharge compliance.
Food Manufacturers command the largest procurement volumes; Municipalities are expanding most quickly.
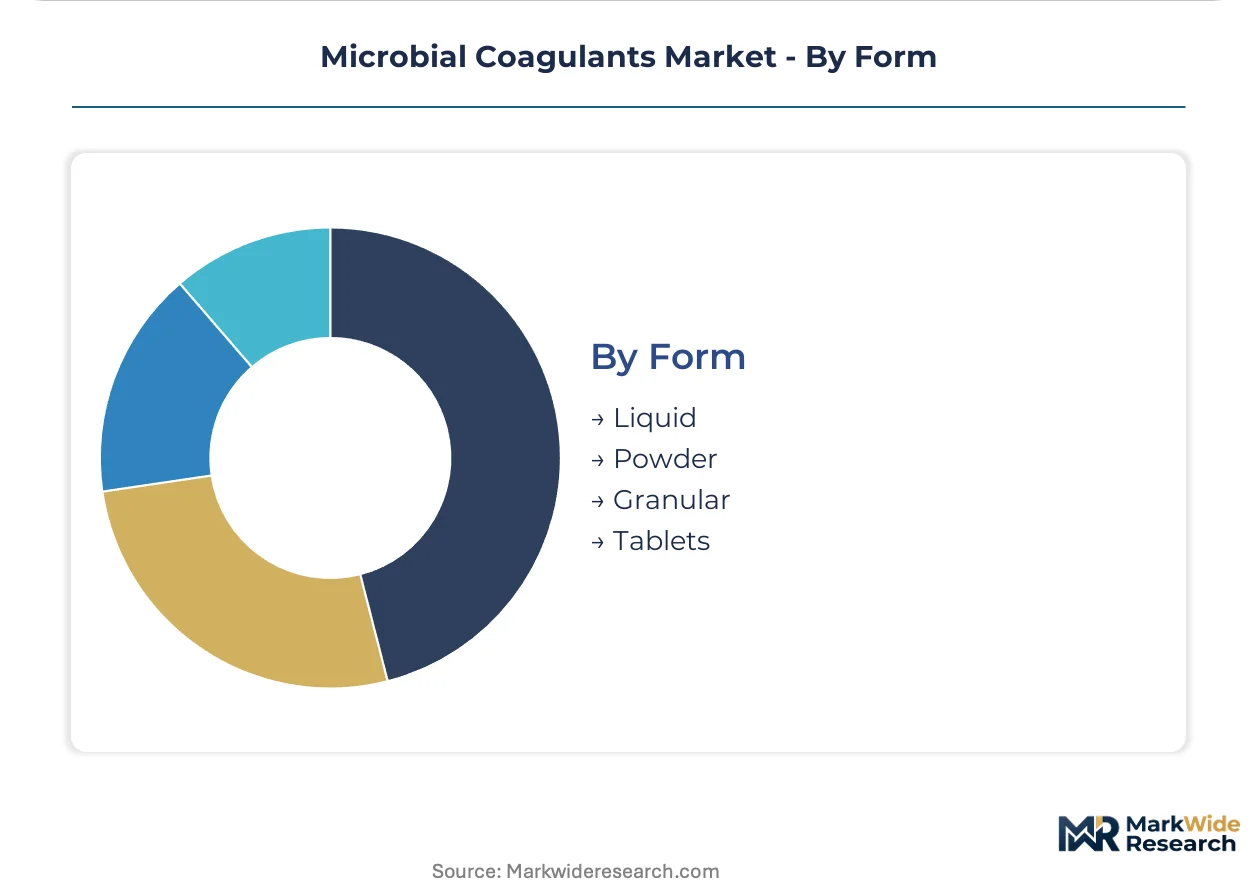
Form:
Liquid formulations require refrigerated distribution infrastructure concentrated in continental European dairy clusters, while powder and granular variants serve remote or seasonal facilities lacking cold-chain access.
- Liquid:Refrigerated formulations optimized for automated industrial dosing in large-scale cheese manufacturing. German, French, and Italian dairy cooperatives standardize on liquid supply chains enabling precise metered addition and reduced handling contamination risk.
- Powder:Shelf-stable variants for remote processing facilities and seasonal cheese production in mountainous or island regions with limited refrigerated distribution.
- Granular:Intermediate stability format occupying niche positions in water treatment plants with batch dosing systems and intermediate storage capabilities.
- Tablets:Pre-measured solid formulations for small-scale food processing and decentralized water treatment applications requiring simplified handling protocols.
Liquid holds the largest share; momentum sits with Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation infrastructure clusters in Germany, France, and Italy concentrate microbial coagulant supply capacity for European dairy processing. These three markets anchor continental procurement patterns as regulatory chemistry substitution mandates reshape municipal water treatment demand.
Germany
Bavarian and North Rhine-Westphalian dairy cooperatives drive concentrated demand for fermentation-produced chymosin as cheese manufacturers abandon animal-derived rennet under EU food labeling regulations. The EU Green Deal's binding biological clarification targets accelerate municipal retrofitting of aluminum sulfate-dependent water treatment plants in the Rhine-Ruhr industrial corridor.
France
Île-de-France and Auvergne-Rhône-Alpes host the densest clusters of large-scale dairy processing facilities transitioning to microbial coagulant systems. EMA food enzyme safety evaluation pathways tighten approval standards while French municipalities under REACH chemical restriction schedules procure enzymatic coagulation systems for discharge compliance.
Italy
Emilia-Romagna and Lombardy concentrate artisanal and industrial cheese production demanding liquid formulation supply chains with refrigerated distribution. Italian procurement patterns favor integrated agreements bundling coagulants with dairy cultures as large cooperatives consolidate supplier relationships under EMA-guided certification timelines.
United States
Wisconsin and California dairy processing clusters generate sustained demand for microbial coagulants as domestic cheese production scales. EPA National Pollutant Discharge Elimination System standards drive municipal adoption of enzymatic coagulation over aluminum sulfate in Great Lakes and California water treatment authorities.
China
Shandong and Hebei provinces anchor emerging cheese production infrastructure as domestic dairy consumption expands beyond traditional fresh milk products. Chinese municipalities under MEE water quality directives pilot biological clarification systems, creating parallel demand trajectories for fermentation-derived coagulants outside established dairy applications.
Microbial Coagulants Market Competitive Landscape
Concentration sits with diversified fermentation technology specialists and dairy culture integrators that control European supply relationships. Three to five integrated suppliers capture the majority of procurement volume from large dairy cooperatives, while regional enzyme specialists retain positions in price-sensitive water treatment and Asian manufacturing markets. Dominant competitive moves include backward integration into host strain development and geographic expansion through distribution partnerships in Asia-Pacific dairy modernization clusters.
Among Netherlands-based biotechnology conglomerates, DSM exemplifies the fermentation technology leadership archetype through submerged process scale-up capabilities. Danish specialists Chr. Hansen and Novozymes occupy positions within the culture-coagulant integration and broad enzymatic portfolio tiers respectively, each representing distinct competitive positioning strategies for dairy cooperative procurement consolidation.
| Leading Market Players |
|---|
| DSM |
| DuPont |
| Chr. Hansen |
| Sacco System |
| CSK Food Enrichment |
| Meito Sangyo |
| Amano Enzyme |
| Novozymes |
| Lallemand |
| Others |
Supply & Pricing Matrix
Industrial-scale submerged fermentation titers exceeding one gram per liter from German and Dutch production facilities anchor cost structures across European dairy enzyme supply. These scale economies concentrate pricing power among three to five integrated fermentation specialists while compressing margins for regional suppliers lacking comparable bioprocess optimization.
Pricing Analysis
EMA food enzyme safety evaluations dictate the pricing tier structure across microbial coagulant procurement. Three-tier pricing separates pharmaceutical-grade fermentation-produced chymosin from standard food-grade enzymes and economy fungal acid protease formulations. Price differentiation rests on certification timelines and purity documentation burden, with EMA-compliant grades commanding substantial premia over EPA-registered alternatives for water treatment. Cost compression in economy tiers is intensifying as Chinese polysaccharide alternatives capture price-sensitive municipal contracts. Municipal water treatment authorities exhibit highest price sensitivity due to public procurement constraints, while large German and French dairy cooperatives prioritize supply security over unit cost.
Supply Chain Analysis
Refrigerated liquid inventory cycles of fourteen to twenty-one days constrain geographic reach from continental European production hubs. Supply concentrates in the Netherlands, Denmark, and Germany for fermentation-derived enzymes, while Chinese and Indian manufacturers dominate polysaccharide alternatives. Raw material dependencies include genetically modified Aspergillus oryzae host strains, Kluyveromyces lactis culture banks, and pharmaceutical-grade fermentation media. Single-source vulnerability in GM strain supply creates concentrated technical risk among specialized fermentation houses. Distribution runs through cold-chain logistics partnerships for liquid dairy formulations and standard chemical distribution for powder water treatment grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between EMA and EPA approval pathways fragments procurement standards, creating service and certification niches that specialized suppliers can occupy without direct scale competition against integrated incumbents.
For Market Incumbents: Fortify host strain supply security through backward integration into culture bank ownership or exclusive long-term strain licensing agreements. DSM and Chr. Hansen should deepen precision fermentation capabilities to defend against synthetic biology-enabled entrants targeting yield optimization. EMA timeline compression for food-grade certification represents the critical margin pressure point requiring preemptive regulatory affairs investment. For New Entrants and Emerging Players: Technical service gaps in municipal water treatment retrofit project management present accessible entry points where incumbents under-serve with standardized product offerings. Target Chinese and Indian dairy modernization clusters with powder formulations bypassing refrigerated distribution requirements. Position through integrated biological clarification system design rather than commodity enzyme supply. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platform companies with demonstrated host strain engineering capabilities over traditional culture collection assets. Five-to-ten year viability hinges on regulatory chemistry substitution mandate durability rather than cyclical dairy demand. Watch EMA-EPA regulatory convergence negotiations as the critical inflection signal for cross-Atlantic competitive access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Host Strain Backward Integration | Captive supply of GM Aspergillus oryzae cultures reduces dependency on specialized fermentation houses. |
| Precision Fermentation Platform Investment | Synthetic biology tools enable next-generation yield optimization beyond current submerged fermentation limits. |
| Municipal Water Treatment System Partnerships | Biological clarification retrofit projects in French and German municipalities create multi-year offtake visibility. |
| Asia-Pacific Distribution Partnership | Local powder formulation supply bypasses cold-chain infrastructure gaps in Chinese and Indian dairy clusters. |
| EMA Regulatory Affairs Capability Buildout | Expedited food enzyme safety evaluation navigation compresses time-to-market for new formulations. |
Research Methodology
Cross-validation between primary interviews with dairy procurement directors, municipal water treatment engineers, and fermentation technology specialists anchors the qualitative findings against secondary trade data. Plant managers at German and French dairy cooperatives, EPA compliance officers at US municipal treatment authorities, and technical R&D directors at enzyme manufacturers provided operational perspective. Secondary sources include EMA food enzyme safety evaluation databases, EPA National Pollutant Discharge Elimination System compliance records, EU Green Deal implementation tracking, and customs trade data for fermentation equipment imports. Bottom-up volume modeling from individual facility procurement patterns triangulates against top-down market sizing from industry association production statistics.
Sensitivity analysis across host strain yield assumptions, regulatory approval timeline scenarios, and municipal retrofit adoption curves tests forecast robustness throughout the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, geographic regulatory cluster, and formulation stability requirements. CAGRs derive from regression analysis of historical procurement volume trends against explanatory variables including dairy production growth, chemical substitution mandate bindingness, and fermentation capacity expansion announcements. Industry-specific inputs incorporate EMA evaluation queue lengths and REACH chemical restriction phase-out schedules.
Forecasts assume regulatory continuity in EMA food enzyme safety evaluation procedures and EPA National Pollutant Discharge Elimination System standards; material policy shifts would require re-modeling with revised compliance cost assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Microbiology Testing Market