
 Global Microbial Based Biological Seed Treatment Market | 2026-2036
Global Microbial Based Biological Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbial Based Biological Seed Treatment Market Foresight
Multi-source microbial procurement is consolidating around vertically integrated biomanufacturing platforms. BASF SE anchors European production capacity for Bacillus-based formulations, while Novozymes A/S leverages Danish fermentation expertise to supply active ingredient concentrates globally. Bayer AG competes through its crop science division's controlled distribution network, locking in access to major seed company customers.
Microbial based biological seed treatment comprises living microorganisms—bacteria, fungi, or actinomycetes—applied to seeds prior to planting to enhance nutrient uptake, suppress soil-borne pathogens, or induce systemic resistance in emerging plants, typically formulated at colony-forming unit concentrations between 10^8 and 10^11 CFU per gram. Powder and liquid formulations dominate commercial volumes due to compatibility with existing seed coating infrastructure, though water dispersible granules are gaining traction where dust-off regulations tighten. Bacillus and Trichoderma segments lead microbial type revenue owing to broad-spectrum antagonism against fungal pathogens and established shelf stability, while Rhizobia formulations occupy a specialized but defensible niche in legume crop systems.
The EPA regulates microbial pesticide products under FIFRA with data requirements for non-target organism effects and environmental fate, while the EU Green Deal and REACH framework restrict synthetic chemical seed treatments and create compliance-driven substitution toward biological alternatives. India's Central Insecticides Board mandates registration under the Insecticides Act for imported microbial strains, adding a layer of biosecurity review that shapes market entry timelines. Stakeholders must monitor evolving strain patent landscapes and regulatory equivalence agreements between major agricultural economies to anticipate where formulation registration costs will concentrate or dissipate.
Market Dynamics
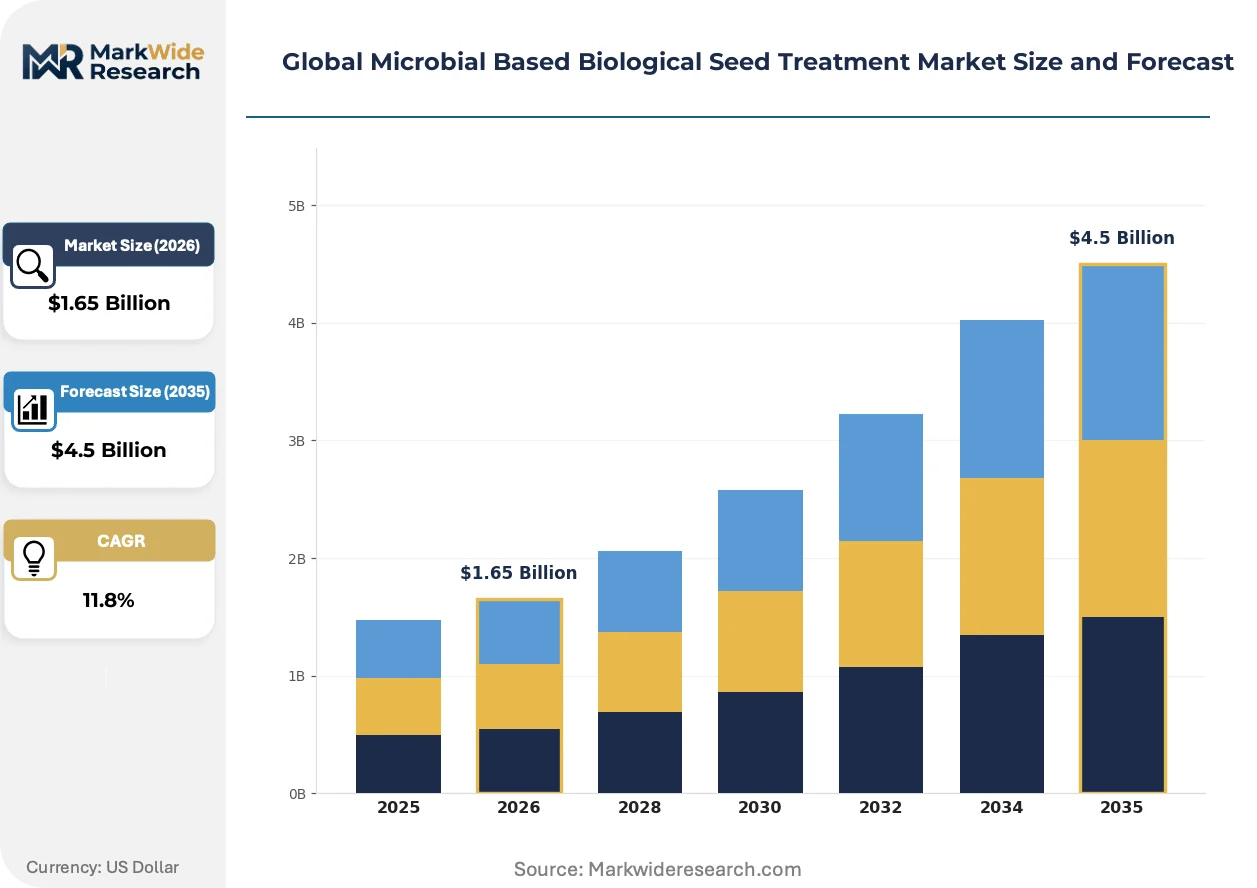
EU Green Deal mandates and F-Gas Regulation restrictions are compressing synthetic chemistry windows while accelerating microbial formulation substitution across major agricultural economies. This regulatory compression is restructuring procurement priorities for row crop producers and seed companies alike.
Growth Catalysts
- EU F-Gas Regulation phase-down:The regulation's tightening quotas on synthetic fumigants are forcing European growers toward Bacillus-based alternatives for soil-borne pathogen suppression.
- Brazilian legume inoculant infrastructure:Deep penetration of Rhizobia application systems across the Cerrado soybean belt creates demonstration effects for adjacent microbial categories.
- Controlled-release encapsulation:Advances in polymer matrix technology are extending shelf stability of Trichoderma formulations from months to multiple growing seasons.
Market Restraints
- Fermentation input volatility:Molasses and soy-derived nutrient media prices fluctuate with commodity crop cycles, compressing margin predictability for concentrate producers.
- Strain banking concentration:Critical germplasm repositories cluster in Denmark and Germany, creating biosecurity chokepoints for Asian and Latin American formulators.
- Application equipment incompatibility:Legacy seed treaters designed for synthetic fungicides lack precision metering for low-viscosity microbial suspensions, requiring capital retrofit.
Strategic Opportunities
- India's Insecticides Act registration pathway:Central Insecticides Board strain review protocols, once navigated, confer multi-year exclusivity windows for first-mover microbial entrants.
- Drone-based aerial inoculation:UAV application systems are opening bypass channels around traditional seed-coating infrastructure for cover crop and pasture legume segments.
- Carbon credit stacking:Nitrogen-fixing microbial treatments qualify for verified offset protocols in Australian and Canadian agricultural carbon markets.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning microbiology, polymer science, and seed physiology concentrates in legacy agricultural chemistry hubs.
- Multi-jurisdiction equivalence:Strain registration in the US under EPA FIFRA does not automatically transfer to EU REACH compliance, duplicating toxicology study costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbial Based Biological Seed Treatment Market |
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $4.5 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Microbial Type: Rhizobia, Trichoderma, Azotobacter, Bacillus, Pseudomonas, Actinomycetes Application Crop: Cereals, Pulses, Oilseeds, Vegetables, Fruits, Fiber Crops Formulation Type: Powder, Liquid, Granules, Water Dispersible Granules, Emulsifiable Concentrates End User Category: Seed Companies, Agricultural Cooperatives, Independent Farmers, Contract Growers, Research Institutions |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, Novozymes A/S, Indigo Ag, Inc., Koppert B.V., Valent BioSciences, Verdesian Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbial Based Biological Seed Treatment Market Shifts & Advancements
Biomanufacturing scale-up and regulatory chemistry substitution are converging to transform how microbial active ingredients reach field application. These forces are compressing development timelines while fragmenting traditional supply hierarchies.
Lyophilization and spray-drying advances are decentralizing production geography for heat-stable Bacillus and Trichoderma concentrates. Mid-scale fermentation facilities in Argentina and Vietnam now achieve viable titers previously requiring Danish or German infrastructure. Regional formulators are capturing margin previously absorbed by intercontinental concentrate shipping.
REACH framework amendments are tightening data requirements for synthetic seed treatment residues in European food and feed chains. The regulatory burden is accelerating withdrawal registrations for neonicotinoid and fipronil chemistries. Biological inoculant segments in France and Germany are capturing shelf space and technical advisory relationships vacated by incumbent chemistry.
Seed company procurement departments are consolidating supplier panels around integrated formulation and application service bundles. Multi-year biological treatment contracts with performance guarantees are displacing spot concentrate purchases. This bundling is most advanced in North American corn and soybean seed channels, where trait licensing and treatment decisions now converge at single decision points.
Global Microbial Based Biological Seed Treatment Market Segmentation
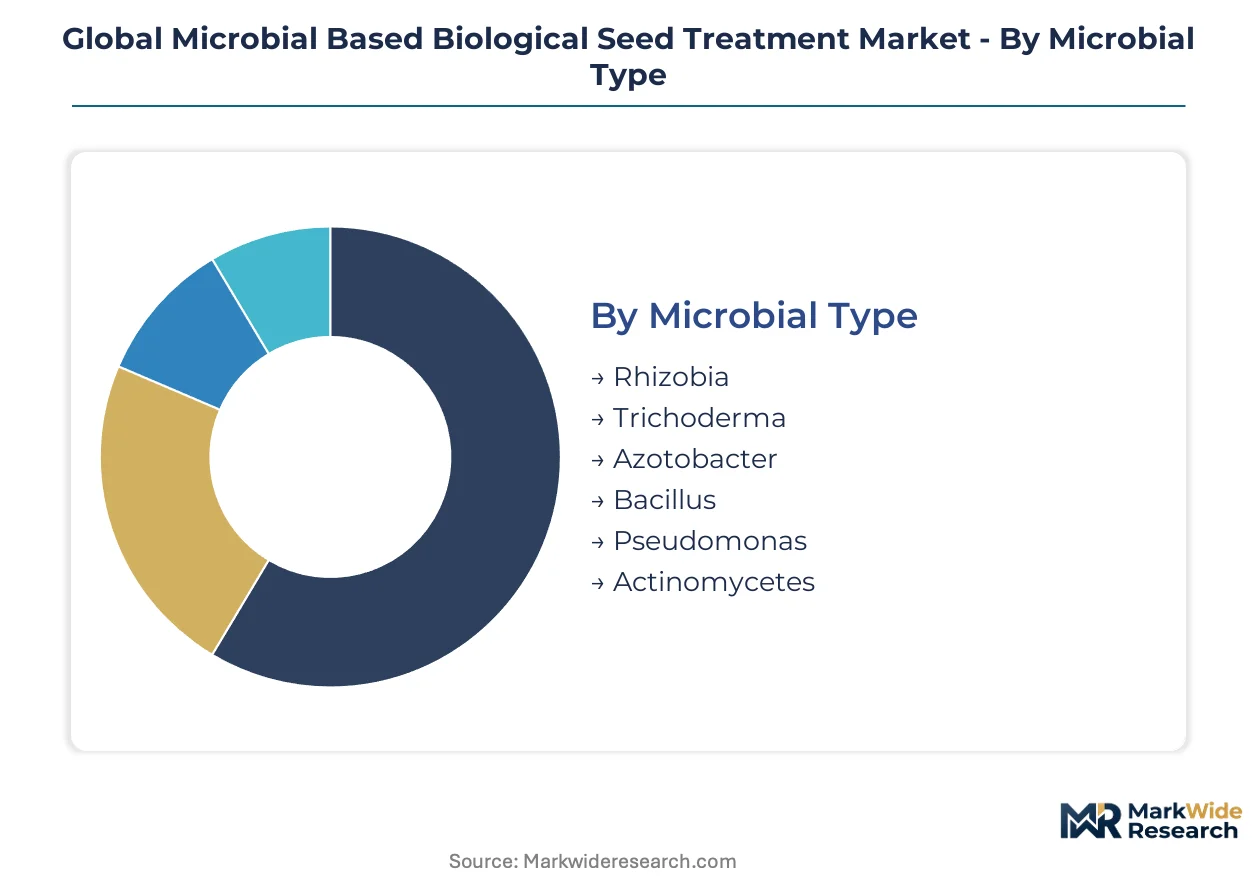
Microbial seed treatment purchasing hinges on crop-specific performance validation and formulation compatibility with existing coating infrastructure. Segmentation reveals where technical specifications align with buyer risk tolerance and application scale.
Microbial Type:
Buyers prioritize shelf stability and antagonistic spectrum when selecting active ingredient platforms.
- Bacillus:Spore-forming bacteria formulated at 10^8 to 10^11 CFU per gram deliver broad-spectrum fungal pathogen suppression. Demand concentrates in North American corn and soybean seed channels where EPA FIFRA registration pathways are established and seed company procurement panels favor proven shelf stability.
- Trichoderma:Filamentous fungi colonize root zones through competitive exclusion and mycoparasitism. Polymer matrix encapsulation advances in Denmark and Germany are extending formulation viability across multiple growing seasons, driving adoption in high-value vegetable seed segments.
- Rhizobia:Specialized nitrogen-fixing symbionts dominate legume inoculant applications.
- Pseudomonas:Fluorescent species produce siderophores and antibiotics for biocontrol.
- Azotobacter:Free-living diazotrophs target non-legume cereal systems.
- Actinomycetes:Filamentous bacteria generate specialized secondary metabolites for niche applications.
Bacillus leads on scale; Trichoderma leads on momentum.
Application Crop:
Volume concentration tracks planted hectarage and treatment cost recovery through yield premiums.
- Cereals:Wheat, rice, and corn seeds receive microbial treatments for root rot suppression and nutrient mobilization. Brazil's Cerrado soybean belt demonstration effects are spilling into adjacent maize systems where cooperatives manage bulk procurement.
- Oilseeds:Canola and sunflower applications emphasize sclerotinia suppression through competitive microbiome establishment. Canadian prairie provinces and Australian wheatbelt regions are expanding treated hectarage under carbon credit protocols that monetize nitrogen fixation.
- Pulses:Legume-specific inoculation infrastructure is mature.
- Vegetables:High-value crops justify premium formulation costs.
- Fruits:Nursery stock and rootstock treatments dominate.
- Fiber Crops:Cotton seed treatment adoption is emerging.
Cereals dominate volume; oilseeds are climbing fastest.
Formulation Type:
Equipment compatibility and dust-off compliance shape formulator R&D priorities.
- Powder:Dry flowable concentrates integrate with legacy seed treaters requiring minimal capital retrofit. Dust-off regulations in France and Germany are compressing powder share where water dispersible alternatives demonstrate superior operator safety profiles.
- Liquid:Aqueous suspensions enable precise CFU dosing and uniform seed coverage. North American seed company technical centers are standardizing liquid handling infrastructure for multi-microbial cocktail applications.
- Water Dispersible Granules:Low-dust formulations address tightening EU occupational exposure limits.
- Granules:Direct soil application bypasses seed coating infrastructure.
- Emulsifiable Concentrates:Oil-based carriers enhance desiccation tolerance.
Powder retains installed base dominance; water dispersible granules gain regulatory tailwinds.
End User Category:
Procurement sophistication varies sharply across buyer types.
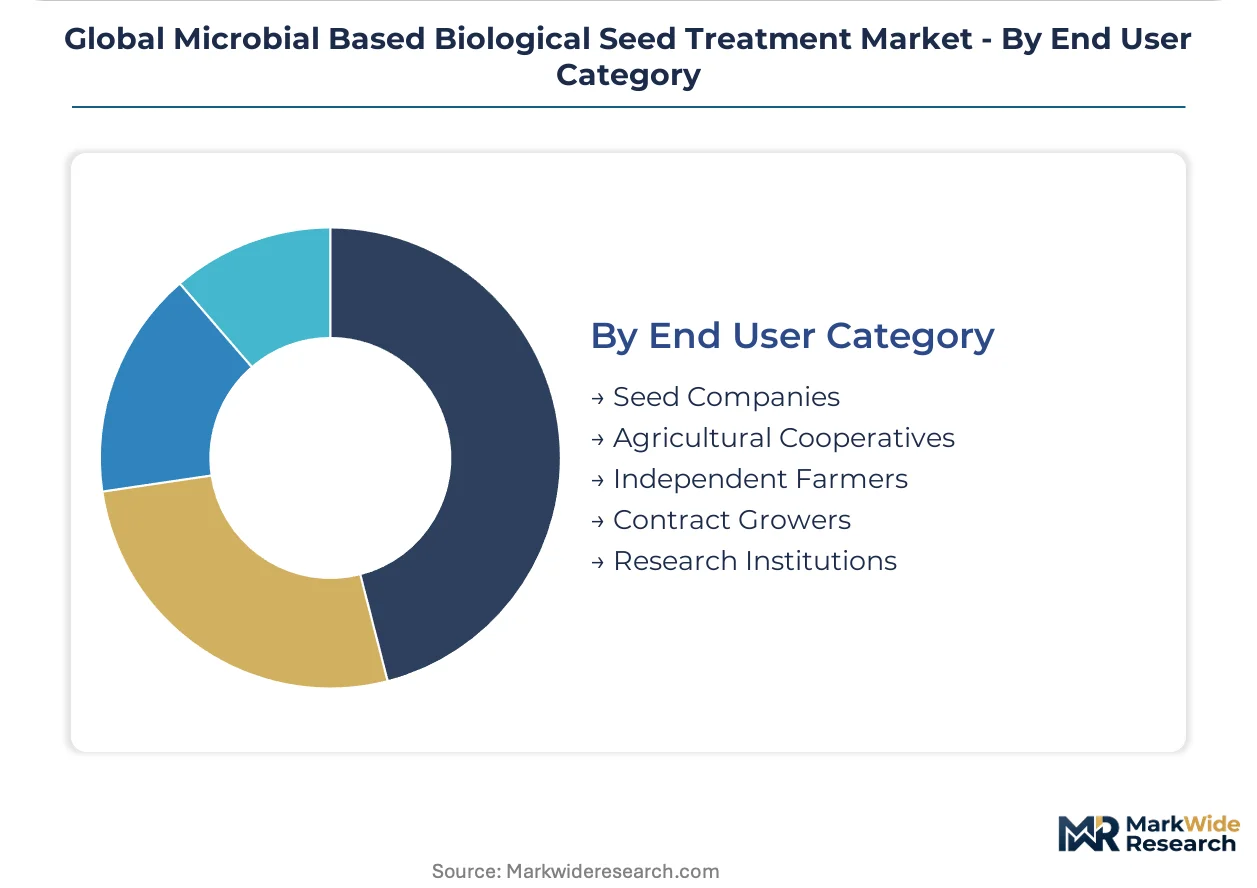
- Seed Companies:Integrated breeding and treatment operations demand multi-year supply contracts with performance guarantees. Bayer AG and BASF SE compete for exclusive formulation partnerships that bundle biological treatments with trait licensing agreements.
- Agricultural Cooperatives:Bulk purchasing power enables treated seed programs for member farms. Brazilian cooperatives in Mato Grosso and Paraná operate centralized inoculation facilities serving soybean and corn growers.
- Independent Farmers:Spot purchases concentrate in regions with shallow cooperative penetration.
- Contract Growers:Processor-linked production specifies treatment protocols.
- Research Institutions:Strain validation and field trial supply.
Seed companies command formulation development resources; cooperatives drive regional penetration depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado soybean belt anchors global microbial seed treatment penetration, with legume inoculant infrastructure creating demonstration effects for adjacent biological categories across major agricultural economies.
United States
Row crop producers in Iowa and Illinois are expanding biological treatment programs as a hedge against synthetic chemistry restrictions. EPA FIFRA registration pathways for Bacillus-based formulations are well-established, accelerating procurement decisions. Seed company technical centers in the Corn Belt are standardizing liquid handling infrastructure for multi-microbial cocktail applications.
Brazil
Deep Rhizobia penetration across Mato Grosso and Paraná creates spillover demand for complementary microbial categories. ANVISA biosecurity protocols for imported strains add registration complexity but confer exclusivity windows for navigated entrants. Cooperatives in the Cerrado operate centralized inoculation facilities serving soybean and corn growers at scale.
Germany
EU Green Deal mandates and F-Gas Regulation phase-downs are compressing synthetic chemistry windows for soil-borne pathogen suppression. ECHA REACH framework amendments tighten residue data requirements, accelerating withdrawal of neonicotinoid chemistries. BASF SE anchors European production capacity for Bacillus-based formulations from Ludwigshafen.
India
Punjab and Haryana wheat systems are emerging as testbeds for Azotobacter-based cereal inoculants. Central Insecticides Board registration under the Insecticides Act mandates strain review protocols that shape market entry timelines. Domestic fermentation capacity in Gujarat is scaling to reduce dependence on Danish and German concentrate imports.
Denmark
Novozymes A/S leverages Danish fermentation expertise to supply active ingredient concentrates globally, with critical germplasm repositories creating biosecurity chokepoints for Asian and Latin American formulators. Polymer matrix encapsulation advances in Copenhagen are extending Trichoderma formulation viability across multiple growing seasons.
Global Microbial Based Biological Seed Treatment Market Competitive Landscape
Global majors compete with regional champions across formulation development and distribution access, producing a tiered structure where integrated agrochemical conglomerates anchor premium supply contracts while mid-scale biomanufacturers capture regional concentrate demand. Strategic archetypes include vertically integrated seed-treatment bundlers, specialized fermentation-to-formulation platforms, and regional application-service providers. Dominant competitive moves center on exclusive multi-year supply contracts with performance guarantees and backward integration into strain banking and biomanufacturing capacity.
Among European-based integrated platforms, BASF SE and Bayer AG exemplify the seed-treatment bundler archetype, leveraging crop science divisions and controlled distribution networks to lock in access to major seed company customers. Novozymes A/S occupies a distinct position as a fermentation-specialist platform supplying active ingredient concentrates globally from Danish infrastructure. These three entities represent the dominant competitive anchors shaping procurement panel consolidation and technical advisory relationships across North American and European channels.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| Novozymes A/S |
| Indigo Ag, Inc. |
| Koppert B.V. |
| Valent BioSciences |
| Verdesian Life Sciences |
| Others |
Supply & Pricing Matrix
Formulation chemist scarcity in Denmark and Germany creates labor-cost differentials that widen spreads between premium multi-microbial cocktails and economy-grade single-strain concentrates. Buyers in North American seed company procurement panels absorb premium pricing for performance-guaranteed bundles, while spot purchasers in shallow cooperative regions face sharper price sensitivity.
Pricing Analysis
Input-cost pass-through from molasses and soy-derived nutrient media volatility shapes contract-based long-term offtake as the dominant pricing model. Price differentiation rests on certification grade—EPA FIFRA registration confers tier premiums over unregistered concentrates—and volume scale, with seed companies locking multi-year supply agreements. Cost compression in economy-tier Bacillus formulations is intensifying because Brazilian and Vietnamese mid-scale fermentation facilities are achieving viable titers previously requiring Danish infrastructure. Independent farmers exhibit highest price sensitivity; integrated seed companies demonstrate least sensitivity due to bundled trait licensing economics.
Supply Chain Analysis
Reverse-logistics flows for expired or temperature-compromised microbial concentrates remain underdeveloped, creating working capital burdens for distributors holding shelf-stable inventory across multiple growing seasons. Geographic supply concentrates in Denmark, Germany, and Brazil, with critical germplasm repositories and fermentation infrastructure anchoring European output. Raw material dependencies draw from agricultural commodity cycles—molasses, soy meal, and mineral salts—while polymer matrix encapsulation inputs feed from specialty chemical suppliers. Single-source vulnerability concentrates around Danish strain banking for Trichoderma germplasm. Distribution runs through seed company technical centers and agricultural cooperative inoculation facilities, with direct-to-farmer channels shallow outside North American Corn Belt and Brazilian Cerrado.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Microbial Based Biological Seed Treatment Market functions as a stable compounder, with regulatory chemistry substitution under EU Green Deal mandates delivering predictable demand expansion regardless of commodity price cycles.
For Market Incumbents: Extend performance-guarantee contract terms to lock seed company procurement panels before Brazilian and Vietnamese fermentation scale-up erodes concentrate premiums. Backward integration into strain banking in Copenhagen or Ludwigshafen defends against biosecurity chokepoint risks. Prioritize polymer matrix encapsulation R&D to extend Trichoderma shelf stability beyond competing Bacillus offerings. For New Entrants and Emerging Players: Independent farmers in India's Punjab and Haryana wheat systems represent an underserved buyer archetype with shallow cooperative penetration and unmet demand for Azotobacter-based cereal inoculants. Drone-based aerial inoculation for cover crop segments offers a go-to-market angle that bypasses capital-intensive seed-coating infrastructure. ANVISA registration complexity in Brazil confers exclusivity windows for navigated entrants. For Investors and Strategic Acquirers: Agricultural chemical conglomerates with crop science divisions are the most active acquirer in this space, seeking fermentation-to-formulation platforms to fill biological portfolio gaps. Mid-scale biomanufacturers with captive strain libraries and regional production footprints in Argentina or Vietnam represent prime acquisition targets over a long-term viability window. Monitor EPA FIFRA registration queue velocity and EU REACH equivalence agreement progress as inflection indicators for formulation registration cost concentration or dissipation.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Acquisition | Captive germplasm repositories in Denmark reduce biosecurity chokepoint exposure for formulators. |
| Polymer Encapsulation Scale-Up | Danish matrix technology extends Trichoderma viability across multiple growing seasons. |
| Multi-Jurisdiction Registration | EPA FIFRA and EU REACH alignment cuts duplicate toxicology study burdens. |
| Cooperative Inoculation Infrastructure | Brazilian Cerrado facilities demonstrate regional penetration depth for adjacent microbial categories. |
| Carbon Credit Protocol Integration | Australian and Canadian agricultural markets monetize nitrogen-fixing treatment verification. |
Research Methodology
Multiple input streams—executive interviews with seed company procurement directors, fermentation platform technical leads, and agricultural cooperative agronomists; regulatory filing analysis from EPA, ECHA, and India's Central Insecticides Board; and customs trade data on microbial concentrate imports—were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of integrated agrochemical conglomerates, ANVISA strain registration databases, and EU F-Gas Regulation implementation reports. Primary fieldwork captured formulation chemist scarcity assessments and seed treater retrofit requirements.
Data-stream reconciliation across microbial type, application crop, formulation format, and end-user category dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume builds and value-per-unit trajectories, with inputs from planted hectarage forecasts, treatment penetration rates by crop system, and regulatory substitution elasticity assumptions. Industry-specific forecast inputs included EU Green Deal implementation timelines and Brazilian cooperative inoculation facility expansion plans.
Inputs from regulatory agencies and seed company technical centers were available through the study window; gaps in real-time fermentation capacity utilization data introduce uncertainty bands around concentrate supply elasticity assumptions. Forecasts reflect documented assumptions regarding strain registration pathway durations and polymer encapsulation adoption curves. Practitioners should monitor EU REACH equivalence agreement negotiations and ANVISA biosecurity protocol amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Salinomycin Market