
 Microbial API Market | 2026-2036
Microbial API Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial API Market Analytics
Market Context with Strategic Players
Recombinant DNA-derived APIs are pivoting away from traditional chemical synthesis toward precision fermentation platforms, slashing solvent use and carbon intensity. BASF SE leverages its integrated biotechnology hubs in Germany to sustain cost leadership in industrial enzyme APIs. Lonza Group AG anchors high-value microbial manufacturing through Swiss-based contract development capabilities. DSM-Firmenich differentiates its portfolio with aroma-chemical and vitamin precursors produced via engineered yeast strains.
Technical Definition and Structural Segments
Microbial active pharmaceutical ingredients comprise therapeutic compounds biosynthesized through bacterial, fungal, or yeast fermentation processes, typically requiring pH-controlled bioreactors operating at 25-37°C with dissolved oxygen monitoring to ensure batch consistency. These APIs serve as the molecular foundation for antibiotics, enzyme therapies, and nutritional additives across human and animal health applications. Antibiotics retain the largest revenue share within product type segmentation, though enzymes are gaining traction in biologic drug conjugation. Pharmaceutical applications dominate end-use demand, while biotechnology represents the fastest-expanding application segment driven by CRISPR-associated protein production.
Regulatory Framework and Forward Outlook
FDA current good manufacturing practice mandates and EMA's ICH Q3D elemental impurity guidelines enforce stringent microbial purity thresholds that filter out subscale fermenter operators. China's NMPA now requires continuous manufacturing data submissions for imported microbial APIs, tightening market access for non-domestic suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs to avoid dual-registration burdens.
Market Dynamics
Fermentation capacity concentration in India and China is redrawing procurement geography, as Western buyers confront single-source dependencies for generic antibiotic APIs and statin intermediates.
Growth Catalysts
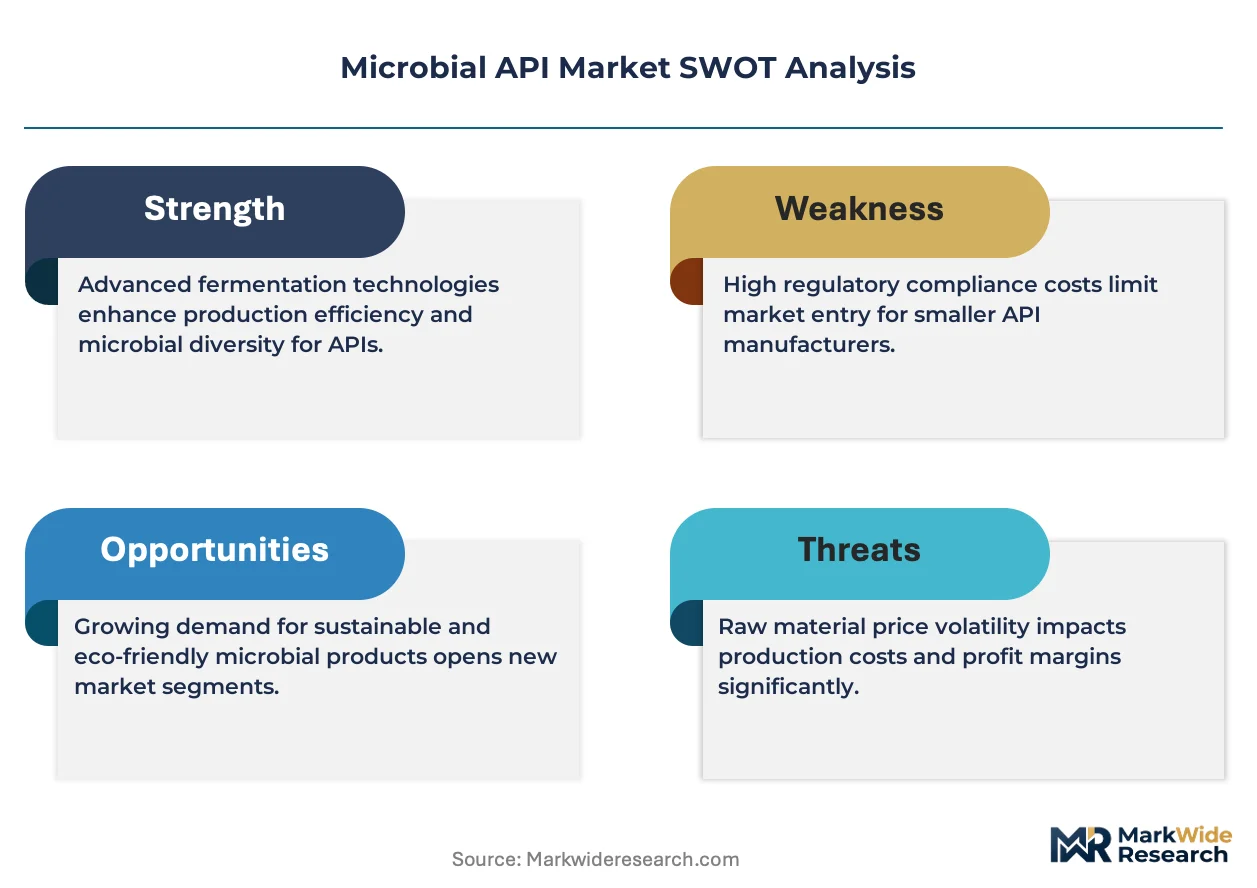
- ICH Q3D Elemental Impurity Guidelines:EMA's tightened thresholds for heavy-metal contamination are forcing facility upgrades that filter out subscale competitors, consolidating volume among compliant producers.
- Continuous Manufacturing Mandates:China's NMPA now requires real-time data submissions for imported microbial APIs, accelerating automation investments among export-oriented fermenter operators.
- Bioconjugation Demand:Enzyme therapies for antibody-drug conjugates are pulling capacity away from traditional antibiotic fermentation toward high-purity recombinant protein production.
Market Restraints
- Feedstock Volatility:Corn syrup and soybean meal prices swing with agricultural commodity cycles, compressing margins for bulk fermentation operators lacking long-term supply contracts.
- Geographic Supply Concentration:Over 60% of global cephalosporin API fermentation sits in Shandong and Jiangsu provinces, creating systemic disruption risk from regional environmental enforcement actions.
- Endotoxin Control Costs:LAL testing and depyrogenation infrastructure requirements price out entrants below 50,000-liter bioreactor scale.
Strategic Opportunities
- CRISPR-Associated Protein Production:Gene-editing tool manufacturing represents a greenfield application segment with pricing power distinct from commoditized antibiotics.
- Swissmedic GMP Certification:Swiss regulatory alignment with FDA standards opens premium pricing tiers for European contract manufacturers serving biotech innovators.
- Precision Fermentation Convergence:Synthetic biology platforms combining AI-driven strain engineering with automated bioprocess control are collapsing development timelines for novel molecules.
Industry Challenges
- Bioprocess Engineer Scarcity:PhD-level expertise in metabolic pathway optimization and scale-up troubleshooting commands premium compensation, constraining expansion timelines.
- Legacy ERP Integration:Continuous manufacturing data streams from smart bioreactors clash with batch-record systems designed for 1990s compliance workflows.
- Patent Thicket Navigation:Engineered yeast strain IP held by academic institutions and biotech startups complicates freedom-to-operate assessments for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial API Market |
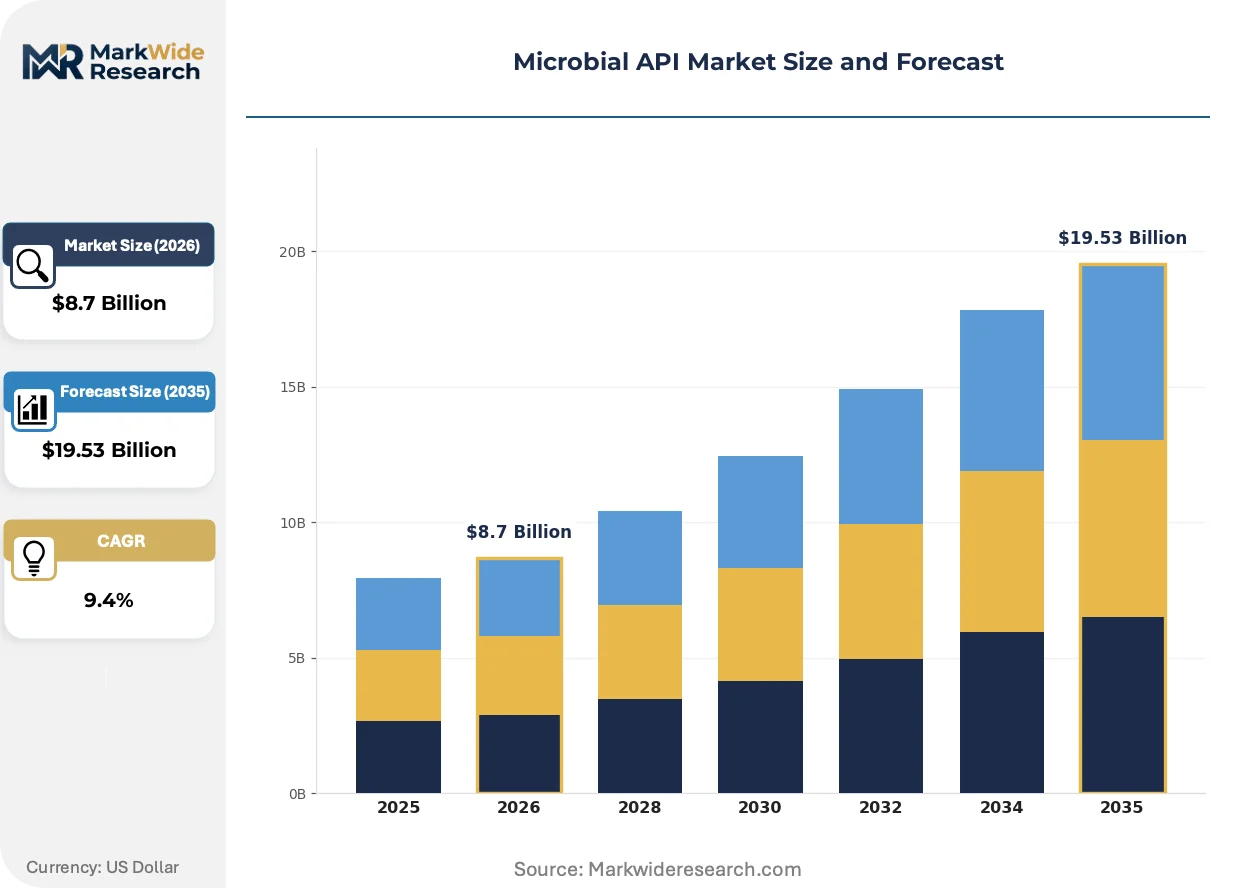
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Enzymes, Amino Acids, Polysaccharides Application: Pharmaceuticals, Agriculture, Food & Beverage, Biotechnology End User: Hospitals, Research Institutions, Pharmaceutical Companies, Biotech Firms Delivery Mode: Injection, Oral, Topical, Inhalation |
| Companies Covered | BASF SE, KOLON LIFE SCIENCE, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Tianjin Tianyao Pharmaceuticals Co., Ltd., DSM-Firmenich, Lonza Group AG, Xellia Pharmaceuticals, CSPC Pharmaceutical Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial API Market Evolving Landscape
Continuous processing architectures and single-use bioreactor systems are displacing stainless-steel batch infrastructure, compressing changeover times and enabling multi-product flex manufacturing.
Single-use bioreactor technology is absorbing capital allocation from traditional stainless-steel installations. Contract manufacturers in South Korea and Italy are adopting 2,000-liter disposable vessels for clinical-phase microbial APIs. The technology is absorbing validation burdens and cleaning downtime that previously locked facilities into single-product campaigns.
REACH authorization requirements for solvent-intensive chemical synthesis are redirecting pharmaceutical intermediate production toward aqueous fermentation routes. EMA's tightened environmental risk assessments now factor carbon intensity into marketing authorization renewals. Antibiotic APIs with fermentation-based supply chains are gaining preference in EU tender processes.
Buyers are consolidating supplier panels from twelve-plus vendors to three or four strategic partners with integrated quality and regulatory capabilities. Large generic pharmaceutical firms in the United States now require dual-sourcing from fermenters with harmonized USP-EP-ChP documentation. This concentration is most visible in injectable cephalosporin procurement, where qualification costs exceed $2 million per supplier site.
Microbial API Market Segmentation
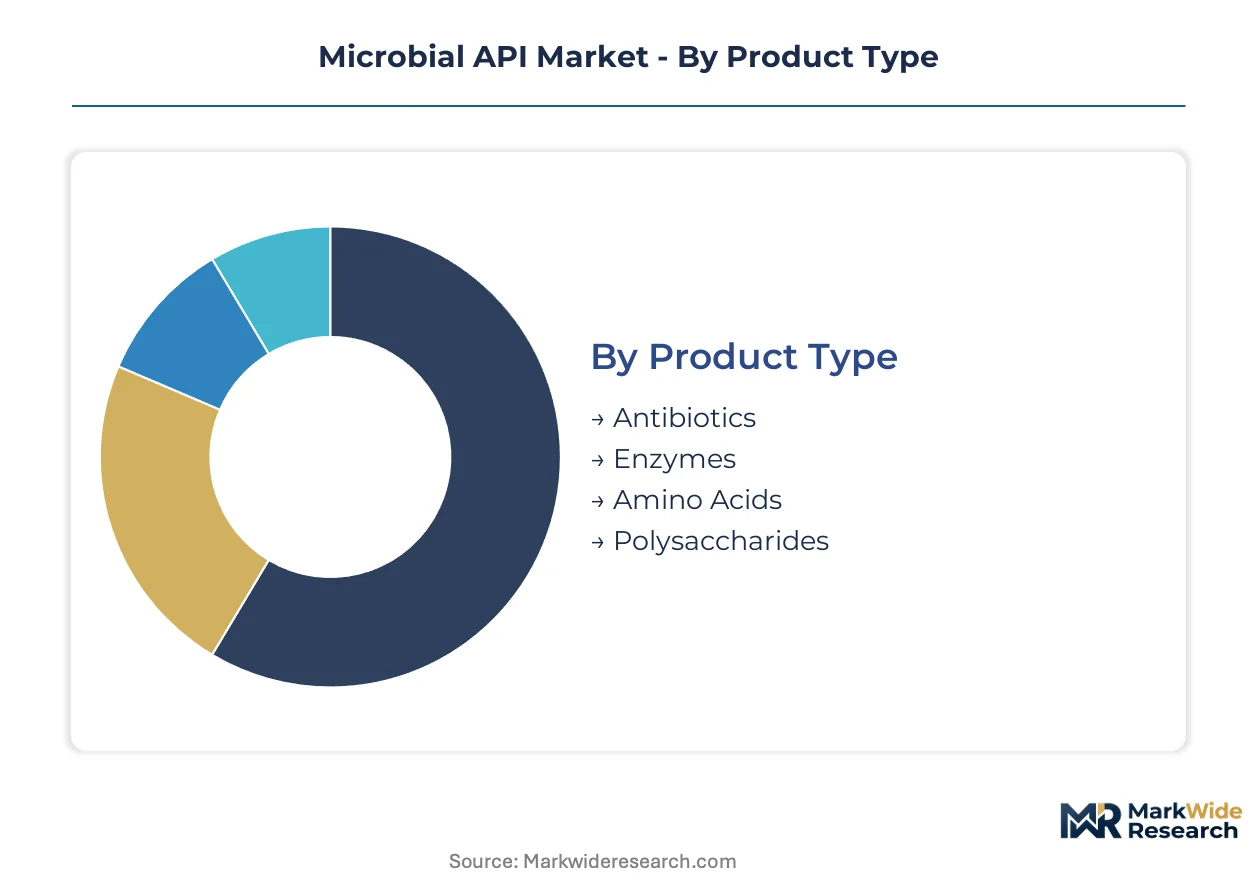
Segmentation in the microbial API market reveals distinct manufacturing footprints and regulatory pathways. Each dimension exposes different margin structures, from bulk fermentation commodities to precision-engineered biologics requiring specialized bioreactor configurations.
Product Type:
Standalone fermentation products dominate bulk procurement contracts, while embedded enzyme systems integrate into downstream bioprocessing workflows.
- Antibiotics:Cephalosporin and penicillin derivatives synthesized via submerged fermentation in stainless-steel or single-use bioreactors. Demand concentrates in injectable formulations across South Korea and Italy as hospital-acquired infection protocols tighten. FDA and EMA impurity thresholds force continuous quality verification.
- Enzymes:Recombinant proteins engineered for therapeutic and industrial catalysis, requiring pH-controlled environments with dissolved oxygen monitoring. CRISPR-associated protein production is pulling capacity from traditional antibiotic lines in Swiss and German contract manufacturing facilities.
- Amino Acids:Nutritional and pharmaceutical-grade building blocks produced via Corynebacterium glutamicum fermentation. China’s NMPA mandates real-time manufacturing data for imported grades.
- Polysaccharides:Complex carbohydrate APIs including hyaluronic acid and xanthan gum for medical and food applications. Indian producers are scaling fermentation capacity for export markets.
Antibiotics lead volumes today; enzymes are gaining share fastest.
Application:
Cost tier stratification separates commodity fermentation outputs from high-purity biologic intermediates commanding premium qualification overhead.
- Pharmaceuticals:Human and veterinary drug actives requiring GMP compliance across FDA, EMA, and NMPA jurisdictions. Injectable cephalosporins absorb the largest procurement budgets from U.S. generic firms.
- Biotechnology:Gene-editing tools and diagnostic enzyme production. Precision fermentation platforms in Switzerland and South Korea are collapsing development timelines for novel molecules.
- Agriculture:Animal feed additives and crop protection actives with lower purity thresholds than pharmaceutical grades. Brazilian ANVISA and Indian FSSAI registrations govern import access.
- Food & Beverage:Fermentation-derived vitamins, enzymes, and acidulants for processed food applications. EU EFSA safety assessments determine market authorization timelines.
Pharmaceuticals absorb the largest revenue pool; biotechnology shows the steepest expansion trajectory.
End User:
Customer type determines batch size requirements, with hospital procurement favoring pre-qualified suppliers and research institutions accepting small-scale fermentation runs.
- Pharmaceutical Companies:Integrated generic manufacturers and innovator firms sourcing cephalosporin and statin intermediates. U.S. buyers now require dual-sourcing from fermenters with harmonized USP-EP-ChP documentation.
- Biotech Firms:Emerging companies outsourcing CRISPR protein and antibody-drug conjugate enzyme production to Swiss and South Korean contract manufacturers.
- Hospitals:Direct procurement of compounded injectable antibiotics with stringent endotoxin specifications. LAL testing requirements price out subscale suppliers.
- Research Institutions:Academic and government laboratories purchasing small-batch fermentation products for preclinical development. Chinese and Indian suppliers dominate this price-sensitive segment.
Pharmaceutical companies anchor procurement volumes; biotech firms are expanding orders most rapidly.
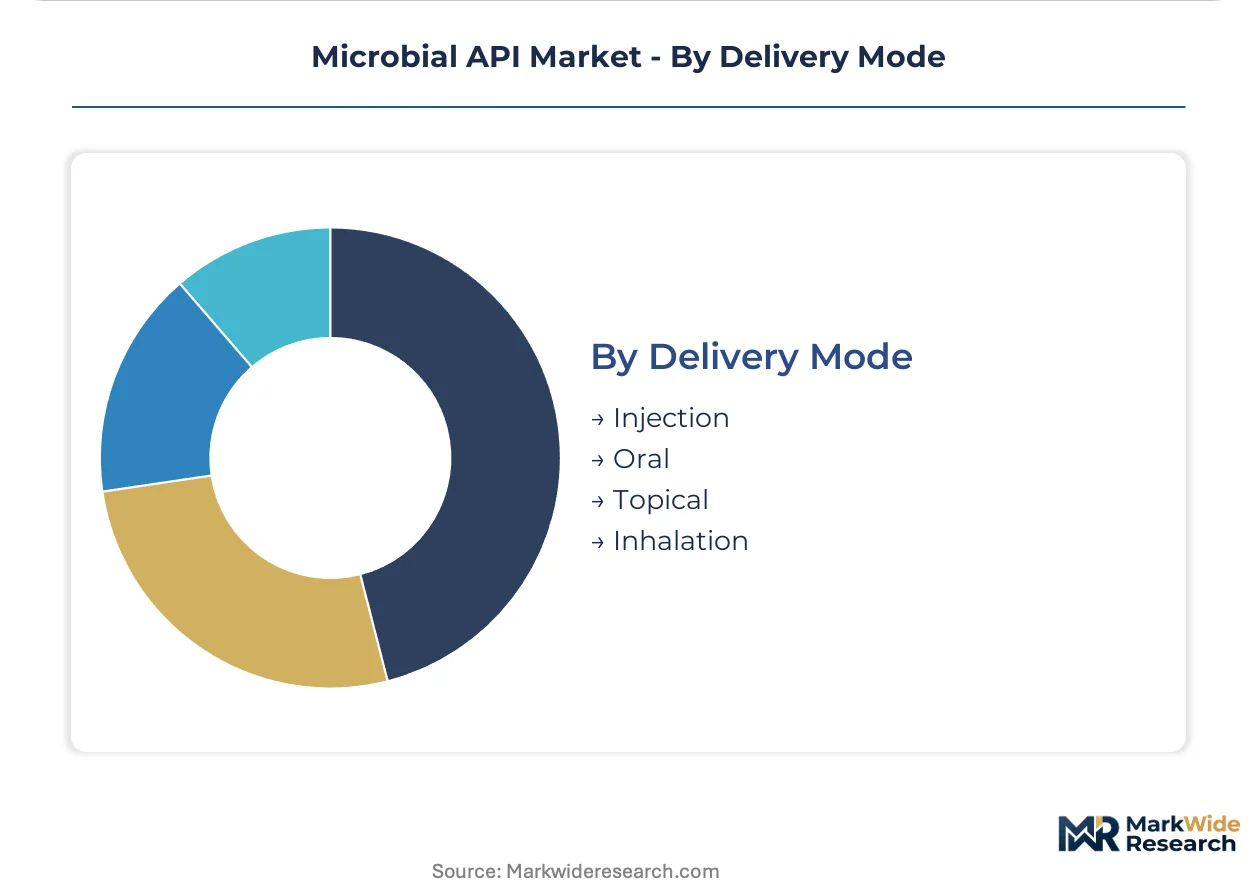
Delivery Mode:
Supply concentration varies by administration route, with injectable APIs requiring the most stringent pyrogen control and documentation.
- Injection:Parenteral formulations demanding WFI-grade water systems and validated depyrogenation protocols. Cephalosporin injection APIs concentrate in Shandong and Jiangsu provinces.
- Oral:Tablet and capsule actives with broader impurity tolerances than injectable grades. Indian fermentation hubs supply cost-optimized oral antibiotic APIs.
- Topical:Cream, ointment, and ophthalmic preparations requiring particulate matter controls below injectable standards. Italian manufacturers specialize in clinical-phase topical enzyme APIs.
- Inhalation:Pulmonary delivery systems with particle size distribution requirements. Limited fermentation-derived actives currently serve this route.
Injection commands the highest qualification barriers; oral delivery retains the largest volume footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces concentrate over sixty percent of global cephalosporin API fermentation capacity, creating systemic exposure to environmental enforcement actions. Western buyers confront single-source dependencies for generic antibiotic APIs and statin intermediates. Procurement geography is redrawing around India and China as pharmaceutical companies scale fermentation-based manufacturing.
United States
Generic pharmaceutical firms absorb the largest procurement budgets for injectable cephalosporins, with qualification costs exceeding two million dollars per supplier site. FDA current good manufacturing practice mandates enforce stringent microbial purity thresholds that filter out subscale fermenter operators. Hospital procurement in the Northeast and Midwest favors pre-qualified suppliers with harmonized USP-EP-ChP documentation.
China
The NMPA now requires continuous manufacturing data submissions for imported microbial APIs, tightening market access for non-domestic suppliers. Real-time data submission mandates accelerate automation investments among export-oriented fermenter operators. Tianjin and Hebei province pharmaceutical clusters are scaling fermentation capacity for generic antibiotics targeting Western markets.
India
Pharmaceutical companies in Maharashtra and Gujarat are scaling fermentation-based manufacturing for generic antibiotics and statin intermediates. CDSCO alignment with ICH Q3D elemental impurity guidelines forces facility upgrades that consolidate volume among compliant producers. Mumbai-Pune corridor fermentation hubs supply cost-optimized oral antibiotic APIs to regulated markets.
Switzerland
Swissmedic GMP certification opens premium pricing tiers for European contract manufacturers serving biotech innovators. Swiss regulatory alignment with FDA standards enables dual-qualification efficiency for gene-editing tool manufacturing. Basel-region biotechnology clusters anchor high-value microbial manufacturing through contract development capabilities.
South Korea
MFDS oversight of bioconjugation demand pulls capacity toward high-purity recombinant protein production for antibody-drug conjugates. Seoul-Incheon corridor contract manufacturers adopt two-thousand-liter disposable vessels for clinical-phase microbial APIs. Single-use bioreactor technology absorbs validation burdens that previously locked facilities into single-product campaigns.
Microbial API Market Competitive Landscape
Global majors compete with regional champions across fermentation capacity and regulatory qualification depth. The vendor base stratifies between integrated chemical conglomerates with biotechnology hubs and specialized contract manufacturers with Swiss or South Korean regulatory positioning. Three archetypes dominate: precision fermentation platform operators, bulk antibiotic fermentation specialists, and hybrid chemical-biotechnology integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with automation investments accelerating in response to Chinese continuous manufacturing mandates.
Within the precision fermentation tier, DSM-Firmenich and Lonza Group AG exemplify platform operators combining engineered strain capabilities with automated bioprocess control. BASF SE anchors the hybrid archetype through integrated biotechnology hubs sustaining cost leadership in industrial enzyme APIs. Among Asia-based specialists, Tianjin Tianyao Pharmaceuticals Co., Ltd. occupies a position within bulk antibiotic fermentation supply chains serving regulated export markets. These three entities represent distinct strategic postures: biotechnology-led premium positioning, chemical-biotechnology integration, and scale-driven generic API supply.
| Leading Market Players |
|---|
| BASF SE |
| KOLON LIFE SCIENCE |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Tianjin Tianyao Pharmaceuticals Co., Ltd. |
| DSM-Firmenich |
| Lonza Group AG |
| Xellia Pharmaceuticals |
| CSPC Pharmaceutical Group Ltd. |
| Others |
Value Network & Pricing Analysis
Swissmedic-GMP-certified premium tiers command three-to-five-fold markups over CDSCO-registered economy grades, with that bifurcation embedding directly into procurement contracts and distribution network design. Pharmaceutical buyers in the United States and Europe absorb qualification costs exceeding two million dollars per supplier site, while Indian and Chinese fermentation hubs compete on landed cost for oral antibiotic APIs.
Pricing Analysis
Feedstock cost pass-through from corn syrup and soybean meal volatility compresses margins for bulk fermentation operators lacking long-term agricultural supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-certified CRISPR protein manufacturers from FDA-registered injectable cephalosporin suppliers and CDSCO-registered oral antibiotic producers. Cost compression in economy tiers is intensifying because NMPA continuous manufacturing mandates force automation investments that smaller fermenters cannot absorb. Hospital procurement committees demonstrate lowest price sensitivity for WFI-grade injectable APIs, while research institutions drive aggressive negotiation on small-batch enzyme orders.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai anchor hub-and-spoke patterns for temperature-controlled API shipments to formulation facilities. Manufacturing gravity centers on Shandong and Jiangsu provinces for cephalosporin fermentation, Maharashtra and Gujarat for oral antibiotic APIs, and the Basel region for high-value bioconjugation enzymes. Raw material dependencies draw from Ukrainian corn, Brazilian soybean meal, and Chinese dextrose supply pools. Single-source vulnerability concentrates in Shandong province environmental enforcement exposure. Distribution runs through qualified contract logistics providers with validated cold-chain documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA and EMA impurity threshold tightening functions as a regulatory compounder, with ICH Q3D guidelines filtering subscale competitors and consolidating volume among compliant producers.
For Market Incumbents: Deepen backward integration into engineered yeast strain IP through licensing agreements with academic institutions holding CRISPR-associated protein patents. Expand fermentation capacity in Tianjin and Hebei provinces to capture NMPA-registered export volume before continuous manufacturing mandates harden. Consolidation among subscale Indian competitors presents acquisition opportunities for CDSCO-aligned facility networks.
For New Entrants and Emerging Players: The premium-economy price-point gap in CRISPR-associated protein production opens white-space targeting of biotech firm outsourcing demand. South Korean contract manufacturers with MFDS alignment and single-use bioreactor infrastructure represent the most penetrable competitive tier. Precision fermentation platform development with AI-driven strain engineering offers a defensible go-to-market angle distinct from commoditized antibiotic supply.
For Investors and Strategic Acquirers: Consolidation pressure builds where CDSCO facility upgrade requirements exceed subscale operator balance sheet capacity. Five-to-ten-year viability favors precision fermentation platform operators with automated bioprocess control and Swissmedic regulatory positioning. Acquisition targets should demonstrate harmonized USP-EP-ChP documentation and dual-sourcing relationships with U.S. generic pharmaceutical firms. Watch NMPA enforcement patterns on continuous manufacturing data submissions as the signal for export-oriented capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Development | AI-driven strain engineering collapses timelines for novel CRISPR protein manufacturing. |
| Swissmedic GMP Certification Investment | Swiss regulatory alignment opens premium pricing tiers for biotech contract manufacturers. |
| Backward Integration into Feedstock Supply | Long-term corn syrup and soybean meal contracts insulate margins from agricultural volatility. |
| Single-Use Bioreactor Infrastructure Deployment | Disposable vessel technology absorbs validation burdens and enables multi-product flex manufacturing. |
| Harmonized USP-EP-ChP Documentation Investment | Dual-qualification efficiency meets U.S. generic firm procurement requirements for injectable cephalosporins. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation facility directors, regulatory affairs leads at contract manufacturers, hospital procurement managers, and biotech firm outsourcing executives with secondary validation. FDA 483 inspection observations, EMA marketing authorization databases, NMPA import registration filings, and CDSCO manufacturing license records anchored supply-side assessment. Bottom-up capacity modeling and top-down demand triangulation from pharmaceutical company procurement disclosures cross-verified volume estimates.
Segment-weighting approaches distributed value across product type, application, end user, and delivery mode dimensions, with regional regulatory cluster effects explicitly modeled. CAGRs were derived from trajectory fitting to historical fermentation capacity expansion patterns and projected bioconjugation demand curves across the analysis window. Forecast inputs incorporated NMPA continuous manufacturing mandate implementation timelines and ICH Q3D elemental impurity threshold enforcement intensity.
Caveats apply where NMPA regulatory enforcement patterns, Shandong province environmental actions, or CRISPR protein demand inflections could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Mycoplasma Plate Antigens Market