
 Automated Microbial Detection Systems Market | 2026-2036
Automated Microbial Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Microbial Detection Systems Market Outlook
Contract research organizations is bifurcating from pharmaceutical companies as the fastest-expanding buyer archetype in automated microbial detection. Becton, Dickinson and Company leverages its installed base in clinical diagnostics to extend into environmental monitoring applications. bioMérieux anchors European demand through specialized culture detection platforms serving food safety regulators. Thermo Fisher Scientific dominates the North American instrument landscape with integrated PCR workflows for pharmaceutical quality control.
Automated microbial detection systems comprise instrument platforms that enumerate, identify, or characterize microorganisms without manual plating or microscopic enumeration, typically achieving detection thresholds of 1 CFU per sample through ATP bioluminescence or nucleic acid amplification methods. These systems serve industrial and commercial purposes by replacing 48-72 hour compendial methods with same-shift actionable results for release decisions. PCR Systems command the largest revenue pool among product types due to their regulatory acceptance for pathogen screening in food and pharmaceutical matrices. Next-Generation Sequencing represents the fastest-expanding technology segment as microbial identification demands shift from phenotypic to genotypic characterization for root-cause contamination investigations.
The FDA enforces 21 CFR Part 11 electronic records requirements that shape software architecture and data integrity features in instruments sold to US pharmaceutical manufacturers. The EMA's Annex 1 revision mandates continuous viable monitoring in Grade A environments, directly stimulating demand for real-time optical sensor platforms in European aseptic filling operations. The WHO's guidance on good manufacturing practices for biological products creates harmonized quality expectations that instrument vendors must address across multiple national submissions. Stakeholders should monitor how regulatory convergence between FDA and EMA data integrity expectations reshapes validation service requirements and aftermarket revenue streams.
Market Dynamics
The FDA's Process Analytical Technology initiative and EMA's Annex 1 revision are compressing batch release timelines, forcing pharmaceutical manufacturers to abandon 48-hour compendial methods for same-shift microbial detection platforms.
Growth Catalysts
- EU Annex 1 sterile manufacturing mandates:The EMA's revised guidance on continuous viable monitoring in Grade A environments is accelerating procurement of real-time optical sensor platforms across European aseptic filling operations.
- ATP bioluminescence adoption:Food safety regulators are validating rapid ATP-based detection for environmental monitoring, replacing traditional plating methods in high-throughput production facilities.
- German biologics cluster investment:Concentrated capital deployment in monoclonal antibody manufacturing around Munich and Heidelberg is driving instrument procurement for contamination control.
Market Restraints
- Capital intensity of PCR workflow integration:Pharmaceutical quality control labs face six-figure instrument investments plus dedicated cleanroom infrastructure for nucleic acid amplification platforms.
- Reagent supply concentration:Polymerase enzymes and fluorescent probe chemistries concentrate among three specialized biochemical suppliers, creating input cost volatility and qualification delays.
- 21 CFR Part 11 compliance friction:FDA electronic records requirements impose software architecture constraints that extend validation timelines and lock vendors into legacy data integrity frameworks.
Strategic Opportunities
- Next-Generation Sequencing for root-cause analysis:Genotypic microbial identification is displacing phenotypic methods in contamination investigations, opening service revenue streams for sequencing-as-a-service models.
- Contract research organization procurement expansion:CROs are bifurcating from pharmaceutical companies as a distinct buyer archetype with specialized high-throughput screening requirements.
- WHO GMP harmonization:The WHO's guidance on biological product manufacturing creates unified quality expectations that instrument vendors can address through single multi-jurisdictional submissions.
Industry Challenges
- Microbiology-automation skill convergence:Facilities struggle to hire personnel possessing both traditional microbiology expertise and automated platform programming capabilities.
- Legacy LIMS integration complexity:New detection platforms must interface with established laboratory information management systems through custom API development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Microbial Detection Systems Market |
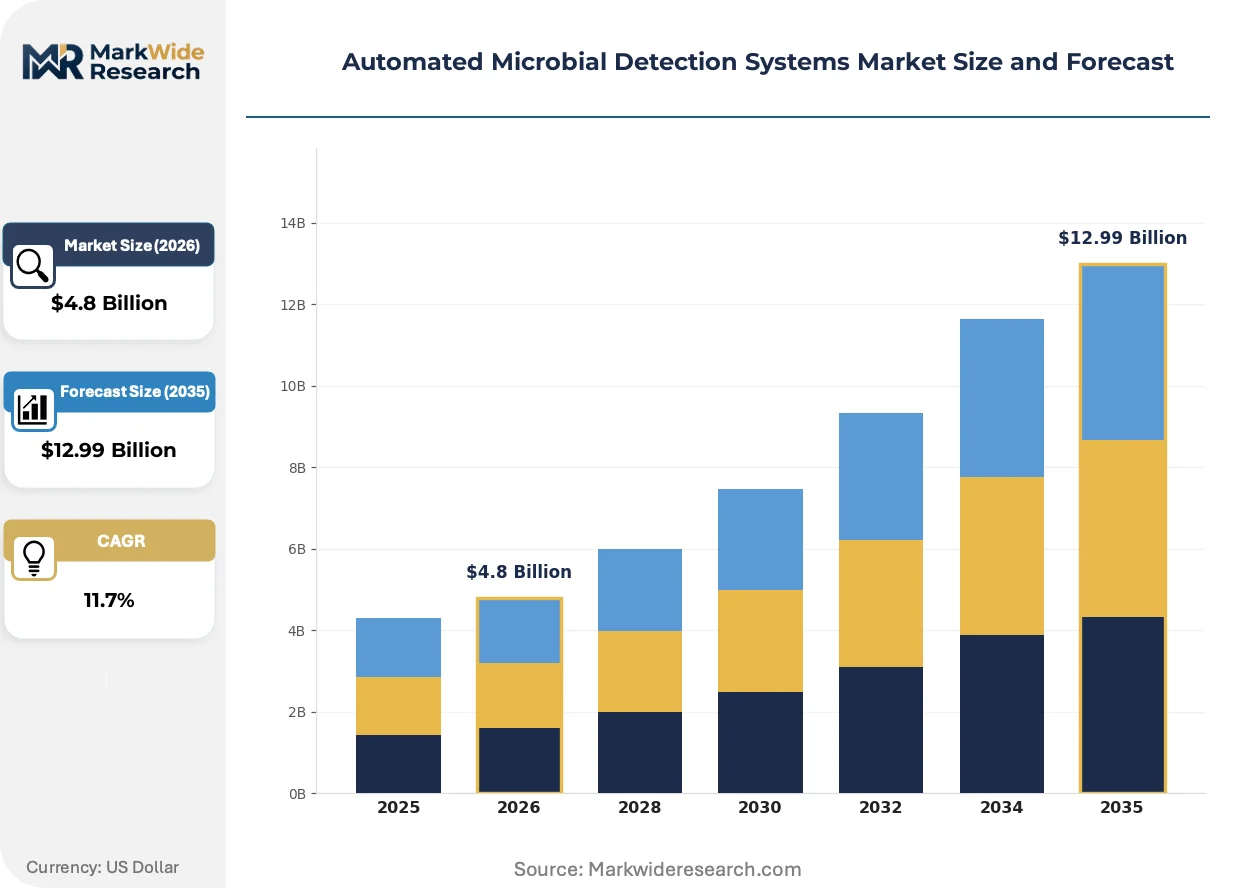
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Systems, Culture Detection Systems, Next-Generation Sequencing, Flow Cytometry End User: Pharmaceutical Companies, Food and Beverage Manufacturers, Environmental Testing Laboratories, Contract Research Organizations Technology: Electrochemical Sensors, Optical Sensors, Microfluidics, LAMP Technology Application: Quality Control, Research & Development, Clinical Diagnostics, Pathogen Testing |
| Companies Covered | Becton, Dickinson and Company, bioMérieux, Thermo Fisher Scientific, Danaher Corporation, QIAGEN, Merck KGaA, Charles River Laboratories, Bruker Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Microbial Detection Systems Market Strategic Shifts
Detection technology is converging with data analytics platforms, compressing the time from sample acquisition to actionable contamination intelligence from shifts to minutes.
Microfluidic sample preparation cartridges are miniaturizing. These devices automate cell lysis and nucleic acid extraction in disposable consumables. Biologics manufacturers in Germany and Switzerland are adopting them for in-process monitoring. The technology is miniaturizing benchtop workflows into handheld formats, enabling point-of-use environmental testing without centralized lab infrastructure.
EMA's Annex 1 revision mandates continuous viable particle monitoring in Grade A cleanrooms. This policy eliminates periodic grab-sampling approaches. Aseptic filling operations across France, Italy, and Spain are retrofitting isolators with real-time optical sensors. The regulation is forcing instrument vendors to validate sensor performance against traditional growth-based methods.
Service unbundling is fragmenting traditional procurement. Pharmaceutical buyers are separating instrument capital expenditure from validation, training, and reagent supply contracts. This pattern concentrates in North American quality control departments where finance teams demand granular cost visibility. Third-party validation specialists are capturing service revenue previously retained by original equipment manufacturers.
Automated Microbial Detection Systems Market Segmentation
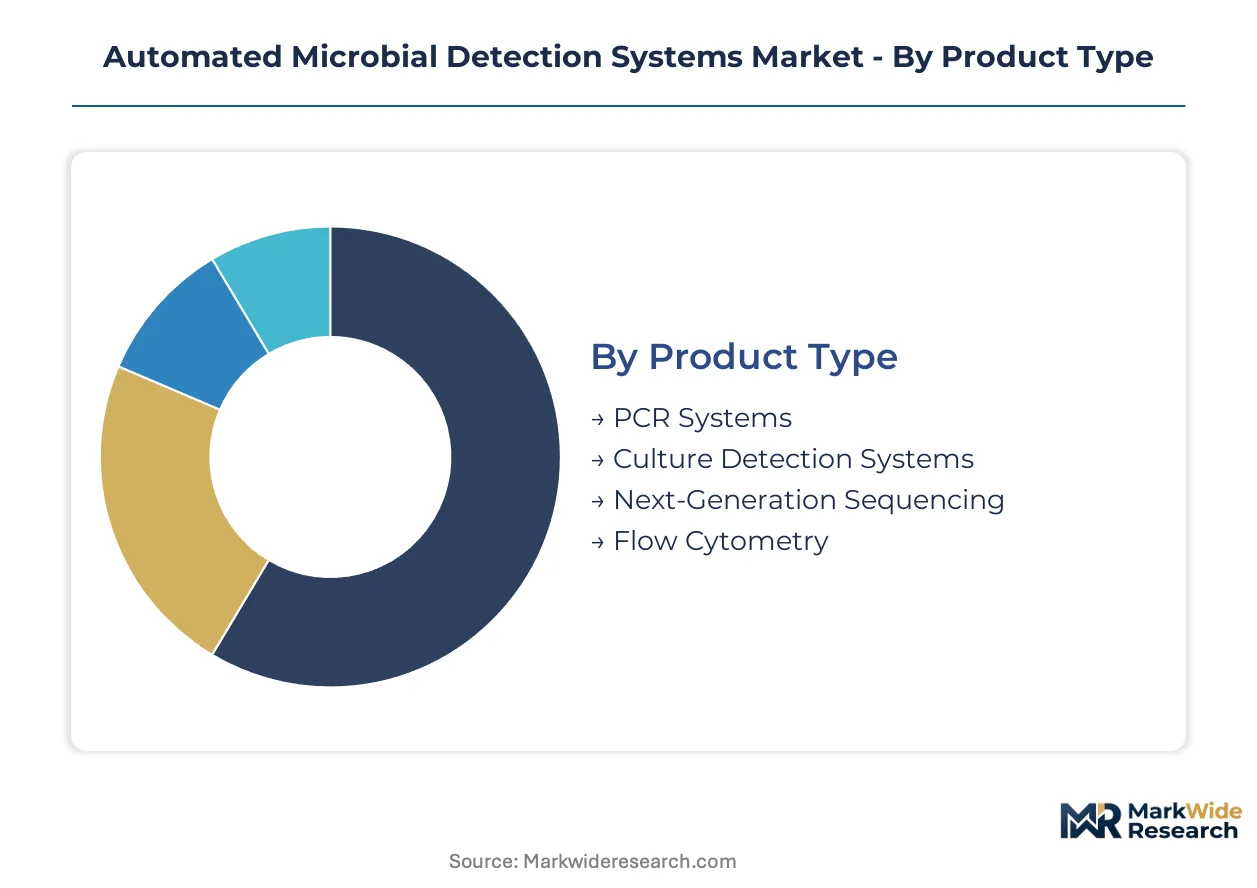
Automated microbial detection systems fragment across four analytical dimensions. Product type determines detection speed and capital intensity. End user concentration shapes procurement patterns and validation requirements. Technology selection drives reagent economics and operator skill demands. Application context dictates regulatory submission pathways and performance specifications.
Product Type:
Margin pools concentrate in platforms achieving regulatory pre-qualification for pharmaceutical release testing, where instrument placement locks in multi-year consumable revenue streams.
- PCR Systems:Thermal cycling platforms amplify nucleic acid targets with detection thresholds reaching single-digit CFU equivalents. Pharmaceutical quality control labs in the United States and Germany dominate procurement, driven by FDA 21 CFR Part 11 compliance requirements and EMA Annex 1 sterile manufacturing mandates that disqualify slower growth-based methods for batch release decisions.
- Next-Generation Sequencing:Massively parallel sequencing platforms identify microorganisms through ribosomal RNA gene profiling or whole-genome characterization. Contract research organizations and root-cause investigation services are expanding capacity fastest, as genotypic identification displaces phenotypic biochemical testing for contamination source tracking in biologics manufacturing.
- Culture Detection Systems:Automated incubation and imaging platforms enumerate colony-forming units without manual plate reading. Food safety regulators validate these for environmental monitoring programs.
- Flow Cytometry:Laser-based cell sorting and enumeration platforms achieve rapid viability assessment. Research and development applications drive placement in academic and government laboratories.
PCR Systems hold installed capacity across pharmaceutical manufacturing sites. Next-Generation Sequencing is rotating up the share rankings as contamination investigation budgets expand.
End User:
Procurement authority is fragmenting as finance teams demand unbundled contracts separating capital expenditure from validation and reagent supply.
- Pharmaceutical Companies:In-house quality control departments operate under FDA and EMA mandates for continuous environmental monitoring. Batch release timeline compression is forcing abandonment of 48-hour compendial methods in favor of same-shift detection platforms, particularly at biologics manufacturing clusters in Germany and Switzerland.
- Contract Research Organizations:High-throughput screening operations require standardized platforms capable of handling diverse sample matrices with minimal method development. CROs are bifurcating from pharmaceutical companies as a distinct buyer archetype with specialized procurement workflows and volume-based pricing expectations.
- Food and Beverage Manufacturers:Environmental monitoring programs in high-throughput production facilities validate ATP bioluminescence and PCR methods for pathogen screening. Regulatory acceptance varies by national food safety authority.
- Environmental Testing Laboratories:Water quality and soil assessment applications demand ruggedized platforms capable of field deployment. Public utility contracts drive procurement cycles.
Pharmaceutical Companies anchor current revenue concentration. Contract Research Organizations are climbing the fastest as outsourcing of microbiological testing accelerates.
Technology:
Platform selection determines reagent supply chain exposure and operator training requirements, with electrochemical and optical sensors diverging in maintenance intensity.
- Optical Sensors:Real-time viable particle detection platforms use laser-induced fluorescence to enumerate microorganisms without culture enrichment. EMA Annex 1 revision mandates for Grade A cleanroom monitoring are accelerating retrofit installations across French, Italian, and Spanish aseptic filling operations, forcing validation against traditional growth-based reference methods.
- Microfluidics:Disposable cartridge systems automate cell lysis and nucleic acid extraction in miniaturized formats. Biologics manufacturers in Germany and Switzerland are adopting these for in-process monitoring, with handheld formats enabling point-of-use environmental testing without centralized laboratory infrastructure.
- Electrochemical Sensors:Amperometric and impedimetric platforms detect metabolic activity through redox reactions. Food safety applications dominate current deployment.
- LAMP Technology:Loop-mediated isothermal amplification operates without thermal cycling equipment, reducing capital barriers. Field-based pathogen detection programs in resource-limited settings drive adoption.
Optical Sensors command premium positioning in sterile manufacturing. Microfluidics is gaining share fastest as miniaturization reduces cleanroom footprint requirements.
Application:
Regulatory submission burden varies sharply across contexts, with quality control applications demanding extensive validation documentation that research use cases escape.
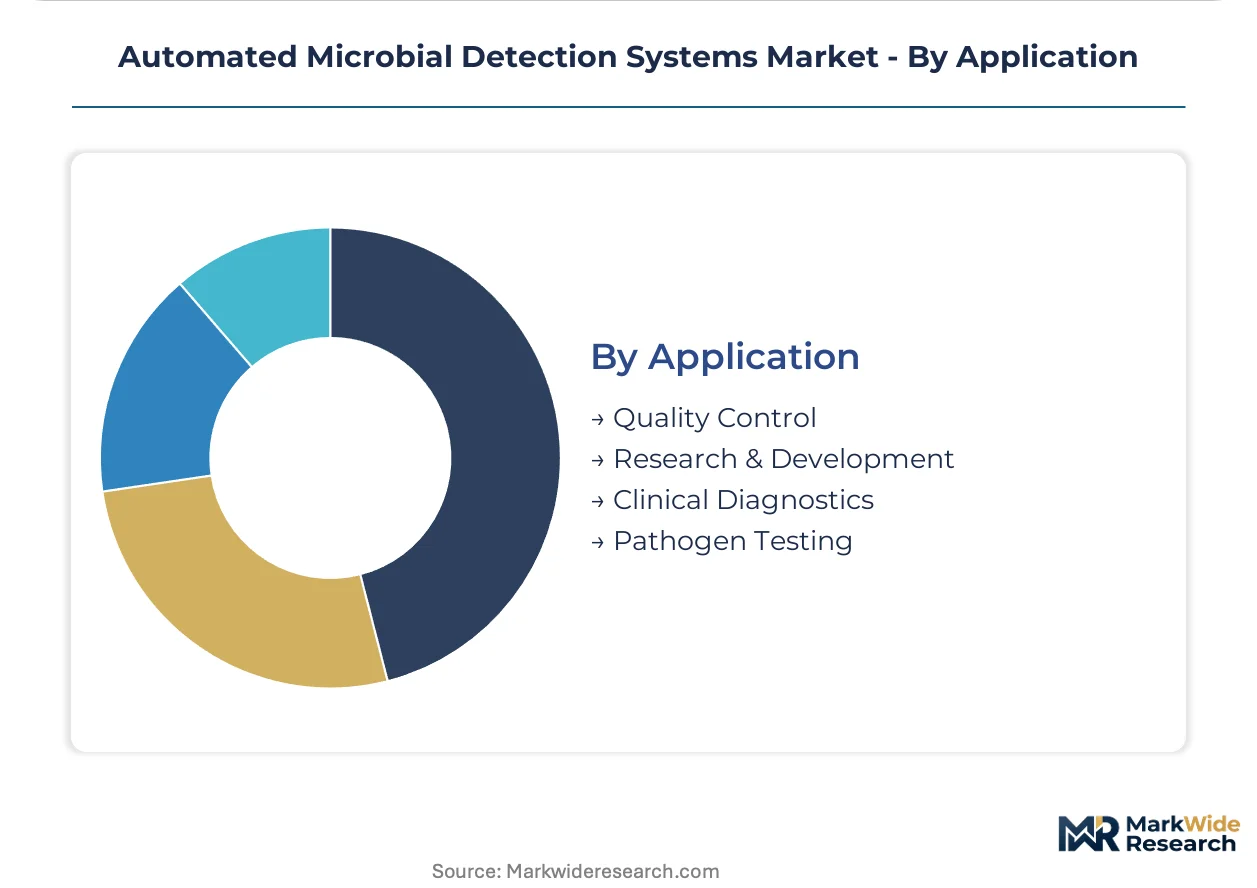
- Quality Control:Batch release and environmental monitoring applications require platforms validated against pharmacopeial reference methods. FDA Process Analytical Technology initiative and EMA Annex 1 revision are compressing acceptable detection timelines, forcing pharmaceutical manufacturers to replace growth-based methods with rapid alternatives.
- Pathogen Testing:Food safety and clinical screening applications prioritize detection speed over taxonomic resolution. Regulatory acceptance frameworks differ between FDA food safety mandates and clinical diagnostic approval pathways.
- Research & Development:Microbial characterization for strain development and fermentation optimization tolerates higher method development burden. Academic and biotechnology research departments drive demand.
- Clinical Diagnostics:Patient sample testing requires platforms meeting in vitro diagnostic regulatory standards. Hospital laboratory consolidation is concentrating procurement authority.
Quality Control holds the deepest installed base. Pathogen Testing is rotating up the share rankings as food safety regulators validate rapid methods for environmental monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and contract research organizations concentrate procurement in jurisdictions with stringent contamination control mandates and established biologics manufacturing infrastructure. The United States, Germany, Switzerland, Japan, and the United Kingdom anchor instrument demand through divergent regulatory pathways and cluster investments.
United States
FDA's 21 CFR Part 11 electronic records requirements and Process Analytical Technology initiative compress batch release timelines for pharmaceutical quality control labs. The agency mandates same-shift microbial detection alternatives to traditional 48-hour compendial methods. Biologics manufacturing clusters around Boston and San Francisco drive procurement of PCR-based platforms for environmental monitoring.
Germany
EMA Annex 1 revision on sterile manufacturing mandates continuous viable monitoring in Grade A cleanrooms, accelerating retrofit installations across aseptic filling operations. The country's national pharmaceutical regulator enforces validation against growth-based reference methods. Munich and Heidelberg biologics clusters concentrate monoclonal antibody production, driving instrument procurement for contamination control.
Switzerland
Swissmedic aligns with EMA standards while maintaining distinct submission requirements for automated detection platforms used in pharmaceutical release testing. The Basel biopharmaceutical corridor anchors demand for real-time optical sensors in sterile manufacturing. Microfluidic cartridge adoption concentrates in Swiss facilities seeking point-of-use environmental testing without centralized lab infrastructure.
Japan
PMDA's quality expectations for biological products create harmonized validation requirements that instrument vendors address through dedicated submissions. The country's national standards body certifies rapid microbial detection methods for pharmaceutical applications. The Kanto region around Tokyo concentrates biologics manufacturing investment, driving procurement of ATP bioluminescence platforms for compressed batch release.
United Kingdom
The Medicines and Healthcare products Regulatory Agency maintains post-Brexit alignment with EMA Annex 1 standards while operating independent inspection regimes. MHRA mandates data integrity frameworks comparable to FDA 21 CFR Part 11 for automated systems. The Golden Triangle biotech cluster between London, Cambridge, and Oxford drives demand for next-generation sequencing in root-cause contamination investigations.
Automated Microbial Detection Systems Market Competitive Environment
Player mix skews toward diversified life science conglomerates with installed bases in adjacent diagnostics segments. Market structure concentrates around three to five integrated platform vendors capable of delivering validated workflows across multiple regulatory jurisdictions. Strategic archetypes include clinical-to-industrial extenders leveraging diagnostics infrastructure, European specialists anchoring regional food safety and pharmaceutical demand, and North American integrators dominating PCR workflow standardization. Competitive moves center on validation service unbundling and multi-jurisdictional regulatory submission bundling.
Within the clinical-to-industrial extender archetype, Becton, Dickinson and Company occupies a position exemplifying installed-base leverage into environmental monitoring applications. bioMérieux represents the European specialist tier, anchoring regional demand through culture detection platforms serving food safety regulators. Thermo Fisher Scientific sits within the North American integrator category, exemplifying dominance in PCR workflow standardization for pharmaceutical quality control. These three entities collectively represent the concentration patterns visible across the vendor landscape.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| bioMérieux |
| Thermo Fisher Scientific |
| Danaher Corporation |
| QIAGEN |
| Merck KGaA |
| Charles River Laboratories |
| Bruker Corporation |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Polymerase enzyme substitution for fluorescent probe chemistries is redrawing procurement geography toward South Korean and German biochemical suppliers while compressing margin structures for mid-tier instrument vendors. This input shift simultaneously elevates reagent contract values and concentrates pricing power among three specialized enzyme manufacturers.
Pricing Analysis
Cost-plus contracts with polymerase price indexation dominate reagent supply agreements, locking pharmaceutical buyers into annual escalators tied to fermentation input costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated platforms from CE-marked equivalents and unvalidated research-use systems. Pricing pressure stems from CRO procurement offices demanding unbundled validation and training contracts. Contract research organizations exhibit highest price sensitivity; biologics manufacturers in Germany and Switzerland show lowest.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time reagent deliveries to European pharmaceutical clusters, extending safety stock requirements. Polymerase enzymes concentrate in South Korea and Germany; optical sensor components source from Japan and the United States; microfluidic cartridges manufacture in Switzerland and Ireland. Single-source vulnerability pervades thermostable enzyme supply. Distribution runs through authorized distributor networks with regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of personnel combining microbiology expertise with automated platform programming is constraining deployment velocity and elevating implementation risk for buyers. This capability gap favors vendors with embedded training ecosystems.
For Market Incumbents: Secure reagent supply exclusivity through backward integration into polymerase fermentation or long-term offtake agreements with South Korean biochemical suppliers. Lock in validation service revenue by acquiring third-party compliance specialists before CRO procurement offices complete vendor consolidation. Next-generation sequencing substitution for phenotypic identification threatens culture detection platform margins. For New Entrants and Emerging Players: Differentiate on microfluidic cartridge miniaturization for point-of-use environmental monitoring in Swiss and German biologics facilities. Target food safety regulators in France and Italy validating ATP bioluminescence for high-throughput production monitoring. Pursue sequencing-as-a-service models for root-cause contamination investigations where capital barriers exclude in-house platform acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward European specialists with anchored regulatory relationships and validated Annex 1 compliance pathways. Long-term viability hinges on multi-jurisdictional submission capabilities spanning FDA 21 CFR Part 11 and EMA data integrity expectations. Monitor EMA-FDA regulatory convergence as inflection signal for validation service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Supply Integration | Backward integration into polymerase fermentation secures margin control against South Korean supplier concentration. |
| Validation Service Acquisition | Third-party compliance specialist capture locks in aftermarket revenue from unbundled CRO procurement contracts. |
| Microfluidic Platform Launch | Handheld cartridge miniaturization enables point-of-use testing without centralized lab infrastructure in Swiss facilities. |
| Multi-Jurisdictional Submission | Single FDA-EMA validation package reduces regulatory friction for pharmaceutical quality control instrument vendors. |
| Sequencing-as-a-Service Model | Genotypic identification service revenue captures contamination investigation budgets from capital-constrained CROs. |
Study Parameters
Initial hypotheses were tested against primary input from quality control directors, regulatory affairs leads, CRO procurement officers, and instrument validation specialists and refined through secondary cross-checks against FDA 510(k) filings, EMA submission databases, pharmacopeial reference method updates, and SEC 10-K instrument revenue disclosures. Bottom-up instrument shipment tracking and top-down reagent consumption modeling were triangulated against reported vendor financials.
Variance decomposition across product type, end user archetype, technology platform, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from log-linear trend fitting across the projection horizon. Forecast inputs incorporated EMA Annex 1 implementation timelines, FDA Process Analytical Technology adoption curves, and German biologics cluster capital expenditure patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory tightening and stable polymerase supply; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market