
 North America Biocontrol Agents Market | 2026-2036
North America Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biocontrol Agents Market Insights
Modular biocontrol product suites is consolidating buyer choice across the North America Biocontrol Agents Market, with suppliers bundling microbial inoculants, pheromone dispensers, and predator release systems into season-long crop protection programs. Koppert Biological Systems anchors its position through specialized predator and parasitoid production facilities in Ontario and California. BASF SE extends its reach by leveraging microbial strain libraries developed through sustained R&D investment in agricultural biotechnology. Marrone Bio Innovates differentiates via bioherbicide and bioinsecticide platforms targeting herbicide-resistant weed complexes.
Biocontrol agents comprise living organisms or naturally derived compounds that suppress pest populations through predation, parasitism, competition, or antibiosis, with microbial formulations typically containing specified colony-forming units per gram and requiring controlled temperature storage between 4°C and 25°C to maintain viability. These agents serve as core components of integrated pest management systems across conventional and organic production systems. Microbial agents occupy the dominant value share as Bacillus thuringiensis and Trichoderma-based products command established manufacturing scale and distributor familiarity. Biochemical agents represent the fastest-expanding category, driven by plant extract formulations gaining EPA Section 25(b) exempt status and bypassing full registration timelines. Insect pheromones concentrate margin pools in mating disruption applications for tree nuts and stone fruits, where per-acre premiums justify precision deployment costs.
The EPA's biopesticide registration framework and FIFRA compliance requirements shape product development timelines and label claims across the United States, while Health Canada's PMRA establishes parallel standards for Canadian market access. The USDA National Organic Program and state-level restricted material lists in California and Washington determine eligible inputs for certified organic operations. Stakeholders must monitor evolving resistance management mandates from the EPA's Pesticide Resistance Action Committee and state department of agriculture enforcement patterns that will determine which biocontrol modalities secure preferred placement in integrated pest management guidelines.
Market Dynamics
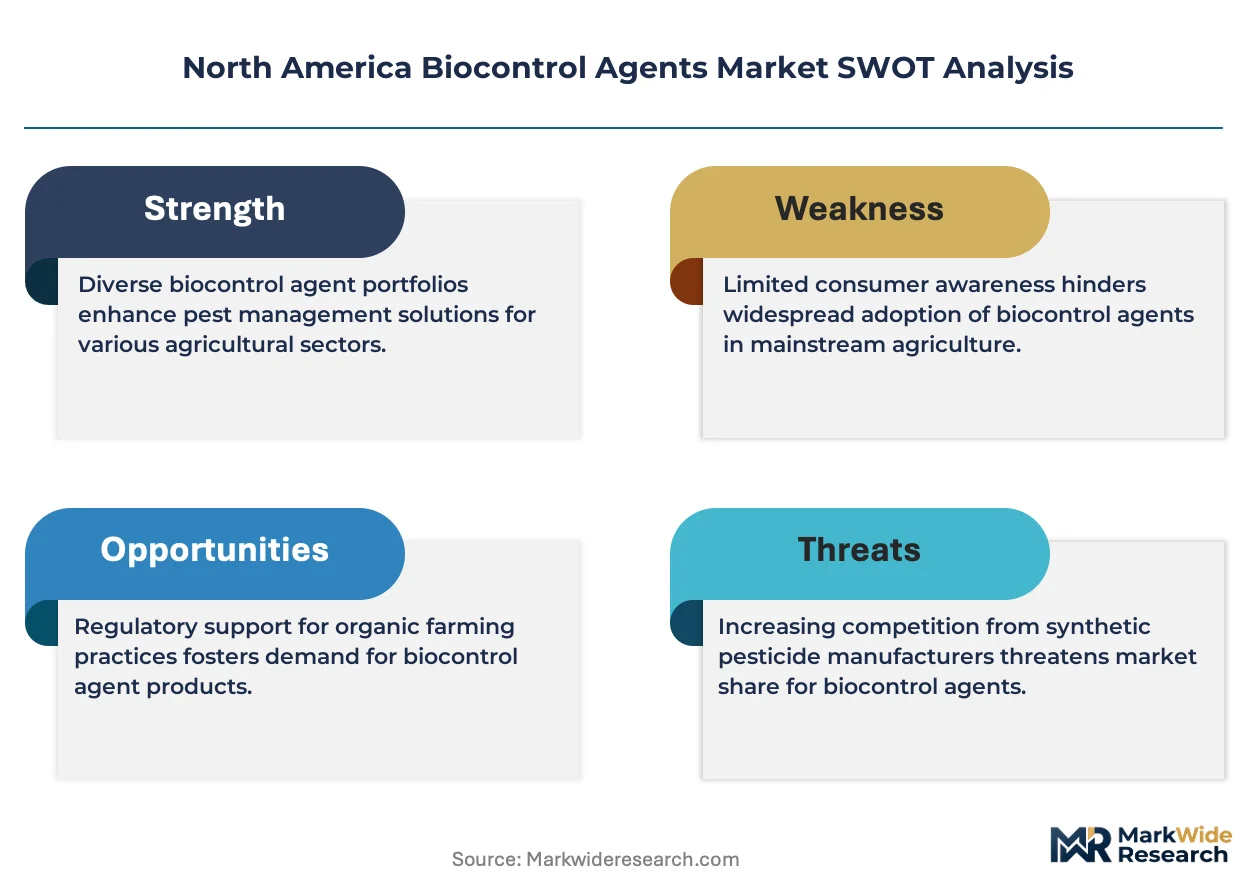
The EPA's streamlined biopesticide registration pathways under FIFRA Section 3 are compressing product development timelines from 36 months to 18 months, enabling faster commercialization of microbial formulations and accelerating competitive entry into specialty crop segments.
Growth Catalysts
- Herbicide Resistance Pressure:Glyphosate-resistant weed complexes in Midwestern row crops are forcing growers to seek alternative suppression methods, expanding addressable acreage for bioherbicide platforms.
- California's Restricted Material Lists:State-level organic certification requirements are mandating biocontrol inputs for certified operations in the Central Valley, creating guaranteed demand pools.
- Microbial Formulation Stability:Advances in encapsulation technologies extending shelf life beyond 24 months are reducing cold-chain dependency and expanding distribution reach into secondary agricultural regions.
Market Restraints
- Input Cost Volatility:Fermentation-grade substrates and specialized growth media for Bacillus and Trichoderma strains face price swings tied to corn and soybean commodity markets.
- Supply Concentration Risk:Predator insect production for augmentative release programs clusters in Ontario and California facilities, creating vulnerability to regional climate events.
- Technical Limitation:Narrow environmental windows for microbial agent efficacy—temperature, humidity, UV exposure—restrict reliable performance to specific growing zones and seasons.
Strategic Opportunities
- Underpenetrated Geography:Pacific Northwest berry operations in Washington and Oregon remain underserved by pheromone mating disruption systems relative to California tree nut acreage.
- Technology Convergence:Integration of drone-based precision application with microbial inoculant delivery is opening foliar spray markets previously inaccessible to ground equipment.
- Regulatory Tailwind:EPA Section 25(b) minimum risk exemptions for plant-derived biochemicals are bypassing full registration costs, lowering capital barriers for novel extract formulations.
Industry Challenges
- Talent Scarcity:Qualified entomologists and microbial ecologists capable of field-validating biocontrol protocols remain concentrated in university extension programs with limited private-sector mobility.
- Capex Intensity:Controlled-environment rearing facilities for parasitoid wasps require specialized HVAC and lighting systems with 7-10 year depreciation horizons.
- Integration Complexity:Synchronizing biocontrol release schedules with synthetic pesticide application windows demands sophisticated farm management software that many mid-scale operations lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biocontrol Agents Market |
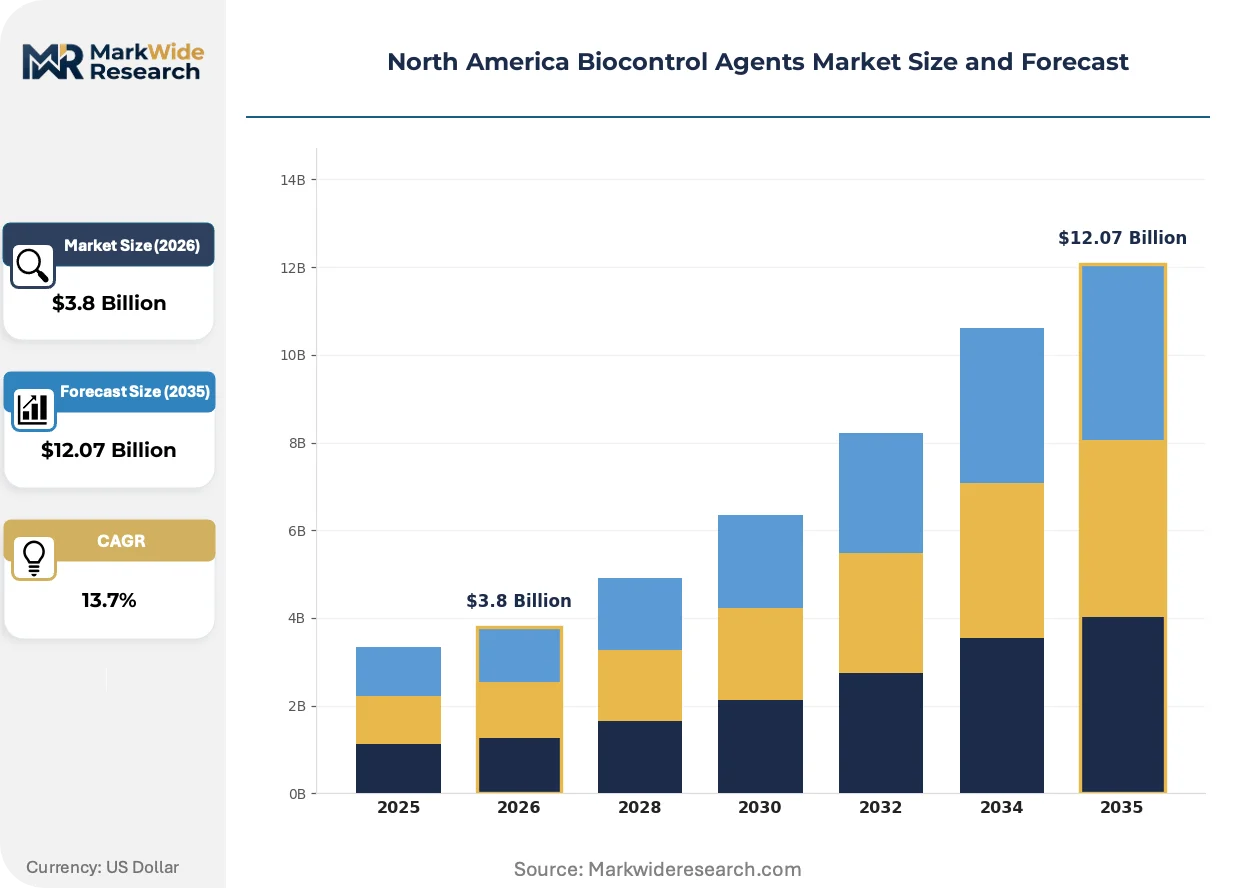
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Agents, Biochemical Agents, Insect Pheromones, Predators Application: Agriculture, Horticulture, Turf, Greenhouse Customer Type: Farmers, Agricultural Cooperatives, Distributors, Government Agencies Distribution Channel: Direct Sales, Retail, E-commerce, Others |
| Companies Covered | Koppert Biological Systems, BASF SE, Biobest Group, Marrone Bio Innovations, Certis Biologicals, Valent BioSciences, BioWorks Inc., Andermatt Biocontrol, Novozymes, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biocontrol Agents Market Trends and Innovations
Formulation chemistry and delivery mechanism advances are compressing the performance gap between biological and synthetic crop protection, reshaping procurement criteria across conventional and organic production systems.
RNA interference technology is integrating into bioinsecticide development pipelines, enabling species-specific pest suppression without off-target effects on beneficial insects. Specialty vegetable growers in Florida and Arizona are piloting foliar-applied dsRNA formulations against lepidopteran pests. The technology is integrating with existing integrated pest management protocols by reducing refuge requirements and resistance selection pressure compared to Bt toxins.
Health Canada's PMRA is harmonizing data requirements with EPA biopesticide standards through the North American Free Trade Agreement technical working group, reducing redundant efficacy studies for cross-border product registrations. Canadian field trial data is gaining reciprocal acceptance for US label amendments. Manitoba and Saskatchewan pulse crop producers are benefiting from accelerated access to Trichoderma seed treatments previously delayed by regulatory divergence.
Direct-to-grower digital platforms are displacing traditional distributor-led technical service models for biocontrol procurement. Large-scale row crop operations in the Corn Belt are subscribing to season-long pest monitoring and automated replenishment programs. This shift concentrates most visibly among 5,000+ acre Midwestern operations seeking to reduce per-acre technical consultation costs while maintaining prescription accuracy.
North America Biocontrol Agents Market Segmentation
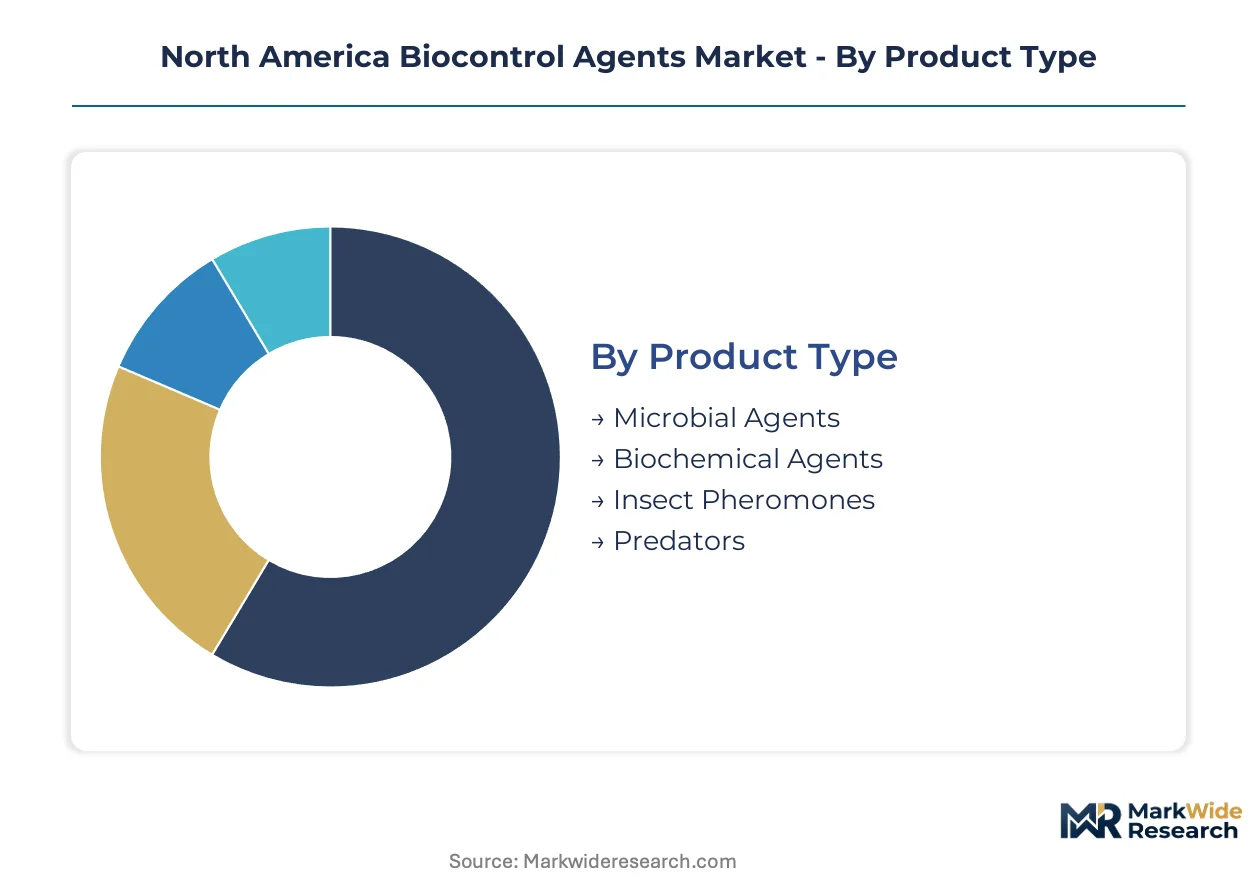
Biocontrol procurement patterns across North America diverge sharply by operational scale and crop system complexity. Segmentation reveals where microbial formulations command premium positioning versus where pheromone systems justify precision investment.
Product Type:
Replacement cycles for biocontrol formulations are compressing as shelf-life improvements and resistance management protocols accelerate grower refresh rates.
- Microbial Agents:Formulations containing specified colony-forming units of Bacillus thuringiensis, Trichoderma, and Pseudomonas strains dominate acreage treated across Midwestern row crops. Demand concentrates in Iowa and Illinois corn-soy rotations where EPA-registered bioinsecticides integrate into Bt refuge management strategies. Cold-chain requirements between 4°C and 25°C limit distribution reach into secondary markets lacking controlled storage infrastructure.
- Biochemical Agents:Plant-derived compounds and naturally occurring substances gaining EPA Section 25(b) exempt status bypass full registration timelines. California Central Valley specialty crop growers deploy these for organic certification compliance on restricted material lists. Faster approval pathways are attracting R&D investment toward novel extract formulations targeting herbicide-resistant weed complexes.
- Insect Pheromones:Synthetic copies of natural insect sex pheromones deployed for mating disruption in tree nuts and stone fruits command per-acre premiums that justify precision application costs.
- Predators:Augmentative release programs for parasitoid wasps and predatory mites require specialized rearing facilities with controlled-environment HVAC systems.
Microbial Agents sits at the top of the volume ranking, with Biochemical Agents climbing the fastest.
Application:
Cost tier differentiation separates input-intensive specialty systems from commodity-scale deployment economics.
- Agriculture:Large-scale row crop operations across the US Corn Belt integrate biocontrol into integrated pest management protocols for corn, soybean, and wheat production. Demand drivers include glyphosate-resistant weed pressure and EPA resistance management mandates. Input cost volatility for fermentation-grade substrates ties program economics to corn and soybean commodity price swings.
- Horticulture:High-value fruit and vegetable production in California, Florida, and Arizona deploys precision biocontrol for export market phytosanitary compliance. Per-acre input budgets accommodate pheromone mating disruption and microbial inoculant combinations that commodity grain operations cannot absorb.
- Turf:Golf course and sports field maintenance programs in suburban corridors favor low-residue biological options for worker re-entry interval flexibility.
- Greenhouse:Controlled-environment agriculture facilities leverage predator insect releases for zero-residue production targeting premium retail channels.
Agriculture captures the dominant value share, while Horticulture delivers the steepest margin expansion trajectory.
Customer Type:
Procurement authority is consolidating among entities with technical validation capabilities and volume leverage.
- Farmers:Individual growers operating 5,000+ acre Midwestern operations subscribe to direct-to-grower digital platforms for automated replenishment programs. Technical service demands are shifting from distributor-led consultation to algorithmic prescription tools.
- Agricultural Cooperatives:Member-owned buying organizations aggregate demand across multiple operations to secure volume pricing and shared technical support resources.
- Distributors:Traditional channel intermediaries face displacement as manufacturers build direct relationships with large-scale operators.
- Government Agencies:USDA and state department of agriculture programs subsidize biocontrol adoption for integrated pest management demonstration projects and organic transition support.
Farmers represent the largest addressable base, with Agricultural Cooperatives gaining procurement influence fastest.
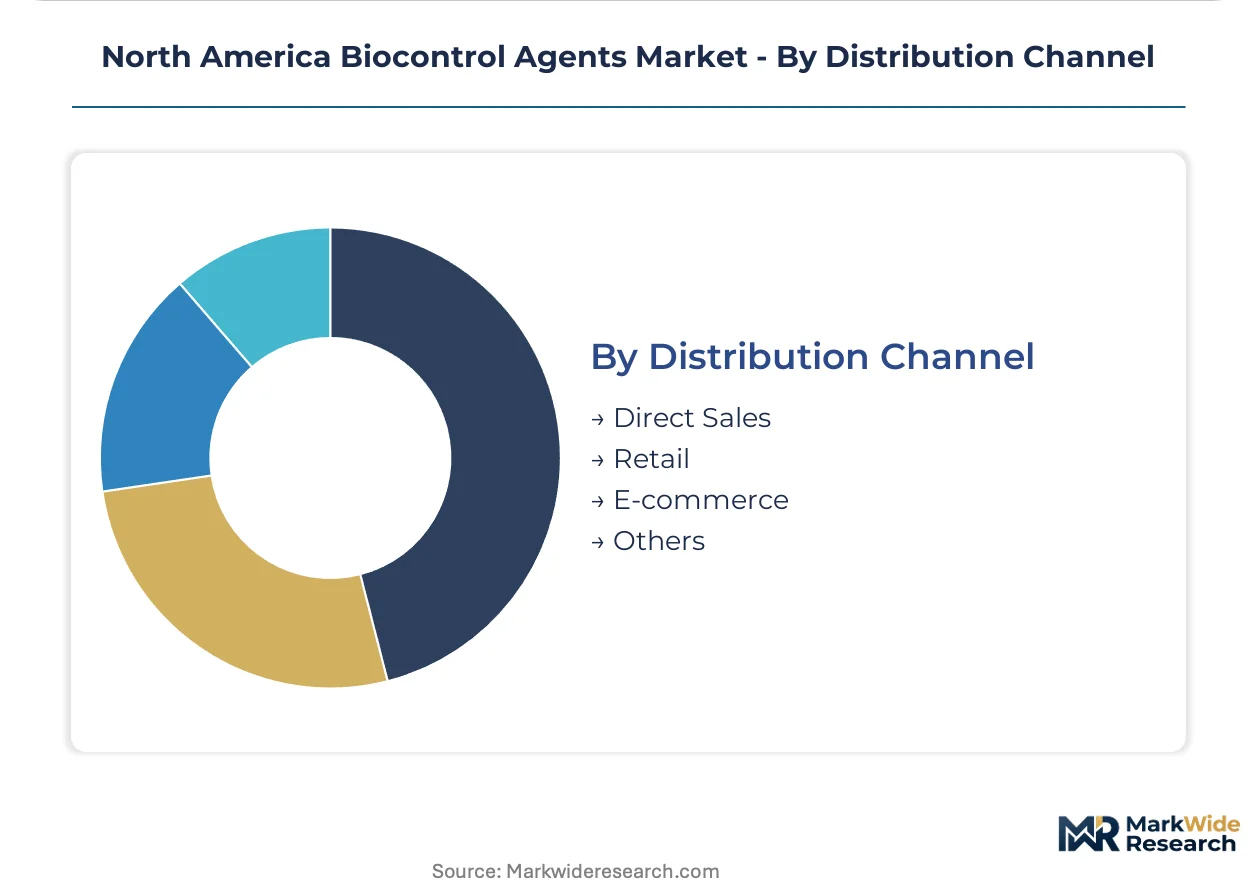
Distribution Channel:
Channel economics favor direct relationships where technical complexity requires specialized application guidance.
- Direct Sales:Manufacturers maintain technical service teams for large-scale row crop and specialty vegetable operations requiring protocol customization. Season-long pest monitoring subscriptions concentrate in this channel among Corn Belt operators seeking reduced per-acre consultation costs.
- Retail:Farm supply stores and agricultural input retailers serve mid-scale operations with standardized microbial formulations and predator release kits.
- E-commerce:Digital platforms are capturing share in pheromone dispenser and microbial inoculant categories where growers self-diagnose pest pressure and reorder autonomously.
- Others:Consultant-mediated procurement and integrated pest management service providers bundle biocontrol into comprehensive crop protection programs.
Direct Sales maintains volume leadership, with E-commerce expanding most quickly in standardized product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biocontrol agent commercialization first achieved industrial scale in the United States during the 1980s as EPA biopesticide registration pathways formalized under FIFRA amendments. California's Central Valley and Florida's citrus belt served as the original proving grounds for microbial formulation stability and augmentative predator release protocols.
United States
Midwestern corn-soy rotations in Iowa and Illinois drive microbial agent volume as glyphosate-resistant weed pressure forces alternative suppression methods. EPA's streamlined Section 3 registration compresses development timelines from 36 months to 18 months. California's Central Valley specialty crop growers anchor pheromone mating disruption demand for tree nuts and stone fruits.
Canada
Manitoba and Saskatchewan pulse crop producers accelerate Trichoderma seed treatment adoption as Health Canada's PMRA harmonizes data requirements with EPA standards. The North American Free Trade Agreement technical working group eliminates redundant efficacy studies. Ontario hosts specialized predator insect production facilities serving cross-border augmentative release programs.
Mexico
Export-oriented vegetable operations in Sinaloa and Baja California deploy biocontrol for phytosanitary compliance with US and Canadian import standards. Mexico's national agricultural regulator registers microbial formulations under parallel review protocols with EPA determinations. Guanajuato's berry expansion creates emerging demand for predator mite release systems.
North America Biocontrol Agents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and technical service intensity. The vendor base stratifies between multinational agrochemical conglomerates with microbial strain libraries and specialized biologicals producers with captive rearing infrastructure. Three archetypes dominate: integrated agribusiness divisions leveraging R&D scale, dedicated biocontrol specialists with predator production facilities, and platform biotech firms commercializing novel extract formulations. Competitive moves concentrate on strategic partnerships for distribution reach and technology licensing for RNA interference pipeline access.
Within the dedicated biocontrol specialist tier, Koppert Biological Systems and Biobest Group exemplify facility-dependent production models with controlled-environment rearing capabilities. BASF SE represents integrated agribusiness participation through microbial platform leverage. Marrone Bio Innovations occupies a position among platform-focused developers targeting herbicide-resistant weed complexes with novel biochemical agents.
| Leading Market Players |
|---|
| Koppert Biological Systems |
| BASF SE |
| Biobest Group |
| Marrone Bio Innovations |
| Certis Biologicals |
| Valent BioSciences |
| BioWorks Inc. |
| Andermatt Biocontrol |
| Novozymes |
| Others |
Pricing and Supply Chain Analysis
Corn and soybean commodity price indices cascade directly into fermentation-grade substrate costs for Bacillus and Trichoderma production, compressing margin pools at the standard formulation tier while premium cold-chain-dependent microbial agents retain pricing power through controlled-environment guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated shelf-life guarantees from basic CFU-count formulations and generic predator release kits. Price differentiation hinges on EPA registration status and cold-chain certification tier, with Section 25(b) exempt biochemicals commanding intermediate positioning. Cost compression in the economy tier is intensifying because input cost volatility for corn-derived growth media feeds through to commodity microbial formulations. Mid-scale specialty crop growers in the Pacific Northwest exhibit highest price sensitivity, while California organic-certified operations absorb premium tier costs for restricted material list compliance.
Supply Chain Analysis
Reverse-logistics networks for temperature-compromised microbial shipments return non-viable product to Ontario and California rearing facilities for strain recovery and reformulation. Geographic supply concentration clusters in the United States, Canada, and Mexico, with Ontario hosting specialized parasitoid wasp production and California anchoring predator mite facilities. Raw material dependencies draw from fermentation-grade substrates, specialized HVAC equipment for controlled-environment rearing, and pheromone synthesis precursors. Single-source vulnerability concentrates in Ontario's predator insect production, where regional climate events could disrupt cross-border augmentative release programs. Distribution runs through direct technical service teams for large-scale operators, supplemented by e-commerce platforms for standardized pheromone and microbial reordering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Biocontrol Agents Market functions as a geographic-arbitrage play between EPA's 18-month Section 3 registration timeline and Health Canada's harmonized PMRA standards, where regulatory cost differentials create cross-border product launch sequencing advantages.
For Market Incumbents: Deploy strain library leverage as the defensive anchor. BASF SE and Novozymes should deepen captive microbial platform control through backward integration into fermentation substrate production, insulating margin pools from corn commodity swings. Incumbents must secure EPA Section 25(b) exempt status for novel plant extract pipelines before emerging biotech firms capture biochemical agent share, while expanding Ontario and California rearing facility redundancy to neutralize climate-driven supply concentration risk. For New Entrants and Emerging Players: Enter via Pacific Northwest berry operations in Washington and Oregon, where pheromone mating disruption penetration lags California tree nut acreage by substantial margins. Drone-integrated microbial delivery systems for foliar spray markets represent the most penetrable application wedge, as ground equipment inaccessibility has historically excluded these acres from biocontrol adoption. A direct-to-grower digital platform with algorithmic prescription tools bypasses distributor channel control concentrated among Midwestern cooperatives. For Investors and Strategic Acquirers: Asymmetric upside sits with platform biotech firms commercializing RNA interference bioinsecticide pipelines, where species-specific suppression technology commands premium acquisition multiples relative to commodity microbial formulations. Long-term viability over the extended horizon rests on regulatory tailwinds for novel biochemical agents and convergence with precision agriculture hardware. The signal to watch is EPA resistance management mandate enforcement patterns, which will determine whether biocontrol modalities secure preferred placement in integrated pest management guidelines or face synthetic pesticide reversion pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Controlled-environment storage networks unlock distribution into secondary agricultural regions lacking 4°C-25°C facilities. |
| RNA Interference Pipeline Licensing | dsRNA formulation access enables species-specific lepidopteran suppression without Bt toxin refuge requirements. |
| Direct-to-Grower Platform Development | Algorithmic prescription tools displace distributor-led technical service models among 5,000+ acre Corn Belt operations. |
| Cross-Border Regulatory Harmonization | PMRA-EPA data reciprocity eliminates redundant efficacy studies for Canadian pulse crop market entry. |
| Encapsulation Technology Scale-Up | Shelf-life extension beyond 24 months reduces cold-chain dependency and expands secondary market reach. |
Research Methodology
Multiple input streams — biocontrol manufacturer technical directors, EPA regulatory affairs specialists, California Department of Agriculture compliance officers, and Midwestern agricultural cooperative procurement leads — were reconciled against secondary validation from EPA biopesticide registration databases, Health Canada PMRA submission records, USDA National Organic Program restricted material lists, and state-level department of agriculture enforcement patterns. Bottom-up acreage estimates for microbial agent deployment across Iowa and Illinois corn-soy rotations were triangulated with top-down value projections for pheromone mating disruption in California tree nut systems.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions for microbial agents, biochemical agents, insect pheromones, and predator release systems, with additional granularity by application intensity across agriculture, horticulture, turf, and greenhouse end-uses. CAGRs were derived from historical adoption curves for Bt-based bioinsecticides and projected penetration rates for RNA interference formulations. Forecast inputs incorporated EPA registration timeline compression effects, Health Canada-EPA harmonization benefits for cross-border products, and cold-chain infrastructure expansion trajectories into secondary markets.
Inputs from EPA registration databases and state-level restricted material list updates were available through the study window; gaps in real-time grower adoption data for drone-integrated microbial delivery introduce uncertainty bands around precision application segment projections. Forecasts reflect assumptions regarding sustained glyphosate-resistant weed pressure and organic certification growth trajectories, with revision risk tied to synthetic pesticide resistance management mandate enforcement intensity and fermentation substrate commodity price volatility. Practitioners should monitor EPA Pesticide Resistance Action Committee guideline updates and Ontario climate event frequency for early signals of supply chain disruption or regulatory preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Seed Biostimulants Market