
 Global Microbial Fermentation Technology Market | 2026-2036
Global Microbial Fermentation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbial Fermentation Technology Market Foresight
China is reconfiguring global microbial fermentation capacity through state-backed biomanufacturing parks in Tianjin and Suzhou. Lonza Group AG leverages its Singapore and Guangzhou facilities to anchor microbial CDMO services across Asia-Pacific. Novozymes A/S dominates industrial enzyme fermentation with in-house strain development platforms that sustain cost leadership in biofuel applications.
Microbial fermentation technology deploys controlled bioreactor environments to cultivate bacteria, yeast, or filamentous fungi for metabolite or protein production, typically operating at pH 6.5-7.5 and dissolved oxygen above 20% saturation for aerobic processes. Fed-batch systems generate the highest revenue share in pharmaceutical applications because titers for recombinant proteins exceed 10 g/L, yet continuous fermentation is displacing legacy batch methods in biofuel operations where steady-state productivity cuts downtime. Biotechnology firms represent the most concentrated end-user segment, absorbing contract capacity for plasmid DNA and therapeutic enzymes.
FDA's Quality by Design framework and EMA's Good Manufacturing Practice Annex 1 revisions mandate closed-system fermentation and real-time bioburden monitoring for sterile biologics. China's NMPA now requires local clinical trial data for imported microbial-derived APIs, reshaping filing strategies for multinational manufacturers. Stakeholders must decide whether to build captive fermentation capacity or lock in long-term CDMO contracts before bioreactor lead times extend further.
Market Dynamics
Fed-batch fermentation systems face displacement pressure from continuous bioreactor platforms as biofuel producers prioritize steady-state productivity over legacy batch titers. Pharmaceutical manufacturers simultaneously confront FDA and EMA purity mandates that demand closed-system upgrades, forcing capital allocation decisions between captive capacity and CDMO partnerships.
Growth Catalysts
- EMA Annex 1 Revisions:Sterile manufacturing mandates for biologics accelerate single-use bioreactor adoption across European CDMO networks, compressing validation timelines for microbial-derived APIs.
- China Biomanufacturing Parks:State-backed clusters in Tianjin and Suzhou concentrate strain engineering talent and downstream processing infrastructure, drawing contract fermentation volume from multinational sponsors.
- Cell-Free Protein Synthesis:Emerging platform technologies reduce dependency on living cultures for select therapeutic proteins, opening capacity reallocation opportunities for traditional fermentation assets.
Market Restraints
- Stainless Steel Bioreactor Lead Times:Equipment delivery schedules extending beyond eighteen months delay capacity expansion for mid-scale pharmaceutical manufacturers.
- Chinese NMPA Localization Requirements:Mandatory domestic clinical trial data for imported microbial-derived APIs fragment global filing strategies and duplicate development costs.
- Plasmid DNA Substitution:Synthetic biology platforms and cell-free expression systems capture niche therapeutic protein applications previously served by bacterial fermentation.
Strategic Opportunities
- Brazil ANVISA Pathway Acceleration:Streamlined biosimilar approval frameworks for microbial-derived products reduce time-to-market for fermentation-based generics in Latin America.
- Continuous Manufacturing Convergence:Integration of perfusion bioreactors with real-time analytical technologies enables 24/7 operational models that batch systems cannot replicate.
- Carbon-Negative Fermentation:EU Green Deal industrial decarbonization incentives position gas-fermentation platforms utilizing CO2 feedstocks for preferential project financing.
Industry Challenges
- Process Analytical Technology Integration:Legacy batch record systems require costly retrofitting to accommodate FDA Quality by Design real-time monitoring mandates.
- Strain Engineering Talent Scarcity:Competition between industrial enzyme and pharmaceutical sectors for metabolic engineering specialists compresses compensation benchmarks and extends hiring cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbial Fermentation Technology Market |
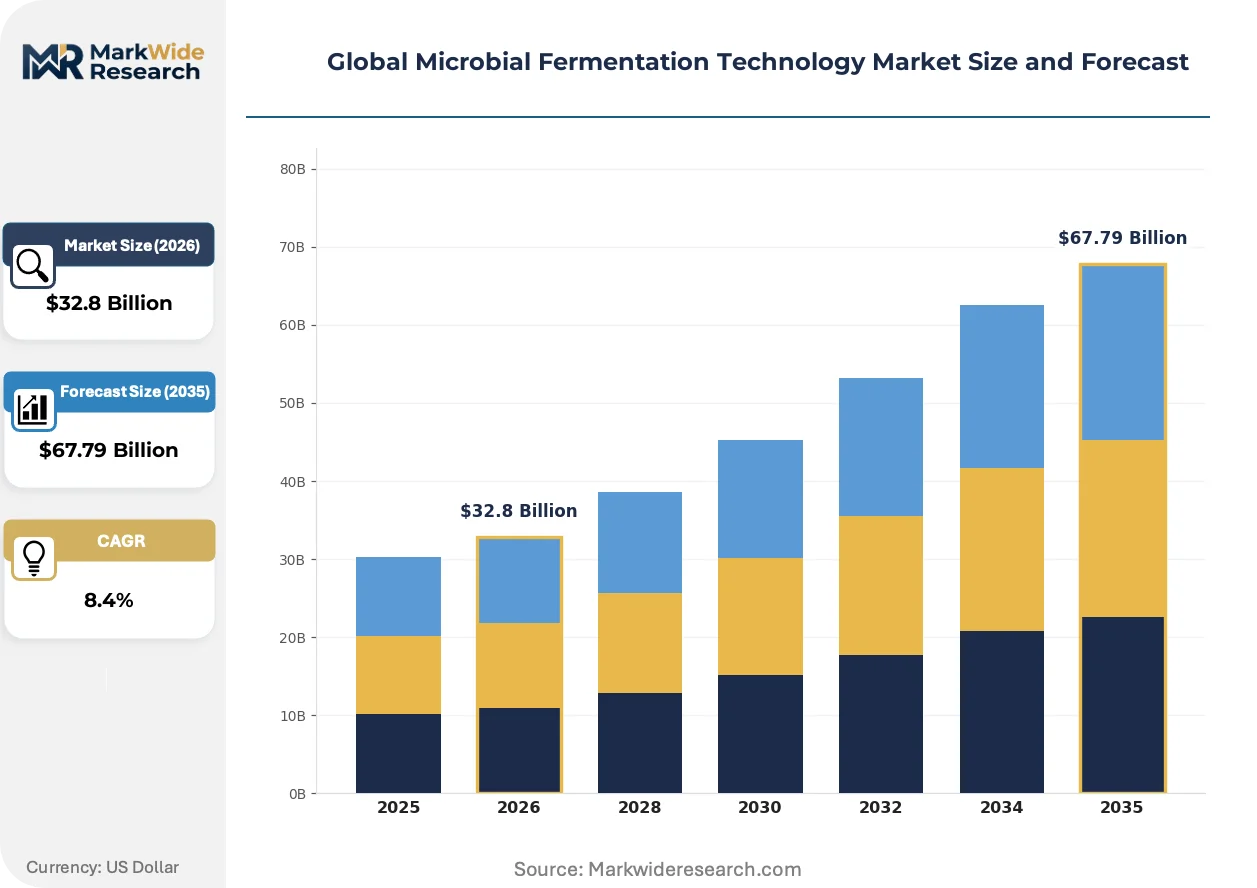
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fermentation Type: Batch, Continuous, Fed-Batch, Solid-State, Submerged Technology: Immobilized Cell, Ultrasound-Assisted, Aerobic, Anaerobic, Hybrid Application: Pharmaceuticals, Biofuels, Food & Beverages, Waste Treatment, Biopolymers End User: Biotechnology Firms, Agrochemical Producers, Chemical Manufacturers, Research Institutes, Food Processing Units |
| Companies Covered | Lonza Group AG, Novozymes A/S, Koninklijke DSM NV, F. Hoffmann-La Roche AG, Danone UK, Biocon Ltd., AbbVie Inc., BioVectra Inc., FUJIFILM Diosynth Biotechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbial Fermentation Technology Market Shifts & Advancements
Bioreactor automation and synthetic biology toolkits are compressing strain development cycles from years to months, reshaping competitive differentiation around speed rather than scale alone. This acceleration favors technology-integrated CDMOs over equipment-reliant legacy operators.
Single-use bioreactor systems is hybridizing with traditional stainless steel infrastructure as pharmaceutical manufacturers deploy hybrid facilities that match disposable upstream processing with durable downstream purification trains. Mid-scale biotechnology firms adopt this configuration fastest, balancing contamination risk reduction against capital efficiency. The hybrid architecture enables rapid product changeovers that dedicated stainless steel lines cannot match, compressing contract manufacturing margins for inflexible assets.
FDA's Quality by Design framework now mandates real-time release testing protocols for sterile biologics, forcing fermentation operators to embed process analytical technologies directly into bioreactor control systems. This regulatory compression elevates validation costs for smaller CDMOs while creating compliance moats for technology-leaders. European sterile API manufacturers face parallel EMA Annex 1 revisions that synchronize transatlantic standards, simplifying multi-territory filing strategies for integrated global sponsors.
Biopharmaceutical procurement teams now unbundle fermentation capacity contracts from downstream purification services, reversing historical integrated sourcing patterns. This disintermediation pressures full-service CDMOs to demonstrate standalone bioreactor pricing competitiveness against specialized upstream-only providers. The trend concentrates in North American biotechnology clusters where venture-backed sponsors prioritize capital-efficient milestone-based outsourcing over long-term integrated partnerships.
Global Microbial Fermentation Technology Market Segmentation
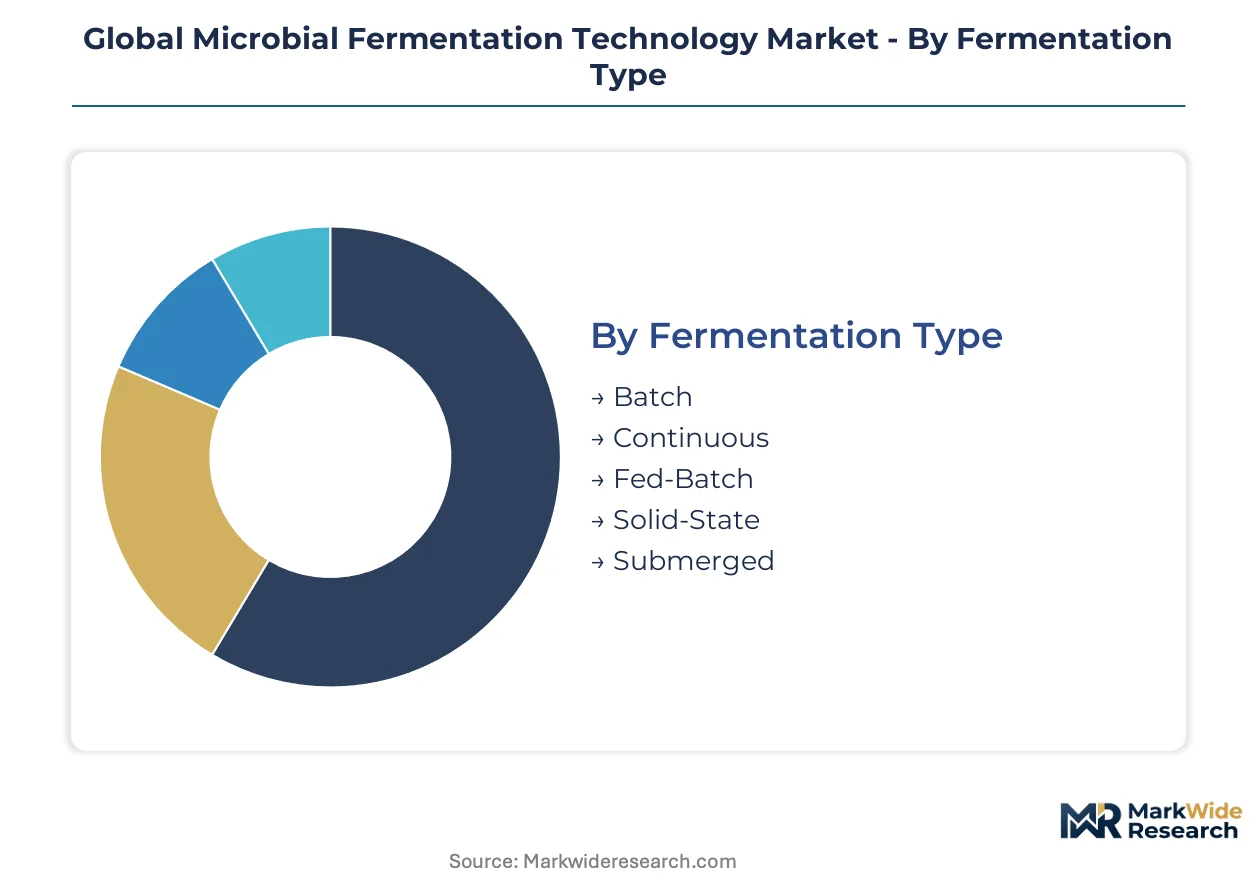
Microbial fermentation technology segments diverge sharply by process economics and capital intensity. Cycle times for pharmaceutical fed-batch systems stretch across weeks, while continuous biofuel platforms compress turnover to hours, reshaping equipment selection and facility design across end-use verticals.
Fermentation Type:
Cycle times separate these modes dramatically: fed-batch pharmaceutical runs extend 10-14 days for protein maturation, whereas continuous ethanol systems achieve steady-state within hours of startup.
- Fed-Batch:Intermittent nutrient feeding sustains high cell density without overflow metabolism, enabling recombinant protein titers above 10 g/L. Demand concentrates in US and European CDMO networks serving monoclonal antibody sponsors facing FDA Quality by Design mandates for sterile biologics.
- Continuous:Perfusion bioreactors maintain steady-state operation with constant media exchange and harvest, maximizing volumetric productivity for commodity products. Biofuel producers in Brazil and the US deploy these systems to minimize downtime between batch turnovers.
- Batch:Closed-cycle operation with defined start and end points suits multi-product facilities requiring frequent changeovers.
- Solid-State:Moist solid substrates replace liquid media for fungal metabolite production, common in Asian enzyme manufacturing.
- Submerged:Liquid-phase cultivation dominates industrial-scale antibiotic and organic acid production.
Fed-batch anchors the volume base while continuous gains share at the steepest rate.
Technology:
Cost tiers stratify sharply: immobilized cell systems command premium pricing for specialty chemical applications, whereas aerobic platforms scale most economically for bulk pharmaceutical production.
- Immobilized Cell:Cells entrapped in porous matrices or surface-attached to carriers enable extended operational lifecycles beyond free-suspension limits. Citric acid and amino acid manufacturers in China leverage these systems for reduced downstream separation costs.
- Aerobic:Forced oxygen transfer through sparging or mechanical agitation supports high-density bacterial and yeast cultures. Recombinant protein producers across Germany, Switzerland, and Singapore standardize on aerobic stirred-tank configurations for therapeutic enzyme output.
- Ultrasound-Assisted:Acoustic cavitation enhances mass transfer rates in viscous fermentation broths.
- Anaerobic:Oxygen exclusion enables specific metabolic pathways for ethanol, butanol, and hydrogen production.
- Hybrid:Combined aerobic-anaerobic phases optimize complex metabolite synthesis in polyketide manufacturing.
Aerobic systems dominate installed capacity while immobilized cell configurations expand most quickly in high-value chemical segments.
Application:
Application margins range from single-digit percentages in bulk biofuels to high double-digits in orphan-disease biologics, dictating technology investment thresholds.
- Pharmaceuticals:Sterile biologics production demands closed-system bioreactors with real-time bioburden monitoring and validated cleaning protocols. CDMOs in China, India, and Ireland compete for contract manufacturing of plasmid DNA and therapeutic enzymes under divergent FDA, EMA, and NMPA filing requirements.
- Biofuels:Cellulosic ethanol and advanced biofuel platforms prioritize volumetric productivity over titer purity, accepting higher contamination risk for cost minimization. US and Brazilian producers drive equipment demand for continuous fermentation systems integrated with distillation trains.
- Food & Beverages:Cultured proteins, enzymes, and flavor compounds leverage GRAS strain lineages.
- Waste Treatment:Anaerobic digestion of organic effluents generates biogas for energy recovery.
- Biopolymers:Polyhydroxyalkanoates and polylactic acid precursors require precise carbon flux control.
Pharmaceuticals anchors the value base while biofuels gains share at the steepest rate in unit volume terms.
End User:
Customer sophistication spans venture-backed biotechnology startups outsourcing entirely to integrated agrochemical giants with captive fermentation campuses.
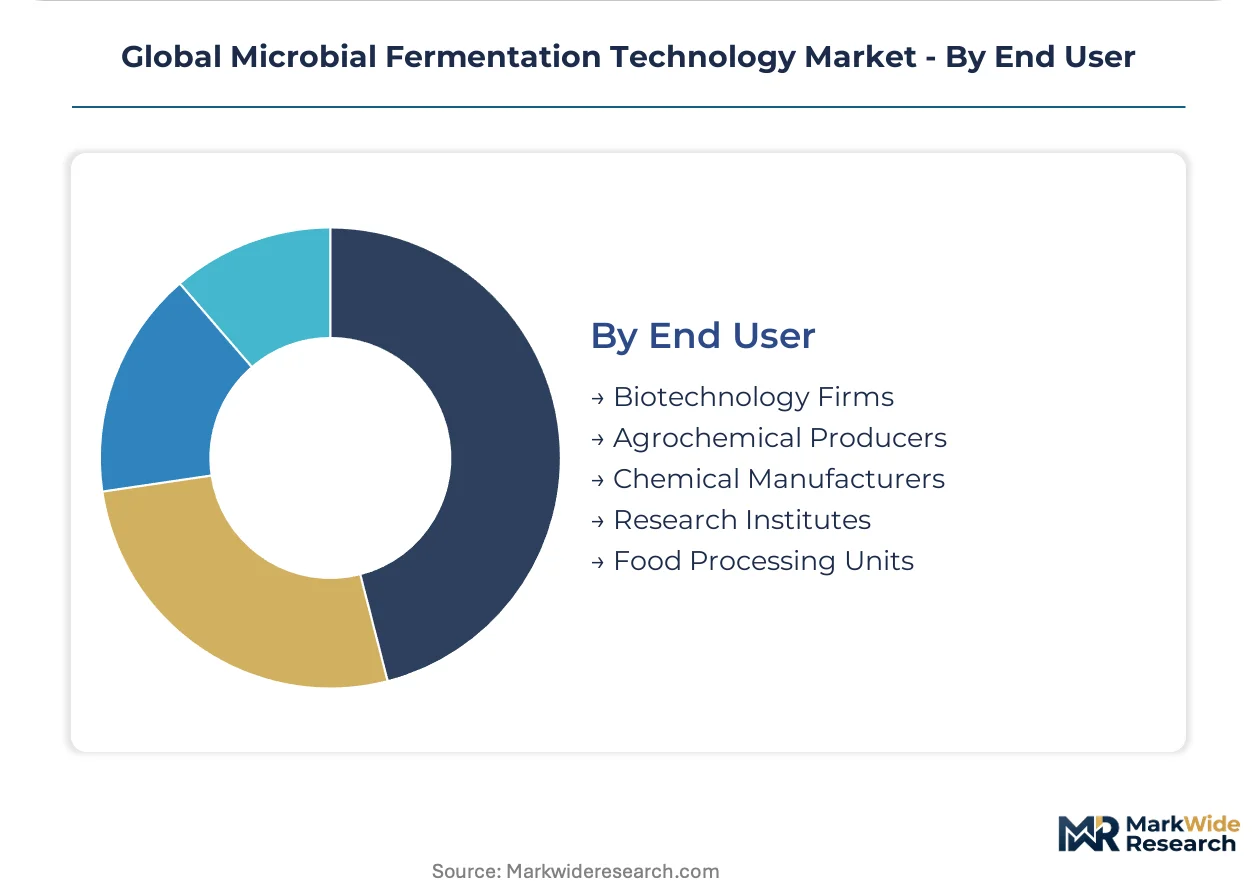
- Biotechnology Firms:Venture-funded drug developers concentrate contract demand for plasmid DNA, viral vectors, and therapeutic proteins, prioritizing speed-to-IND over unit cost. These sponsors unbundle fermentation from downstream purification, sourcing upstream capacity from specialized CDMOs in Boston, San Francisco, and Basel corridors.
- Agrochemical Producers:Biopesticide and biofertilizer manufacturers deploy fermentation for Bacillus thuringiensis and Trichoderma biomass production. Brazilian and Indian agricultural markets drive demand for cost-optimized batch systems with regional strain adaptation.
- Chemical Manufacturers:Industrial enzyme and organic acid producers balance captive capacity with toll manufacturing arrangements.
- Research Institutes:Academic and government laboratories pilot novel strains at bench and pilot scale.
- Food Processing Units:Enzyme, preservative, and cultured ingredient producers integrate fermentation into existing hygienic processing infrastructure.
Biotechnology firms anchor the innovation premium while agrochemical producers gains share at the steepest rate in emerging agricultural markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA purity mandates for sterile biologics anchor the United States as the regulatory benchmark, while China's NMPA localization requirements and state-backed biomanufacturing parks are reconfiguring capacity distribution. Germany, Switzerland, and India complete the geographic matrix through divergent specialization patterns.
United States
FDA's Quality by Design framework and Annex 1 alignment for sterile manufacturing drive single-use bioreactor upgrades across Boston and San Francisco biotechnology clusters. CDMOs in these corridors absorb venture-funded demand for plasmid DNA and therapeutic enzyme production. The Southeast is attracting greenfield fermentation facilities seeking lower operating costs and proximity to agricultural feedstock networks.
China
NMPA requirements for domestic clinical trial data on imported microbial-derived APIs are fragmenting global filing strategies. State-backed biomanufacturing parks in Tianjin and Suzhou concentrate strain engineering talent and downstream processing infrastructure. Domestic CDMOs in these clusters are building mega-facilities to capture contract volume from multinational sponsors previously served by Western capacity.
Germany
EMA Annex 1 revisions on sterile manufacturing accelerate validation timelines for microbial-derived APIs across European CDMO networks. Industrial enzyme producers in Bavaria and North Rhine-Westphalia leverage aerobic stirred-tank configurations for therapeutic enzyme output. The country's chemical manufacturing heritage supports hybrid facilities combining disposable upstream processing with durable downstream purification trains.
Switzerland
Swissmedic alignment with FDA and EMA standards positions the country as a multi-territory filing hub for integrated global sponsors. Basel's biotechnology corridor hosts concentrated contract manufacturing demand for monoclonal antibodies and recombinant proteins. The regulatory convergence simplifies validation protocols for sponsors seeking simultaneous US and European market entry.
India
CDSCO frameworks for biosimilar approval and cost-optimized batch systems attract fermentation-based generic production. Hyderabad and Bengaluru biotechnology clusters specialize in plasmid DNA and therapeutic enzyme contract manufacturing. Domestic players balance captive capacity with toll manufacturing arrangements for multinational agricultural and pharmaceutical sponsors.
Global Microbial Fermentation Technology Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized biotechnology CDMOs split the market through divergent capital allocation strategies. The structure tilts toward consolidation at the top tier, with mid-scale operators facing margin compression from hybrid facility investments. Three archetypes dominate: technology-integrated CDMOs with synthetic biology platforms, stainless steel legacy operators with validated sterile capacity, and industrial enzyme specialists with in-house strain development. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as bioreactor lead times extend beyond eighteen months.
Within the technology-integrated tier, Lonza Group AG exemplifies the CDMO archetype leveraging Singapore and Guangzhou facilities to anchor microbial services across Asia-Pacific. Novozymes A/S occupies a position representing industrial enzyme specialists with sustained cost leadership in biofuel applications. Koninklijke DSM NV sits within the diversified nutrition and bioscience segment, reflecting portfolio breadth across fermentation-derived ingredients.
| Leading Market Players |
|---|
| Lonza Group AG |
| Novozymes A/S |
| Koninklijke DSM NV |
| F. Hoffmann-La Roche AG |
| Danone UK |
| Biocon Ltd. |
| AbbVie Inc. |
| BioVectra Inc. |
| FUJIFILM Diosynth Biotechnologies |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries bioreactor equipment and sterile media components whose freight cost volatility directly shapes pricing power for CDMOs in China and downstream price differentiation for European pharmaceutical sponsors sourcing microbial-derived APIs.
Pricing Analysis
Price spreads between Chinese domestic CDMOs and Western sterile manufacturers exceed 40% for equivalent fed-batch capacity. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated single-use systems from stainless steel batch configurations and non-GMP toll manufacturing. Cost compression in the economy tier is intensifying because Brazilian and Indian agrochemical producers are expanding captive fermentation campuses. Biotechnology firms in Boston and Basel corridors show least price sensitivity for validated sterile capacity, while generic API sponsors in Hyderabad and Sao Paulo corridors exhibit highest sensitivity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate equipment procurement contracts as stainless steel bioreactor manufacturers in Germany and Switzerland absorb working capital pressure to secure backlog commitments. Fermentation capacity expansion draws from Chinese biomanufacturing parks, Indian biosimilar clusters, and Singaporean pharmaceutical hubs for strain engineering talent and downstream purification infrastructure. Single-source vulnerability concentrates in German agitation motor suppliers and Japanese pH sensor manufacturers. Distribution runs through integrated CDMO networks that bundle upstream bioreactor access with downstream purification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of metabolic engineering specialists with both strain development and GMP manufacturing experience is compressing hiring cycles and elevating compensation benchmarks beyond mid-scale CDMO affordability.
For Market Incumbents: Harden sterile capacity moats through accelerated FDA Quality by Design certification investments before EMA Annex 1 revisions take full effect. Secure long-term offtake agreements with Boston and San Francisco biotechnology clusters to lock in utilization rates against emerging Chinese CDMO competition. Vertical integration into proprietary strain development platforms protects margin position against synthetic biology substitution threats. For New Entrants and Emerging Players: Build out carbon-negative fermentation capabilities utilizing CO2 feedstocks to capture EU Green Deal industrial decarbonization incentives before incumbent chemical manufacturers reposition. White-space opportunity concentrates in Brazilian ANVISA pathway acceleration for biosimilar generics and Southeast Asian toll manufacturing for agricultural enzyme applications. Go-to-market leverage rests on rapid strain development cycles enabled by automated synthetic biology toolkits rather than scale-heavy capital deployment. For Investors and Strategic Acquirers: Technology-integrated CDMOs with embedded process analytical technology platforms and real-time bioburden monitoring capabilities represent the most defensible acquisition archetype across the analysis window. Long-term viability hinges on regulatory compliance automation rather than equipment scale alone. Signal to watch is bioreactor lead time extension beyond eighteen months, indicating supply-constrained pricing power inflection for validated sterile capacity owners.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Bioreactor Validation | FDA Quality by Design compliance accelerates sterile API approval timelines for integrated sponsors. |
| Continuous Manufacturing Convergence | Perfusion bioreactor integration with real-time analytics enables 24/7 operational models unmatched by batch systems. |
| Strain Engineering Platform Acquisition | In-house metabolic engineering capabilities reduce dependency on external academic partnerships for novel product pipelines. |
| Carbon-Negative Fermentation Deployment | EU Green Deal financing preferences position CO2-feedstock platforms for preferential project capital access. |
| Hybrid Facility Architecture | Disposable upstream processing combined with durable downstream trains balances contamination risk against capital efficiency. |
Research Methodology
A spread of perspectives from bioprocess engineering directors, regulatory affairs leads at CDMOs, biotechnology firm procurement officers, and strain development scientists converged on the working assumptions underlying capacity expansion timelines and technology adoption curves. Primary interview insights combined with secondary validation from FDA 483 inspection observations, EMA GMP inspection databases, NMPA drug approval records, and CDER guidance documents. Bottom-up facility capacity tallies and top-down biopharmaceutical outsourcing spend estimates underwent triangulation to anchor volume assumptions.
Demand-supply-balance framing modeled fermentation capacity utilization against biologics pipeline expansion across the projection horizon. Segmentation dimensions included fermentation mode, technology tier, application vertical, and end-user sophistication level. CAGRs derived from facility investment announcements, equipment order backlogs, and sponsor outsourcing contract durations. Industry-specific forecast inputs captured bioreactor lead time trends and regulatory validation timeline compression effects.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by state-backed Chinese CDMOs or rapid cell-free protein synthesis platform maturation would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Cell Banking Market