
 South Africa Passenger Vehicles Lubricants Market | 2026-2036
South Africa Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Passenger Vehicles Lubricants Market Analytics
Fleet operators and ride-hailing platforms is collapsing into the dominant buyer archetype as private vehicle ownership stagnates in South Africa's urban centers. ExxonMobil Corporation leverages its synthetic lubricant portfolio to capture high-utilization fleet contracts. Astron Energy anchors its position through an extensive retail and service station network across the country's major transport corridors. Sasol differentiates with domestically produced base oils that reduce import dependency for local blenders.
South Africa passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and protect powertrain components under operating temperatures ranging from sub-zero Highveld winters to sustained highway thermal loads. Their primary commercial purpose is to extend engine and transmission service intervals while meeting OEM warranty requirements in a market where average vehicle age exceeds twelve years. Engine oil occupies the largest value pool given high per-vehicle consumption volumes and frequent drain intervals on aging sedan and hatchback parc vehicles. Synthetic and semi-synthetic grades represent the fastest-expanding performance tier as NRCS-aligned SABS specifications and OEM service mandates push consumers above mineral basestocks. Distribution through service stations and authorized workshops captures the majority of volume, though online platforms are gaining traction among cost-sensitive DIY maintainers in metropolitan areas.
The National Regulator for Compulsory Specifications enforces SABS 1191 and related standards that mandate minimum performance benchmarks for engine oils sold in South Africa, directly influencing blender formulation investments and import certification costs. South Africa's Department of Transport coordinates with the NRCS to align lubricant specifications with emissions control requirements under the National Environmental Management Act, tightening allowable phosphorus and sulfur content in newer grades. Stakeholders must monitor whether pending carbon border adjustments in key trading partner jurisdictions will reshape base oil sourcing economics for domestic blenders.
Market Dynamics
Fleet operator consolidation in Gauteng and Western Cape is compressing lubricant procurement into volume-based contracts, displacing fragmented retail purchasing as the primary demand channel for passenger vehicle servicing.
Growth Catalysts
- Extended drain interval technology:Synthetic and semi-synthetic formulations certified to SABS 1191 specifications enable fleet operators to stretch service windows, reducing total cost of ownership for high-utilization vehicles operating on Johannesburg-Pretoria corridors.
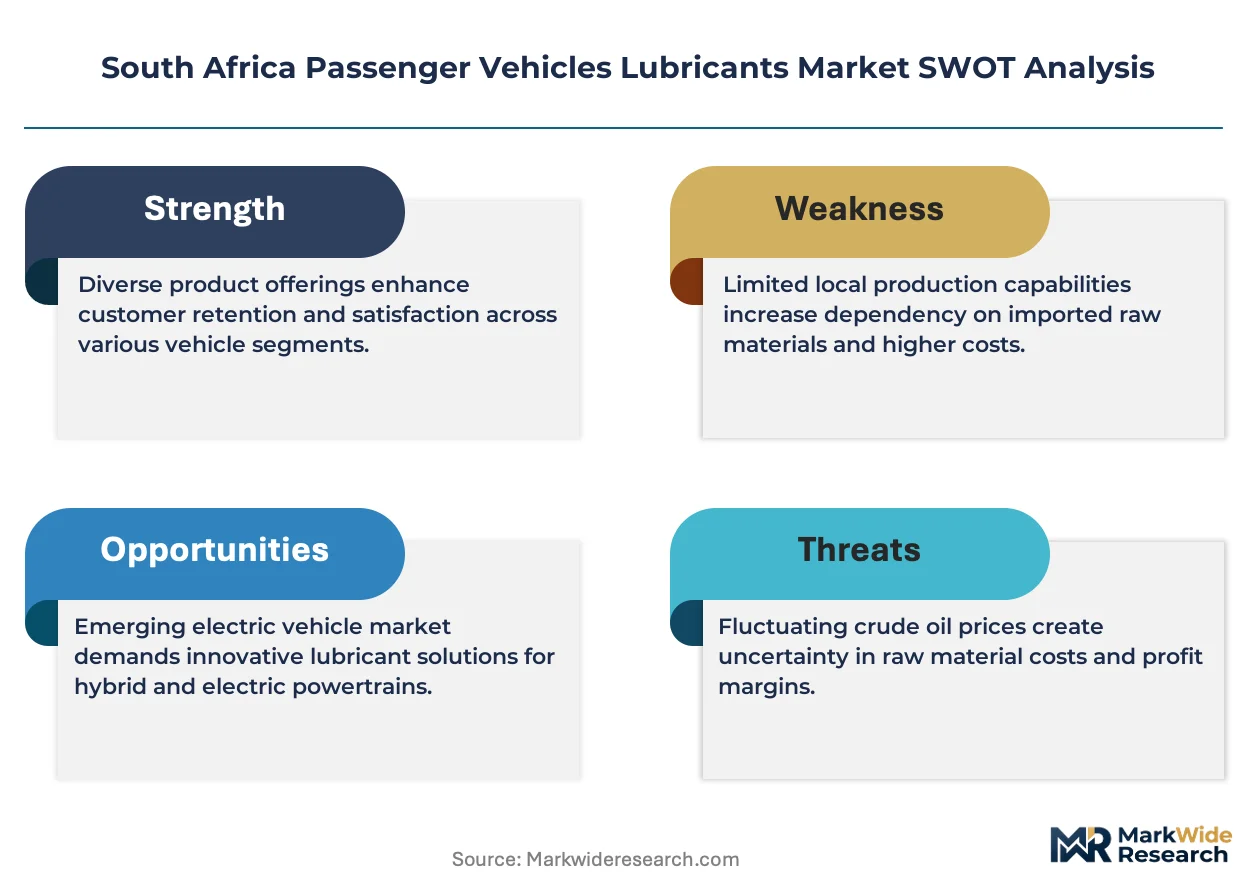
- Ride-hailing platform expansion:Uber and Bolt driver networks in Cape Town, Durban, and Port Elizabeth generate concentrated lubricant demand from vehicles accumulating 80,000+ kilometers annually, far exceeding private ownership utilization rates.
- NRCS enforcement alignment:The National Regulator for Compulsory Specifications mandates phosphorus and sulfur content limits that accelerate formulation upgrades, compelling blenders to invest in higher-performance additive packages.
Market Restraints
- Base oil import dependency:South African blenders source 60-70% of Group II and III base stocks from Middle Eastern and Asian refiners, exposing margins to rand-dollar volatility and shipping cost spikes through Durban port congestion.
- Mineral oil price anchoring:Cost-sensitive DIY maintainers in townships and peri-urban areas resist premium synthetic pricing, locking volume in lower-margin product tiers despite OEM warranty requirements.
- Aging vehicle parc technical constraints:Pre-2010 sedan and hatchback fleets with worn seals and gaskets cannot tolerate low-viscosity synthetic grades without leakage risks, segmenting addressable demand by vehicle vintage.
Strategic Opportunities
- Western Cape fleet servicing gap:Cape Town's ride-hailing density exceeds dedicated fleet maintenance infrastructure, creating whitespace for mobile oil change services and on-site bulk lubricant delivery models.
- SABS certification as competitive moat:Smaller blenders lacking NRCS compliance infrastructure face exit pressure, opening acquisition targets for compliant operators seeking Gauteng market share expansion.
- Workshop management software integration:Digital platforms connecting fleet operators to authorized service centers enable predictive maintenance scheduling, embedding lubricant procurement into automated workflow systems.
Industry Challenges
- Skilled lubricant technician shortage:Diagnostic capability for modern engine oil analysis and condition monitoring remains concentrated in Johannesburg and Pretoria dealerships, leaving secondary cities underserved.
- Multi-grade inventory complexity:Service stations must stock 5W-30, 5W-40, 10W-40, and 15W-40 variants across mineral, semi-synthetic, and synthetic tiers, straining working capital and shelf space optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Passenger Vehicles Lubricants Market |
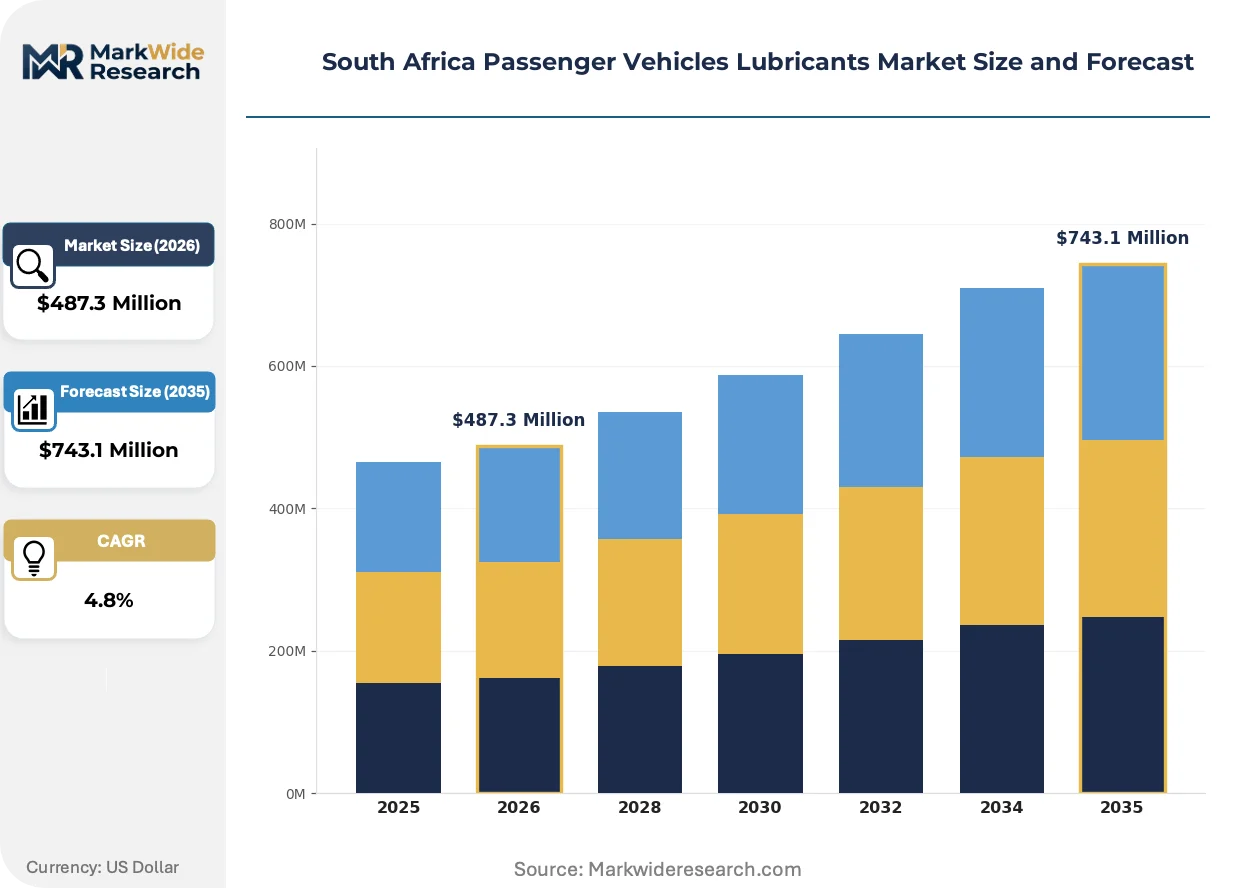
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Vehicle Type: Sedans, SUVs, Hatchbacks, Coupes Performance Grade: Mineral, Synthetic, Semi-Synthetic, High-Mileage Distribution Channel: Retail Stores, Online Platforms, Service Stations, Distributors |
| Companies Covered | ExxonMobil Corporation, TotalEnergies, Astron Energy, FUCHS, Sasol, BP PLC (Castrol), Shell, Puma Energy, Engen Petroleum Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and procurement digitization are compressing traditional service models. Three developments are restructuring how lubricants reach end-users and what performance specifications dominate blender R&D priorities.
Low-viscosity 0W-20 and 5W-30 synthetic grades engineered for turbocharged direct-injection engines are miniaturizing the addressable market for conventional mineral oils. Fleet procurement managers at Bolt and Uber partner networks in Johannesburg specify these grades exclusively, accepting premium pricing to minimize downtime. The technology is compressing blender production runs toward high-performance formulations while idling Group I base oil processing capacity.
South Africa's Department of Transport coordinates with the NRCS to align SABS 1191 revisions with Euro 6-equivalent emissions standards, tightening phosphorus limits to protect catalytic converter longevity. Local blenders must reformulate additive packages or forfeit OEM approvals from Volkswagen, Toyota, and Ford assembly operations in Gauteng. The policy is forcing smaller competitors toward contract manufacturing arrangements with multinational compounders holding pre-certified formulations.
Digital procurement platforms connecting fleet operators to bulk lubricant distributors are displacing traditional service station walk-in purchases. Takealot and specialized B2B marketplaces enable price transparency and consolidated invoicing for multi-vehicle operators in Durban and Cape Town. The channel shift is most visible among mid-size logistics fleets with 50-200 vehicles seeking to centralize maintenance spend under procurement officers rather than decentralized driver discretion.
South Africa Passenger Vehicles Lubricants Market Segmentation
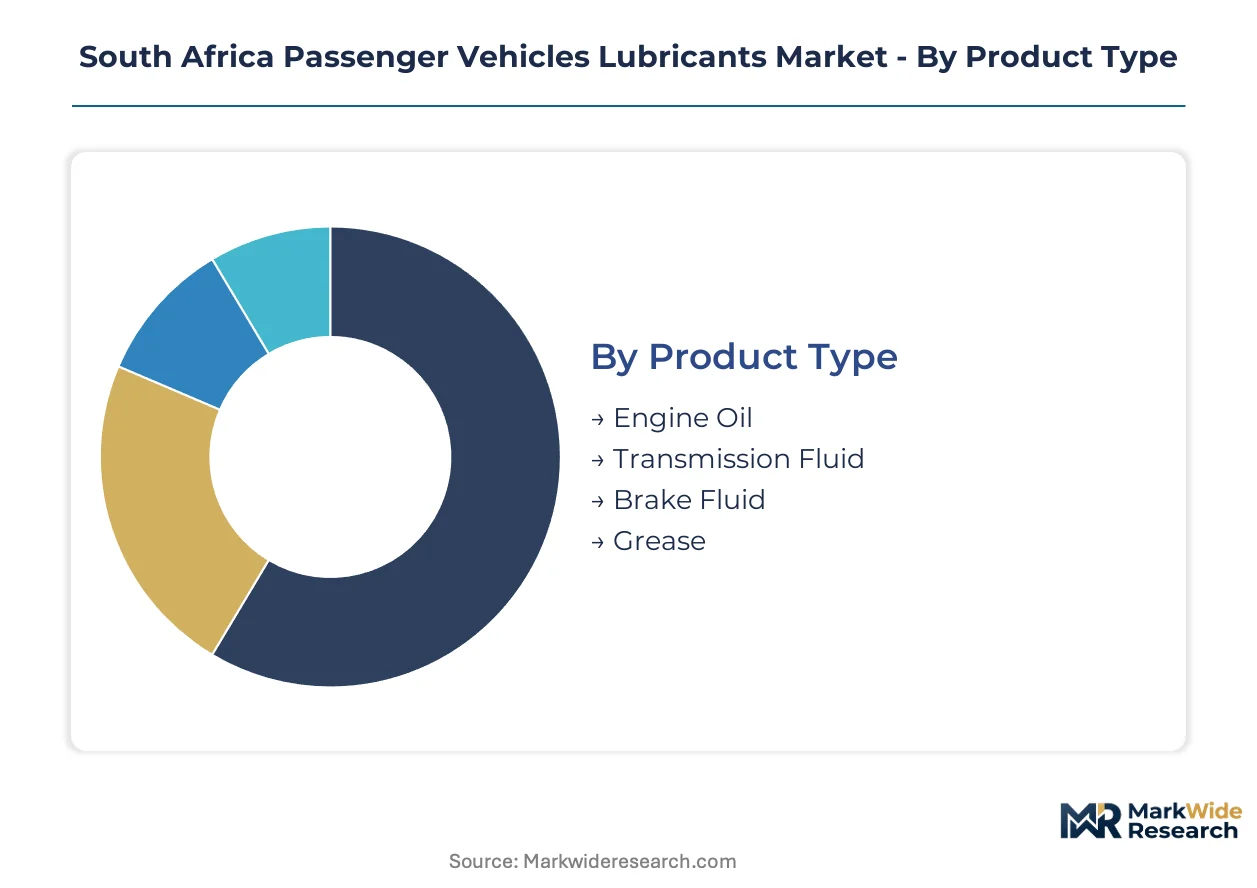
South Africa's passenger vehicle lubricants market fragments across four dimensions that determine formulation chemistry, pricing power, and channel access. NRCS-enforced SABS standards create regulatory fault lines between compliant and non-compliant product tiers, while Gauteng's fleet density concentrates demand in specific performance grades.
Product Type:
NRCS mandates under SABS 1191 establish minimum performance benchmarks that segment lubricant categories by drain interval capability and thermal stability requirements.
- Engine Oil:Formulated hydrocarbon-based fluids with additive packages engineered for friction reduction and heat dissipation across Highveld temperature extremes. Fleet operators in Johannesburg-Pretoria corridors specify high-performance grades exclusively, accepting premium pricing to minimize vehicle downtime on high-utilization routes.
- Transmission Fluid:Specialized lubricants for automatic and manual gearbox systems requiring precise viscosity retention under sustained highway thermal loads. Demand concentrates in authorized workshops servicing aging sedan parc vehicles where seal compatibility constrains formulation selection.
- Brake Fluid:Hydraulic fluids meeting DOT specifications for moisture resistance and boiling point stability. DIY maintainers in peri-urban areas drive volume through retail channel purchases despite technical complexity of proper system flushing.
- Grease:Thickened lubricants for chassis and bearing applications with limited synthetic penetration due to price sensitivity in informal maintenance sectors.
Engine Oil handles the majority of throughput; Transmission Fluid is gaining share fastest as automatic transmission penetration rises in urban fleet vehicles.
Vehicle Type:
Cost tier differentiation separates high-utilization commercial assets from discretionary private vehicles with divergent maintenance spend patterns.
- Sedans:Dominant vehicle category in South Africa's aging parc with average age exceeding twelve years. Ride-hailing platforms in Cape Town and Durban concentrate lubricant demand in this segment through intensive annual mileage accumulation.
- SUVs:Premium vehicle segment with OEM warranty requirements mandating synthetic formulations. Higher displacement engines and towing applications drive elevated per-vehicle lubricant consumption versus passenger car categories.
- Hatchbacks:Compact urban vehicles with fragmented maintenance patterns spanning authorized dealerships and informal township workshops. Price elasticity varies sharply between metropolitan and peri-urban owner populations.
- Coupes:Low-volume performance segment with specialized lubricant requirements for high-revving engines and limited aftermarket service infrastructure outside Gauteng and Western Cape.
Sedans anchor volume throughput; SUVs command the steepest expansion trajectory as fleet operators upgrade vehicle specifications.
Performance Grade:
Supply concentration in Group II and III base stocks shapes blender formulation investments and import certification economics.
- Mineral:Conventional Group I base oil formulations with limited additive investment. Cost-sensitive DIY maintainers in townships resist premium pricing despite SABS compliance requirements, locking volume in lower-margin tiers.
- Synthetic:Engineered Group III and PAO-based fluids with extended drain interval certification. Bolt and Uber partner networks specify these grades exclusively to stretch service windows on Johannesburg-Pretoria corridors.
- Semi-Synthetic:Blended formulations balancing performance upgrade with price accessibility. Mid-size logistics fleets with 50-200 vehicles favor this tier for cost-controlled maintenance centralization.
- High-Mileage:Specialized formulations with seal conditioners for vehicles exceeding 150,000 kilometers. Pre-2010 sedan parc compatibility requirements segment addressable demand by vehicle vintage and technical condition.
Mineral formulations retain volume leadership; Synthetic grades are climbing the fastest as NRCS enforcement tightens phosphorus and sulfur content limits.
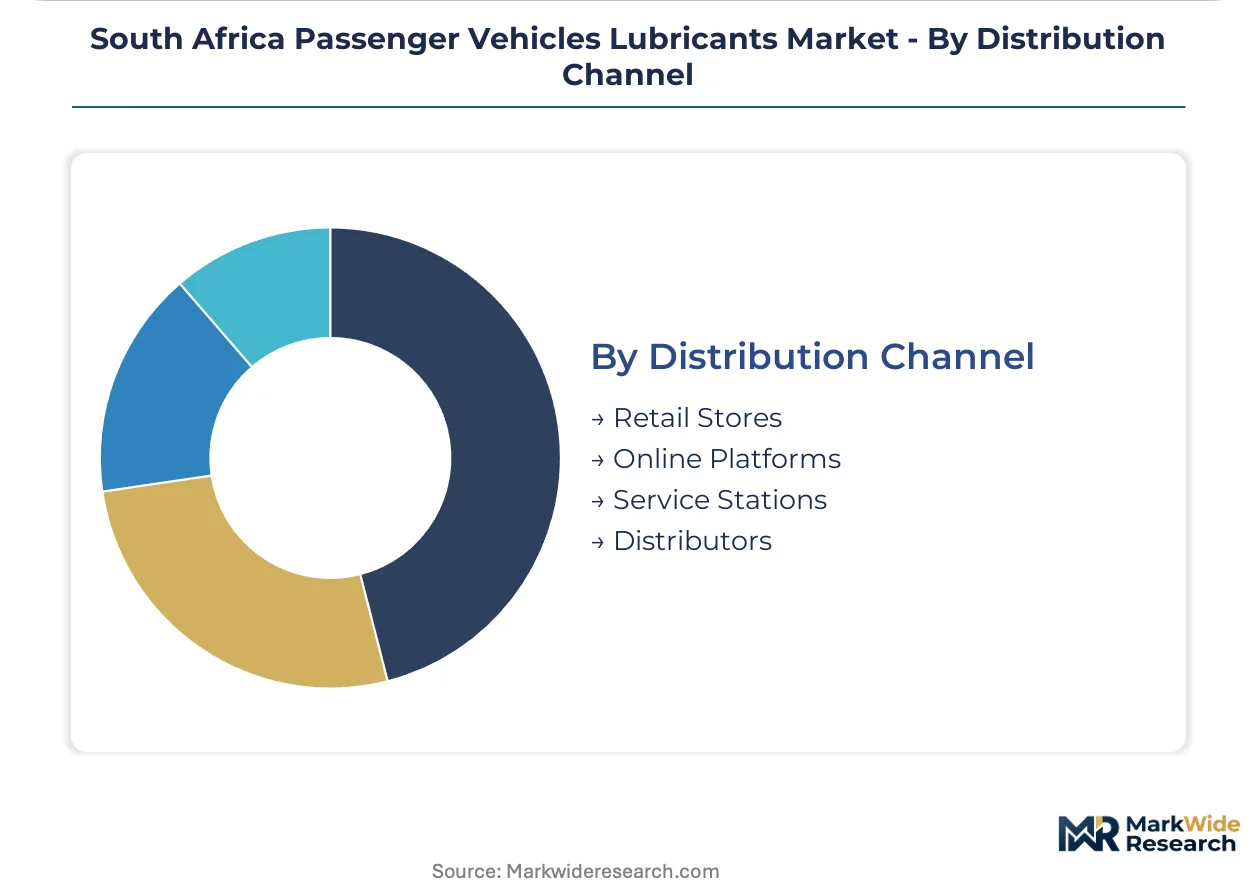
Distribution Channel:
Customer type fragmentation between institutional procurement officers and individual vehicle owners determines channel economics and working capital requirements.
- Retail Stores:Physical outlets including automotive parts chains and general merchandise retailers serving DIY maintainers. Inventory complexity across multi-grade specifications strains shelf space optimization in peri-urban locations.
- Online Platforms:Digital marketplaces including Takealot and specialized B2B portals enabling price transparency and consolidated invoicing. Fleet procurement officers in Durban and Cape Town leverage these channels to centralize maintenance spend.
- Service Stations:Branded fuel retail networks with attached workshops capturing walk-in lubricant purchases. Astron Energy's corridor presence anchors volume through this channel on major transport routes.
- Distributors:Bulk lubricant suppliers delivering to independent workshops and fleet maintenance facilities. Mobile oil change services in Western Cape rely on distributor relationships for on-site delivery models.
Service Stations process the majority of transactions; Online Platforms are expanding most quickly as fleet procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blending capacity and fleet servicing infrastructure concentrate in Gauteng province, where Johannesburg and Pretoria generate the majority of passenger vehicle lubricant demand. Western Cape and KwaZulu-Natal function as secondary demand nodes shaped by distinct utilization patterns and regulatory enforcement intensity.
Gauteng Province
Ride-hailing fleet density in Johannesburg-Pretoria corridors drives synthetic lubricant procurement at volumes exceeding private ownership benchmarks. The National Regulator for Compulsory Specifications maintains its headquarters in Pretoria, enabling rapid SABS 1191 compliance verification for blenders operating in the province. Midrand and Rosslyn industrial zones host the bulk of domestic formulation facilities serving OEM assembly operations.
Western Cape
Cape Town's Bolt and Uber driver networks accumulate annual mileage that compresses drain intervals and elevates per-vehicle lubricant consumption. Provincial environmental regulations under the Western Cape Department of Environmental Affairs and Development Planning align with national emissions control frameworks. Stikland and Paarden Eiland industrial areas concentrate bulk lubricant storage and distribution infrastructure for regional fleet servicing.
KwaZulu-Natal
Durban's port logistics and coastal climate conditions shape lubricant specifications addressing humidity-related corrosion protection. The KwaZulu-Natal Department of Transport coordinates vehicle roadworthiness testing that indirectly enforces lubricant quality through emissions inspection linkages. Pinetown and Prospecton manufacturing zones support regional blending operations dependent on imported base oil shipments through Durban harbor.
Eastern Cape
Port Elizabeth and East London vehicle assembly plants generate OEM-specified lubricant demand tied to warranty service networks. Provincial economic development programs under the Eastern Cape Development Corporation incentivize automotive supplier clustering. Coega Industrial Development Zone attracts lubricant distributors seeking export access to Southern African Development Community markets.
Free State
Bloemfontein's position as a logistics interchange creates fleet servicing demand from long-haul transport operators traversing the N1 corridor. The Free State Department of Police, Roads and Transport manages vehicle licensing that interfaces with roadworthiness standards affecting maintenance compliance. Phuthaditjhaba and Welkom mining belt communities sustain mineral oil demand from aging vehicle parcs with limited synthetic upgrade penetration.
South Africa Passenger Vehicles Lubricants Market Competitive Landscape
Concentration sits with multinational energy conglomerates possessing integrated base oil supply and retail distribution networks. Three domestic blenders maintain viable positions through corridor-specific service station presence and fleet contract relationships. Competitive dynamics revolve around SABS certification acquisition and bulk procurement platform integration rather than price-led displacement.
Among integrated petroleum majors, ExxonMobil Corporation and Shell anchor the premium synthetic segment through direct OEM approval relationships and high-performance formulation portfolios. Astron Energy occupies a distinctive position through its extensive retail and service station network across South Africa's major transport corridors. Sasol represents the domestic upstream integration archetype with captive base oil production reducing import dependency for local blending operations.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| TotalEnergies |
| Astron Energy |
| FUCHS |
| Sasol |
| BP PLC (Castrol) |
| Shell |
| Puma Energy |
| Engen Petroleum Ltd |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Gauteng fleet operators and bulk lubricant distributors lock in synthetic grade supply access while anchoring price visibility against rand-dollar volatility on imported Group II and III base stocks. These contracts compress spot market participation for high-volume buyers, segmenting procurement economics between institutional purchasers and fragmented retail channels.
Pricing Analysis
Volume-discount tiering structures stratify across fleet-scale contracts, mid-size logistics procurement, and individual DIY purchases. Price differentiation centers on SABS 1191 certification grade and synthetic formulation investment, with premium grades commanding substantial uplifts for extended drain interval capability. Cost compression in mineral oil tiers intensifies as rand depreciation elevates import base stock landed costs. Township-based DIY maintainers exhibit highest price sensitivity, resisting synthetic upgrade despite OEM warranty exposure.
Supply Chain Analysis
Strategic stockpile preferences dominate blender inventory strategy, with Gauteng facilities maintaining 60-90 day Group II and III base oil cover against Durban port congestion risks. Supply concentrates in Middle Eastern and Asian refiners, with South African blenders drawing from Saudi Arabian, South Korean, and Singaporean sources. Single-source vulnerability runs through the Durban-Richards Bay logistics corridor. Distribution runs through branded service station networks, bulk distributor fleets, and emerging B2B digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Africa passenger vehicles lubricants market functions as a service-attach opportunity where predictive maintenance software and fleet management platforms expand faster than base lubricant volume growth. Recurring revenue layers from condition monitoring subscriptions and automated procurement systems outpace hardware margin expansion.
For Market Incumbents: Secure SABS 1191 certification moats through additive package pre-approval investments, blocking smaller blenders from OEM contract eligibility. Anchor corridor presence by acquiring distressed distributor assets in Western Cape fleet servicing gaps. Vertical integration into captive base oil processing, following Sasol's domestic production model, defends margin position against import cost volatility. For New Entrants and Emerging Players: Mobile oil change services for Cape Town ride-hailing density represent the most penetrable whitespace, where dedicated fleet infrastructure lags vehicle utilization intensity. Target mid-size logistics fleets with 50-200 vehicles through workshop management software integration, embedding lubricant procurement into automated maintenance scheduling workflows. Pursue white-label contract manufacturing for NRCS-compliant blenders lacking formulation R&D capability. For Investors and Strategic Acquirers: NRCS-compliant regional blenders with established Gauteng fleet contracts present acquisition targets as regulatory enforcement accelerates competitor exit. Long-term viability hinges on synthetic grade portfolio depth and digital procurement platform integration. Monitor SABS 1191 revision timing as inflection indicator for formulation investment intensity and additive package supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| SABS Certification Investment | Pre-approval for SABS 1191 revisions blocks competitor access to OEM fleet contracts. |
| Backward Integration into Base Oil | Captive Group II/III production shields margins from rand-dollar volatility on imports. |
| Workshop Software Integration | Predictive maintenance platforms embed lubricant procurement into automated fleet workflows. |
| Mobile Fleet Servicing Expansion | On-site oil change models capture Western Cape ride-hailing density exceeding fixed infrastructure. |
| Digital Procurement Platform Partnership | B2B marketplace integration enables price transparency and consolidated invoicing for multi-vehicle operators. |
Research Methodology
A spread of perspectives from lubricant blenders, fleet procurement managers, aftermarket distributors, and NRCS compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SABS documentation, Department of Transport regulatory filings, and customs trade records on base oil imports. Bottom-up volume modeling from Gauteng, Western Cape, and KwaZulu-Natal demand nodes triangulated against top-down market sizing from petroleum industry association data.
Segmentation dimensions modeled include product type, vehicle category, performance grade tier, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis on historical fleet utilization trends and synthetic penetration trajectories, cross-referenced with NRCS enforcement intensity assumptions. Forecast inputs incorporated ride-hailing platform vehicle registration data and OEM assembly plant output projections for warranty-captured lubricant demand.
Underlying assumptions cover rand exchange rate stability, Durban port throughput capacity, and NRCS enforcement continuity, with deviation risk concentrated in carbon border adjustment implementation by European trading partners. Revision becomes warranted when base oil import cost thresholds breach blender margin sustainability or SABS 1191 revision timing accelerates formulation compliance deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Lubricants Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Bulgaria Automotive Engine Oils Market