
 Global Automotive Camera Cleaning System Market | 2026-2036
Global Automotive Camera Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Camera Cleaning System Market Intelligence
The migration of value from standalone hardware components to integrated system sales with software-defined features is reconfiguring profit pools for suppliers. Bosch leverages its extensive electronics and software expertise to offer complete ADAS sensor packages. Continental AG competes by providing scalable cleaning solutions for different vehicle segments, from budget to premium. Valeo specializes in sensor technology, integrating cleaning systems directly into its camera and LiDAR modules to ensure performance.
An automotive camera cleaning system is an active mechanism designed to clear contaminants such as dirt, water, and ice from the lenses of ADAS cameras. These systems typically utilize either high-pressure fluid sprays or targeted air jets, activated automatically or manually to maintain sensor visibility. Fluid spray systems represent the dominant product type due to their effectiveness in various weather conditions. Demand is overwhelmingly concentrated in the passenger vehicles application, with OEMs constituting the primary end-user channel for factory-installed units.
Regulatory frameworks are critical, with the EU's General Safety Regulation and guidelines from the US NHTSA implicitly requiring reliable sensor performance. In parallel, China's national standards for intelligent connected vehicles (ICVs) are creating a mandate for robust sensor cleaning solutions. Automakers and suppliers must decide whether to standardize on a single high-performance cleaning architecture or create tiered solutions for different vehicle price points.
Market Dynamics
The market's trajectory is fundamentally tied to automotive safety regulations. Mandates like the European Union's General Safety Regulation, which require ADAS functionalities dependent on clear camera views, are transforming cleaning systems from optional features to non-negotiable standard equipment.
Growth Catalysts
- Regulatory Mandates:The EU's General Safety Regulation and similar guidelines from the US NHTSA are compelling automakers to ensure reliable sensor performance, directly spurring demand for active cleaning systems in passenger vehicles.
- ADAS Proliferation:The expansion of Level 2 and Level 3 autonomous driving features into mass-market vehicle segments necessitates clear, uninterrupted data from multiple cameras, making cleaning systems essential hardware.
- Chinese ICV Initiative:China's national strategy for intelligent connected vehicles (ICVs) is creating a large, concentrated market where robust sensor cleaning is a prerequisite for meeting government performance standards for new models.
Market Restraints
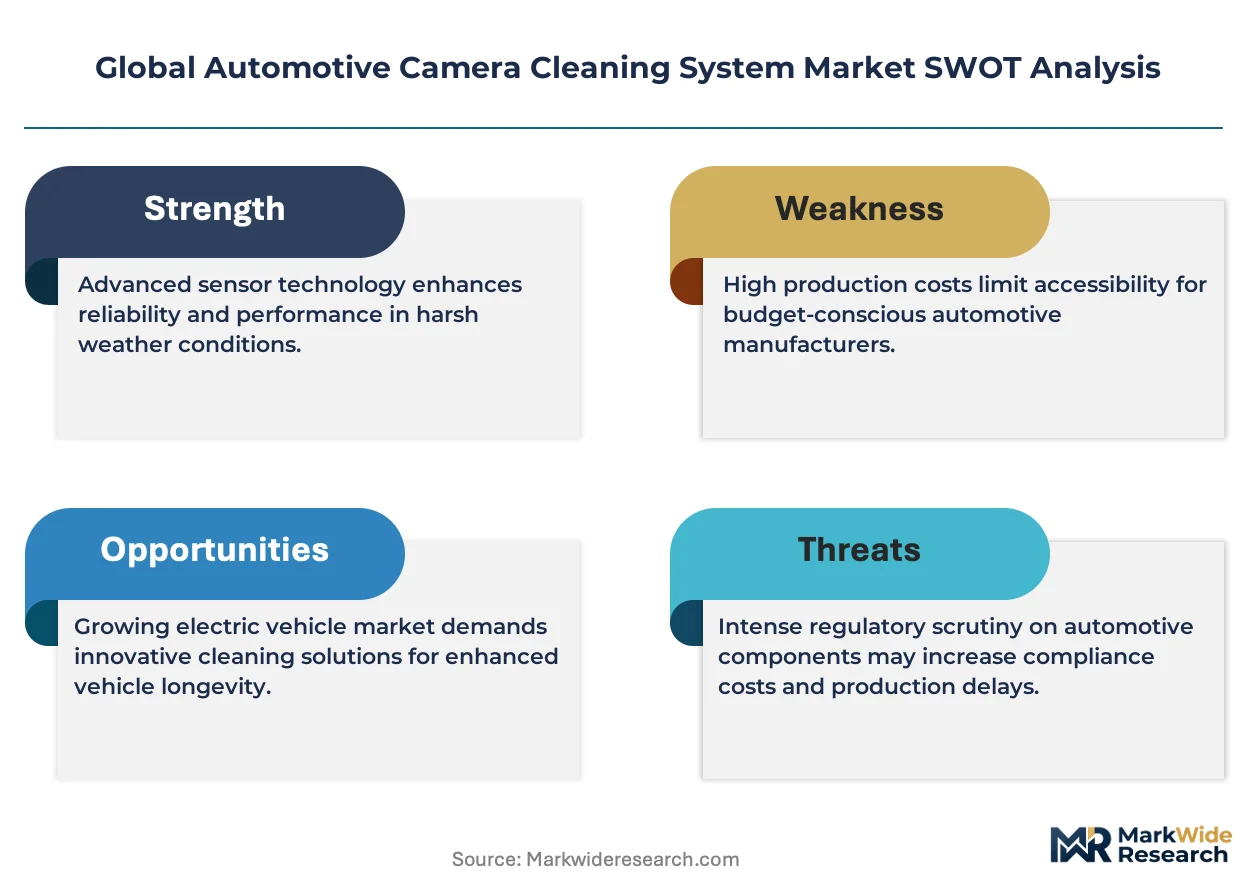
- Cost Pressures in Economy Segments:The added bill-of-materials cost for a complete cleaning system, including pumps, nozzles, and control units, presents a significant barrier to adoption in highly price-sensitive economy and budget vehicle classes.
- Performance in Extreme Cold:Standard fluid-based systems can fail in freezing conditions due to ice formation in nozzles and lines, requiring costly heated components or specialized de-icing fluids that increase system complexity.
- Aftermarket Viability:The deep integration of cleaning systems with OEM vehicle software and electronics makes developing universal, cost-effective aftermarket retrofit solutions exceptionally difficult, limiting a potential revenue channel.
Strategic Opportunities
- Commercial Vehicle Telematics:Equipping long-haul trucks and delivery vans with camera cleaning systems supports fleet management and safety by ensuring uptime for video telematics and blind-spot monitoring systems in all weather conditions.
- Sensor Fusion Cleaning Platforms:Developing unified cleaning solutions that service multiple sensor types, such as cameras, LiDAR, and radar, offers a path to higher-value system sales by providing a single, integrated platform for automakers.
- Service and Consumables:A recurring revenue model can be built around the sale of proprietary cleaning fluids, replacement nozzles, and service contracts, particularly in the commercial vehicle and premium passenger car segments.
Industry Challenges
- System Integration Complexity:Ensuring that the cleaning system's software controller communicates flawlessly with the vehicle's central computer and ADAS control unit without creating diagnostic faults is a persistent engineering hurdle for suppliers.
- Lack of Performance Standardization:Without an agreed-upon industry standard like an ISO certification for cleaning effectiveness, automakers must rely on their own internal testing, creating validation friction and inconsistent requirements for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Camera Cleaning System Market |
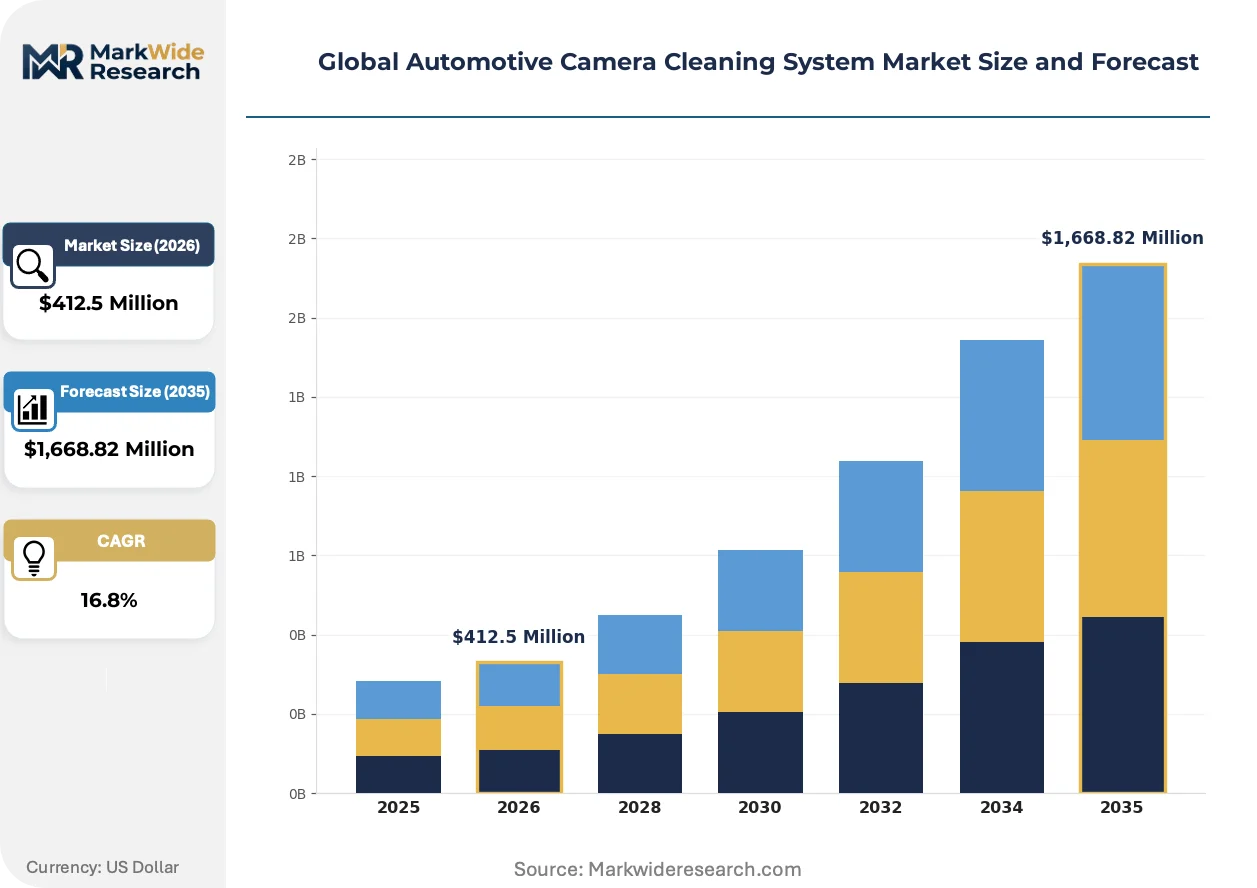
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,668.82 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Jets, Fluid Sprays, Wiper Blades, Ultrasonic Cleaners Technology: Electromechanical, Pneumatic, Hydraulic, Piezoelectric Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Specialty Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Service Centers |
| Companies Covered | Bosch, Continental AG, Valeo, Denso Corporation, Hyundai Mobis, Magna International, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, Ficosa Internacional SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Camera Cleaning System Market Strategic Shifts & Innovations
The market is evolving from providing simple fluid delivery hardware to offering intelligent, software-controlled systems that are integral to sensor performance. This shift places a premium on electronics expertise and the ability to integrate with complex vehicle networks.
Advanced systems now use telescopic nozzles and targeted air-fluid bursts. Automakers in the premium segment are adopting these solutions for critical sensors like forward-facing cameras and LiDAR. The value proposition is migrating from selling a standalone hardware kit to offering a performance-guaranteed, fully integrated sensor module that includes cleaning as a core feature.
The EU's General Safety Regulation is a primary force shaping system design. Its requirements for features like lane-keeping assist and emergency braking implicitly mandate that the associated cameras remain operational in adverse conditions. Consequently, automakers selling into the European Union are increasingly making camera cleaning systems standard equipment, even on lower-priced models.
OEM purchasing behavior is moving away from sourcing individual components toward procuring complete, pre-validated system modules. This trend favors large, vertically integrated Tier 1 suppliers who can deliver a turnkey solution encompassing the pump, fluid reservoir, hoses, nozzles, and control software. This shift is most pronounced in North America and Europe, where ADAS complexity makes single-source system responsibility highly attractive to vehicle manufacturers.
Global Automotive Camera Cleaning System Market Segmentation
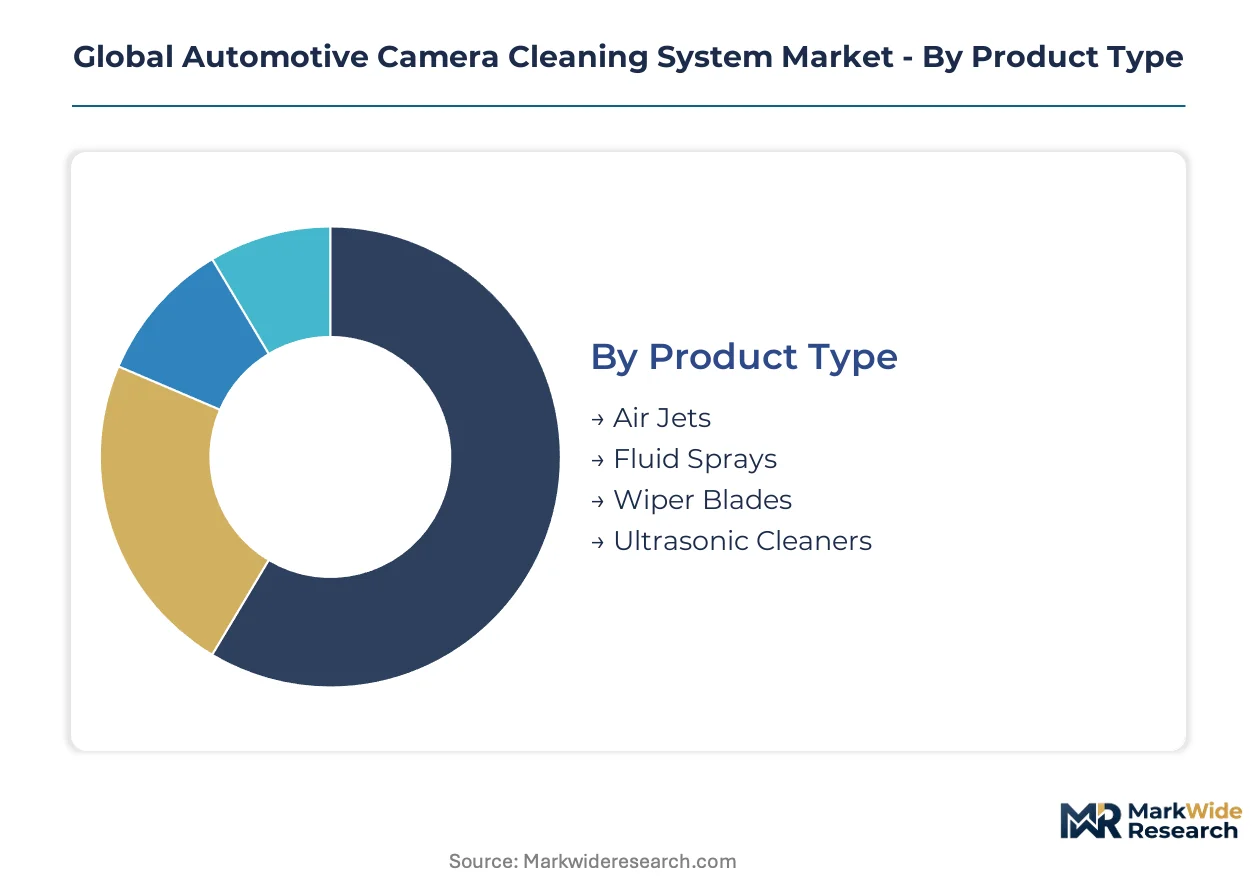
The global automotive camera cleaning system market is segmented to provide a detailed understanding of the various product types, underlying technologies, target applications, and primary end-user channels. This segmentation helps identify specific demand pockets and the unique requirements across different vehicle categories and operational environments.
Product Type:
After-sales-service intensity for cleaning systems varies significantly across product types, influencing maintenance requirements and recurring revenue potential for suppliers.
- Fluid Sprays:These systems utilize high-pressure fluid jets to clear contaminants from camera lenses, offering broad effectiveness across diverse weather conditions. Demand for fluid spray systems is concentrated in passenger vehicles, driven by the EU's General Safety Regulation requiring consistent ADAS functionality.
- Air Jets:Air jet systems employ targeted bursts of compressed air to remove dust, dirt, and water, often used in conjunction with fluid sprays for specific scenarios. Their adoption is increasing in premium vehicles, particularly for LiDAR and radar units where fluid residue can be problematic.
- Wiper Blades:Miniature wiper mechanisms physically clear camera lenses, providing a mechanical solution for persistent debris or ice. These are less common due to complexity and potential for scratching, but find niche applications in heavy-duty commercial vehicles.
- Ultrasonic Cleaners:Ultrasonic systems use high-frequency vibrations to dislodge microscopic particles and water droplets from camera surfaces. This advanced technology is under development for high-end autonomous vehicles in countries like Germany and Japan.
Fluid Sprays holds the largest share; momentum sits with Air Jets.
Technology:
The choice of underlying technology impacts system cost and integration complexity within the vehicle's electrical architecture.
- Electromechanical:These systems rely on electric motors and pumps to drive fluid or air delivery, representing the most common and mature technology. Electromechanical solutions are standard in factory-installed units for passenger cars across North America and Europe.
- Pneumatic:Pneumatic systems utilize compressed air, often sourced from the vehicle's existing air brake system in commercial applications, to clear camera lenses. This approach is gaining traction in heavy trucks and buses in countries like China, where robust performance is critical.
- Hydraulic:Hydraulic systems employ fluid pressure to actuate cleaning mechanisms, offering high force output for specialized applications. Their use is limited due to complexity, primarily found in heavy machinery or specialty vehicles.
- Piezoelectric:Piezoelectric technology uses voltage to deform materials, creating precise, high-frequency vibrations for cleaning. This innovative technology is being explored for compact, low-power solutions in advanced sensor modules.
Electromechanical solutions currently lead in adoption; pneumatic systems are gaining traction.
Application:
Different vehicle applications demand varying levels of cleaning system robustness and operational frequency.
- Passenger Vehicles:This segment includes sedans, SUVs, and compact cars, where ADAS integration is rapidly becoming standard. Passenger vehicles represent the largest application area, driven by safety mandates from the US NHTSA and the EU's General Safety Regulation.
- Commercial Vehicles:This category encompasses trucks, buses, and vans used for logistics and public transport, where clear camera views support telematics and blind-spot monitoring. Commercial vehicle demand is growing, particularly for long-haul fleets in countries like the United States and Germany.
- Off-Road Vehicles:Designed for challenging terrains, these vehicles require highly durable cleaning systems to contend with mud, dust, and extreme conditions. Specific demand arises from mining and construction sectors in regions with harsh environments.
- Specialty Vehicles:This segment includes emergency vehicles, agricultural machinery, and autonomous shuttles, each with unique requirements for continuous camera visibility. Adoption is driven by operational safety and efficiency in specific industrial contexts.
Passenger Vehicles account for the majority of installations; commercial vehicles show significant expansion.
End User:
The primary end-user channel determines procurement patterns and the degree of system integration at the manufacturing stage.
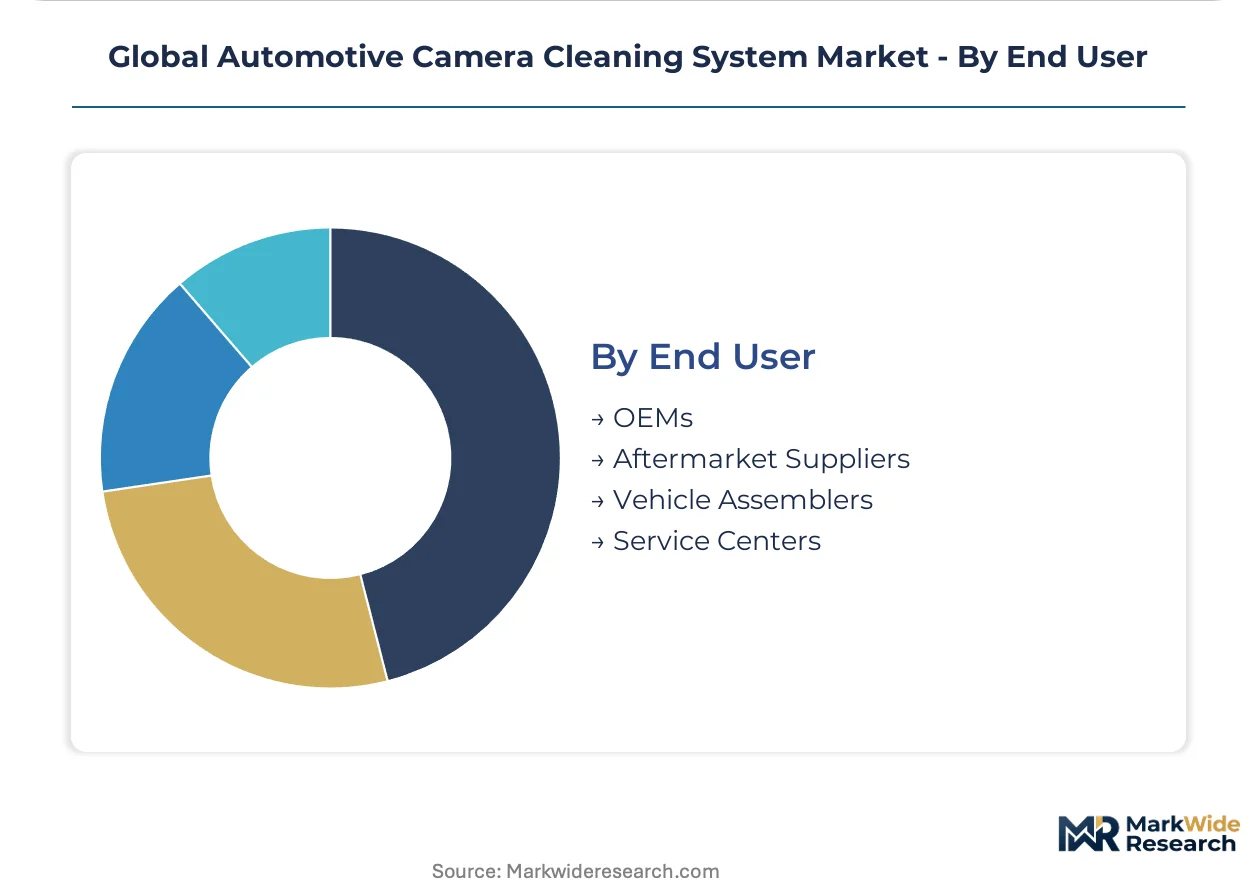
- OEMs:Original Equipment Manufacturers integrate cleaning systems directly into new vehicles during the assembly process, demanding high-volume, deeply integrated solutions. OEMs constitute the dominant end-user segment, particularly for ADAS-equipped vehicles in Germany and Japan.
- Aftermarket Suppliers:These companies provide cleaning systems for installation after a vehicle has left the factory, often as upgrades or replacements. Aftermarket viability is challenged by the deep integration of OEM systems.
- Vehicle Assemblers:This category includes companies that assemble vehicles using components from various suppliers, often for niche markets or custom builds. Their procurement focuses on modular, easily integrated systems.
- Service Centers:Service centers primarily handle maintenance, repair, and replacement of existing cleaning systems. Their demand is for spare parts and specialized fluids.
OEMs represent the dominant purchasing channel; aftermarket suppliers face integration hurdles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Europe prioritizes regulatory compliance for camera cleaning systems, China's market expansion is tied to its burgeoning electric vehicle production and national intelligent connected vehicle standards. The United States focuses on ADAS proliferation. This regional divergence shapes product development and market penetration strategies for suppliers.
China
Demand for camera cleaning systems in China stems from its national intelligent connected vehicle (ICV) strategy and rapid EV sector expansion. China's GB standards for ICVs mandate robust sensor cleaning solutions in new vehicle models. Major automotive manufacturing hubs like the Yangtze River Delta are seeing significant investment.
Germany
German automakers are incorporating camera cleaning systems to meet stringent European Union General Safety Regulation requirements for ADAS functionalities. The KBA implicitly requires reliable sensor performance for vehicle type approval. Automotive clusters in Bavaria and Baden-Württemberg drive innovation in integrated cleaning solutions.
United States
Automotive camera cleaning system integration in the United States is spurred by widespread adoption of Level 2 and Level 3 autonomous driving features. Guidelines from the US NHTSA emphasize reliable sensor performance for safety. Research and development in Michigan's automotive corridor focuses on robust solutions.
Japan
Japanese OEMs integrate camera cleaning systems to enhance reliability of their advanced driver-assistance systems, especially for forward-facing cameras and LiDAR. METI promotes innovation in automotive safety technologies, supporting cleaning system development. Technology clusters in the Kanto region explore ultrasonic cleaning and sensor fusion platforms.
France
French automotive manufacturers standardize camera cleaning systems in new models, driven by the European Union's General Safety Regulation. Compliance with EU mandates ensures features like lane-keeping assist remain operational. Automotive suppliers in the Auvergne-Rhône-Alpes region develop integrated modules for ADAS sensor packages.
Global Automotive Camera Cleaning System Market Key Industry Players
Capability concentration sits with one tier, while scale advantage sits with another in the automotive camera cleaning system market. The market exhibits a tiered structure, with large Tier 1 suppliers dominating integrated system sales to OEMs. These major players leverage extensive electronics and software expertise to offer complete ADAS sensor packages, including the critical cleaning solutions. Smaller, specialized firms focus on niche technologies or specific component manufacturing. Technology licensing and geographic expansion are also key competitive moves for these suppliers.
Among the established automotive suppliers, Bosch exemplifies a leader leveraging extensive electronics and software expertise to offer complete ADAS sensor packages. Continental AG, a German-based company, occupies a position providing scalable cleaning solutions for different vehicle segments, from budget to premium. Valeo, a French automotive supplier, represents specialization in sensor technology, integrating cleaning systems directly into its camera and LiDAR modules to ensure performance. These companies anchor innovation in system integration and continuous functionality for ADAS, driving market evolution.
| Leading Market Players |
|---|
| Bosch |
| Continental AG |
| Valeo |
| Denso Corporation |
| Hyundai Mobis |
| Magna International |
| ZF Friedrichshafen AG |
| HELLA GmbH & Co. KGaA |
| Ficosa Internacional SA |
| Others |
Cost & Logistics Intelligence
Regulatory mandates, such as the EU's General Safety Regulation, directly determine pricing tier spreads and supply chain configuration for automotive camera cleaning systems. These requirements transform optional features into standard equipment, influencing component sourcing and cost allocation.
Pricing Analysis
Long-term contract-based offtake agreements define the primary pricing model for automotive camera cleaning systems supplied to OEMs. Price differentiation stems from the performance tier required for ADAS functionality and the volume scale of OEM procurement. Cost compression in economy vehicle segments intensifies due to the added bill-of-materials. Passenger vehicle economy segments exhibit the highest price sensitivity, while premium and commercial vehicle applications prioritize performance and reliability.
Supply Chain Analysis
Single-source vulnerability within integrated ADAS packages poses a significant supply chain risk for automotive camera cleaning systems. Production concentrates in Germany, France, and Japan, home to major Tier 1 suppliers like Bosch, Valeo, and Denso. The supply chain relies on specialized components including miniature pumps, precision nozzles, and dedicated control units. Direct-to-OEM distribution dominates, with systems integrated during vehicle assembly, particularly for ADAS-equipped models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive camera cleaning system market represents a high-growth disruption, driven by the regulatory inflection of the EU's General Safety Regulation. This mandate for reliable ADAS functionality transforms these systems into essential vehicle components, creating new value pools.
For Market Incumbents:Entrench core market share by deepening software integration with vehicle ADAS platforms, enhancing system reliability. Expand scalable cleaning solutions to address cost pressures in economy segments, avoiding market erosion. Invest in R&D for unified sensor fusion cleaning platforms that service multiple sensor types. This strategic focus ensures sustained competitive advantage against emerging specialized entrants.
For New Entrants and Emerging Players:Pursue niche opportunities in commercial vehicle telematics, where robust cleaning systems enhance fleet safety and uptime. Develop cost-effective, modular solutions for off-road vehicles requiring extreme durability. The commercial vehicle segment offers a penetrable market due to its focus on operational efficiency. A compelling go-to-market angle involves offering integrated service contracts alongside cleaning system installations, ensuring recurring revenue streams.
For Investors and Strategic Acquirers:The EU's General Safety Regulation reshapes the acquisition landscape, emphasizing integrated ADAS solutions. Long-term viability centers on the essential role of camera cleaning in enabling higher levels of autonomous driving. Target specialized software and electronics firms with expertise in sensor fusion or compact cleaning mechanisms. Standardization of cleaning effectiveness, perhaps through an ISO certification, serves as a critical signal for market maturity and consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen ADAS Software Integration | Ensures seamless communication between cleaning systems and vehicle central computers for optimal performance. |
| Develop Sensor Fusion Cleaning Platforms | Offers automakers a unified solution for maintaining visibility across multiple sensor types like cameras and LiDAR. |
| Expand Commercial Vehicle Offerings | Captures growing demand from long-haul fleets for reliable telematics and blind-spot monitoring. |
| Invest in Advanced De-icing Solutions | Addresses performance limitations of fluid-based systems in extreme cold, enhancing reliability for all vehicles. |
| Standardize Cleaning Performance Metrics | Reduces validation friction for OEMs and provides clear benchmarks for suppliers across the market. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and extensive secondary research. Primary insights came from discussions with OEM platform engineers, Tier 1 supplier procurement leads, ADAS system integrators, and commercial fleet managers. Secondary validation drew from vehicle production databases, automotive component trade data, regulatory body publications, and company annual reports. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Forecast inputs considered ADAS penetration rates, EV production forecasts, and evolving regulatory mandates across the modeling period. The analytical framework projected market dynamics by product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market drivers. This approach provided a granular view of market expansion over the projection horizon.
Sensitivities concentrate around changes in ADAS adoption rates, new regulatory timelines, or material cost fluctuations. Forecasts reflect documented assumptions, but these external factors could revise market trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market