
 Italy Passenger Vehicles Lubricants Market | 2026-2036
Italy Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Passenger Vehicles Lubricants Market Foresight
Italy is reshaping its lubricant supply base through expanded blending capacity in the Po Valley corridor. Eni SpA leverages its Ravenna refinery complex to sustain captive base oil supply for passenger vehicle formulations. Q8Oils anchors distribution through its service station network across the peninsula. BP PLC (Castrol) competes on synthetic product specialization for high-performance Italian OEM partnerships.
Italy passenger vehicles lubricants comprise refined petroleum-derived or synthetic base stocks formulated with detergent, dispersant, anti-wear, and viscosity-index improver additives, engineered to reduce friction, dissipate heat, and prevent deposit formation in internal combustion and hybrid powertrain systems. The typical passenger car engine oil operates within viscosity grades spanning SAE 0W-20 to 5W-40, with total base number specifications determining drain interval compatibility. Synthetic oil commands premium positioning among fleet operators seeking extended drain intervals, while mineral oil retains volume leadership in the individual consumer segment through price-accessible service station channels. Additives represent a concentrated margin pool as formulation houses supply proprietary packages to blenders seeking ACEA C-sequence and API SP compliance.
Italy's Ministry of Ecological Transition enforces EU Green Deal mobility targets that tighten CO2 emission thresholds for passenger vehicles, indirectly mandating lower-viscosity lubricant grades that reduce mechanical friction losses. The country's adoption of REACH chemical registration protocols and F-Gas Regulation benchmarks constrains additive chemistries and base oil processing pathways. BIS-equivalent UNI standards govern lubricant labeling and performance claims at the national level, creating a multi-layer compliance architecture for market participants. Stakeholders must monitor the pace of hybrid powertrain penetration against full-electric adoption to calibrate R&D allocation between friction-reduction chemistry and dielectric fluid development.
Market Dynamics
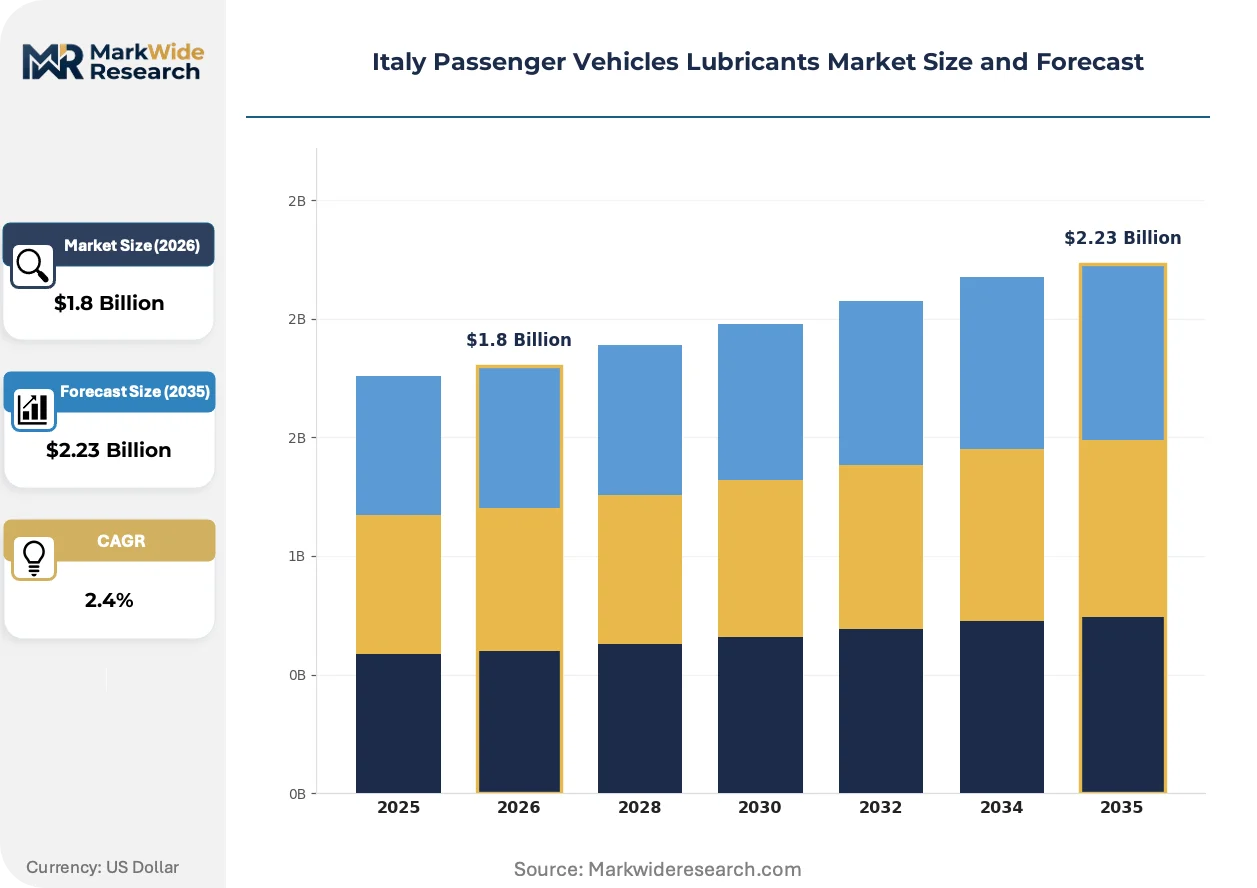
Italy's lubricant demand is bifurcating between extended-drain synthetic formulations for fleet operators and price-sensitive mineral grades for individual motorists, with EU Green Deal emission benchmarks forcing viscosity grade compression across both segments.
Growth Catalysts
- Fleet electrification mandates:EU Green Deal CO2 thresholds are accelerating hybrid powertrain deployment, creating demand for lower-viscosity lubricants that reduce mechanical friction losses in combined combustion-electric systems.
- REACH chemical registration:ECHA protocols are standardizing additive chemistries across Italian blenders, reducing formulation fragmentation and enabling economies of scale in detergent and dispersant procurement.
- Po Valley industrial corridor:Concentrated blending capacity around Ravenna and Milan is shortening finished lubricant distribution lead times to northern Italy's dense automotive service network.
Market Restraints
- Base oil supply concentration:Italian blenders remain dependent on Group II/III base stock imports from northwestern European refiners, exposing margins to feedstock volatility and marine freight rate swings.
- Full-electric substitution:Battery electric vehicle adoption in Italian urban centers is eliminating engine oil demand entirely from passenger car parc segments with the highest annual mileage accumulation.
- F-Gas Regulation constraints:EU benchmarks on fluorinated greenhouse gases are restricting certain viscosity-index improver chemistries, forcing reformulation cycles that extend R&D timelines.
Strategic Opportunities
- Central-southern service station penetration:Q8Oils and independent distributors are expanding automated quick-lube formats in Campania and Sicily, capturing underpenetrated individual motorist segments outside the northern industrial belt.
- Dielectric fluid development:Hybrid thermal management requirements are converging with battery cooling needs, opening formulation white space for lubricant houses with electrochemical compatibility expertise.
- Extended drain interval certification:ACEA C6 and API SP standards are creating premium positioning for synthetic products that command service bundling premiums from fleet maintenance contracts.
Industry Challenges
- Additive package integration complexity:Blenders must reconcile detergent, dispersant, and anti-wear chemistries across divergent OEM specifications from Fiat, Stellantis, and Volkswagen Group powertrain divisions.
- Drain interval calibration:Fleet operators demand predictive oil life algorithms that account for Italian stop-start urban driving cycles, requiring sensor integration and telemetry partnerships beyond traditional lubricant capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Semi-synthetic Oil, Additives Customer Type: Individual Consumers, Fleet Operators, Repair Shops, Auto Dealers Distribution Channel: Online Retail, Service Stations, Auto Parts Shops, Wholesalers Application: Engine Lubrication, Gearbox Lubrication, Brake Fluid, Hydraulic Fluids |
| Companies Covered | Q8Oils, ExxonMobil Corporation, BP PLC (Castrol), TotalEnergies, FUCHS, Eni SpA, Royal Dutch Shell Plc, Repsol, PETRONAS Lubricants International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry and distribution architecture are diverging as Italian lubricant suppliers respond to powertrain electrification and tightening emission protocols. Three developments are restructuring competitive positioning.
Low-viscosity SAE 0W-16 and 0W-20 synthetic base stocks are penetrating premium passenger car segments as OEMs pursue mechanical efficiency gains. Fiat and Stellantis powertrain engineering divisions are specifying these grades for new hybrid architectures. Conventional 5W-40 mineral formulations are rendering obsolete in factory-fill and warranty-maintenance channels for vehicles produced after 2024.
EU Green Deal mobility targets are tightening CO2 emission thresholds through 2035, indirectly mandating lubricant grade compression across the Italian parc. Italy's Ministry of Ecological Transition enforces these benchmarks through vehicle registration taxation and urban access restrictions. ACEA C-sequence compliance is becoming a mandatory procurement filter for fleet operators tendering public and corporate mobility contracts.
Service bundling is displacing standalone lubricant transactions as fleet maintenance contracts consolidate procurement decisions. Integrated vehicle health monitoring platforms are capturing oil change scheduling authority from individual motorists. Northern Italy's industrial corridor exhibits the most advanced concentration of this shift, with Milan-based fleet management companies negotiating direct blender relationships that bypass traditional distribution tiers.
Italy Passenger Vehicles Lubricants Market Segmentation
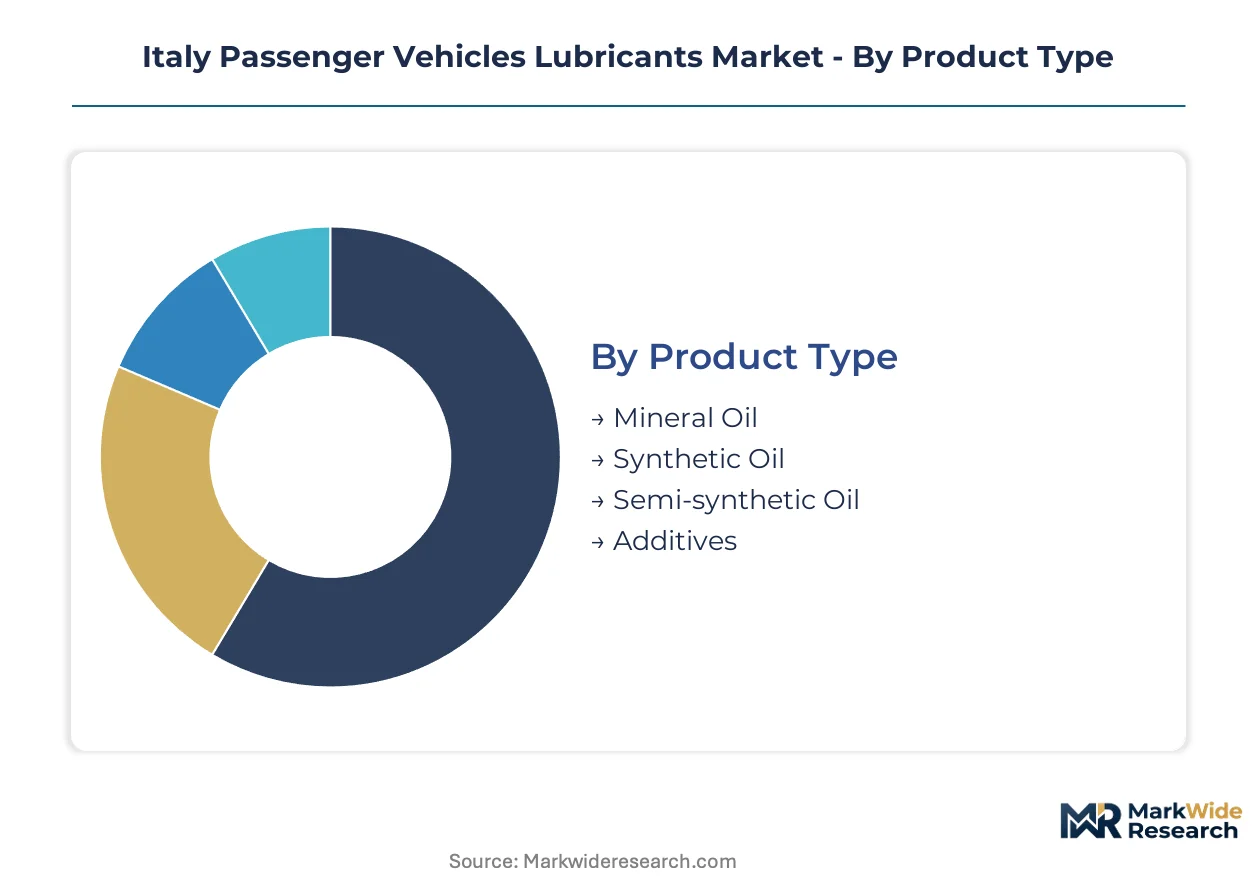
Segmentation in Italy's passenger vehicle lubricants market reveals divergent service intensity patterns across customer types and distribution channels. Fleet operators demand predictive maintenance integration, while individual motorists prioritize price accessibility and convenience proximity.
Product Type:
After-sales-service intensity varies sharply across lubricant formulations, with synthetic grades requiring technical consultation for drain interval optimization while mineral oils flow through high-volume, low-touch channels.
- Synthetic Oil:Formulated from Group III/IV base stocks with engineered additive packages delivering SAE 0W-16 to 0W-30 viscosity grades for hybrid powertrain compatibility. Demand concentrates among Milan and Turin fleet operators pursuing ACEA C6 certification for extended drain intervals under EU Green Deal emission benchmarks.
- Mineral Oil:Refined petroleum-derived base stocks with conventional additive treatment, dominant in SAE 5W-40 and 10W-40 grades for older vehicle parc. Volume leadership persists across Campania and Sicily service stations where price sensitivity dominates individual motorist procurement decisions.
- Semi-synthetic Oil:Blended formulation combining Group II base stocks with synthetic content for mid-tier performance positioning.
- Additives:Proprietary detergent, dispersant, and anti-wear chemical packages supplied by formulation houses to Italian blenders.
By volume, Mineral Oil leads. By growth pace, Synthetic Oil is expanding most quickly.
Customer Type:
Cost tier stratification separates enterprise procurement with negotiated blender direct relationships from fragmented individual transactions.
- Fleet Operators:Corporate and public mobility managers consolidating lubricant procurement through integrated maintenance contracts with predictive oil life monitoring. Procurement concentrates in the Po Valley industrial corridor where Stellantis and Volkswagen Group fleet volumes anchor blender direct agreements bypassing distribution tiers.
- Individual Consumers:Price-sensitive vehicle owners purchasing through service station quick-lube formats or auto parts retail, with minimal brand loyalty and high channel convenience weighting. Geographic dispersion across central-southern regions limits synthetic penetration due to lower hybrid vehicle adoption rates.
- Repair Shops:Independent mechanical service providers stocking mid-tier formulations for general service work.
- Auto Dealers:Authorized service centers executing warranty-maintenance with OEM-specified lubricant grades.
Fleet Operators capture the steepest expansion trajectory as service bundling displaces standalone transactions. Individual Consumers retain absolute volume dominance.
Distribution Channel:
Volume concentration follows the northern industrial corridor's dense automotive service network, with channel selection correlating to customer technical sophistication.
- Service Stations:Automated quick-lube formats with immediate availability of SAE 5W-30 and 5W-40 grades for drive-in consumers. Q8Oils anchors this channel through peninsula-wide retail presence, with highest throughput in Lombardy and Emilia-Romagna.
- Auto Parts Shops:Specialist retail supplying repair shops and knowledgeable enthusiasts with broader viscosity grade selection including low-viscosity synthetics. Northern Italy concentration mirrors hybrid powertrain penetration patterns.
- Online Retail:E-commerce platforms gaining traction for bulk synthetic purchases by cost-conscious fleet sub-segments.
- Wholesalers:Regional distributors serving independent repair networks with inventory financing and delivery logistics.
Service Stations lead by transaction volume. Online Retail is climbing the fastest as procurement digitization accelerates.
Application:
Application maturity diverges between saturated engine lubrication and emerging dielectric fluid requirements for hybrid thermal management.
- Engine Lubrication:Internal combustion and hybrid powertrain oils comprising SAE 0W-20 through 5W-40 grades with ACEA C-sequence compliance. Demand concentrates in northern Italy's hybrid vehicle corridor where Fiat and Stellantis powertrain specifications mandate synthetic formulations.
- Gearbox Lubrication:Manual and automatic transmission fluids with friction modification for dual-clutch architectures. Fleet operators in Turin and Bologna logistics hubs drive specification complexity as automated manual transmissions proliferate in light commercial units.
- Brake Fluid:DOT 3/4/5.1 glycol-ether and silicone formulations for hydraulic brake systems.
- Hydraulic Fluids:Power steering and suspension system lubricants with viscosity stability requirements.
Engine Lubrication dominates by volume. Gearbox Lubrication is gaining share fastest as transmission complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian lubricant blending capacity clusters along the Po Valley industrial corridor, with Ravenna and Milan anchoring supply-side concentration for northern Europe distribution. This geographic configuration shapes procurement patterns across the peninsula's heterogeneous automotive parc.
Lombardy
Milan's dense fleet operator base drives synthetic lubricant demand for hybrid powertrain servicing under EU Green Deal emission benchmarks. The Ministry of Ecological Transition enforces CO2 thresholds through vehicle registration taxation that favors lower-viscosity formulations. Stellantis fleet volumes in the Milan metropolitan area anchor direct blender agreements bypassing traditional distribution tiers.
Piedmont
Turin's automotive engineering heritage sustains specialized gearbox lubricant demand for automated manual transmissions in light commercial units. REACH chemical registration protocols standardize additive procurement across regional blenders. The Turin-Bologna logistics corridor concentrates fleet maintenance contracts with predictive oil life monitoring integration.
Emilia-Romagna
Bologna's position as a transport hub generates concentrated demand for extended-drain synthetic formulations among logistics fleet operators. F-Gas Regulation constraints on fluorinated greenhouse gases restrict certain viscosity-index improver chemistries, forcing reformulation cycles. Q8Oils anchors automated quick-lube formats with highest throughput in this region.
Campania
Naples and surrounding provinces exhibit price-sensitive mineral oil dominance through service station quick-lube channels serving individual motorists. Lower hybrid vehicle adoption rates limit synthetic penetration compared to northern regions. Independent distributors are expanding automated formats to capture underpenetrated consumer segments.
Sicily
Palermo and Catania service stations retain volume leadership in conventional SAE 5W-40 and 10W-40 grades for older vehicle parc. Geographic dispersion constrains supply chain efficiency, extending distribution lead times from northern blending centers. Price accessibility dominates procurement decisions among individual vehicle owners.
Italy Passenger Vehicles Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the formulation and additive supply chain. The Italian market exhibits consolidated blending capacity alongside fragmented distribution at the service station level. Three archetypes define competitive positioning: integrated oil majors with captive refining, independent blenders with regional distribution density, and additive formulation houses supplying proprietary packages. Capacity expansion in the Po Valley corridor and strategic partnerships for predictive maintenance telemetry represent dominant competitive vectors.
Among Italy-based integrated operators, Eni SpA and Q8Oils occupy positions spanning captive supply through retail distribution. ExxonMobil Corporation and BP PLC (Castrol) exemplify multinational majors competing on synthetic specialization and OEM partnership alignment. These players represent the spectrum from upstream-integrated to technology-licensed market participation archetypes.
| Leading Market Players |
|---|
| Q8Oils |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| TotalEnergies |
| FUCHS |
| Eni SpA |
| Royal Dutch Shell Plc |
| Repsol |
| PETRONAS Lubricants International |
| Others |
Supply & Pricing Matrix
Group II/III base stock import dependency from northwestern European refiners determines both the premium-to-economy pricing spread across synthetic and mineral grades and the concentration of blending capacity in Italy's Po Valley corridor. This single-source feedstock exposure compresses margins on low-viscosity formulations while amplifying price volatility transmission to fleet operators with extended-drain contracts.
Pricing Analysis
EU Green Deal emission benchmarks dictate the pricing tier structure across Italy's passenger vehicle lubricants market. ACEA C6 and API SP certification separates premium synthetic formulations from standard mineral grades, with price differentiation driven by additive package complexity and drain interval extension guarantees. Cost compression in the synthetic tier intensifies as Eni SpA and multinational majors expand Ravenna refinery output, while individual motorists in Campania and Sicily exhibit highest price sensitivity through service station procurement.
Supply Chain Analysis
Northwestern European refiners in the Netherlands, Germany, and Belgium hold captive capacity for Group II/III base stocks feeding Italian blenders. Formulation chemistry draws from detergent and dispersant additive packages sourced from specialized chemical houses, with viscosity-index improver supply resting on F-Gas Regulation compliance. Single-source vulnerability concentrates in marine freight corridors connecting Rotterdam to Ravenna, while distribution runs through Q8Oils' peninsula-wide service station network and independent auto parts channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across Italy's Po Valley corridor is shifting procurement authority from fragmented individual motorists toward centralized maintenance contracts with direct blender negotiation power.
For Market Incumbents: Harden synthetic formulation capabilities against full-electric substitution by accelerating dielectric fluid R&D for hybrid thermal management systems. Secure captive base oil supply through backward integration into Group III refining or long-term offtake agreements with northwestern European suppliers. Channel control through predictive maintenance telemetry partnerships with Milan-based fleet management companies defends margin position against price-transparent e-commerce penetration. For New Entrants and Emerging Players: Central-southern automated quick-lube formats in Campania and Sicily represent the most penetrable entry point for mineral-grade volume capture outside Eni SpA and Q8Oils distribution dominance. Mid-tier semi-synthetic positioning for repair shops seeking ACEA C3 compliance without premium synthetic pricing offers secondary wedge. Direct-to-fleet digital procurement platforms bypassing traditional wholesale tiers provide the strongest go-to-market angle for technology-native entrants. For Investors and Strategic Acquirers: EU Green Deal 2035 CO2 phase-out mandates reshape the acquisition landscape toward electrochemical compatibility capabilities and hybrid powertrain fluid portfolios. Long-term viability centers on blenders with formulation expertise spanning friction-reduction chemistry and dielectric thermal management, positioned across the 5-10 year electrification transition. Vertically integrated operators with captive base oil supply and predictive maintenance platform partnerships signal durable competitive positioning. Battery electric vehicle penetration rates in Italian urban centers serve as the critical inflection indicator for engine oil demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Dielectric Fluid Development | Hybrid thermal management convergence with battery cooling opens formulation white space for electrochemical specialists. |
| Backward Integration into Base Oil | Captive Group III supply from Ravenna refinery expansion insulates Eni SpA from northwestern European feedstock volatility. |
| Predictive Maintenance Telemetry | Sensor-integrated oil life algorithms secure fleet contract bundling authority from traditional distribution tiers. |
| Central-Southern Quick-Lube Expansion | Automated formats in Campania and Sicily capture underpenetrated individual motorist segments outside northern industrial concentration. |
| ACEA C6 Certification Investment | Extended drain interval compliance commands service bundling premiums from Po Valley fleet maintenance contracts. |
Research Methodology
Cross-validation between primary interviews with lubricant blenders, fleet procurement managers, and aftermarket distributors anchors the qualitative findings against secondary trade data and regulatory filings. Plant managers at Po Valley blending facilities, OEM technical specification engineers, and service station network operators provided operational perspective. Bottom-up volume modeling triangulates with top-down macroeconomic indicators and vehicle parc projections.
Calibration against historical elasticity patterns and segment-specific adoption curves shapes the analytical framework across the projection horizon. Propulsion architecture segmentation—spanning internal combustion, hybrid, and battery electric—combines with viscosity grade tier and customer type dimensions. CAGRs derive from regression analysis of fleet electrification mandates, REACH chemical registration compliance costs, and hybrid powertrain penetration trajectories.
Practitioners should monitor battery electric vehicle adoption rates in Milan and Turin metropolitan areas for early signals of engine oil demand inflection. Forecasts reflect assumptions on EU Green Deal enforcement timing and additive chemistry reformulation cycles under F-Gas Regulation constraints. Quarterly review of fleet operator procurement contract structures and hybrid vehicle registration data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Car Rack Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
North America Automotive Airfilters Market