
 North America Automotive Parts Aluminum Die Casting Market | 2026-2036
North America Automotive Parts Aluminum Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Parts Aluminum Die Casting Market Analytics
OEM supply contracts for aluminum die cast powertrain components is tilting toward suppliers with captive melting and machining capacity. Nemak leverages vertical integration across its Mexican and US plants to secure long-term transmission housing contracts. Pace Industries sustains geographic dominance through its southeastern US foundry network. Martinrea International Inc. specializes in structural die castings for electric vehicle platforms, differentiating its portfolio from traditional internal-combustion suppliers.
Automotive parts aluminum die casting is a metal-forming process wherein molten aluminum alloys are injected under high pressure into hardened steel molds to produce near-net-shape components with wall thicknesses typically below 3 millimeters. The process yields parts with excellent dimensional repeatability and surface finish, serving primarily to reduce vehicle mass while maintaining structural integrity under mechanical and thermal loads. High-pressure die casting occupies the largest share of production volume, though vacuum die casting is gaining share where porosity-sensitive structural applications require weldability and heat-treatable properties. Engine blocks remain a mature, high-volume category with consolidated supply, while structural components for battery enclosures and motor housings represent the fastest-expanding margin pool as OEM electrification programs scale.
NHTSA fuel-economy standards and EPA tailpipe emissions rules directly shape aluminum content targets in vehicle design cycles, pushing OEMs toward lighter powertrain and chassis architectures. EPA enforcement of corporate average fuel economy benchmarks and state-level zero-emission vehicle mandates in California and Quebec create dual regulatory pressures that cascade into die casting procurement specifications. Stakeholders must monitor how NHTSA rulemakings on fleet-wide efficiency targets interact with shifting OEM platform strategies to anticipate capacity allocation decisions across the supplier base.
Market Dynamics
OEM electrification roadmaps are compressing die casting contract cycles as battery enclosure and motor housing specifications outpace traditional powertrain tooling refresh rates. High-pressure die casting capacity in Michigan and Ontario faces reallocation pressure toward structural EV components.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:Stringent fleet-wide efficiency benchmarks force aluminum substitution in chassis and powertrain assemblies. Die cast transmission housings and engine blocks absorb incremental regulatory load.
- Quebec zero-emission vehicle mandates:Provincial sales quotas accelerate OEM platform electrification. Battery tray and motor housing die casting contracts expand to meet localized compliance requirements.
- High-pressure die casting process maturation:Vacuum-assisted variants enable heat-treatable structural grades. Porosity reduction unlocks weldability for crash-critical EV battery enclosures.
Market Restraints
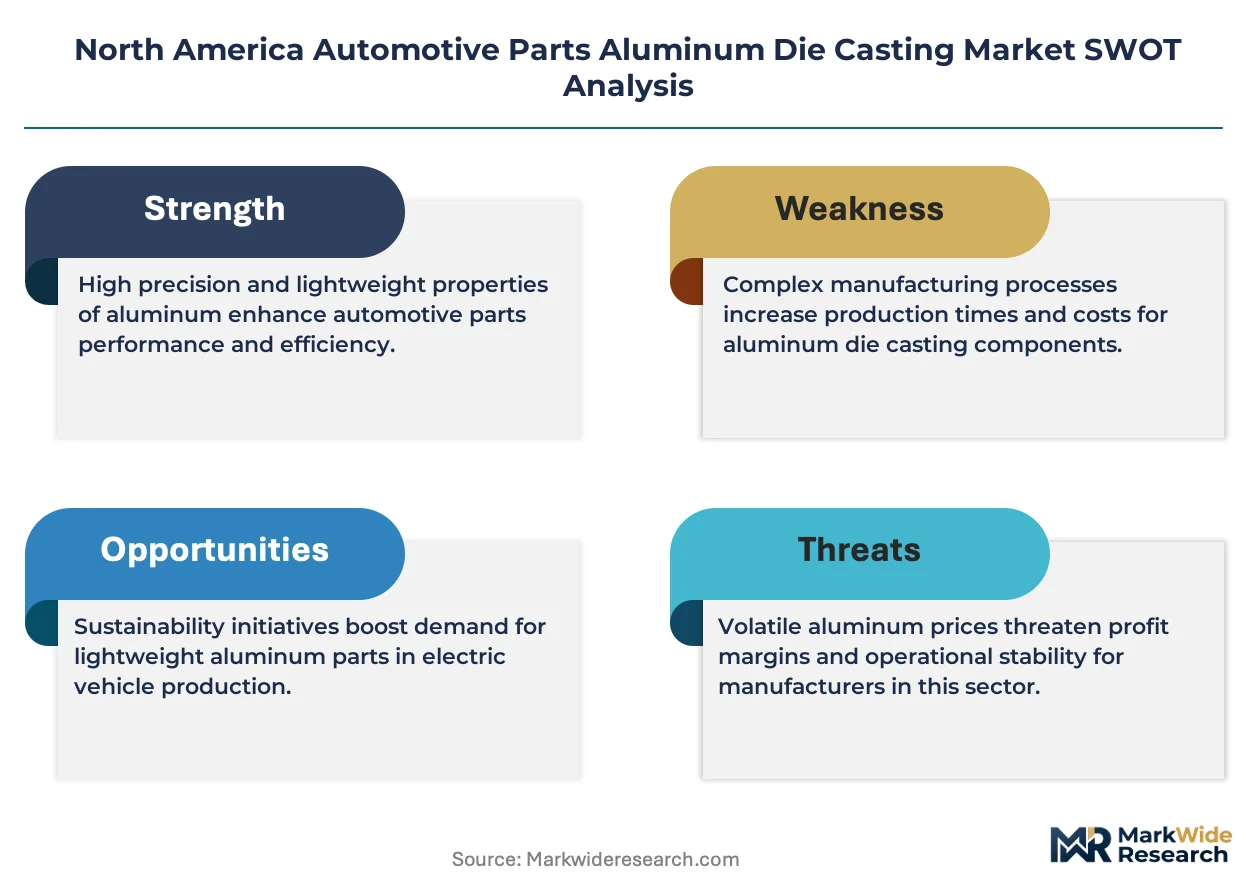
- Primary aluminum price volatility:LME aluminum price swings compress foundry margin buffers. Smaller independent casters lack hedging infrastructure to absorb input cost spikes.
- Tooling lead time concentration:Hardened steel mold fabrication capacity clusters in Ontario and Michigan. Die manufacturing bottlenecks extend new program launch timelines.
- Magnesium substitution threat:Thixomolding advances for seat frames and steering columns displace aluminum in select interior structural applications.
Strategic Opportunities
- Mexico nearshoring corridor expansion:OEM assembly capacity growth in Guanajuato and Nuevo León creates captive die casting demand. Suppliers with Monterrey-Saltillo logistics networks capture incremental transmission housing volume.
- Integrated battery enclosure die casting:Single-piece aluminum tray designs replace multi-component steel assemblies. Thermal management channel integration reduces downstream welding operations.
- US Inflation Reduction Act domestic content credits:Battery component assembly incentives favor North American-sourced aluminum castings. OEM procurement teams prioritize USMCA-qualified suppliers for IRA-compliant platforms.
Industry Challenges
- Process technician scarcity:High-pressure die casting machine operation and die maintenance skills concentrate among aging workforce cohorts. Technical training pipeline gaps constrain foundry expansion timelines.
- Heat treatment furnace capex intensity:T7 tempering capacity for structural EV grades requires multimillion-dollar continuous furnace investments. Mid-tier suppliers face balance sheet constraints for qualification-grade equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Parts Aluminum Die Casting Market |
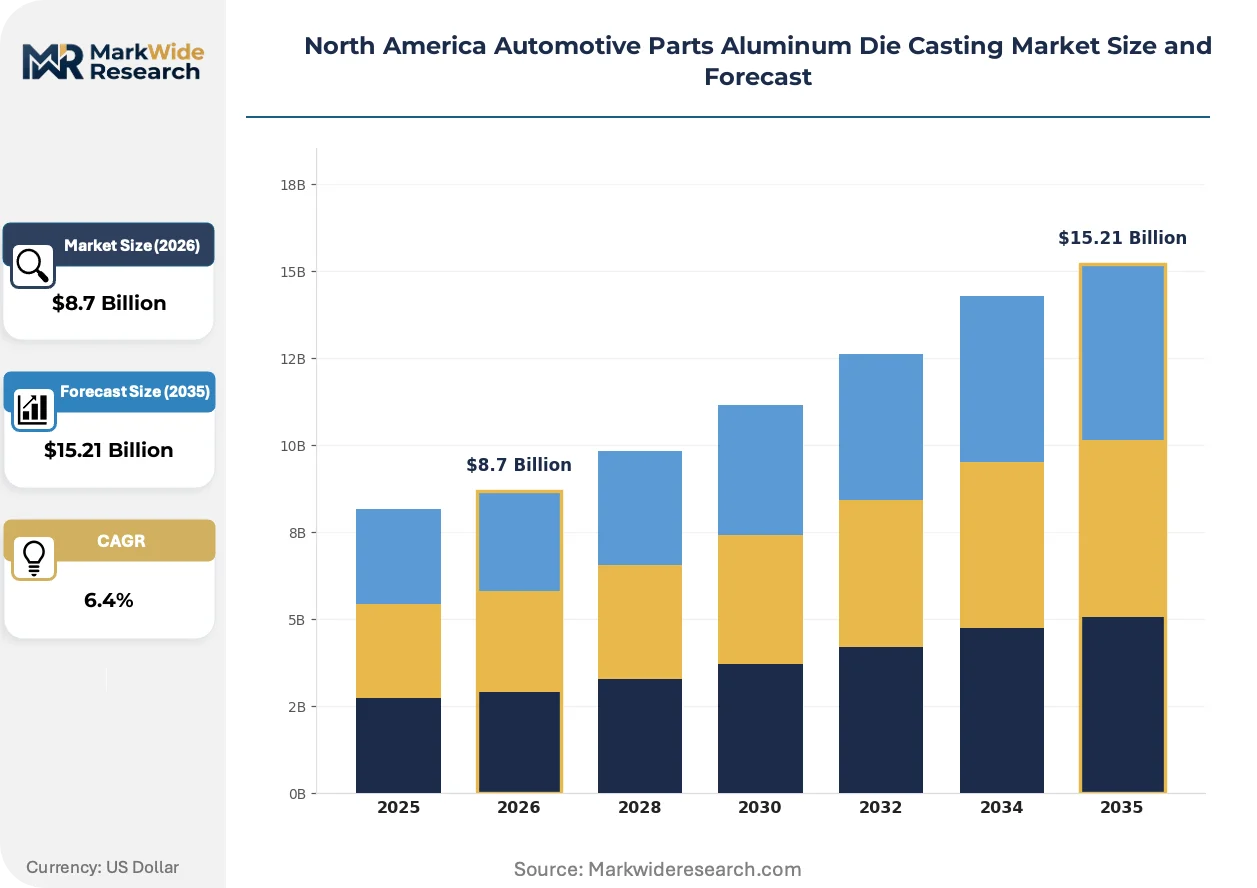
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Blocks, Transmission Housings, Structural Components, Suspension Parts End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting Material Grade: Aluminum 356, Aluminum 319, Aluminum 413, Aluminum 6061 |
| Companies Covered | Amtek Group, Nemak, Pace Industries, Martinrea International Inc., Linamar Corporation, Kemlows Diecasting Products Ltd, Dynacast Inc., Aludyne Inc., Samkee Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Parts Aluminum Die Casting Market Evolving Landscape
Digital twin deployment is compressing die design validation cycles while real-time porosity monitoring reshapes quality assurance protocols. These shifts intersect with regulatory tightening and OEM platform consolidation.
Virtual die tryout software is virtualizing physical prototyping stages in complex multi-slide tooling programs. Tier-1 suppliers deploy simulation-to-production workflows for transmission housings with integrated cooling galleries. This compression eliminates two to three physical iteration cycles, collapsing program development timelines from concept to PPAP approval.
NHTSA fuel-economy enforcement actions are accelerating aluminum content negotiations in light-truck platform redesigns. The agency's 2024-2026 model year compliance scrutiny forces OEM engineering teams to revisit casting alloy specifications. Full-size pickup programs now specify A380 variants with silicon content optimization for as-cast strength-to-weight ratios.
Long-term capacity reservation contracts are displacing spot procurement for strategic die casting programs. OEM supply chain teams lock Michigan and Ontario foundry output three to five years forward for battery enclosure platforms. This shift concentrates volume with vertically integrated suppliers capable of captive melting and machining commitments.
North America Automotive Parts Aluminum Die Casting Market Segmentation
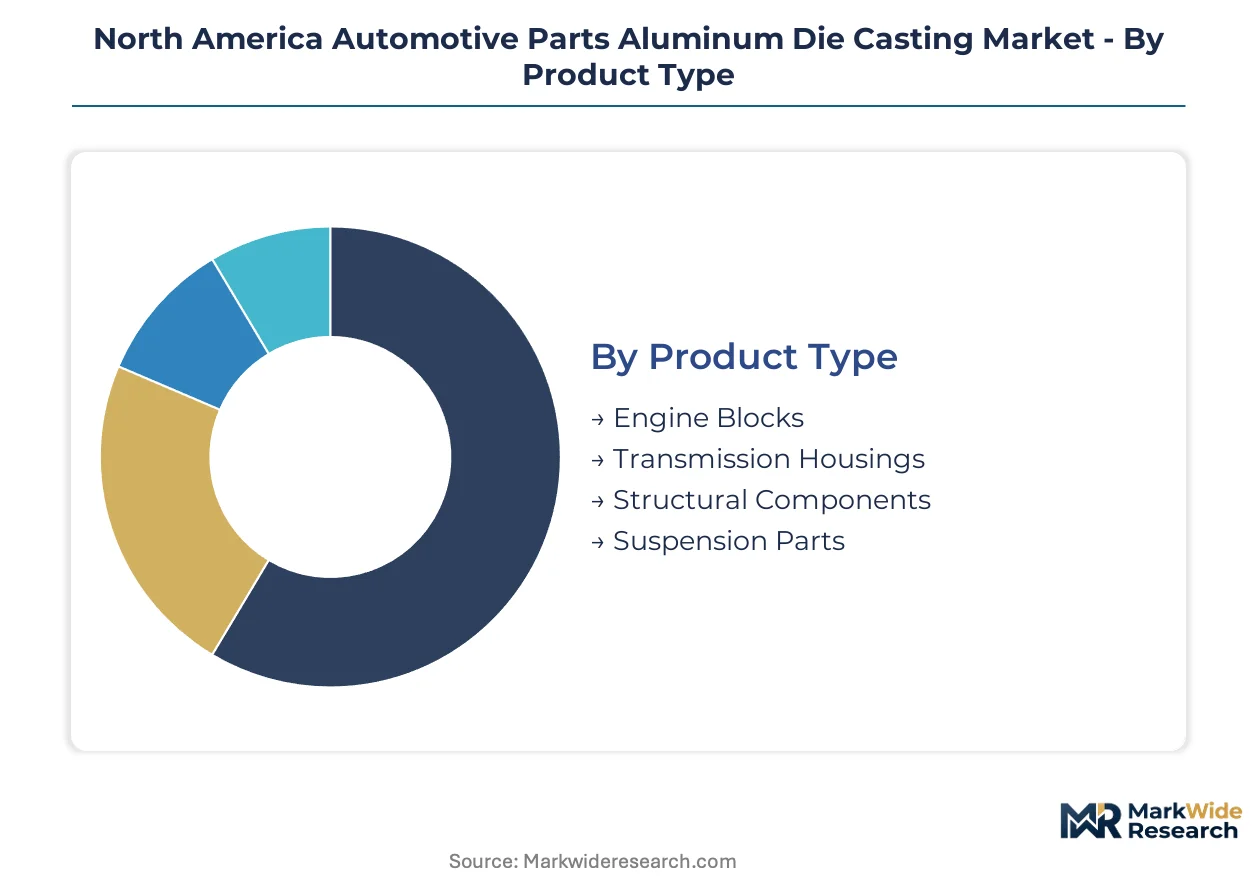
Segmentation in North American automotive aluminum die casting reveals how regulatory pressure and electrification reshape procurement priorities across product categories. OEM sourcing strategies diverge sharply between mature powertrain applications and emerging EV structural programs.
Product Type:
Powertrain and chassis applications span divergent maturity curves, with electrification redrawing the margin landscape.
- Engine Blocks:High-pressure die casting of A380 and 319 alloys delivers cylinder block assemblies with integrated coolant jackets. EPA fuel-economy mandates sustain demand in Michigan and Ontario light-truck platforms, though ICE volume plateaus constrain foundry expansion.
- Transmission Housings:Complex multi-slide tooling produces clutch and gearbox enclosures with internal oil galleries. Guanajuato assembly plant proximity drives Mexican supply corridor concentration for automatic transmission programs.
- Structural Components:Battery trays and motor housings require vacuum-assisted porosity control for weldability.
- Suspension Parts:Control arms and knuckles utilize squeeze-cast variants for fatigue resistance.
Established volume favors Engine Blocks; emerging adoption favors Structural Components.
End User:
Customer concentration shapes contract structures, with captive capacity locking in multi-year procurement cycles.
- OEMs:Ford, General Motors, and Stellantis operate captive die casting facilities for proprietary powertrain architectures. In-house transmission housing production at Detroit-Hamtramck and Windsor secures supply continuity for high-volume truck platforms.
- Tier-1 Suppliers:Magna, Lear, and Dana source aluminum castings for integrated module assembly. Long-term capacity reservation contracts with Ontario foundries lock three-to-five-year output for battery enclosure platforms.
- Aftermarket Suppliers:Remanufactured engine block demand concentrates in independent rebuild channels.
- Vehicle Assemblers:EV-native manufacturers without casting heritage rely entirely on external supply.
Procurement consolidation favors Tier-1 Suppliers; margin pressure concentrates on Aftermarket Suppliers.
Technology:
Process selection hinges on wall thickness requirements and porosity tolerance thresholds.
- High-Pressure Die Casting:Molten aluminum injection at 1,000-1,500 bar produces thin-walled transmission housings with cycle times under 90 seconds. Michigan and Ontario manufacturing corridors host concentrated capacity for this dominant process.
- Vacuum Die Casting:Evacuated die cavities eliminate gas entrapment, enabling T7 heat treatment for structural EV grades. Quebec battery enclosure programs specify vacuum-assisted production for crash-critical weldability.
- Low-Pressure Die Casting:Controlled fill rates suit thick-section engine blocks requiring minimal porosity.
- Gravity Die Casting:Slower fill dynamics serve low-volume suspension components with complex coring.
Process maturation favors High-Pressure Die Casting; technology substitution favors Vacuum Die Casting.
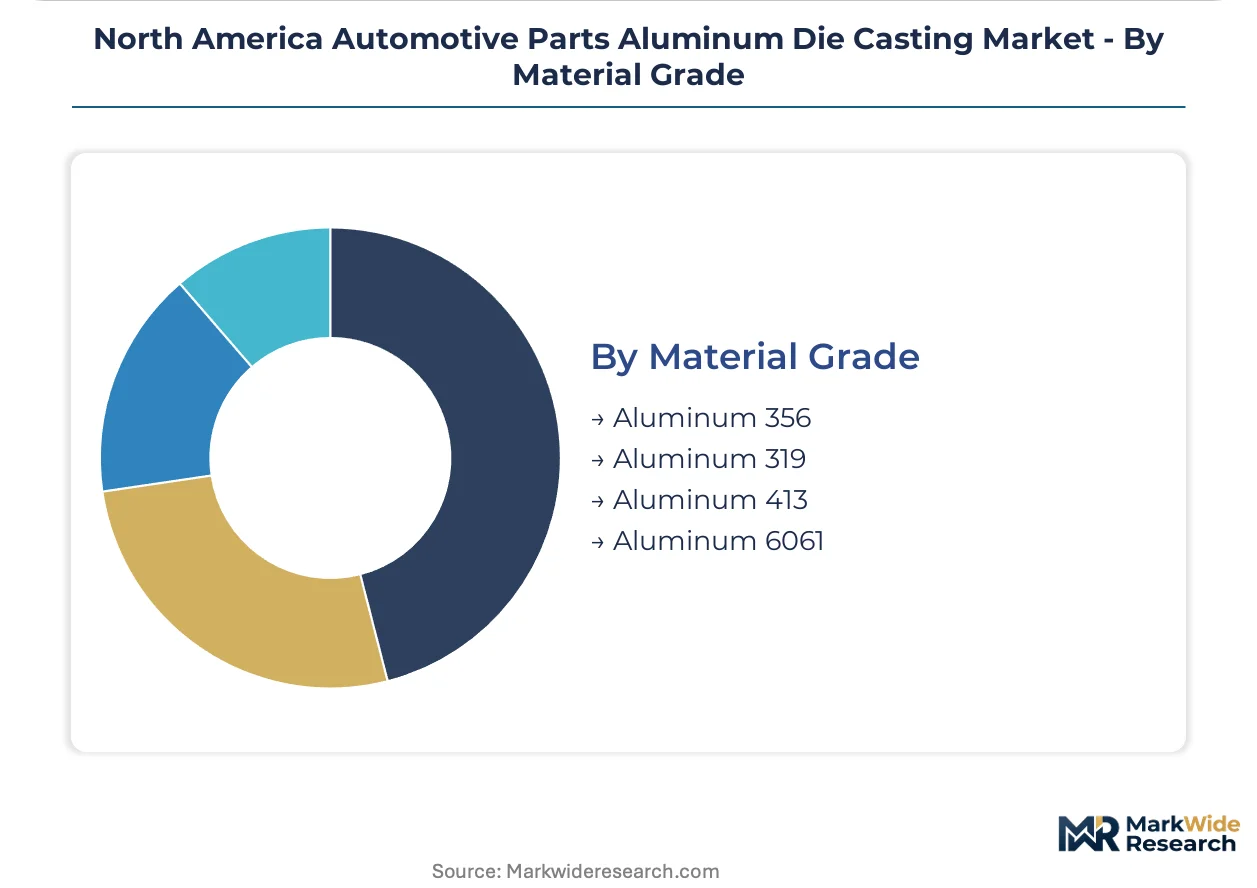
Material Grade:
Alloy specification balances castability against post-cast mechanical performance requirements.
- Aluminum 319:Copper-bearing composition delivers as-cast strength for transmission housings without heat treatment. Ontario foundries favor 319 for cost-sensitive high-volume programs where T7 tempering capex is prohibitive.
- Aluminum 356:Magnesium-silicon system responds to T6 tempering with elongation properties critical for battery tray crash performance. Michigan EV structural programs specify 356-T6 for single-piece enclosure designs.
- Aluminum 413:High silicon content improves fluidity in thin-wall sections.
- Aluminum 6061:Wrought-grade extrusion stock competes in hybrid casting-forging applications.
Cost efficiency favors Aluminum 319; performance specification favors Aluminum 356.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Michigan and Ontario manufacturing corridors while Mexican border states compete on assembly proximity. Die casting contract values diverge sharply between high-specification structural EV programs and mature powertrain volume. Regulatory enforcement intensity across EPA regions and provincial mandates reshapes capacity allocation decisions.
United States
Michigan-based OEM captive foundries dominate transmission housing production for Detroit Three truck platforms. EPA Corporate Average Fuel Economy enforcement actions accelerate aluminum content negotiations for light-duty fleet compliance. Southeast US assembly plant expansion in Tennessee and South Carolina pulls die casting investment toward regional supplier networks.
Canada
Ontario's Windsor-Toronto corridor hosts concentrated high-pressure die casting capacity serving cross-border automotive supply chains. Quebec zero-emission vehicle mandates drive battery enclosure specification demand with localized procurement requirements. Federal clean technology investment tax credits support T7 heat treatment furnace installations for structural EV grades.
Mexico
Guanajuato and Nuevo León assembly plant growth creates captive demand for automatic transmission housing supply. USMCA domestic content rules favor North American-sourced aluminum castings for IRA-compliant battery platforms. Monterrey-Saltillo logistics networks capture incremental volume from OEMs seeking tariff-advantaged supply chain configurations.
North America Automotive Parts Aluminum Die Casting Market Competitive Landscape
Vertically integrated specialists and regional foundry networks split the market between long-term contract security and spot volume flexibility. Consolidation pressure intensifies as OEM electrification programs demand captive melting and machining commitments. Three archetypes dominate: Mexican-North American corridor operators with assembly proximity, Great Lakes manufacturers with OEM captive relationships, and structural EV specialists with vacuum die casting qualification. Capacity reservation contracts and heat treatment furnace investments represent the dominant competitive moves reshaping supplier positioning.
Among North American die casting specialists, Nemak, Pace Industries, and Martinrea International Inc. exemplify divergent strategic positioning. The first represents Mexican-North American corridor integration with multi-plant melting and machining networks. The second anchors southeastern US foundry concentration serving regional assembly demand. The third occupies structural die casting specialization for electric vehicle platform architectures, differentiating from traditional internal-combustion supply bases. Each archetype captures distinct contract structures as OEM procurement teams segment suppliers by process capability and geographic coverage requirements.
| Leading Market Players |
|---|
| Amtek Group |
| Nemak |
| Pace Industries |
| Martinrea International Inc. |
| Linamar Corporation |
| Kemlows Diecasting Products Ltd |
| Dynacast Inc. |
| Aludyne Inc. |
| Samkee Automotive |
| Others |
Value Network & Pricing Analysis
LME aluminum smelter concentration in Canada and the US Gulf Coast feeds directly into margin distribution across the North American die casting tier. Foundries with captive melting capacity capture premium spreads on heat-treatable structural grades, while independent casters absorb volatility through indexed raw material pass-through clauses.
Pricing Analysis
Configured-to-order vacuum die cast battery enclosures command substantial premiums over standard high-pressure transmission housings. Pricing stratifies across premium, standard, and economy tiers based on porosity certification levels and T7 tempering capability. Cost compression in standard-grade engine blocks is intensifying because OEMs consolidate volume with vertically integrated suppliers. Tier-1 module assemblers exhibit highest price sensitivity, whereas EV-native OEMs prioritize performance specification over unit economics.
Supply Chain Analysis
Extended payment terms from Detroit Three OEMs now stretch to 90-120 days, forcing supply-chain finance facilities among mid-tier Ontario foundries. Primary aluminum draws from Canadian smelters, US secondary recyclers, and Mexican remelt operations. Single-source vulnerability concentrates in hardened steel mold fabrication capacity clustered around Windsor and Detroit. Distribution runs through Tier-1 module assembly plants co-located with OEM vehicle assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American automotive aluminum die casting sits in early-cycle expansion as EV platform electrification penetrates light-truck and SUV segments previously dominated by iron powertrain castings.
For Market Incumbents: Insulate core transmission housing margins through backward integration into aluminum melting and machining capacity. Lock long-term capacity reservation contracts with Detroit Three OEMs before EV-native competitors qualify alternative structural suppliers. Magnesium thixomolding substitution in interior applications threatens peripheral revenue streams.
For New Entrants and Emerging Players: Build out vacuum die casting qualification for single-piece battery tray architectures where incumbent high-pressure specialists lack heat-treatment furnace infrastructure. Quebec battery enclosure programs offer the most penetrable entry point given localized zero-emission vehicle mandates. Pursue direct qualification with EV-native OEMs lacking captive casting heritage.
For Investors and Strategic Acquirers: Capital is best deployed toward structural EV specialists with vacuum-assisted process capability and T7 tempering infrastructure. The five-to-ten year viability window favors suppliers with demonstrated weldability qualification for crash-critical battery enclosures. Watch NHTSA fuel-economy enforcement intensity as the inflection signal for accelerated aluminum content negotiations in light-truck platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Die Casting Qualification | T7 heat-treatable structural grades unlock crash-critical EV battery enclosure contracts from Ford and GM. |
| Captive Melting Capacity Expansion | In-house aluminum remelt operations hedge LME price volatility and secure USMCA domestic content credits. |
| Monterrey-Saltillo Logistics Network | Proximity to Guanajuato assembly plants captures tariff-advantaged transmission housing volume for Stellantis programs. |
| Digital Twin Deployment | Virtual die tryout software collapses program development timelines from concept to PPAP approval by eliminating physical iterations. |
| Process Technician Training Pipeline | Technical apprenticeship programs address aging workforce scarcity constraining high-pressure machine operation capacity. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, foundry operations managers, and heat treatment furnace OEMs provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against vehicle production databases, IHS Markit registration data, EPA fuel-economy compliance filings, and USMCA trade flow records. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions.
Scenario-bracketing framed low, base, and high cases across the projection horizon without fixed-year anchoring. Segmentation dimensions modeled include propulsion architecture, component structural criticality, process technology tier, and regional production cluster. CAGRs derived from regression analysis of historical capacity utilization against OEM platform launch schedules, with EV content-per-vehicle trajectories and EPA regulatory stringency indices as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese die casting specialists or sudden NHTSA rulemaking acceleration would shift outcomes. Macroeconomic aluminum price spikes, Quebec zero-emission vehicle mandate tightening, or breakthrough magnesium alloy substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Struts System Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Global Automotive Stampings Market
Automotive Parts
Automotive Grease Market
Automotive Parts
VVT Actuators Market