
 Philippines Passenger Vehicles Lubricants Market | 2026-2036
Philippines Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Passenger Vehicles Lubricants Market Analytics
API SP certification is rotating as the baseline qualification for suppliers seeking access to modern gasoline engine portfolios in the Philippines. Royal Dutch Shell Plc leverages its integrated refining and blending infrastructure to sustain supply continuity across the archipelago. Petron Corporation anchors its position through domestic manufacturing scale at its Bataan refinery complex. Phoenix Petroleum Philippines Inc. competes via aggressive channel expansion into provincial retail networks.
Philippines passenger vehicles lubricants are formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with synthetic formulations typically offering viscosity grades such as 0W-20 or 5W-30 for tropical operating conditions. These products serve the essential commercial purpose of extending engine life and maintaining fuel efficiency across high-temperature, stop-and-go driving environments prevalent in Philippine urban corridors. Engine oil commands the dominant volume position among product types due to mandatory drain intervals tied to OEM warranty requirements, while synthetic formulations capture expanding share as Japanese and Korean automakers specify lower-viscosity grades for newer powertrains. The aftermarket provider channel concentrates margin pools through bulk supply agreements with independent service workshops, though fleet operators represent the fastest-growing end-user segment as ride-hailing and logistics platforms professionalize maintenance schedules.
The Department of Energy enforces fuel and lubricant quality standards that mandate minimum performance specifications for products sold in the Philippine market, while the Bureau of Product Standards operates certification schemes that gate market access for imported and domestically blended lubricants. BIS-aligned testing protocols for viscosity stability and oxidation resistance are shaping reformulation investments among blenders serving the OEM channel. Stakeholders must monitor how the Land Transportation Office's vehicle inspection modernization could tighten documentation requirements for lubricant change intervals in commercial fleets.
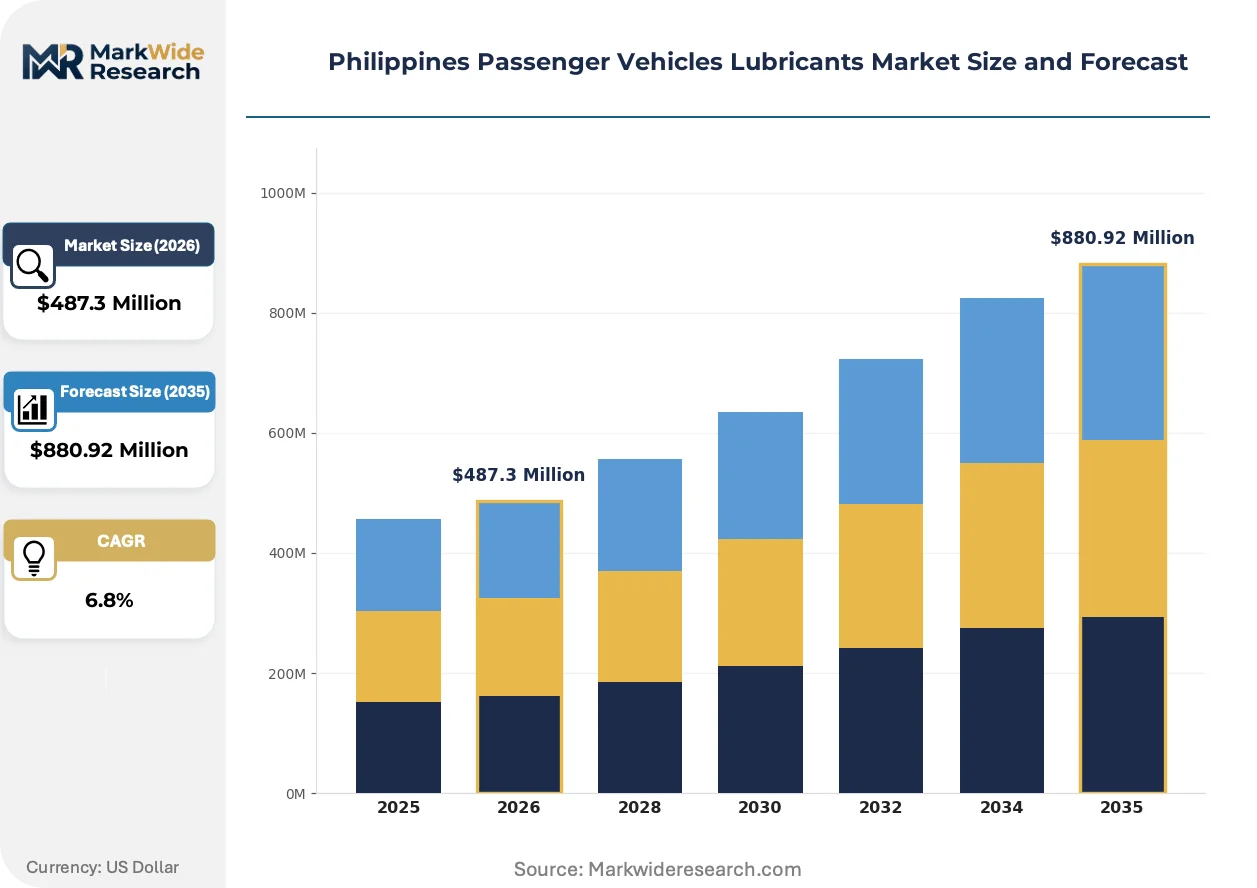
Market Dynamics
API SP certification mandates from Japanese and Korean automakers are compressing formulation cycles across Philippine blending facilities, forcing domestic producers to accelerate base stock upgrades or surrender OEM fill contracts to integrated multinationals.
Growth Catalysts
- DOE Fuel Quality Regulations:The Department of Energy's escalating performance specifications for lubricant oxidation stability and deposit control are pulling demand toward higher-tier synthetic formulations that command premium positioning in service workshops.
- Fleet Operator Professionalization:Ride-hailing platforms and last-mile logistics providers operating across Metro Manila and Cebu are institutionalizing preventive maintenance schedules that shorten drain intervals and expand bulk lubricant procurement volumes.
- Tropical Viscosity Grades:0W-20 and 5W-30 specifications optimized for high-temperature, high-humidity operating conditions are capturing expanded share as newer powertrains from Toyota, Honda, and Hyundai enter the Philippine parc.
Market Restraints
- Group II/III Base Oil Import Dependency:Philippine blenders lack domestic catalytic hydrocracking capacity, forcing reliance on Singapore and South Korean refiners for high-quality base stocks that face freight cost volatility and currency fluctuation exposure.
- Bataan Refinery Concentration:Petron Corporation's integrated refining complex processes the majority of domestic base oil supply, creating single-point vulnerability for national lubricant production continuity during turnaround maintenance or unplanned outages.
- Extended OEM Drain Intervals:Synthetic formulations with 10,000-kilometer service life are displacing conventional 5,000-kilometer products, structurally compressing lubricant consumption per vehicle despite parc expansion.
Strategic Opportunities
- Mindanao Service Network Gap:Davao and Cagayan de Oro corridors remain underserved by branded lubricant distribution, presenting first-mover potential for channel partners establishing bulk supply relationships with emerging fleet operators in southern logistics hubs.
- BIS Certification Alignment:Bureau of Product Standards harmonization with ISO viscosity classification and oxidation testing protocols creates pathway for Philippine blenders to access ASEAN regional supply contracts previously gated by certification mismatches.
- E-Commerce Channel Integration:Direct-to-workshop digital procurement platforms are bypassing traditional distributor tiers, enabling lubricant marketers to capture margin pools previously allocated to provincial stockists in Luzon and Visayas corridors.
Industry Challenges
- Additive Package Sourcing Complexity:Lubrizol, Infineum, and Afton supply agreements require minimum volume commitments that strain mid-scale Philippine blenders attempting to serve fragmented provincial workshop segments with irregular offtake patterns.
- API SP Testing Infrastructure:Domestic laboratories lack sequence IIIH and LSPI test capability, forcing blenders to ship samples to Singapore or Thailand for certification, extending new product introduction timelines by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Oil, Grease Formulation: Synthetic, Conventional, Semi-Synthetic, Biodegradable Application: Passenger Cars, SUVs, Light Trucks, Motorcycles End User: OEMs, Aftermarket Providers, Retail Consumers, Fleet Operators |
| Companies Covered | BP Plc (Castrol), Royal Dutch Shell Plc, Chevron Corporation, TotalEnergies, Petron Corporation, Phoenix Petroleum Philippines Inc., PTT Lubricants, Unioil Petroleum Philippines Inc., Valvoline Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Passenger Vehicles Lubricants Market Evolving Landscape
Synthetic formulation chemistry and digital distribution infrastructure are converging to compress traditional supply tiers while elevating performance certification requirements across the Philippine aftermarket.
Group III+ base oils synthesized through severe hydrocracking and isodewaxing are decomposing the historical premium attached to polyalphaolefin formulations in tropical passenger car applications. Independent service workshops in Quezon City and Makati are specifying these hydroprocessed mineral bases for 0W-20 and 5W-30 drain intervals at 15-20% cost reduction versus full synthetics. The price-performance repositioning is forcing lubricant marketers to defend margin through additive differentiation rather than base stock origin claims.
Department of Energy circulars mandating deposit control and fuel economy retention testing are accelerating reformulation investments among Bataan-based blenders serving the OEM channel. The regulatory pressure compresses product lifecycle management cycles from 36 months toward 18-month refresh intervals. Domestic manufacturers lacking in-house tribology laboratories are outsourcing validation to third-party facilities in Singapore, extending time-to-market for new viscosity grades.
Workshop procurement through B2B platforms aggregating inventory across multiple lubricant brands is displacing exclusive distributor relationships in Metro Manila's dense service center corridors. Fleet maintenance managers at Grab and Angkas partner workshops are consolidating supplier interfaces through these digital intermediaries, capturing volume discounts previously available only to national account holders. The channel shift concentrates purchasing influence among platform operators rather than traditional provincial stockists.
Philippines Passenger Vehicles Lubricants Market Segmentation
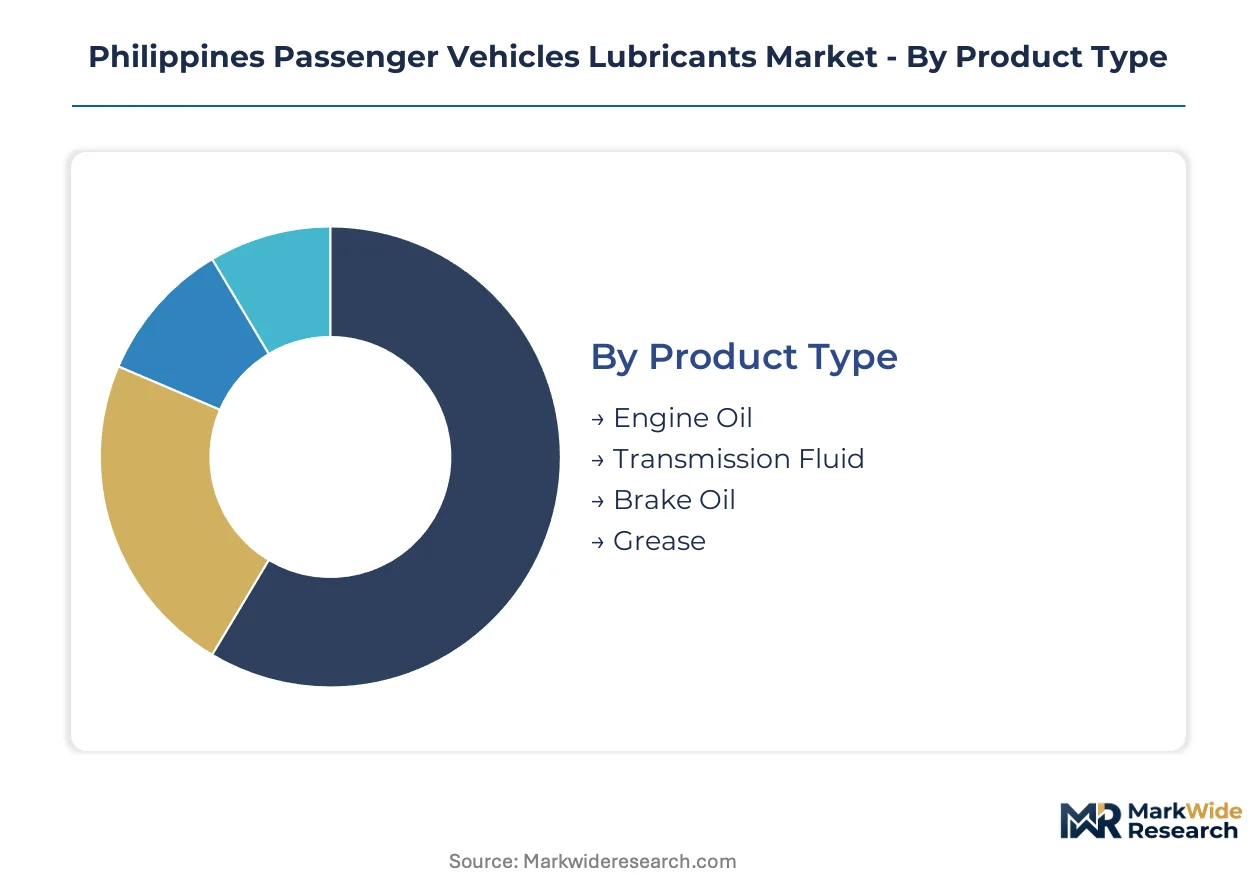
Segmentation in the Philippine passenger vehicle lubricants market reveals how reformulation pressures and channel shifts are redistributing value across product tiers. Understanding where substitution threats concentrate helps suppliers prioritize certification investments and distribution partnerships.
Product Type:
Engine Oil faces the most intense substitution pressure as extended drain intervals and synthetic formulations compress unit consumption per vehicle, forcing blenders to defend position through additive differentiation rather than volume scale.
- Engine Oil:Formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines. Demand concentrates in Metro Manila's dense service center network where fleet operators professionalize maintenance schedules and shorten replacement cycles despite longer synthetic service life.
- Transmission Fluid:Specialized lubricants engineered for gear protection and thermal stability across automatic and continuously variable transmissions. Adoption is accelerating in Cebu and Davao corridors as Japanese OEMs expand CVT-equipped model distribution into provincial markets.
- Brake Oil:Hydraulic fluids meeting DOT 3 and DOT 4 specifications for brake system operation. Replacement follows collision repair and preventive maintenance protocols in independent workshops.
- Grease:Semi-solid lubricants for chassis and bearing applications. Demand tracks commercial vehicle utilization rates in logistics corridors.
Engine Oil retains volume leadership; Transmission Fluid holds the steepest expansion curve.
Formulation:
Cost tier stratification across base stock grades determines margin capture, with Group III+ hydroprocessed mineral oils eroding traditional synthetic premiums through price-performance repositioning.
- Synthetic:Formulations utilizing polyalphaolefin or severe hydrocracked base stocks delivering 0W-20 and 5W-30 viscosity grades. OEM fill contracts with Toyota, Honda, and Hyundai anchor demand in Luzon assembly and import channels.
- Conventional:Mineral-based lubricants refined from solvent-extracted base stocks. Price-sensitive independent workshops in provincial Visayas and Mindanao corridors sustain procurement volumes despite specification upgrades in Metro Manila.
- Semi-Synthetic:Blends combining Group I/II mineral bases with synthetic content. Positioned as intermediate tier for vehicle owners exiting warranty periods.
- Biodegradable:Environmentally formulated lubricants meeting biodegradability thresholds for sensitive operating environments. Niche adoption in ecotourism fleet applications.
Synthetic formulations command premium positioning; Semi-Synthetic blends are climbing fastest as warranty expirations expand the addressable base.
Application:
Vehicle parc composition across Luzon, Visayas, and Mindanao shapes viscosity grade requirements, with tropical climate conditions favoring lower-weight formulations regardless of vehicle category.
- Passenger Cars:Sedan and hatchback lubricant demand driven by Japanese OEM service specifications. 0W-20 grades specified for newer powertrains are displacing 5W-30 in Metro Manila fleet renewals.
- SUVs:Sport utility vehicle applications requiring enhanced thermal stability for stop-and-go driving and occasional off-pavement operation. Higher sump capacities sustain per-vehicle revenue versus compact segments.
- Light Trucks:Commercial pickup and van lubricant procurement tied to logistics platform fleet standardization. Grab and Lalamove partner workshops consolidate supplier relationships.
- Motorcycles:Two-wheeler lubricant demand concentrated in dense urban corridors where Angkas and Move It operations intensify engine stress through continuous idling.
Passenger Cars retain volume leadership; Light Trucks hold the steepest expansion curve.
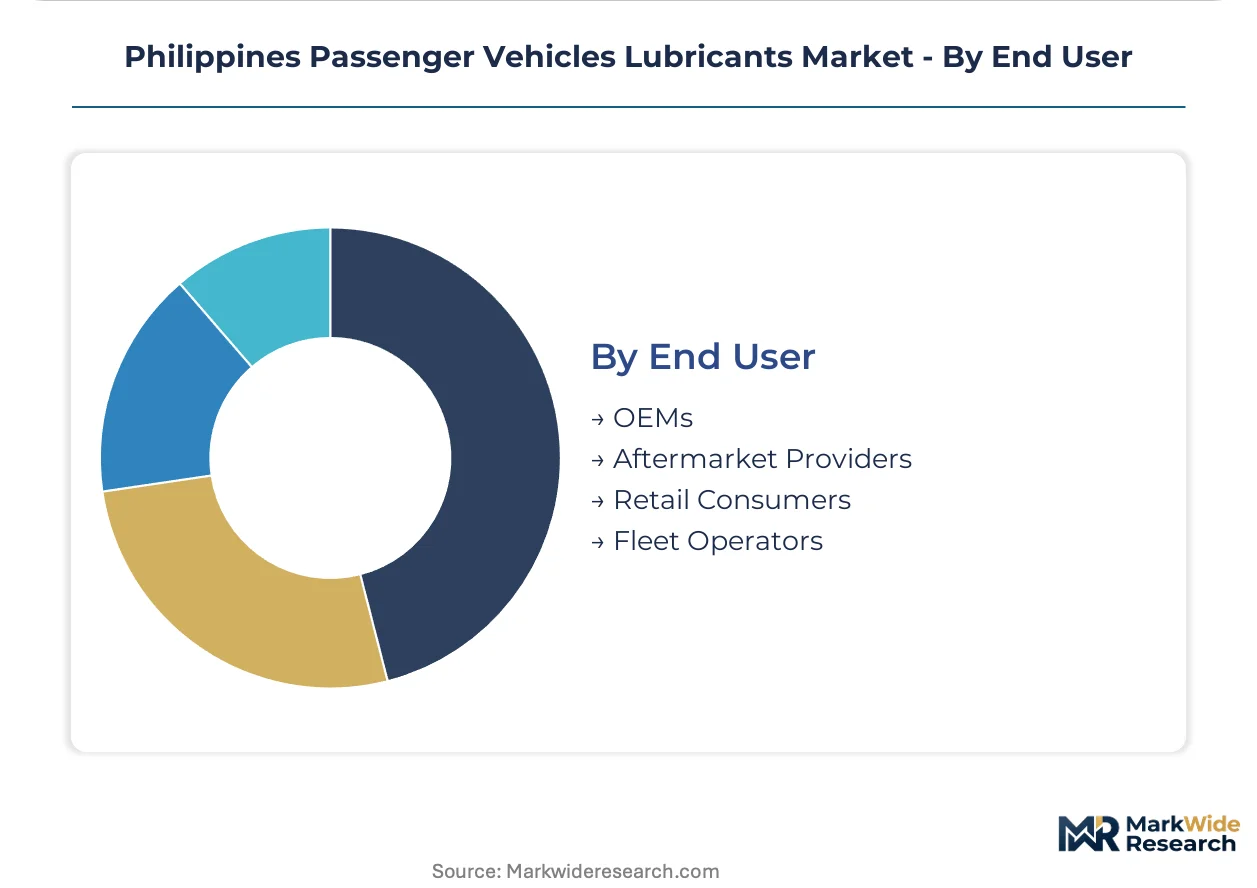
End User:
Customer type determines procurement scale and specification authority, with fleet operators consolidating purchasing power previously fragmented across individual vehicle owners.
- OEMs:Original equipment manufacturers specifying factory fill and dealer service lubricants. API SP certification gates access to Japanese and Korean automaker supply contracts.
- Aftermarket Providers:Independent service workshops and fast-lube chains purchasing through distributor networks or emerging B2B platforms. Bulk supply agreements concentrate margin pools.
- Retail Consumers:Individual vehicle owners purchasing through auto parts retailers and service stations. Price sensitivity sustains conventional formulation share.
- Fleet Operators:Ride-hailing platforms and last-mile logistics providers institutionalizing preventive maintenance. Professionalized schedules expand procurement volumes despite extended synthetic drain intervals.
Aftermarket Providers retain volume leadership; Fleet Operators hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators concentrate procurement authority across three Philippine sub-regions where vehicle utilization intensifies and service infrastructure gaps persist. Luzon dominates volume absorption while Visayas and Mindanao present channel expansion vectors for lubricant marketers.
Metro Manila and Calabarzon
Ride-hailing platforms and last-mile logistics providers drive synthetic lubricant demand through professionalized maintenance schedules. The Department of Energy's fuel quality regulations mandate oxidation stability testing that elevates formulation standards for suppliers serving this corridor. Quezon City and Makati host the densest service center networks where B2B procurement platforms displace traditional distributor relationships.
Central Luzon
Petron Corporation's Bataan refinery complex anchors domestic base oil supply for blenders serving OEM fill contracts and aftermarket channels. Bureau of Product Standards certification requirements gate market access for imported and domestically blended lubricants. The Subic-Clark logistics corridor sustains bulk lubricant offtake from fleet operators managing regional distribution networks.
Cebu and Central Visayas
Japanese OEMs expand CVT-equipped model distribution into provincial markets, accelerating transmission fluid adoption beyond traditional engine oil demand. The Land Transportation Office's vehicle inspection modernization could tighten documentation requirements for commercial fleet maintenance. Cebu City's emerging service center density attracts lubricant marketers establishing direct workshop relationships.
Davao and Northern Mindanao
Emerging logistics hubs in southern Philippines remain underserved by branded lubricant distribution networks. Provincial fleet operators currently rely on conventional formulations through fragmented supply channels. Cagayan de Oro's growing commercial vehicle parc presents first-mover opportunity for bulk supply agreements with professionalizing maintenance operations.
Philippines Passenger Vehicles Lubricants Market Competitive Landscape
Player mix skews toward integrated petroleum majors with captive refining infrastructure and domestic blenders dependent on imported base stocks. Market structure concentrates around three to four entities controlling OEM fill contracts and national distribution networks. Strategic archetypes include integrated multinationals leveraging global additive technology, domestic refiners with backward integration into base oil production, and independent marketers competing through provincial channel expansion. Competitive moves center on API SP certification acceleration and B2B platform partnerships that compress traditional distributor tiers.
Among integrated petroleum majors, Royal Dutch Shell Plc and BP Plc through its Castrol brand occupy positions defined by global additive supply agreements and archipelago-wide distribution infrastructure. Petron Corporation exemplifies the domestic refiner archetype with captive base oil production at its Bataan complex. Phoenix Petroleum Philippines Inc. represents the aggressive channel expansion model targeting provincial retail networks beyond Metro Manila's saturated service center corridors.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| Royal Dutch Shell Plc |
| Chevron Corporation |
| TotalEnergies |
| Petron Corporation |
| Phoenix Petroleum Philippines Inc. |
| PTT Lubricants |
| Unioil Petroleum Philippines Inc. |
| Valvoline Inc. |
| Others |
Value Network & Pricing Analysis
Eight-to-twelve-week laboratory testing lead times for API SP certification samples shipped to Singapore or Thailand compress formulation refresh cycles and concentrate pricing power among integrated multinationals with captive testing infrastructure, while domestic blenders absorb margin erosion from freight cost volatility and currency fluctuation exposure on imported Group II/III base stocks.
Pricing Analysis
Cost-plus contracts indexed to Singapore-published Group II/III base oil spot assessments dominate procurement between Bataan-based blenders and fleet operators, with API SP certification tier and volume scale serving as the primary price differentiation drivers. Pricing pressure stems from Group III+ hydroprocessed mineral oils eroding traditional polyalphaolefin premiums through 15-20% cost reductions at equivalent viscosity performance. Retail consumers in provincial Visayas and Mindanao corridors exhibit highest price sensitivity, while OEM fill contract holders demonstrate lowest sensitivity due to warranty compliance requirements.
Supply Chain Analysis
Singapore and South Korea anchor regional base oil supply through catalytic hydrocracking complexes serving Philippine blenders lacking domestic capacity, with additive packages drawing from Lubrizol, Infineum, and Afton supply agreements requiring minimum volume commitments. Raw material dependencies center on Group II/III base stocks, viscosity modifier polymers, and detergent-dispersant additive systems. Single-source vulnerability concentrates at Petron Corporation's Bataan refinery complex, which processes the majority of domestic base oil supply. Distribution runs through national distributor networks, emerging B2B procurement platforms, and direct bulk supply relationships with fleet operators in Metro Manila and Cebu corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
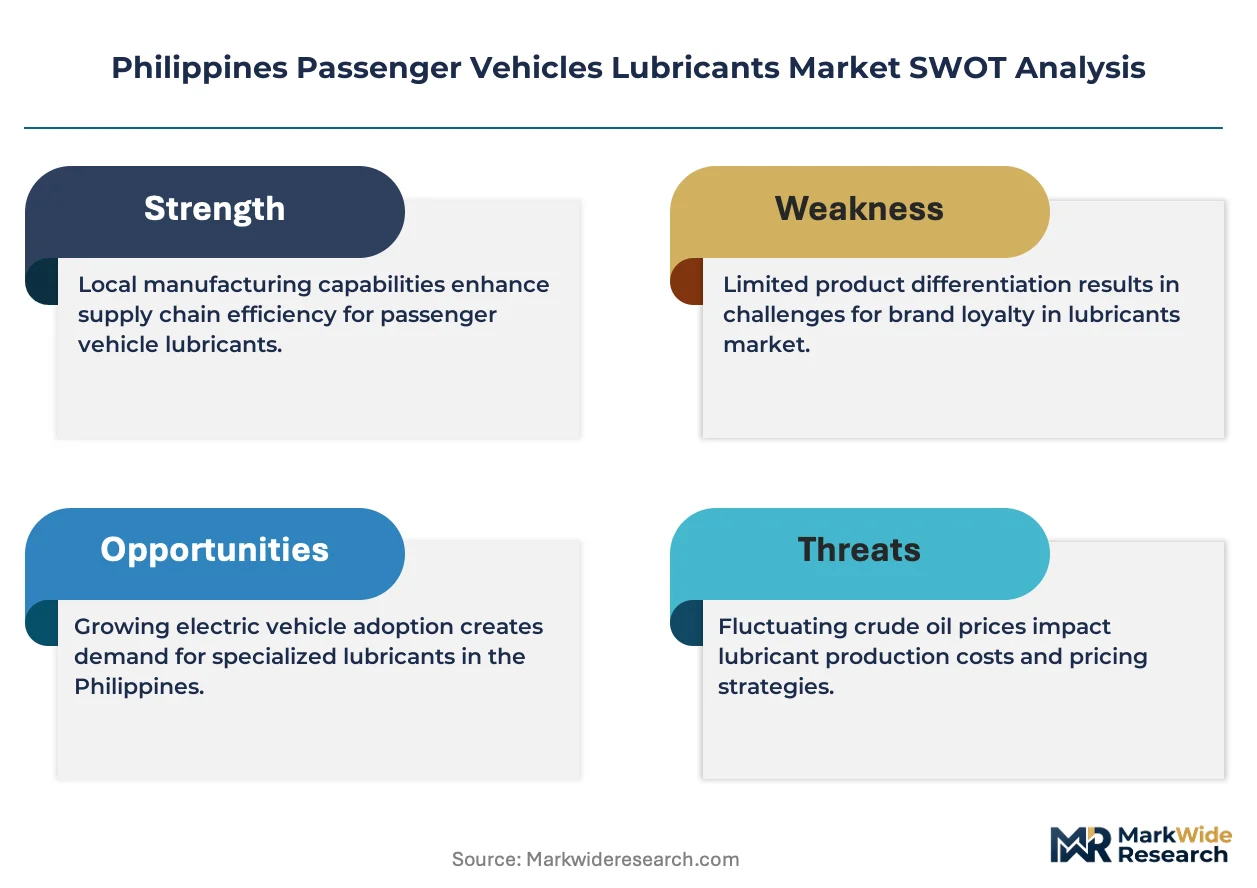
Incumbents face substitution defense imperatives as electric vehicle powertrain adoption threatens long-term internal combustion engine lubricant demand, requiring strategic repositioning toward thermal management fluids and e-axle greases.
For Market Incumbents: Fortify API SP certification pipelines through Singapore laboratory partnerships or third-party validation investments to compress 8-12-week testing timelines threatening OEM fill contract retention. Deepen backward integration into additive package blending or secure exclusive supply agreements with Lubrizol, Infineum, or Afton to defend margin position against integrated multinational competitors with global technology access. For New Entrants and Emerging Players: Differentiate on B2B platform partnerships targeting Grab and Angkas partner workshops consolidating supplier interfaces through digital procurement intermediaries. White-space concentration sits in Davao and Cagayan de Oro corridors where provincial fleet operators rely on fragmented conventional formulation supply channels, presenting first-mover opportunity for branded bulk supply agreements with professionalizing maintenance operations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because market structure concentrates around three to four entities controlling OEM fill contracts and national distribution networks, with mid-scale blenders facing additive package minimum volume commitment strain. Acquisition target archetype: domestic blenders with Bureau of Product Standards certification and established workshop relationships but lacking API SP testing infrastructure. Signal to watch: Land Transportation Office vehicle inspection modernization tightening documentation requirements for commercial fleet lubricant change intervals.| Strategic Initiative | Industry Significance |
|---|---|
| API SP Certification Acceleration | Compresses testing timelines to defend OEM fill contracts against integrated multinationals with Singapore laboratory access. |
| Mindanao Service Network Expansion | Captures first-mover advantage in Davao and Cagayan de Oro corridors underserved by branded distribution. |
| B2B Platform Partnership | Consolidates supplier interfaces with Grab and Angkas partner workshops displacing traditional distributor tiers. |
| Group III+ Base Oil Transition | Defends margin through price-performance repositioning against full synthetic formulations in tropical applications. |
| Additive Package Supply Security | Secures exclusive agreements with Lubrizol, Infineum, or Afton to meet minimum volume commitments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with lubricant blending plant managers, fleet maintenance directors at ride-hailing platforms, aftermarket workshop owners, and Department of Energy regulatory officers; and secondary validation through Bureau of Product Standards certification records, Department of Energy circulars, customs import data for base oil and additive shipments, and vehicle registration databases from the Land Transportation Office. Bottom-up triangulation across service center density estimates and fleet operator procurement volumes reconciled against top-down lubricant consumption models per vehicle parc segment.
Across the analysis window, the forecasting framework modeled volume and value projections across product type, formulation grade, vehicle application, and end-user category dimensions, with CAGRs derived from regression analysis of historical consumption patterns against vehicle parc expansion and drain interval extension trajectories. Key inputs included Japanese and Korean OEM service specification timelines, tropical climate viscosity grade adoption curves, and fleet operator professionalization rates in Metro Manila and provincial corridors.
Decision-makers should treat outputs as directional under assumptions of sustained internal combustion engine parc dominance and stable Department of Energy regulatory trajectories; material deviation through accelerated electric vehicle adoption or fuel quality specification shifts would warrant model refresh. Recalibration cycles align with material shifts in OEM powertrain specifications, BIS certification harmonization progress, and fleet operator consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Russia Automotive Airfilters Market