

Luxury Car Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Car Hoses Market Insights
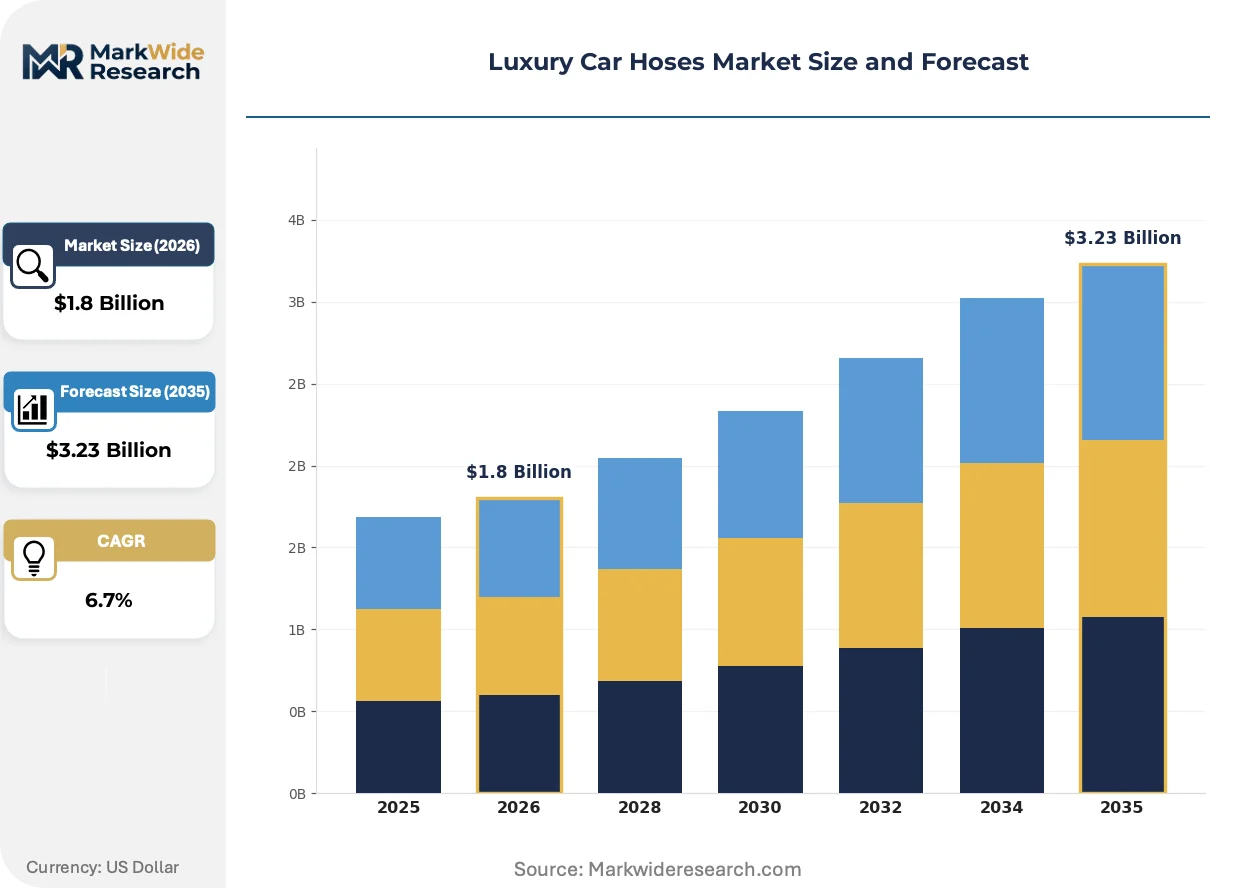
Market Context
IATF 16949 certification is unwinding the supplier base, forcing sub-tier manufacturers toward audited quality systems or exit. Continental AG leverages its captive rubber compounding and hose extrusion footprint across European luxury OEM corridors. Gates Corporation sustains North American aftermarket dominance through branded distribution and specification-grade product lines. Sumitomo Riko anchors Asian supply relationships with vibration-damping hose assemblies engineered for premium Japanese and Korean nameplates.
Technical Definition and Segment Structure
Luxury car hoses are pressure-rated fluid conduits manufactured from elastomeric or fluoropolymer compounds with textile, aramid, or stainless-steel reinforcement layers, designed to operate across temperature ranges from minus forty to over two hundred degrees Celsius while resisting hydrocarbon permeation and electrochemical degradation. Their primary purpose is to maintain sealed fluid circuits for thermal management, braking force transmission, and forced induction in high-performance powertrains where failure tolerance approaches zero. Brake hoses and turbocharger hoses command disproportionate margin pools due to safety-critical certification burdens and material intensity in fluoropolymer barrier layers. Silicone and PTFE material grades are gaining specification share as engine bay thermal loads rise with downsized turbocharged architectures.
Regulatory Frame and Outlook
EPA tailpipe standards, NHTSA brake system regulations, and REACH substance restrictions collectively dictate hose compound formulations, permeation limits, and supplier qualification pathways in the United States and European Union. China's MIIT fuel consumption targets and GB standards for automotive fluids are converging with these frameworks, creating a transnational compliance floor for export-capable manufacturers. Stakeholders must monitor the divergence between regional chemical restriction timelines and OEM platform consolidation cycles to calibrate compound development roadmaps and capital allocation decisions.
Market Dynamics
Electrified powertrain thermal management is restructuring demand toward fluoropolymer barrier layers capable of withstanding sustained temperatures above 150°C, forcing compounders to abandon conventional NBR and EPDM formulations in premium vehicle segments.
Growth Catalysts
- EU Green Deal decarbonization mandates:REACH substance restrictions are accelerating fluoropolymer substitution timelines, with OEMs pre-emptively reformulating hose compounds to avoid supply disruption during platform consolidation cycles.
- Downsized turbocharger architectures:Charge air cooling circuits in high-performance combustion engines require silicone-based hose assemblies with aramid reinforcement, expanding specification-grade procurement volumes.
- German premium vehicle assembly corridors:Supplier co-location patterns around Stuttgart and Munich create concentrated sourcing basins that amplify procurement efficiency for IATF 16949-certified manufacturers.
Market Restraints
- Fluoropolymer raw material concentration:PTFE and FKM resin supply concentrates among Japanese and Chinese chemical producers, exposing compounders to input cost volatility and geopolitical freight disruptions.
- REACH authorization timelines:ECHA substance evaluation windows extend 18-36 months, freezing formulation development roadmaps for hose manufacturers awaiting regulatory clarity on PFAS restrictions.
- Thermoplastic hose substitution:Multi-layer nylon tubing for thermal management circuits offers 40% weight reduction versus rubber assemblies, threatening specification share in non-pressurized applications.
Strategic Opportunities
- Battery electric vehicle thermal loops:Coolant hose specifications for high-voltage battery packs and power electronics represent underpenetrated white space with distinct pressure-temperature profiles versus combustion-era designs.
- China MIIT fuel consumption targets:Domestic premium OEMs are accelerating turbocharger penetration to meet corporate average fuel economy mandates, expanding demand for fluorosilicone charge air hoses.
- Direct OEM-supplier digital procurement platforms:Volkswagen Group and BMW are piloting blockchain-tracked material certification systems that bypass traditional tiered distribution, rewarding compounders with audited quality systems.
Industry Challenges
- IATF 16949 certification backlog:Sub-tier extrusion houses face 12-18 month audit queues, constraining capacity expansion for OEMs seeking qualified alternative suppliers.
- PFAS compound legacy liability:Hose manufacturers must maintain dual formulation inventories during transition periods, complicating inventory management and warranty traceability.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Car Hoses Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to fragment established supply relationships, with specification authority migrating from tier suppliers toward OEM central engineering functions.
Fluorosilicone barrier technology is bifurcating the market between legacy EPDM formulations and next-generation charge air hose specifications. Premium German and Korean OEMs are adopting fluorosilicone assemblies for 48V mild-hybrid turbocharger circuits, compressing specification windows for conventional compounds and forcing compounders to choose between capital-intensive resin compounding investments or exit from forced induction applications.
REACH PFAS restriction proposals are compelling reformulation across European supply chains. ECHA's 2023 restriction roadmap targets perfluorinated compounds in automotive fluid handling, driving Continental AG and peer compounders toward hydrogenated nitrile and bio-based epichlorohydrin alternatives. Brake hose manufacturers face the steepest compliance burden, as DOT-approved barrier layers historically relied on PTFE permeation resistance.
Specification-grade procurement is consolidating around OEM central engineering functions with direct material qualification authority. Tier-1 assembly houses are losing formulation specification autonomy as Volkswagen, Mercedes-Benz, and BMW centralize hose compound approval through corporate material databases. This pattern is most visible in Germany, where IATF 16949-certified compounders now negotiate directly with OEM material engineering rather than through tier-1 purchasing departments.
Luxury Car Hoses Market Segmentation
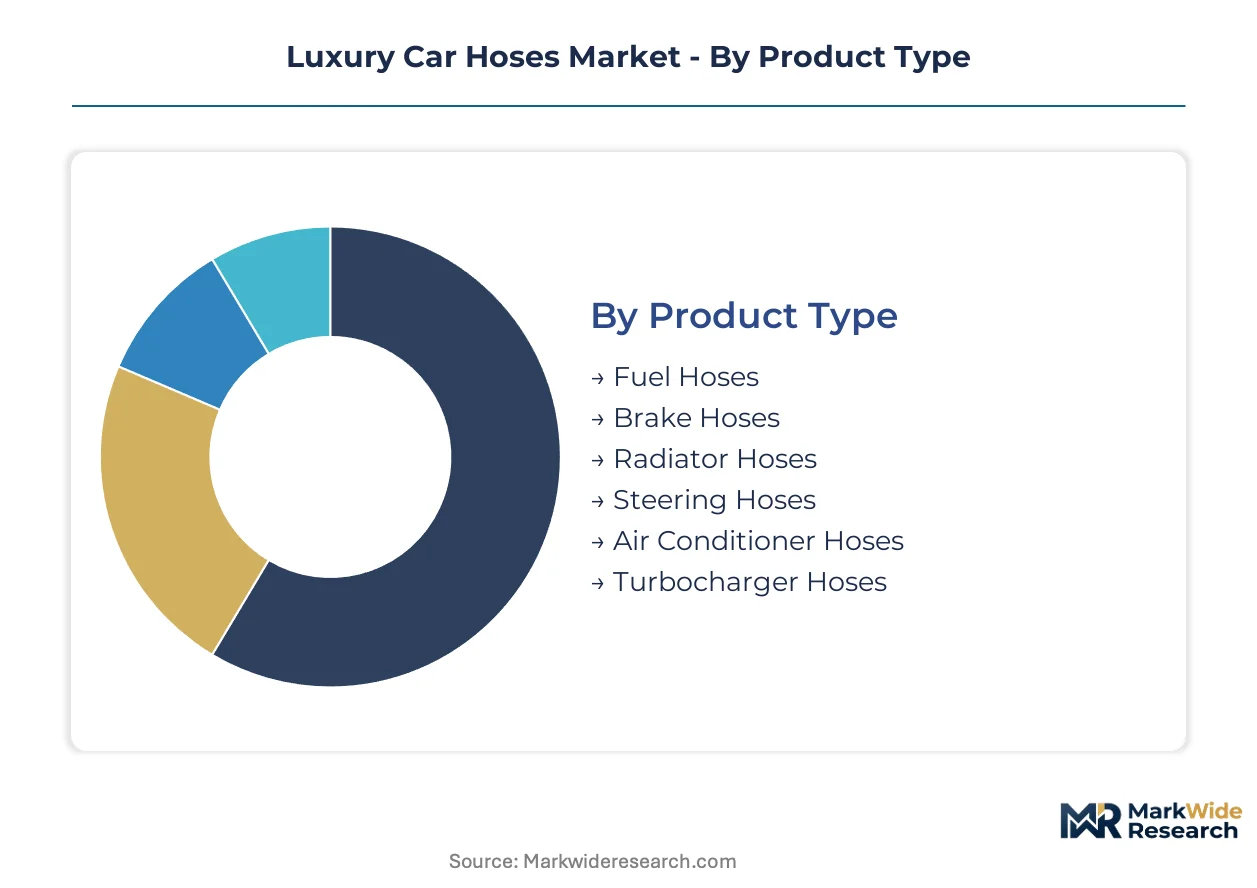
Segmentation in the luxury car hoses market tracks how thermal management complexity and regulatory chemistry restrictions are fragmenting procurement patterns across fluid handling systems. Specification authority is migrating from tier suppliers toward OEM central engineering functions, forcing compounders to align roadmaps with distinct pressure-temperature profiles rather than generic automotive grades.
Product Type:
Fluoropolymer substitution pressure varies sharply across hose functions, with safety-critical and high-temperature applications facing the steepest reformulation mandates while legacy cooling circuits retain conventional elastomer specifications.
- Turbocharger Hoses:Fluorosilicone barrier layers with aramid reinforcement withstand sustained temperatures above 200°C in charge air cooling circuits. German premium OEMs specify these for 48V mild-hybrid architectures, compressing demand for conventional EPDM formulations in forced induction applications.
- Brake Hoses:PTFE-lined assemblies with stainless-steel braid reinforcement must maintain DOT-approved permeation resistance under REACH PFAS restriction timelines. ECHA substance evaluation windows are forcing compounders toward hydrogenated nitrile alternatives while maintaining safety-critical certification burdens.
- Fuel Hoses:Multi-layer barrier constructions with fluoropolymer inner cores resist hydrocarbon permeation in direct injection systems.
- Radiator Hoses:EPDM formulations with textile reinforcement dominate coolant circulation despite thermoplastic substitution threats in non-pressurized circuits.
- Steering Hoses:High-pressure hydraulic assemblies with crimped metal fittings serve rack-and-pinion power assist systems.
- Air Conditioner Hoses:Nylon barrier layers with rubber cover stock handle refrigerant circulation in climate control circuits.
Radiator hoses anchor the volume base while turbocharger hoses gain share at the steepest rate.
Material:
Cost tier stratification separates fluoropolymer compounds commanding specification premiums from commodity elastomers facing thermoplastic displacement in weight-sensitive applications.
- PTFE:Virgin and filled polytetrafluoroethylene resins provide near-zero permeation in fuel and brake barrier layers. Japanese and Chinese chemical producers concentrate resin supply, exposing compounders to input cost volatility and geopolitical freight disruptions.
- Silicone:VMQ and FVMQ grades withstand extreme temperature cycling in engine bay applications. Premium Korean nameplates specify fluorosilicone variants for turbocharger circuits, expanding specification-grade procurement volumes.
- Reinforced Rubber:Traditional NBR and EPDM compounds with textile or wire reinforcement serve legacy cooling and fuel applications.
- EPDM:Ethylene-propylene-diene monomer formulations dominate coolant hoses for cost-sensitive thermal management.
- Neoprene:Chloroprene rubber retains niche applications in transmission oil cooling.
- Nylon:Multi-layer thermoplastic tubing offers 40% weight reduction versus rubber assemblies in battery electric vehicle thermal loops.
Reinforced rubber retains the largest installed base while nylon expands most quickly in electrified powertrain applications.
Application:
Application segmentation tracks how electrification is restructuring fluid circuit priorities, with combustion-era cooling and fuel systems yielding ground to battery thermal management and power electronics cooling.
- Engine Cooling:Silicone and EPDM hose assemblies circulate coolant through internal combustion powertrains. Stuttgart and Munich assembly corridors concentrate procurement for German premium nameplates, amplifying sourcing efficiency for IATF 16949-certified manufacturers.
- Turbocharging Systems:Fluorosilicone charge air hoses with aramid reinforcement handle compressed air temperatures in downsized engines. China's MIIT fuel consumption targets are accelerating turbocharger penetration among domestic premium OEMs.
- Fuel Delivery:Multi-layer barrier hoses resist permeation in high-pressure direct injection circuits.
- Hydraulic Control:Reinforced elastomer assemblies transmit braking and steering force in safety-critical circuits.
- HVAC:Refrigerant hoses with nylon barrier layers serve climate control systems.
- Emission Control:High-temperature hoses route exhaust gas recirculation and crankcase ventilation.
Engine cooling commands the largest specification volume while turbocharging systems climb the fastest as downsized architectures proliferate.
End User:
Customer type segmentation reveals how procurement centralization is bypassing traditional tiered distribution, with OEM material engineering functions gaining direct specification authority over compound formulation.
- OEMs:Volkswagen Group and BMW pilot blockchain-tracked material certification systems that reward compounders with audited quality systems. Direct digital procurement platforms are consolidating specification authority in corporate material databases.
- Tier-1 Suppliers:Continental AG and Sumitomo Riko maintain assembly relationships with captive compounding and vibration-damping expertise. These houses are losing formulation autonomy as OEMs centralize hose compound approval.
- Vehicle Assemblers:Contract manufacturers in premium vehicle corridors source pre-approved hose assemblies from qualified supplier lists.
- Aftermarket Providers:Gates Corporation sustains North American dominance through branded distribution and specification-grade product lines.
Tier-1 suppliers handle the greatest assembly volume while OEM direct procurement expands most quickly through digital certification platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium vehicle assembly corridors concentrate procurement power among German, Chinese, and American luxury OEMs, with supplier co-location patterns amplifying sourcing efficiency for IATF 16949-certified compounders in each geography.
Germany
Stuttgart and Munich assembly basins anchor European demand for fluorosilicone turbocharger hoses as Mercedes-Benz and BMW accelerate 48V mild-hybrid penetration. REACH substance restrictions under the EU Green Deal are forcing compounders toward hydrogenated nitrile alternatives. Continental AG maintains captive rubber compounding operations across Baden-Württemberg and Bavaria corridors.
China
Domestic premium OEMs are expanding turbocharger specification volumes to meet MIIT corporate average fuel economy mandates. Shanghai and Beijing assembly clusters concentrate procurement for NIO, Li Auto, and BYD's Denza sub-brand. GB standards for automotive fluids are converging with European permeation limits, creating transnational compliance requirements for export-capable suppliers.
United States
EPA tailpipe standards and NHTSA brake system regulations dictate hose compound formulations for Detroit Three luxury divisions. Southeast assembly corridors in Tennessee and South Carolina host BMW and Mercedes-Benz transplants, creating regional sourcing basins distinct from Midwest supplier networks. Gates Corporation sustains aftermarket dominance through branded distribution.
Japan
Tokyo and Nagoya industrial basins concentrate demand for vibration-damping hose assemblies engineered for Lexus and Infiniti nameplates. METI fuel efficiency targets are accelerating downsized turbocharger architectures across premium segments. Sumitomo Riko anchors Asian supply relationships through material qualification partnerships with Toyota and Honda.
South Korea
Seoul Capital Area assembly clusters drive specification-grade procurement for Genesis and Kia's premium sub-brands. MFDS-aligned chemical safety assessments are converging with REACH substance evaluation timelines. Hyundai Motor Group's Ulsan complex is piloting blockchain-tracked material certification systems for direct supplier qualification.
Luxury Car Hoses Market Competitive Landscape
Player mix skews toward integrated rubber compounders with captive extrusion capacity and tier-1 assembly houses with OEM-direct material qualification pathways. Market structure concentrates around three strategic archetypes: European integrated compounders with in-house resin blending, Asian vibration-damping specialists with OEM captive relationships, and North American aftermarket distributors with specification-grade branded lines. Dominant competitive moves include backward integration into fluoropolymer resin compounding and digital procurement platform participation bypassing traditional tiered distribution.
Among European integrated compounders, Continental AG exemplifies the captive rubber compounding archetype with audited quality systems across luxury OEM corridors. Gates Corporation represents the aftermarket-distribution vector with specification-grade product lines sustaining North American presence. Sumitomo Riko occupies a position within the Asian vibration-damping specialist tier, anchoring supply relationships through material engineering partnerships with premium Japanese and Korean nameplates.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Sumitomo Riko Company |
| Parker Hannifin |
| TI Fluid Systems |
| Dayco |
| Cooper Standard Automotive |
| Nichirin |
| Toyoda Gosei |
| Others |
Pricing and Supply Chain Analysis
Captive fluoropolymer compounding capacity in Germany and Japan anchors price floors for specification-grade hose assemblies, with scale advantages concentrating among IATF 16949-certified compounders who supply directly to OEM material engineering functions. This scale concentration compresses margin recovery for sub-tier extrusion houses lacking audited quality systems, while REACH substance restrictions add reformulation cost layers that tier-1 suppliers struggle to pass through in fixed-price contracts.
Pricing Analysis
Cost-plus contracts with fluoropolymer resin indexation dominate procurement between OEMs and tier-1 assembly houses. Three-tier pricing structure across premium fluorosilicone, standard silicone, and economy EPDM grades reflects certification burden and thermal performance. Cost compression in EPDM radiator hoses is intensifying because thermoplastic substitution threats force rubber compounders to absorb material volatility. Aftermarket distributors exhibit highest price sensitivity, while OEM direct procurement tolerates specification premiums for REACH-compliant barrier layers.
Supply Chain Analysis
Japan and China anchor virgin PTFE and FKM resin production, with German compounders drawing from Asian chemical producers for fluoropolymer feedstock. Raw material dependencies center on perfluorinated resins, aramid fiber, and hydrogenated nitrile rubber. Single-source vulnerability concentrates in Japanese resin suppliers, exposing European compounders to geopolitical freight disruptions. Distribution runs through tier-1 assembly houses toward OEM central engineering, bypassing traditional purchasing departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrified powertrain thermal management is disrupting procurement patterns, with fluoropolymer substitution timelines compressing as REACH PFAS restrictions force simultaneous reformulation across brake and turbocharger applications.
For Market Incumbents: Secure captive fluoropolymer compounding capacity or long-term resin offtake agreements with Japanese and Chinese chemical producers to defend against input cost volatility. Deepen backward integration into hydrogenated nitrile rubber production as PTFE alternatives gain specification share under ECHA substance evaluation timelines. For New Entrants and Emerging Players: Anchor in battery electric vehicle thermal loop specifications, where coolant hose pressure-temperature profiles diverge from combustion-era designs and incumbent compounders lack qualified formulations. Target direct OEM qualification through blockchain-tracked material certification pilots at Volkswagen Group and BMW, bypassing tier-1 distribution chokepoints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IATF 16949-certified compounders with direct OEM material engineering relationships and audited quality systems spanning multiple premium vehicle corridors. Acquisition candidates should demonstrate qualification pathways across fluorosilicone, hydrogenated nitrile, and bio-based epichlorohydrin formulations. The signal to watch is ECHA authorization timeline clarity on PFAS restrictions, which will determine stranded asset risk in legacy PTFE compounding capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Compounding | Captive PTFE and FKM production insulates Continental AG from Japanese supplier concentration. |
| Direct OEM Digital Procurement Platform Participation | Blockchain-tracked certification at BMW rewards compounders with audited IATF 16949 quality systems. |
| Hydrogenated Nitrile Formulation Development | REACH-compliant alternatives to PTFE brake hose barriers address ECHA substance restriction timelines. |
| Battery Electric Vehicle Thermal Loop Qualification | Distinct pressure-temperature profiles for high-voltage coolant circuits create white-space expansion opportunity. |
| Long-Term Resin Offtake Agreements | Fixed-price fluoropolymer supply contracts with Chinese producers hedge against geopolitical freight disruptions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed automotive suppliers, IHS Markit vehicle production databases, and ECHA substance restriction documentation. Primary interviews engaged OEM platform engineers, tier-1 supplier procurement directors, fluoropolymer compounder technical leads, and aftermarket distribution channel managers. Bottom-up modeling of hose content per vehicle by powertrain architecture triangulates against top-down market value reconstruction from supplier revenue disclosures.
Segmentation dimensions modeled include hose function, material compound, vehicle propulsion architecture, and regional production cluster. CAGRs derive from regression analysis of historical procurement volumes against turbocharger penetration rates and electrification adoption curves. Forecast inputs incorporate MIIT fuel consumption target trajectories, REACH authorization timeline scenarios, and OEM platform consolidation cycles.
Material uncertainties — ECHA PFAS restriction finalization, fluoropolymer resin supply disruptions, and thermoplastic substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory convergence between GB standards and European permeation limits. Recalibration cycles align with material shifts in substance restriction timelines and OEM thermal management architecture decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.