
 Automotive Brake Wheel Cylinder Market | 2026-2036
Automotive Brake Wheel Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Wheel Cylinder Market Outlook
Aftermarket distributors is reorganizing procurement priorities as commercial fleet operators gain share over individual vehicle owners in brake cylinder replacement cycles. Robert Bosch GmbH leverages its captive foundry network to control casting quality for hydraulic cylinder housings. Continental AG anchors European OEM supply through integrated brake system architectures. Aisin Corporation specializes in lightweight aluminum cylinder designs for Asian passenger vehicle platforms.
An automotive brake wheel cylinder is a hydraulic or pneumatic actuator mounted within drum brake assemblies, typically machined from cast iron or aluminum alloy with bore diameters ranging from 17.46 mm to 38.1 mm, that converts fluid pressure into mechanical force to expand brake shoes against the drum surface. The component serves as the critical force-multiplication element in drum brake systems, maintaining vehicle deceleration performance under varying thermal and load conditions. Single acting cylinders dominate entry-level applications while double acting variants command premium positioning in heavy-duty segments. Aftermarket channels sustain higher margin pools than OEM supply due to fragmented demand and price elasticity among independent repair networks.
China's MIIT enforces GB 12676 and GB 7258 braking performance standards that mandate minimum deceleration rates and thermal fade resistance for commercial vehicles, directly shaping cylinder bore specifications and material selection. India's BIS aligns automotive brake component testing with AIS-001 protocols under Central Motor Vehicle Rules, creating compliance barriers for uncertified imports. The EU's REACH regulation restricts hexavalent chromium coatings traditionally used for cylinder corrosion protection, forcing suppliers toward trivalent alternatives or composite material transitions. Stakeholders must monitor evolving brake emissions testing protocols and material substitution timelines to preserve product certification validity across target markets.
Market Dynamics
Commercial fleet operators are consolidating procurement power across emerging markets, forcing cylinder suppliers to restructure volume pricing and technical service bundles around multi-year maintenance contracts rather than discrete part sales.
Growth Catalysts
- GB Protocol Tightening:China's MIIT has revised braking performance standards under GB 12676 and GB 7258, mandating enhanced thermal fade resistance that expands demand for double-acting cylinder architectures in heavy-duty segments.
- Drum Brake Resurgence:Commercial vehicle fleet operators across India and Southeast Asia are expanding drum brake procurement as cost-sensitive markets prioritize repairability over disc brake conversion.
- Western Automotive Corridor Concentration:Manufacturing investment clusters around Pune and Chennai are attracting tier-one cylinder suppliers seeking proximity to brake system integrators and export logistics hubs.
Market Restraints
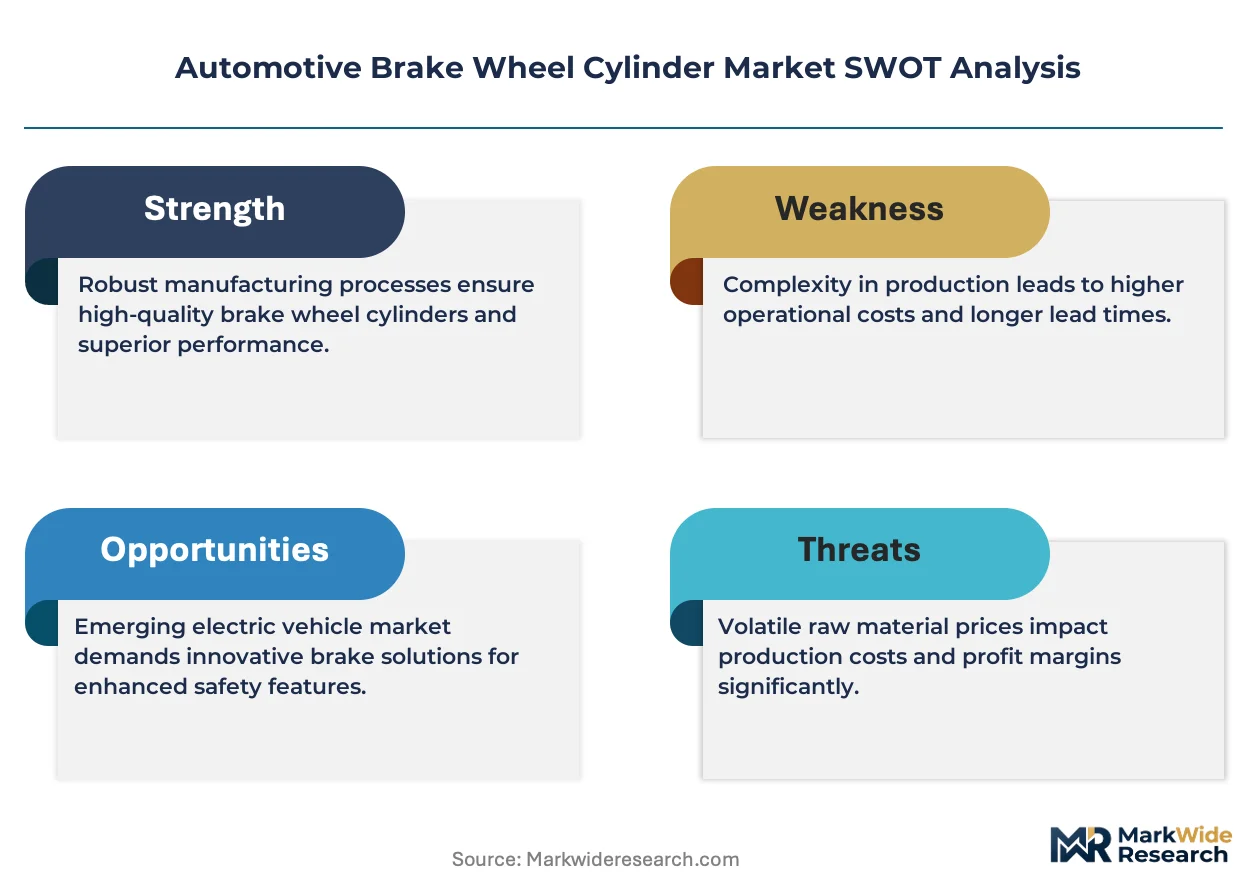
- Cast Iron Input Volatility:Foundry-grade pig iron pricing fluctuations compress margin predictability for cylinder housing producers locked into annual OEM supply agreements.
- REACH Coating Restrictions:The EU's REACH regulation has banned hexavalent chromium corrosion treatments, forcing costly retooling toward trivalent alternatives or composite material transitions without immediate cost pass-through mechanisms.
- Disc Brake Substitution:Passenger vehicle platforms above the B-segment threshold are accelerating disc brake adoption, constricting addressable market volume for drum-specific cylinder designs.
Strategic Opportunities
- Aluminum Lightweighting:Asian passenger vehicle platforms are adopting aluminum alloy cylinder housings to meet corporate fleet CO2 targets, creating premium positioning for suppliers with high-pressure die-casting capabilities.
- Aftermarket Channel Digitization:Independent repair networks in India are migrating procurement to B2B platforms, enabling direct-to-workshop distribution that bypasses traditional multi-tier distributor markups.
- PLI Scheme Alignment:India's Production Linked Incentive scheme for automotive components offers tariff relief for localized brake system manufacturing, incentivizing greenfield cylinder production facilities in Gujarat and Tamil Nadu.
Industry Challenges
- Dual Certification Burden:Suppliers serving both OEM and aftermarket channels must maintain parallel testing protocols under BIS AIS-001 and in-house fleet operator specifications, stretching quality assurance resources.
- Legacy Tooling Amortization:Cast iron cylinder production lines require extended depreciation cycles that conflict with accelerating material transitions to aluminum and polymer-composite alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Wheel Cylinder Market |
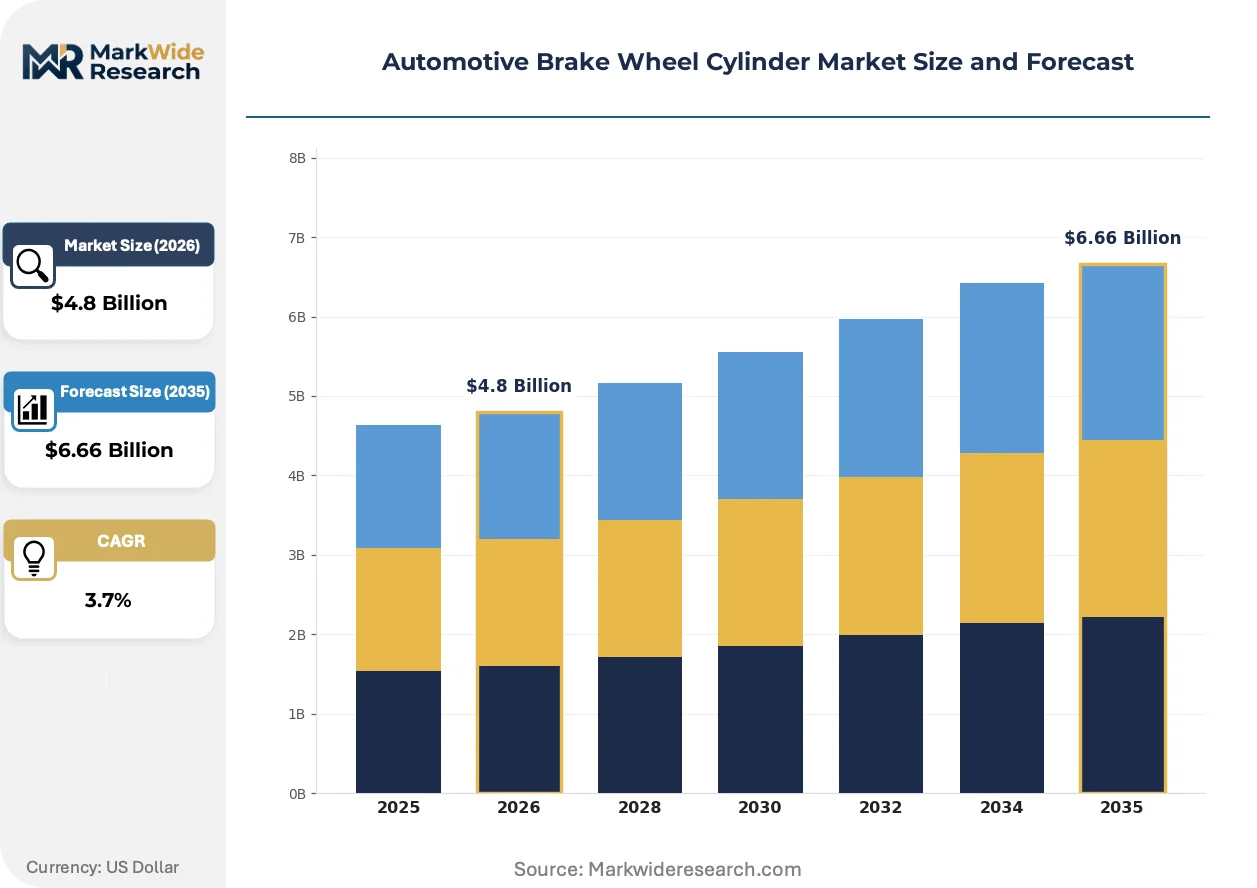
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Pneumatic, Hydraulic End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Material: Aluminum, Cast Iron, Steel, Composite Feature: Corrosion Resistance, Lightweight Design, Easy Installation, High Performance |
| Companies Covered | Robert Bosch GmbH, Continental AG, Aisin Corporation, ZF Friedrichshafen AG, Valeo SA, TBK Co., Ltd., Tenneco Inc., Akebono Brake Industry Co., Ltd., Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Wheel Cylinder Market Strategic Shifts
Material substitution and regulatory chemistry restrictions are forcing concurrent redesign of cylinder architecture and surface treatment protocols, compressing product development cycles while expanding testing validation requirements.
Trivalent chromium conversion coatings are supplanting hexavalent alternatives in corrosion protection for cast iron cylinder housings. European brake system integrators have mandated this transition under supply chain sustainability audits. The shift is compressing qualified supplier pools while elevating coating process capital requirements for tier-two foundries.
REACH Annex XVII restrictions on hexavalent chromium have triggered wholesale reformulation of cylinder surface treatment workflows. Brake component suppliers must now validate alternative passivation chemistries through extended salt-spray and thermal cycling protocols. Asian export-oriented manufacturers face the steepest compliance burden as EU OEMs enforce REACH-aligned supplier certification.
Fleet operator procurement consolidation is displacing fragmented owner-operator maintenance patterns across India's commercial vehicle sector. Large logistics companies now negotiate centralized brake cylinder supply contracts with technical service bundling. This concentration is most visible in the Mumbai-Delhi freight corridor where organized fleet penetration exceeds 40 percent of heavy commercial vehicle registrations.
Automotive Brake Wheel Cylinder Market Segmentation
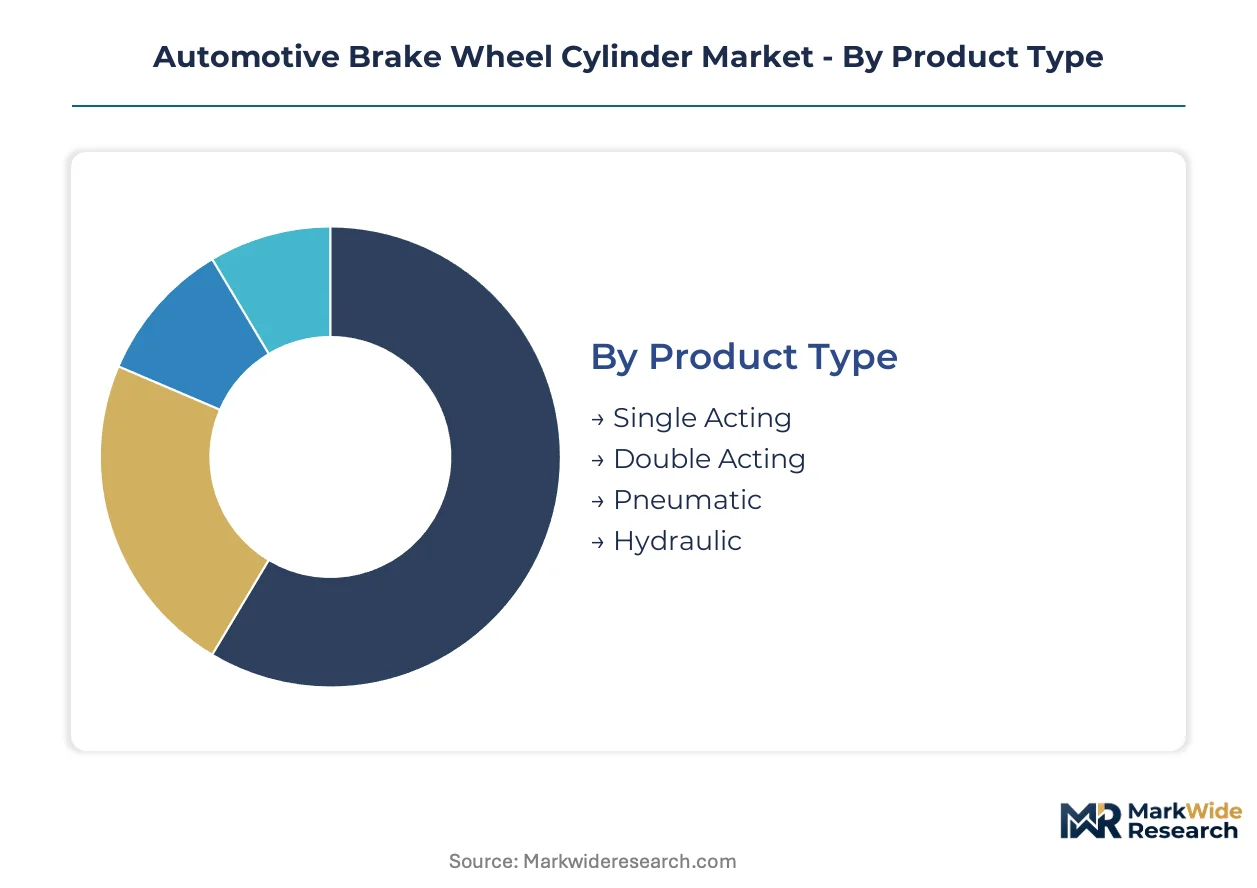
Disc brake substitution pressure varies sharply across brake wheel cylinder segments, forcing suppliers to defend position in drum-dependent applications while capturing residual demand in commercial vehicle strongholds. Material and feature differentiation now determines margin sustainability as regulatory chemistry restrictions eliminate legacy surface treatments.
Product Type:
Double acting architectures face the steepest disc brake substitution threat as passenger platforms above B-segment abandon drum systems entirely.
- Single Acting:These cylinders deploy one hydraulic piston to expand a single brake shoe, typically in trailing-shoe configurations for light commercial vehicles and entry-level passenger cars. Demand concentrates in India's cost-sensitive LCV segment where repairability trumps disc conversion economics under BIS AIS-001 compliance requirements.
- Double Acting:Dual-piston designs apply synchronized force to both leading and trailing shoes, delivering superior thermal fade resistance mandated by China's GB 12676 for heavy commercial vehicles. Fleet operators across India's western automotive corridor specify these variants for multi-axle trucks where brake balance is critical.
- Pneumatic:Compressed-air actuation dominates heavy-duty truck and bus applications above 16 tonnes GVW, particularly in European markets where integrated air brake systems are standard.
- Hydraulic:Fluid-pressure designs retain near-universal presence in passenger vehicles and light commercial applications below 7.5 tonnes.
Single acting cylinders retain volume leadership; double acting variants hold the steepest expansion curve.
End User:
Procurement consolidation among fleet operators is compressing margin pools for traditional distributor channels while elevating technical service requirements.
- OEMs:Original equipment manufacturers specify cylinder bore tolerances and material grades during platform development, locking suppliers into multi-year supply agreements with limited price renegotiation windows.
- Aftermarket:Independent repair networks sustain higher margin realization through fragmented demand and price elasticity, though B2B platform migration in India is eroding traditional multi-tier distributor markups.
- Tier-1 Suppliers:Integrated brake system manufacturers source cylinder subassemblies for incorporation into complete drum brake modules, requiring backward compatibility with multiple vehicle platform specifications.
- Vehicle Assemblers:Knock-down kit producers in emerging markets procure cylinders separately from brake system integrators to optimize local content ratios under PLI scheme requirements.
Aftermarket channels deliver superior margin contribution; fleet operator consolidation is accelerating fastest among end user categories.
Material:
REACH Annex XVII chemistry restrictions are forcing wholesale material transitions before legacy tooling depreciation cycles conclude.
- Aluminum:High-pressure die-cast alloy housings reduce unsprung mass by 40-60% versus cast iron alternatives, meeting corporate fleet CO2 targets across Asian passenger vehicle platforms. Aisin Corporation and comparable suppliers have established captive aluminum foundry capacity to control casting porosity specifications.
- Cast Iron:Foundry-grade pig iron remains dominant in heavy commercial vehicle applications where thermal mass and cost minimization outweigh weight reduction priorities. Input price volatility compresses margin predictability for producers locked into annual OEM agreements.
- Steel:Machined steel cylinders serve niche high-performance and motorsport applications requiring extreme pressure tolerance.
- Composite:Polymer-composite housings are emerging in prototype electric vehicle platforms seeking maximum weight reduction, though thermal cycling validation remains incomplete for mass production release.
Cast iron retains installed base dominance; aluminum alloys are climbing the fastest as lightweighting mandates intensify.
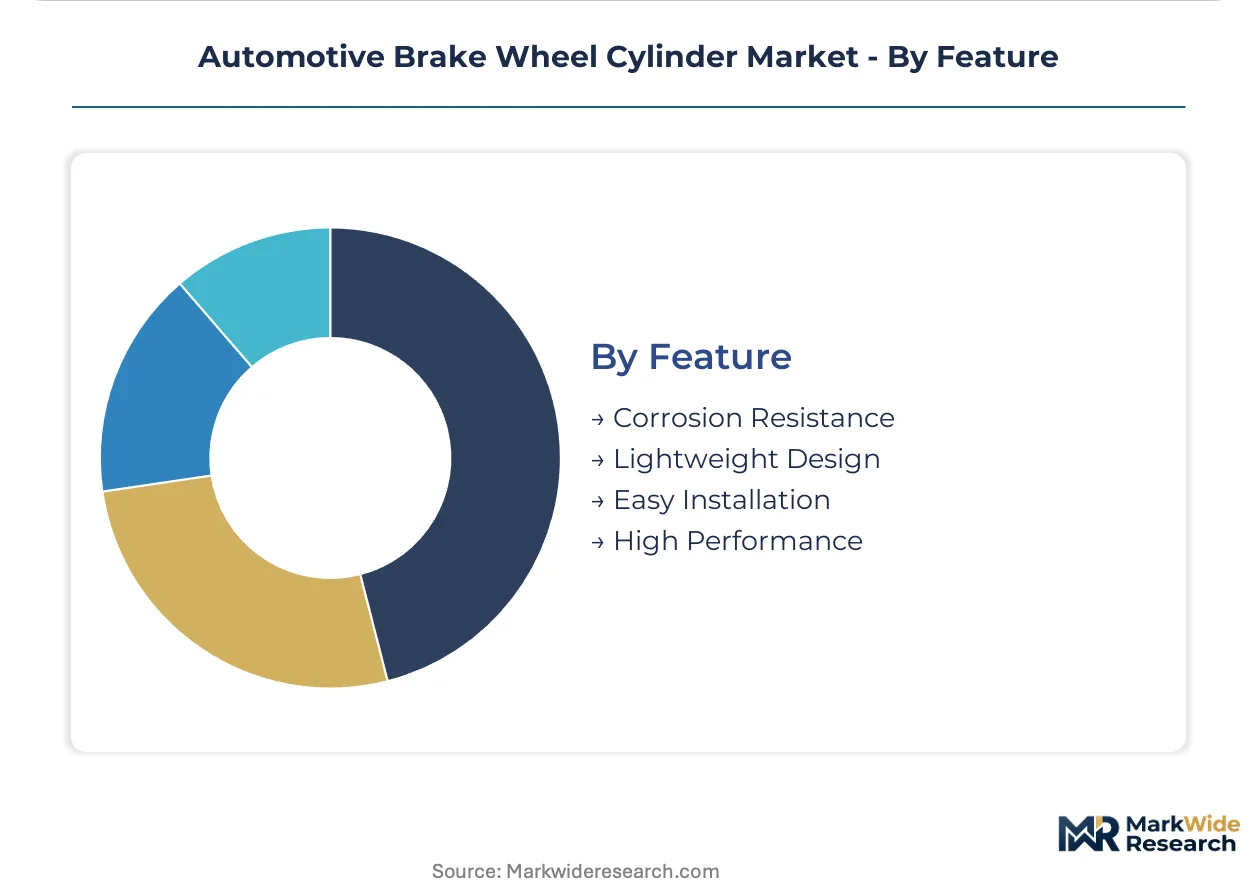
Feature:
Regulatory chemistry bans have elevated corrosion resistance from a secondary specification to a primary design constraint requiring coating process reinvention.
- Corrosion Resistance:Trivalent chromium conversion coatings now supplant banned hexavalent alternatives, validated through extended salt-spray protocols under REACH-aligned supplier certification requirements. European OEMs have mandated this transition through supply chain sustainability audits.
- Lightweight Design:Bore wall thickness optimization and aluminum alloy substitution reduce component mass without sacrificing burst pressure ratings, directly supporting vehicle-level fuel efficiency certification.
- Easy Installation:Quick-connect hydraulic fittings and standardized mounting geometries reduce workshop labor time, a priority for independent repair networks facing technician shortage pressures.
- High Performance:Enhanced thermal fade resistance and pressure consistency specifications address GB 12676 and GB 7258 mandates for commercial vehicle braking performance under sustained load conditions.
Corrosion resistance specifications command the steepest compliance investment; lightweight design features are expanding most quickly across new platform introductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished brake cylinders to Southeast Asian assembly plants while India supplies aftermarket channels across Africa and the Middle East. Germany anchors European OEM supply through integrated brake system architectures. The United States maintains import dependence for cast iron housings from Mexican foundries.
China
Commercial vehicle production expansion drives cylinder demand as domestic fleet operators modernize under MIIT's GB 12676 braking mandates. The MIIT enforces thermal fade resistance standards that favor double-acting cylinder architectures in heavy-duty segments. Manufacturing clusters concentrate in the Yangtze River Delta around Shanghai where tier-one brake system integrators co-locate with high-pressure die-casting facilities.
India
Cost-sensitive commercial vehicle operators sustain drum brake procurement despite disc conversion trends in passenger segments. BIS aligns component testing with AIS-001 protocols under Central Motor Vehicle Rules, creating compliance barriers for uncertified imports. The western automotive corridor around Pune attracts cylinder suppliers seeking proximity to brake system integrators and export logistics infrastructure.
Germany
Integrated brake system manufacturers anchor European OEM supply through captive cylinder production and backward control over casting operations. ECHA's REACH Annex XVII restrictions on hexavalent chromium coatings force wholesale reformulation of surface treatment workflows. Industrial concentration persists in Baden-Württemberg where automotive suppliers cluster around Stuttgart's engineering ecosystem.
United States
Aftermarket distributors reorganize procurement priorities as commercial fleet operators gain share over individual vehicle owners in replacement cycles. NHTSA braking performance standards shape cylinder bore specifications for vehicles sold in the domestic market. Mexican foundries across Nuevo León and the Bajío Region supply cast iron housings to US-based brake system assemblers under USMCA tariff preferences.
Japan
Lightweight aluminum cylinder designs penetrate Asian passenger vehicle platforms as corporate fleet CO2 targets intensify. METI industrial standards govern brake component quality certification for domestic and export markets. Manufacturing activity clusters in the Aichi Prefecture around Nagoya where Toyota-affiliated suppliers maintain dense supplier networks for brake system components.
Automotive Brake Wheel Cylinder Market Competitive Environment
Player mix skews toward diversified automotive suppliers with captive foundry operations and tier-one brake system integrators. The supplier base concentrates around three strategic archetypes: integrated brake system manufacturers with backward casting control, diversified automotive component conglomerates with multi-product portfolios, and specialized hydraulic actuator producers focused on aftermarket channels. Competitive dynamics center on M&A activity targeting foundry capacity and strategic partnerships for aluminum alloy supply security.
Among diversified German automotive suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated system manufacturer archetype with captive control over casting quality. Aisin Corporation occupies a position representing Japanese specialists in lightweight aluminum cylinder architectures. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning strategies across OEM and aftermarket channels.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Aisin Corporation |
| ZF Friedrichshafen AG |
| Valeo SA |
| TBK Co., Ltd. |
| Tenneco Inc. |
| Akebono Brake Industry Co., Ltd. |
| Delphi Technologies |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-week foundry lead times for cast iron cylinder housings concentrate pricing power with integrated suppliers possessing captive melting capacity, while spot-market pig iron exposure erodes margin predictability for non-integrated producers locked into annual OEM contracts.
Pricing Analysis
Cast-iron-to-aluminum technology-generation pricing gaps widen as OEMs negotiate lightweighting premiums for high-pressure die-cast alloy cylinders. Contract-based long-term offtake dominates OEM supply, while aftermarket channels sustain transactional spot purchasing with price differentiation resting on BIS AIS-001 certification grade and technical service bundling. Cost compression in entry-level single-acting cylinders intensifies as Indian fleet operators consolidate procurement volume. Tier-1 brake system integrators exhibit lowest price sensitivity; independent repair networks in fragmented African and Middle Eastern markets remain most elastic.
Supply Chain Analysis
Inbound logistics costs from Ningbo and Shanghai ports to Southeast Asian assembly plants fluctuate with container availability on the Asia-Southeast Asia trade lane, compressing landed cost predictability for export-oriented Chinese foundries. Supply concentrates in China, India, and Germany, with raw material dependencies on foundry-grade pig iron, aluminum alloy ingots, and trivalent chromium conversion chemistries. Tariff exposure under evolving EU-China trade measures threatens cylinder export economics to European aftermarket channels. Distribution runs through tier-one brake system integrators for OEM supply and multi-tier distributor networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling and predictive maintenance contracts for commercial fleet operators expand faster than hardware replacement cycles, transforming cylinder procurement from discrete part sales into recurring service relationships.
For Market Incumbents: Compound defensive positioning by deepening backward integration into captive aluminum foundry capacity and securing trivalent chromium coating process certification ahead of REACH enforcement timelines. Disc brake substitution in passenger vehicles threatens drum-specific cylinder volumes; prioritize GB 12676-compliant double-acting architectures for heavy commercial vehicle platforms where thermal fade resistance mandates sustain demand. Channel control through direct fleet operator contracts displaces traditional distributor markups in India's western automotive corridor. For New Entrants and Emerging Players: Differentiate on aluminum lightweighting capabilities for Asian passenger vehicle platforms seeking CO2 compliance through unsprung mass reduction. White-space targets cluster in India's Production Linked Incentive scheme zones where localized brake system manufacturing attracts tariff relief. The most penetrable segment lies in aftermarket B2B platform supply to independent repair networks migrating procurement online. A direct-to-workshop distribution model bypasses traditional multi-tier markups and captures price-sensitive replacement demand. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates seeking to divest non-core hydraulic actuator portfolios amid strategic restructuring. Long-term viability hinges on material transition flexibility and regulatory chemistry compliance capabilities rather than legacy cast iron scale. Monitor fleet operator procurement consolidation rates across India's Mumbai-Delhi freight corridor as an inflection indicator for aftermarket channel restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Foundry Investment | High-pressure die-casting capacity secures lightweighting margins under MIIT GB protocols. |
| Trivalent Chromium Coating Certification | REACH Annex XVII compliance preserves EU aftermarket access for Asian exporters. |
| Fleet Operator Direct Contracting | Multi-year technical service bundles displace fragmented distributor procurement in India. |
| PLI Scheme Manufacturing Localization | Tariff relief in Gujarat and Tamil Nadu attracts greenfield cylinder production facilities. |
| Aftermarket B2B Platform Integration | Direct-to-workshop distribution captures price-sensitive replacement demand in fragmented channels. |
Study Parameters
A standing panel of Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and commercial fleet maintenance directors provided ongoing calibration across primary interview rounds. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs trade flows, and MIIT GB standard filings. Bottom-up cylinder volume estimates triangulated against top-down brake system market assessments to reconcile segmentation outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled segmentation dimensions spanning product architecture, material grade, end-user channel, and regional production cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates. Industry-specific forecast inputs incorporated PLI scheme uptake rates, REACH compliance transition timelines, and fleet operator consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained commercial vehicle production growth, stable regulatory chemistry frameworks, or intact Asia-Europe trade lanes would require recalibration. Forecasts reflect documented assumptions regarding material substitution velocity and aftermarket channel digitization penetration. Specific risk factors including pig iron price volatility, disc brake substitution acceleration, and BIS certification timeline shifts could revise trajectory expectations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Variable Valve Timing (VVT) Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market