
 Light Vehicle Exhaust and Emissions Systems Market | 2026-2036
Light Vehicle Exhaust and Emissions Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Light Vehicle Exhaust and Emissions Systems Market Foresight
Euro 6 Standards compliance is unwinding the competitive landscape for exhaust system suppliers, raising barriers for uncertified participants. Tenneco Inc. leverages its global manufacturing footprint to serve multiple OEM platforms with integrated aftertreatment solutions. Eberspächer anchors its position through deep specialization in exhaust technology and thermal management systems for light vehicles. Denso Corporation competes by extending its electronics and sensor capabilities into closed-loop emissions control architectures.
Light vehicle exhaust and emissions systems comprise catalytic converters, mufflers, exhaust manifolds, and tailpipes engineered from ferritic stainless steels and advanced ceramic substrates to withstand temperatures exceeding 900°C while reducing hydrocarbon, carbon monoxide, and nitrogen oxide outputs. These assemblies serve the primary commercial purpose of enabling internal combustion engines to meet legally mandated tailpipe emissions limits across regulated markets. Catalytic converters command the largest value share within product type segmentation due to their precious metal content and complex substrate engineering, while selective catalytic reduction technology leads growth within the technology dimension as diesel and gasoline engines alike adopt urea-based NOx reduction. OEMs represent the dominant end user channel, though aftermarket providers are gaining structural importance as vehicle age profiles lengthen and regulatory inspection regimes tighten.
EPA compliance requirements in the United States, Euro 6 Standards enforced by national type-approval authorities across Europe, and China's GB VI emissions rules administered by the Ministry of Ecology and Environment collectively dictate product specifications, testing protocols, and market access conditions for exhaust system manufacturers. These frameworks are accelerating hardware refresh cycles and pushing suppliers toward modular aftertreatment architectures that can adapt to evolving limit values without full platform redesign. Stakeholders must monitor regulatory divergence between jurisdictions, as misalignment in timing or stringency threatens to fragment product portfolios and strain engineering resources across multiple compliance tracks.
Market Dynamics
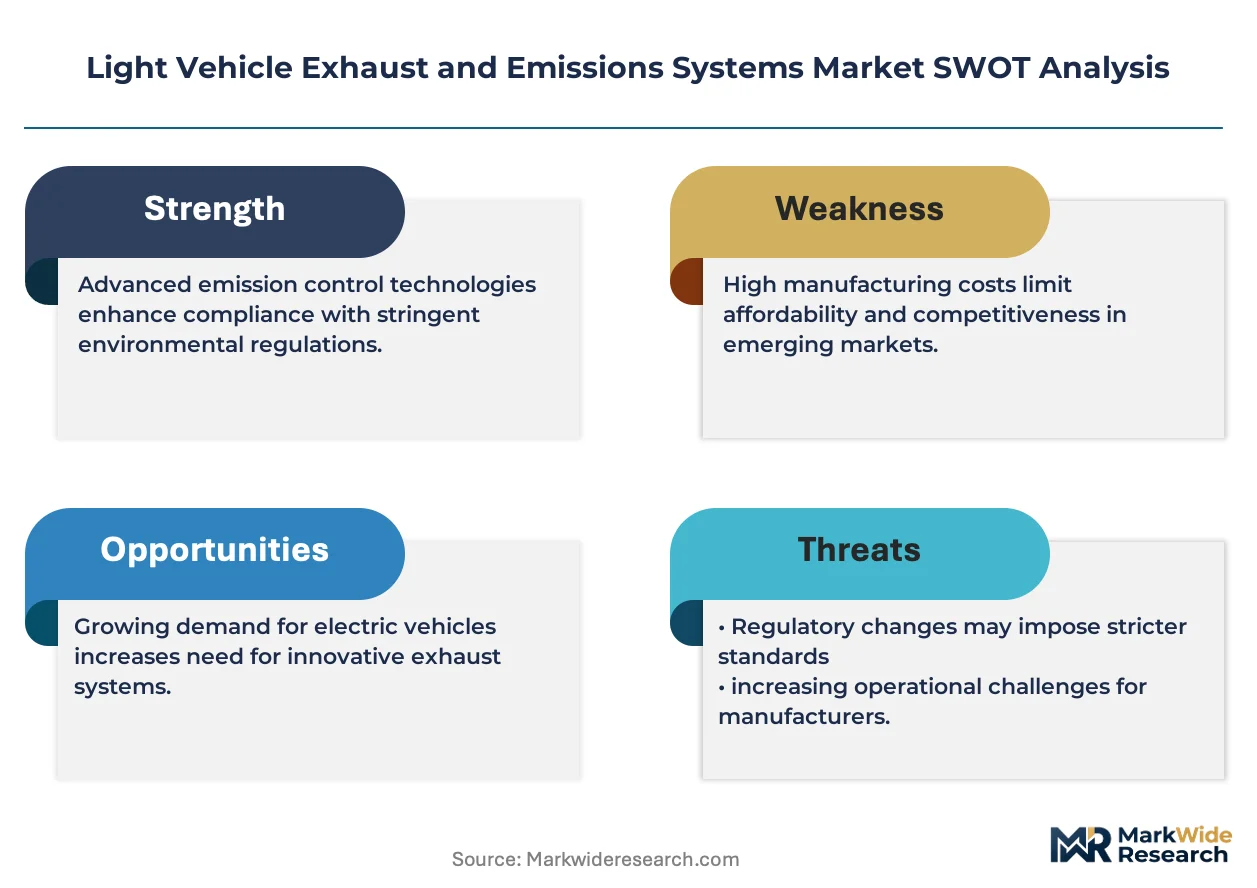
EPA Tier 3 and Euro 6 Standards are compressing hardware refresh cycles while forcing suppliers toward modular aftertreatment architectures that accommodate tightening NOx and particulate limits without full platform redesigns.
Growth Catalysts
- EPA Tier 3 mandates:Light commercial vehicle OEMs in the United States must upgrade gasoline particulate filters and three-way catalysts, sustaining replacement demand across model years.
- China GB VI enforcement:The Ministry of Ecology and Environment's phased rollout drives selective catalytic reduction adoption in domestic passenger car production.
- Ferritic stainless steel substrate advances:Higher temperature tolerance above 900°C enables thinner wall designs that reduce weight while maintaining conversion efficiency.
Market Restraints
- Palladium and rhodium cost volatility:Precious metal price swings compress catalyst margins and complicate long-term OEM contract pricing.
- Supplier concentration in Germany:Exhaust system engineering expertise clusters around Stuttgart and Munich, creating geographic single-point vulnerability for platform sourcing.
- Battery electric vehicle substitution:Zero-tailpipe powertrains eliminate aftertreatment hardware entirely from new vehicle architectures.
Strategic Opportunities
- India BS VI Phase II transition:Stricter real-driving emissions testing creates first-mover advantage for suppliers with proven selective catalytic reduction integration experience.
- Sensor-embedded exhaust architectures:Convergence of NOx sensors with predictive thermal management enables closed-loop emissions optimization.
- Independent aftermarket channels:Tighter inspection regimes in California and Germany lengthen vehicle age profiles, expanding addressable installed base for replacement catalysts.
Industry Challenges
- Calibration engineering scarcity:OEMs compete for limited talent pools capable of integrating urea dosing algorithms with engine control modules.
- Homologation timeline compression:Divergent type-approval deadlines across EPA, KBA, and MEE strain parallel validation track resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Vehicle Exhaust and Emissions Systems Market |
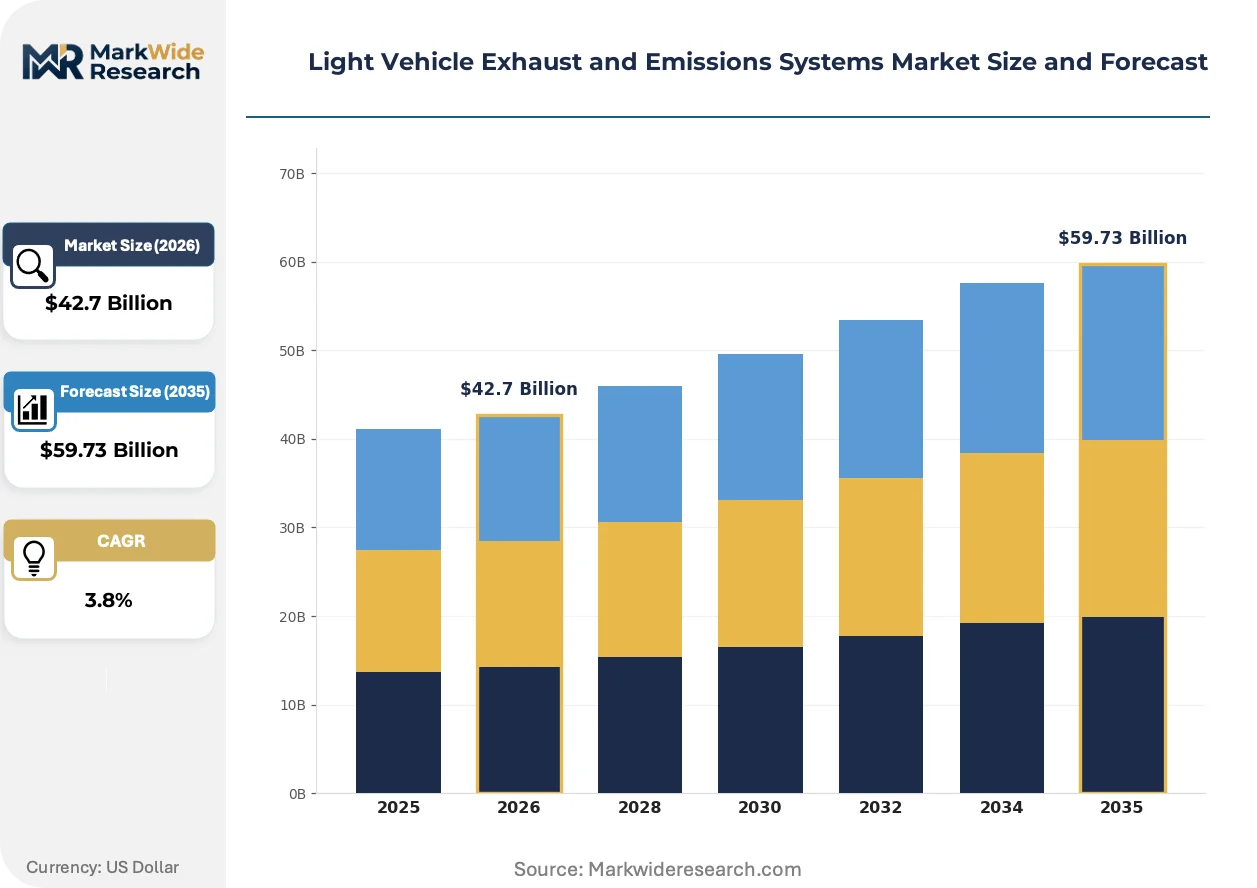
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $59.73 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
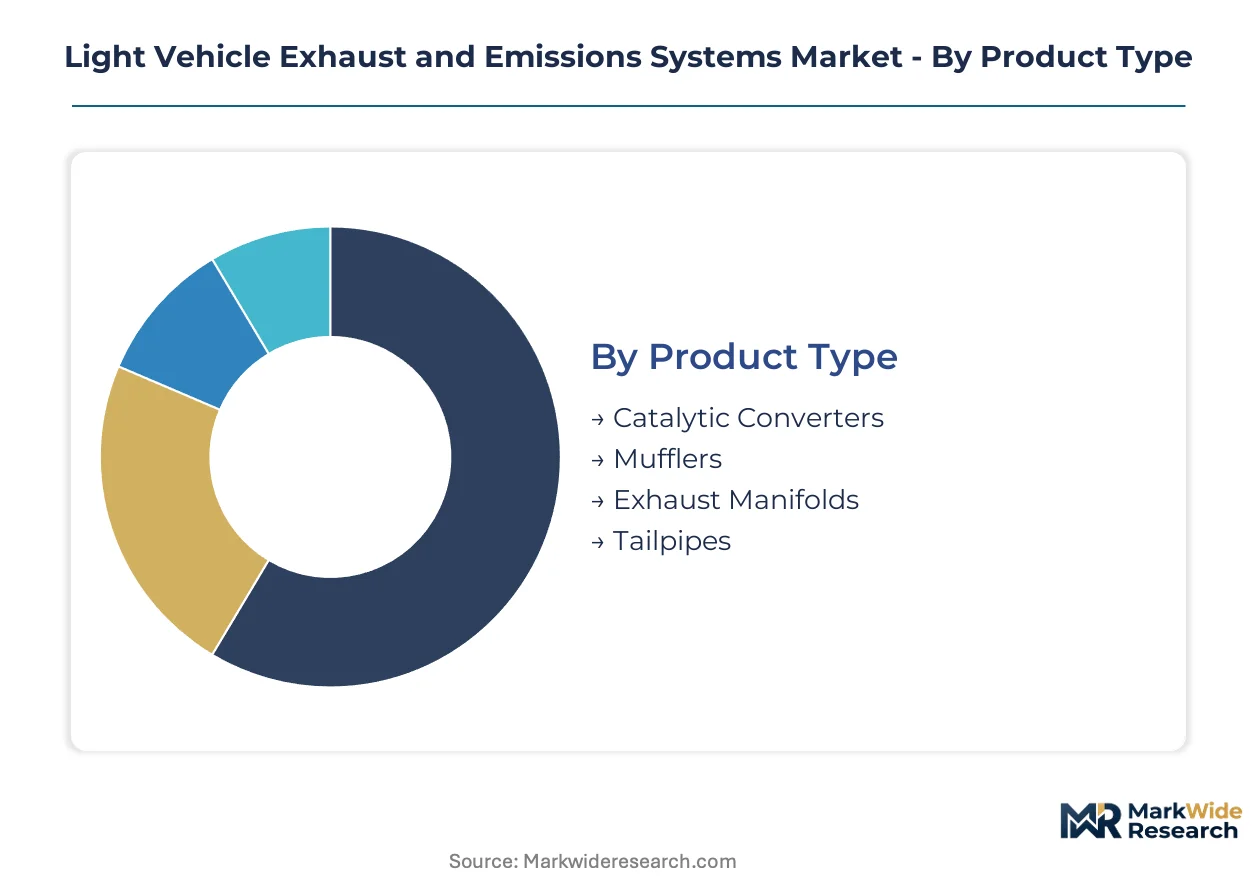
| Segmentation | Product Type: Catalytic Converters, Mufflers, Exhaust Manifolds, Tailpipes Technology: Three-Way Catalysts, Diesel Oxidation Catalysts, Selective Catalytic Reduction, Exhaust Gas Recirculation End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Certification: EPA Compliant, CARB Compliant, ISO Certified, Euro 6 Standards |
| Companies Covered | Forvia, Tenneco Inc., Eberspächer, Continental AG, Futaba Industrial Co., Ltd., Bosal, Benteler International AG, Sejong Industrial Co., Ltd., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Vehicle Exhaust and Emissions Systems Market Shifts & Advancements
Exhaust system architectures are fragmenting between legacy internal combustion optimization and hybrid-electric thermal management requirements, with material science and embedded electronics emerging as the primary vectors of supplier differentiation.
Gasoline particulate filter technology is supplanting conventional three-way catalysts as the primary hydrocarbon control mechanism in direct-injection engines. European OEMs have accelerated GPF fitment ahead of Euro 6d phase-in deadlines. The shift is compressing demand for traditional ceramic substrates while expanding addressable market for coated particulate filtration media.
REACH substance restrictions on nickel and hexavalent chromium coatings are forcing substrate suppliers toward alternative corrosion-resistant surface treatments. The European Chemicals Agency's evolving candidate list creates compliance uncertainty for long-life exhaust components. Manufacturers are responding with accelerated qualification of aluminized steel and ceramic-based protective layers.
Fleet operators are unbundling aftertreatment service contracts from powertrain warranties, creating direct procurement relationships with exhaust specialists. Commercial vehicle leasing companies in Germany now specify residual-value guarantees tied to verified catalyst performance. This channel shift concentrates buying power with large fleet aggregators while squeezing traditional dealer service margins.
Light Vehicle Exhaust and Emissions Systems Market Segmentation
Exhaust system suppliers structure product portfolios around regulatory certification tiers, hardware technology maturity, and channel-specific service requirements. Segmentation discipline determines which aftertreatment architectures capture platform engineering budgets versus aftermarket replacement cycles.
Product Type:
EPA Tier 3 and Euro 6 Standards impose divergent thermal and conversion efficiency specifications across hardware categories, forcing suppliers to maintain parallel substrate engineering tracks.
- Catalytic Converters:Ceramic honeycomb substrates coated with platinum-group metals enable simultaneous oxidation of carbon monoxide and hydrocarbons alongside NOx reduction. Demand concentrates in Germany and China where gasoline particulate filter integration is now mandatory for direct-injection engines under Euro 6d and GB VI Phase II enforcement.
- Mufflers:Multi-chamber acoustic attenuation chambers fabricated from aluminized or ferritic stainless steel manage backpressure while meeting pass-by noise limits. Fleet operators in California specify premium-grade units with extended corrosion warranties tied to CARB compliance verification.
- Exhaust Manifolds:Cast iron or tubular stainless steel headers channel combustion gases toward aftertreatment inlets.
- Tailpipes:Terminal exhaust outlets engineered for thermal durability and aesthetic finishing.
Catalytic converters handle the majority of throughput; mufflers are expanding most quickly on share as acoustic regulations tighten alongside emissions limits.
Technology:
Cost tier differentiation separates legacy oxidation chemistry from advanced urea-based NOx reduction architectures requiring dosing infrastructure integration.
- Three-Way Catalysts:Simultaneous reduction of NOx, CO, and unburned hydrocarbons through precisely balanced air-fuel ratio control. OEMs in the United States deploy these on port-injection gasoline platforms where EPA Tier 3 bin standards still permit conventional stoichiometric operation.
- Selective Catalytic Reduction:Urea decomposition over vanadium or zeolite catalysts achieves NOx conversion exceeding 90% in lean-burn conditions. China's Ministry of Ecology and Environment mandates SCR fitment on diesel passenger cars under GB VI, creating volume concentration absent from earlier regulatory phases.
- Diesel Oxidation Catalysts:Platinum-catalyzed oxidation of soluble organic fraction and carbon monoxide in diesel exhaust streams.
- Exhaust Gas Recirculation:Cooled exhaust recirculation to combustion chambers reduces peak flame temperatures and NOx formation rates.
Three-way catalysts retain dominant volume position; selective catalytic reduction is climbing the fastest as diesel and lean-gasoline architectures proliferate.
End User:
Customer type determines warranty responsibility, technical specification authority, and procurement contract structure across the hardware lifecycle.
- OEMs:Vehicle manufacturers specify integrated aftertreatment modules with 150,000-mile durability validation. Platform engineering decisions in Stuttgart and Detroit concentrate procurement with Tier 1 suppliers capable of simultaneous gasoline particulate filter and selective catalytic reduction production.
- Fleet Operators:Commercial leasing and logistics companies now contract directly for residual-value guarantees tied to verified catalyst performance. German fleet aggregators unbundle aftertreatment service from powertrain warranties, shifting specification authority away from franchised dealer networks.
- Aftermarket Providers:Independent distributors and installer networks serve replacement demand from aging vehicle populations.
- Vehicle Assemblers:Contract manufacturing operations without captive powertrain engineering capabilities.
OEMs command the specification pipeline; fleet operators are gaining share fastest through direct procurement restructuring.
Certification:
Geographic enforcement timing creates product variant complexity as jurisdictions phase in divergent limit values and test protocols.
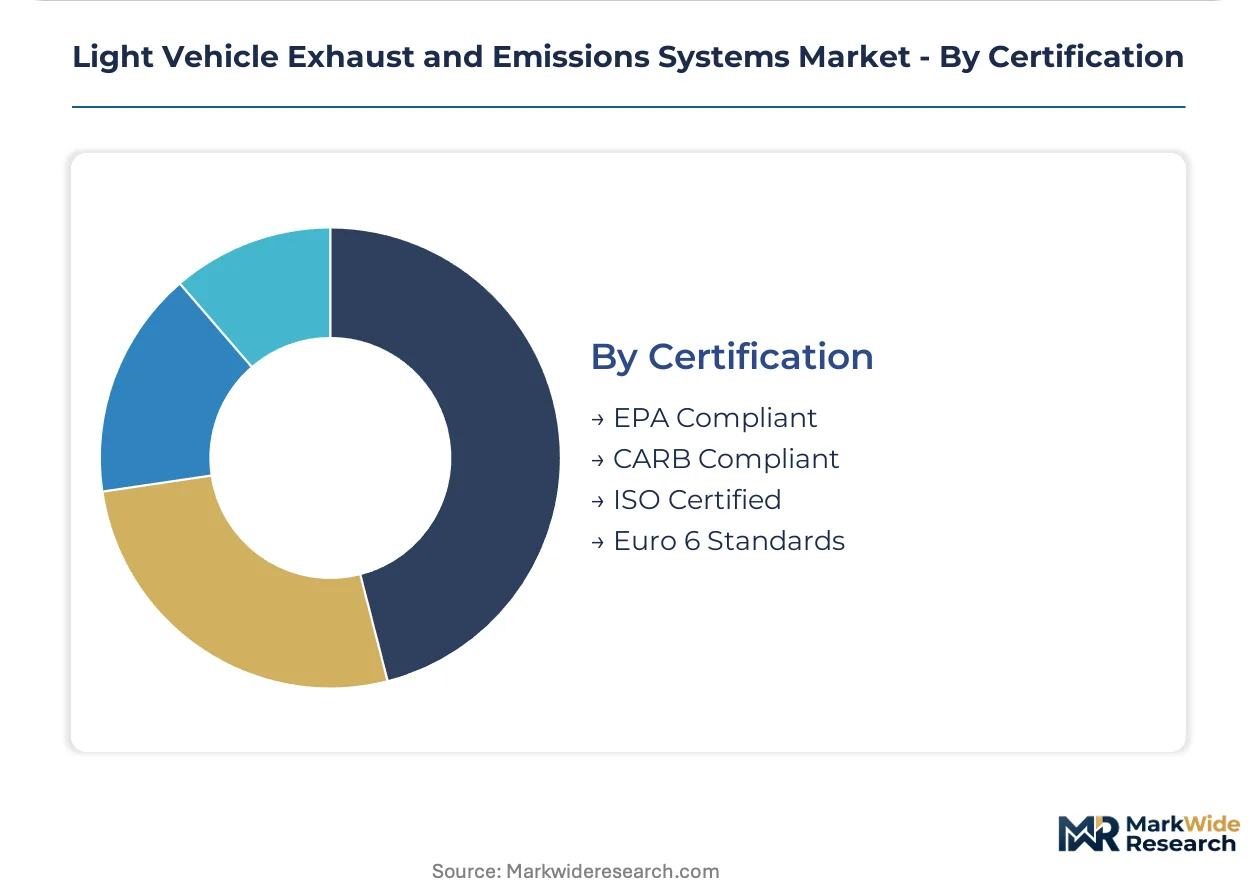
- Euro 6 Standards:European type-approval requirements encompassing real-driving emissions testing and particulate number limits. National authorities in Germany through KBA and France through ANSM enforce homologation deadlines that compress supplier validation calendars.
- EPA Compliant:Federal tailpipe standards administered by the Environmental Protection Agency across 50 states. Tier 3 bin categorization allows OEMs to trade fleet-average performance, sustaining demand for high-conversion catalysts on larger light trucks.
- CARB Compliant:California Air Resources Board standards adopted by 14 additional states, creating a distinct regulatory bloc within the US market.
- ISO Certified:Quality management and environmental management system verification for supplier facility accreditation.
Euro 6 Standards govern the largest certified volume base; CARB compliance is expanding most quickly as state adoption spreads beyond California.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 enforcement in the United States, Euro 6 Standards across Europe, and China's GB VI rollout are compressing compliance timelines and forcing localized aftertreatment hardware production. National regulators are phasing in divergent test protocols that fragment supplier engineering calendars.
United States
Light truck OEMs in Detroit and Dearborn are expanding gasoline particulate filter procurement to meet EPA Tier 3 bin standards for 2026 model years. The Environmental Protection Agency maintains fleet-average trading mechanisms that sustain demand for high-conversion catalysts on larger SUVs. Manufacturing clusters in Michigan and Ohio concentrate stamping and substrate coating operations for domestic pickup platforms.
Germany
Stuttgart-based OEMs are accelerating selective catalytic integration ahead of KBA-enforced Euro 6d real-driving emissions deadlines. The Kraftfahrt-Bundesamt compresses homologation timelines for gasoline direct-injection architectures requiring combined GPF-SCR modules. Engineering expertise clusters around Munich and Wolfsburg, where Tier 1 suppliers operate integrated thermal management development centers.
China
Domestic passenger car manufacturers in Shanghai and Guangzhou are adopting SCR systems for gasoline lean-burn engines under Ministry of Ecology and Environment GB VI Phase II mandates. The MEE's phased rollout creates volume concentration for urea dosing hardware previously absent from earlier regulatory phases. Yangtze River Delta production bases are adding catalyst coating lines to serve local OEM platform engineering.
Japan
Nagoya-area assemblers are optimizing three-way catalyst efficiency for hybrid-electric thermal cycling profiles under METI-coordinated emissions harmonization efforts. The Ministry of Economy, Trade and Industry supports substrate material research through designated automotive technology consortia. Chubu region suppliers specialize in thin-wall ceramic honeycomb production for compact vehicle architectures.
India
Passenger car producers in Pune and Chennai are integrating SCR modules ahead of BS VI Phase II real-driving emissions implementation. The Central Pollution Control Board's stricter testing protocols create first-mover advantage for suppliers with proven urea dosing calibration experience. Tamil Nadu manufacturing corridors are attracting exhaust system fabricators seeking proximity to Maruti Suzuki and Hyundai Motor India assembly plants.
Light Vehicle Exhaust and Emissions Systems Market Competitive Landscape
Player mix skews toward diversified automotive suppliers with captive emissions engineering capabilities, creating a tiered structure where full-system integrators coexist with substrate specialists and regional fabricators. Integrated platform suppliers compete on modular architecture design, while coating specialists differentiate through precious metal loading optimization. Dominant competitive moves include backward integration into ceramic substrate manufacturing and strategic partnerships with urea dosing system providers.
Within the diversified supplier tier, Tenneco Inc. and Continental AG exemplify full-system integrators capable of simultaneous gasoline particulate filter and selective catalytic reduction production. Eberspächer anchors the specialist archetype through concentrated exhaust technology focus. Denso Corporation occupies a position bridging electronics integration with aftertreatment hardware, reflecting the convergence of sensor architectures with thermal management systems.
| Leading Market Players |
|---|
| Forvia |
| Tenneco Inc. |
| Eberspächer |
| Continental AG |
| Futaba Industrial Co., Ltd. |
| Bosal |
| Benteler International AG |
| Sejong Industrial Co., Ltd. |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Euro 6 Standards certification gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while enabling premium positioning for KBA-validated system integrators serving Stuttgart OEM platforms.
Pricing Analysis
Certification level creates the primary spread across the pricing spectrum, with EPA Tier 3 bin compliance and Euro 6d real-driving emissions validation commanding substantial premiums over baseline ISO-certified hardware. Three-tier pricing structure across premium, standard, and economy levels reflects precious metal loading density, substrate wall thickness, and thermal durability guarantees. Cost compression in the economy tier is intensifying because Chinese domestic suppliers are adding coating capacity under GB VI Phase II mandates. Fleet operators represent the least price-sensitive buyer archetype, prioritizing residual-value guarantees over unit cost, while independent aftermarket distributors exhibit acute sensitivity to palladium and rhodium spot volatility.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are elevating inbound logistics costs for ceramic substrate imports, forcing European system integrators toward regional ferritic stainless steel sourcing. Manufacturing gravity centers on Germany, China, and the United States, with substrate coating operations clustering in the Yangtze River Delta and Michigan manufacturing corridors. Raw material dependencies rest on South African platinum-group metals, Australian aluminized steel feedstock, and Japanese ceramic honeycomb precursors. Single-source vulnerability concentrates in rhodium refining capacity, where limited geographic diversification exposes catalyst margins to supply disruption. Distribution runs through captive OEM supply agreements for original fitment, with independent aftermarket channels serving replacement cycles through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales, as fleet operators unbundle aftertreatment maintenance contracts from powertrain warranties and specify performance-based residual guarantees.
For Market Incumbents: Shield platform engineering relationships by securing captive urea dosing calibration capabilities before talent scarcity worsens, and add ceramic substrate coating capacity in the Yangtze River Delta to match Chinese OEM localization requirements. Battery electric vehicle substitution threatens long-term hardware volumes, making backward integration into sensor-embedded thermal management systems the critical defensive lever. For New Entrants and Emerging Players: Aftermarket catalyst remanufacturing represents an underserved service layer where incumbents lack specialized reverse-logistics infrastructure, creating white-space opportunity for independent operators. Target India's BS VI Phase II transition window, where proven SCR integration experience remains scarce among domestic suppliers, and enter through direct fleet procurement channels bypassing franchised dealer networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-embedded exhaust architectures, favoring asset-light coating specialists over integrated system fabricators. Acquisition candidates should demonstrate validated urea dosing algorithm libraries and established KBA homologation track records. The signal to monitor is divergence between EPA and MEE type-approval timelines, which would strain multi-jurisdiction suppliers and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Manufacturing | Captive honeycomb production insulates Tenneco and Continental from Japanese precursor supply constraints. |
| Urea Dosing System Partnership | SCR integration mandates under China's GB VI Phase II require aligned dosing hardware and catalyst chemistry. |
| Sensor-Embedded Exhaust Architecture Development | Convergence of NOx sensing with predictive thermal management enables closed-loop emissions optimization for Euro 6d. |
| Residual-Value Guarantee Structuring | German fleet aggregators now contract directly for verified catalyst performance, bypassing traditional dealer service margins. |
| Regional Manufacturing Footprint Expansion | Yangtze River Delta coating lines serve Shanghai OEM platform engineering under Ministry of Ecology and Environment mandates. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributor operations heads, and KBA homologation specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with exhaust system fabricators and thermal management R&D directors with secondary validation against vehicle production databases, IHS Markit registration data, EPA certification filings, and EMA type-approval records. Bottom-up volume modeling triangulated against top-down OEM platform engineering budgets across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regional vehicle production forecasts and precious metal consumption reports. The analytical framework modeled segmentation across propulsion architecture, aftertreatment technology tier, certification regime, and end-user channel throughout the projection horizon. CAGRs were derived from regression analysis of historical platform content trends and regulatory phase-in schedules, with specific inputs including Euro 6d real-driving emissions test protocol adoption curves and GB VI Phase II enforcement timelines.
Material uncertainties — battery electric vehicle substitution rates, palladium-rhodium price volatility, and regulatory timeline divergence between EPA and MEE — sit outside the modeled envelope. Forecasts reflect assumptions regarding OEM platform engineering continuity and fleet operator contract restructuring. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
North America Automotive Foams Market