
 Two Wheeler Rental Market | 2026-2036
Two Wheeler Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Rental Market Analytics
Tourism-dependent urban mobility is repositioning toward commuter and delivery applications in the two wheeler rental space. Lime leverages its battery-swapping infrastructure to sustain operational density in European micromobility corridors. Cityscoot anchors its competitive position through dockless scooter networks across Paris and Milan. Grow Mobility dominates Latin American markets with fleet scale that extends coverage into secondary cities.
Two wheeler rental encompasses short-term access to motorized scooters, motorcycles, mopeds, and electric vehicles through hourly to monthly pricing arrangements, typically managed via mobile applications with GPS tracking and digital payment integration. The service serves urban commuters seeking flexible mobility without ownership burdens, plus delivery platforms requiring surge fleet capacity. Self-drive and subscription models capture expanding margin pools as operators shift from pure ride-sharing toward recurring revenue structures. Electric vehicle segments within the fleet are accelerating fastest where municipal low-emission zones restrict internal combustion access.
India's Ministry of Road Transport and Highways enforces standardized helmet and vehicle fitness requirements that shape fleet composition decisions for rental operators. The European Union's F-Gas Regulation and impending Euro 5+ emission standards constrain internal combustion scooter availability in member states. Indonesia's Directorate General of Land Transportation mandates commercial vehicle permits that filter informal rental activity into licensed channels. Stakeholders must monitor how battery recycling directives and carbon accounting rules reshape total cost of ownership calculations across operating geographies.
Market Dynamics
Electric powertrain migration is compressing fleet operating costs while battery-swapping infrastructure investments are reshaping capital deployment patterns across urban rental networks. Operators face simultaneous pressure to electrify under municipal low-emission mandates and to absorb upfront asset replacement cycles.
Growth Catalysts
- FAME-II subsidy framework:India's electric mobility incentive structure reduces acquisition costs for fleet operators transitioning from internal combustion to battery-powered two-wheelers. The subsidy tiering favors commercial deployment volumes.
- Last-mile delivery surge:E-commerce logistics platforms across Indonesia, Vietnam, and the Philippines are contracting dedicated rental capacity to manage demand volatility without fixed asset ownership.
- Battery-swapping networks:Station-based exchange systems eliminate charging downtime for high-utilization fleets, enabling operational models that maximize vehicle turnover per unit.
Market Restraints
- Lithium-ion cell supply concentration:Cathode and cell manufacturing capacity clusters in China, creating import dependency and price volatility exposure for fleet operators outside that geography.
- Euro 5+ emission compliance costs:The European Union's tightening standards for internal combustion engines are forcing accelerated retirement of legacy scooter fleets before depreciation cycles complete.
- Insurance premium escalation:Underwriting losses in micromobility segments have hardened commercial liability rates, compressing per-unit margins for rental operators in dense urban corridors.
Strategic Opportunities
- Subscription revenue models:Monthly recurring structures for delivery couriers and commuters reduce customer acquisition costs and improve fleet utilization forecasting precision.
- Secondary city penetration:Bandung, Surabaya, and Medan in Indonesia exhibit rental demand growth with lower competitive density than Jakarta metro corridors.
- Carbon credit monetization:Municipal low-emission zone access permits and verified emission reduction certificates create ancillary revenue streams for electric fleet operators in European markets.
Industry Challenges
- Telematics integration complexity:Legacy fleet management platforms require substantial reconfiguration to interface with battery management systems and swap-station scheduling algorithms.
- Certification timeline compression:Type approval processes for electric two-wheelers under India's CMVR rules and European L-category directives are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Rental Market |
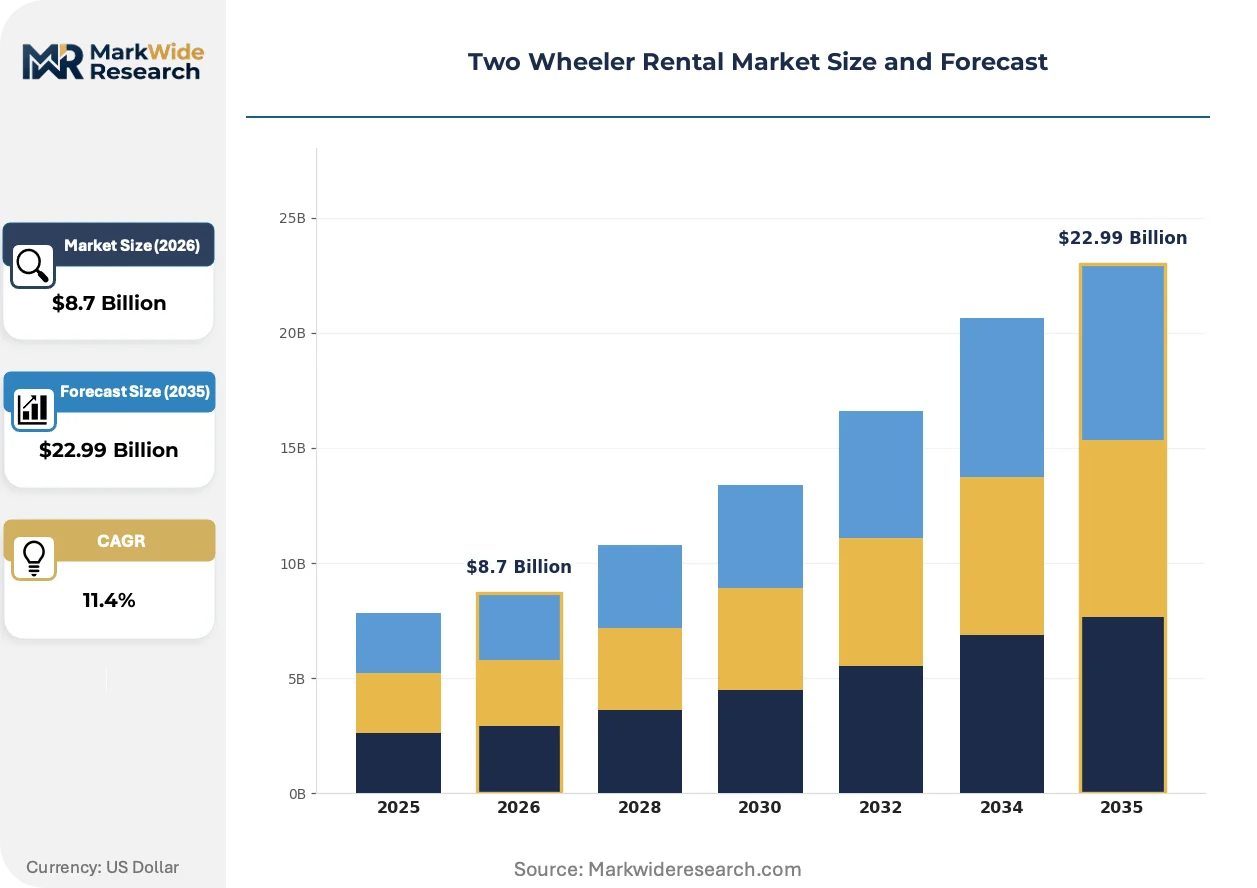
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Ride-Sharing, Subscription, Fleet Leasing Vehicle Type: Scooter, Motorcycle, Moped, Electric Vehicle Customer Type: Tourists, Commuters, Delivery Services, Local Residents Pricing Model: Hourly, Daily, Weekly, Monthly |
| Companies Covered | Grow Mobility, Cityscoot, Lime, Harley-Davidson, COUP, Bird, nextbike, Edelweiss Bike Travel, ofo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Rental Market Evolving Landscape
Operational technology stacks are converging around predictive maintenance algorithms and dynamic pricing engines that respond to real-time demand signals. Three developments are restructuring competitive capability requirements.
Battery-swapping infrastructure is consolidating as the dominant operational model for high-frequency rental applications. Delivery platforms and commuter services in Taipei, Seoul, and Hanoi are adopting station-based exchange systems that reduce vehicle downtime from hours to minutes. This consolidation is compressing competitive differentiation around network density rather than vehicle specifications.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon use in vehicle climate systems, forcing redesign of thermal management in electric two-wheelers. Manufacturers must reformulate cooling circuits and secure alternative refrigerant supply chains. The regulation most affects premium scooter segments where climate control is standard equipment, prompting accelerated R&D allocation.
Corporate procurement of mobility-as-a-service is displacing individual consumer subscriptions as the primary growth channel. Logistics platforms and gig-economy aggregators are negotiating enterprise rental agreements that guarantee fleet availability during peak demand windows. This shift is most visible in Southeast Asian markets where delivery volume concentration creates buyer power asymmetries.
Two Wheeler Rental Market Segmentation
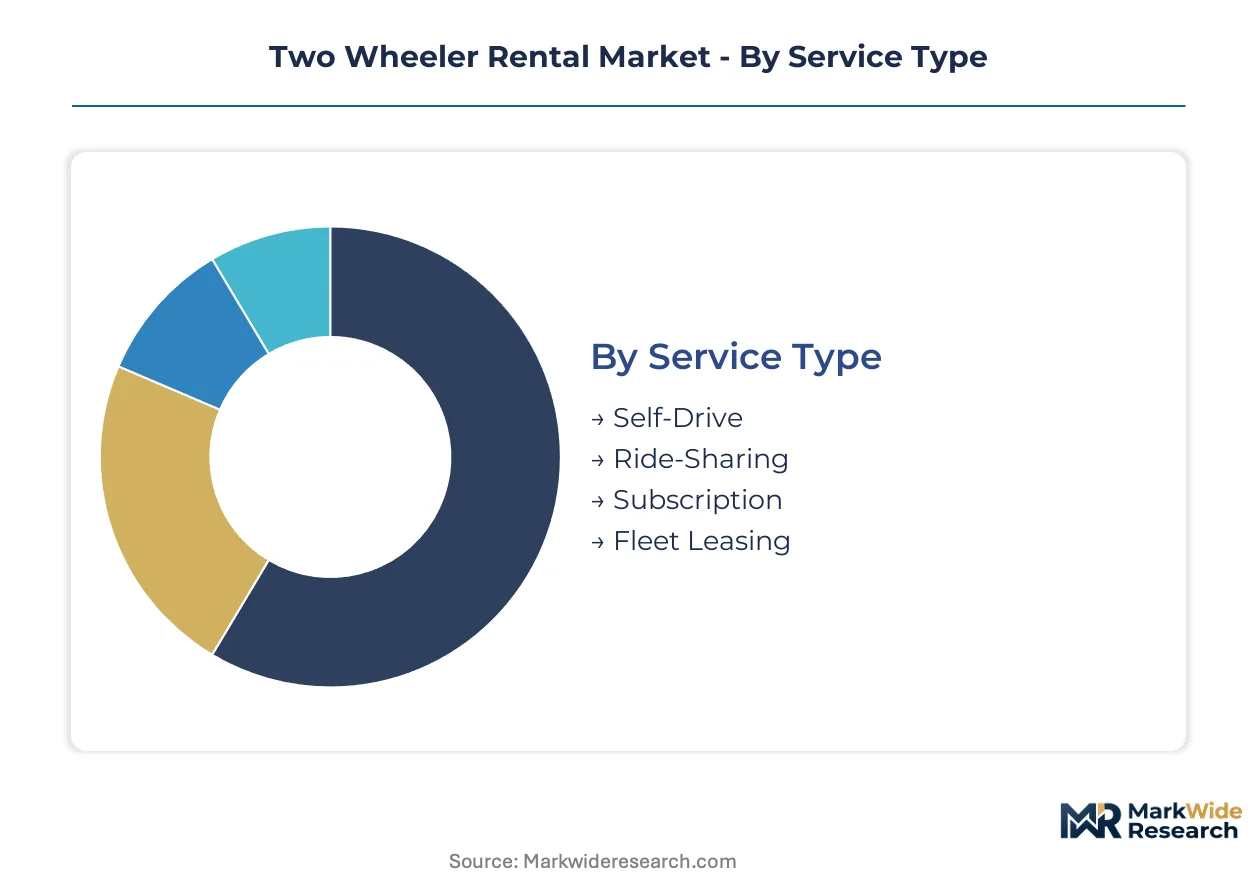
Segmentation in the two wheeler rental market reveals distinct operational economics across service models and vehicle categories. Fleet operators configure asset deployment differently for tourists versus delivery platforms, while pricing granularity shapes utilization patterns and margin capture.
Service Type:
Upgrade cycles across service models vary with asset intensity and customer retention profiles, creating divergent capital replacement schedules for operators.
- Self-Drive:Customers access vehicles through app-based unlocking with GPS-tracked per-minute or per-hour billing. Demand clusters in European micromobility corridors and Southeast Asian urban centers where tourists and commuters seek unscheduled flexibility without ownership burdens.
- Ride-Sharing:Platform-mediated trips connect passengers with driver-operated two-wheelers, common in Jakarta, Ho Chi Minh City, and Bangalore. Regulatory pressure from Indonesia's Directorate General of Land Transportation and India's state transport authorities is compressing informal operator participation.
- Subscription:Fixed monthly fees grant unlimited or high-volume access, capturing delivery couriers and daily commuters seeking predictable mobility costs.
- Fleet Leasing:Enterprise contracts provide dedicated vehicle pools to logistics platforms and food delivery aggregators, with terms spanning six to twenty-four months.
Self-Drive sits at the top of the volume ranking, with Subscription climbing the fastest as delivery platforms seek cost certainty.
Vehicle Type:
Cost tier positioning separates premium electric fleets from economy internal combustion deployments, with mid-range mopeds capturing price-sensitive commuter segments.
- Scooter:Step-through frames with automatic transmissions dominate Southeast Asian rental density, particularly in Indonesia's Jakarta-Bandung corridor where narrow street grids favor compact footprints.
- Motorcycle:Manual transmission units serve longer-distance commuters and intercity travelers across India and Vietnam, with engine displacements from 125cc to 200cc forming the commercial sweet spot.
- Moped:Low-speed restricted vehicles access bicycle lanes in European cities under L1e-A classification, with Paris and Milan operators exploiting regulatory carve-outs for sub-45 km/h speeds.
- Electric Vehicle:Battery-powered two-wheelers accelerate fastest where municipal low-emission zones restrict internal combustion access, with India's FAME-II subsidy tiering favoring commercial fleet adoption.
Scooter deployments generate the highest transaction frequency, while Electric Vehicle configurations gain share fastest under tightening emission mandates.
Customer Type:
Application concentration shapes fleet specification decisions, with delivery platforms demanding ruggedized builds and tourists prioritizing aesthetic appeal.
- Tourists:Short-term rentals spanning one to seven days concentrate in coastal and heritage destinations across Thailand, Bali, and Portugal's Algarve region.
- Commuters:Daily work-trip users in Manila, Bangkok, and São Paulo favor subscription or monthly passes that eliminate per-trip friction.
- Delivery Services:E-commerce logistics and food aggregators contract dedicated capacity across Indonesia, Vietnam, and the Philippines to manage demand volatility without fixed asset ownership.
- Local Residents:Occasional-use renters supplement public transit or replace secondary household vehicles, particularly prevalent in European cities with congestion charging.
Delivery Services anchor fleet utilization rates, with Commuter subscriptions expanding most quickly as operators shift toward recurring revenue structures.
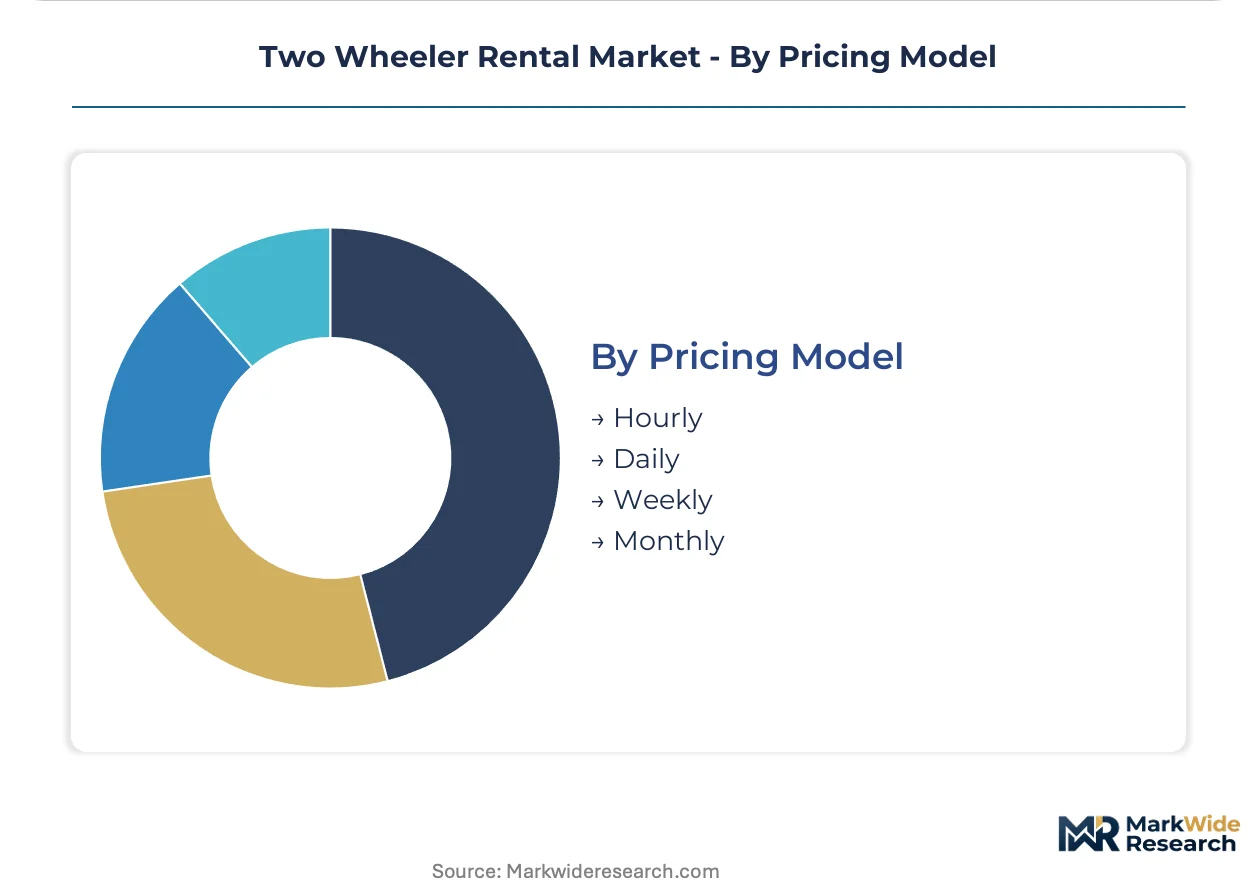
Pricing Model:
Margin profiles vary with duration commitment, with longer-term structures reducing customer acquisition costs and improving demand forecasting precision.
- Hourly:Micro-rentals capture impulse trips and errand completion, common in dense European city centers with competing micromobility options.
- Daily:Twenty-four-hour blocks serve tourists and day-trippers, with pricing typically bundling helmet and insurance to reduce transaction friction.
- Weekly:Seven-day terms attract extended-stay visitors and temporary workers, with operators offering discounted rates against daily accumulation.
- Monthly:Recurring subscriptions lock in delivery couriers and daily commuters, with Jakarta and Bangalore operators reporting highest retention in this tier.
Hourly transactions generate the highest revenue per vehicle-hour, while Monthly structures scale fastest as enterprise procurement displaces individual consumer adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta-Bandung corridor concentration anchors two-wheeler rental density in Southeast Asia, with electric fleet transitions accelerating across municipal low-emission zones and subsidy-enabled procurement reshaping operator economics in priority markets.
Indonesia
Last-mile delivery platforms drive rental adoption across the Jakarta-Bandung corridor where two-wheelers dominate commuter mobility. The Directorate General of Land Transportation mandates commercial vehicle permits that filter informal rental activity into licensed channels. Surabaya and Medan exhibit demand growth with lower competitive density than Jakarta metro corridors.
India
FAME-II subsidy tiering reduces acquisition costs for fleet operators transitioning from internal combustion to battery-powered two-wheelers. The Ministry of Road Transport and Highways enforces standardized helmet and vehicle fitness requirements that shape fleet composition decisions. Bangalore operators report highest retention in monthly subscription tiers among delivery couriers and daily commuters.
Vietnam
E-commerce logistics platforms contract dedicated rental capacity to manage demand volatility without fixed asset ownership. The country's national transport regulator maintains commercial licensing frameworks that formalize rental operator participation. Ho Chi Minh City anchors ride-sharing platform density where driver-operated two-wheelers connect passengers across urban corridors.
France
Dockless scooter networks exploit regulatory carve-outs for sub-45 km/h speeds under L1e-A classification in Paris and Milan corridors. The F-Gas Regulation phases down hydrofluorocarbon use in vehicle climate systems, forcing redesign of thermal management in electric two-wheelers. Paris operators concentrate network density around battery-swapping infrastructure to sustain operational velocity.
Germany
KBA type approval processes for electric two-wheelers under L-category directives extend product launch cycles for manufacturers. Euro 5+ emission standards force accelerated retirement of legacy scooter fleets before depreciation cycles complete. Berlin-Brandenburg micromobility corridors favor moped deployments that access bicycle lanes under restricted speed classifications.
Two Wheeler Rental Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators seek battery-swapping network scale and municipal permit security. The vendor base clusters around three archetypes: dockless micromobility platforms, subscription-focused fleet lessors, and tourism-oriented rental specialists. Consolidation pressure intensifies as delivery platforms negotiate enterprise agreements that guarantee fleet availability during peak demand windows. Geographic expansion and technology licensing represent the dominant competitive moves as operators replicate proven models across secondary cities.
Within the dockless platform tier, Lime and Bird exemplify battery-swapping infrastructure deployment across European and North American urban corridors. Cityscoot occupies a position representing station-based electric scooter networks anchored in Continental European density. Grow Mobility sits within the scale-driven archetype, with fleet coverage extending into Latin American secondary cities. These three operators represent divergent capital deployment strategies: asset-light technology licensing, owned-fleet network density, and geographic breadth through acquisition.
| Leading Market Players |
|---|
| Grow Mobility |
| Cityscoot |
| Lime |
| Harley-Davidson |
| COUP |
| Bird |
| nextbike |
| Edelweiss Bike Travel |
| ofo |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FAME-II subsidized electric fleets and unassisted internal combustion deployments splits pricing power across India's rental corridors, with subsidy-eligible operators capturing margin buffers that unsupported competitors cannot replicate while supply chains reorganize around battery-swapping station density rather than traditional dealership networks.
Pricing Analysis
Input-cost pass-through from lithium-ion cell volatility shapes subscription pricing across Southeast Asian rental markets. Three-tier pricing structure across premium battery-swapping, standard charging, and economy internal combustion tiers reflects utilization guarantees and infrastructure access. Pricing pressure stems from insurance premium escalation in dense urban corridors. Delivery platforms exhibit lowest price sensitivity due to enterprise volume commitments, while tourist segments demand per-hour transparency.
Supply Chain Analysis
Freight cost compression from China-dominated lithium-ion cell manufacturing concentrates cathode supply exposure for operators outside that geography. Battery cell production clusters in China, South Korea, and Japan. Fleet operators draw from semiconductor controllers, thermal management components, and chassis subassemblies. Single-source vulnerability in cell supply creates procurement risk. Distribution runs through manufacturer-direct fleet contracts and third-party leasing aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with India's FAME-II subsidy tiering and Indonesia's commercial permit mandates accelerating formalization of previously informal rental channels.
For Market Incumbents: Deepen battery-swapping network density across Jakarta-Bandung and Bangalore corridors to lock out challengers through station-based infrastructure moats. Acquire secondary-city permit portfolios in Surabaya and Medan before competitive entry accelerates. Battery supply agreement security represents the critical defensive lever against cell price volatility.
For New Entrants and Emerging Players: Launch via enterprise fleet leasing contracts targeting Vietnam's e-commerce logistics platforms, where demand volatility creates appetite for dedicated rental capacity without ownership burden. Secondary Indonesian cities offer lower competitive density than Jakarta metro corridors. Subscription revenue models reduce customer acquisition friction versus per-transaction alternatives.
For Investors and Strategic Acquirers: Asymmetric upside sits with operators holding integrated battery-swapping infrastructure and municipal permit security across multiple urban corridors. Five-to-ten year viability hinges on electrification mandate acceleration and subsidy continuity. Monitor India's CMVR type approval timeline compression as an inflection signal for product launch velocity and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Network Expansion | Station density in Jakarta and Bangalore eliminates charging downtime for high-utilization delivery fleets. |
| Enterprise Fleet Leasing Contracts | Guaranteed availability commitments from Vietnam's e-commerce platforms reduce utilization forecasting uncertainty. |
| FAME-II Subsidized Fleet Procurement | Tiered incentives favor commercial deployment volumes, compressing payback periods for electric transition. |
| Secondary City Permit Acquisition | Surabaya and Medan corridors offer expansion runway with lower competitive density than Jakarta. |
| Telematics Platform Integration | Predictive maintenance algorithms reduce downtime costs across high-turnover rental operations. |
Research Methodology
Coverage spans Southeast Asia, South Asia, and Continental Europe, with primary inputs from each region combining structured interviews with fleet operations directors, municipal transport regulators, battery supply procurement leads, and delivery platform logistics officers alongside secondary validation through customs trade databases, FAME-II subsidy disbursement records, and EU F-Gas Regulation compliance filings. Bottom-up fleet deployment counts triangulate against top-down market sizing from vehicle registration data and operator revenue disclosures.
Granularity extends to service-type, vehicle-type, customer-type, and pricing-model dimensions across the projection horizon, with electric versus internal combustion propulsion architecture modeled as a cross-cutting segment. CAGRs derive from fitted growth curves against historical fleet expansion trajectories and subsidy policy phase-out schedules. Forecast inputs incorporate battery cell price elasticity coefficients and municipal low-emission zone expansion timelines.
Several conditions sit outside the modeled scope, including abrupt subsidy cancellation, trade restriction imposition on lithium-ion cells, and pandemic-scale demand disruption. Forecasts reflect documented assumptions regarding policy continuity and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Bird Carriers Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Bike Rental Market
Transportation Services
United States Car Rental Market
Transportation Services
Middle East Car Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Benchmarking Services for Transportation Rates Market