
 France Automotive Parts Aluminium Die Casting Market | 2026-2036
France Automotive Parts Aluminium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Parts Aluminium Die Casting Market Foresight
The gap between premium structural castings and commodity engine brackets is expanding as OEMs reweight vehicle architectures toward electrification. Rheinmetall Automotive leverages its powertrain heritage to sustain dominance in transmission housings for hybrid platforms. Martinrea Honsel anchors its position through specialized vacuum-assisted casting for battery tray assemblies. Nemak differentiates via high-pressure die casting scale serving Renault and Stellantis assembly networks.
France Automotive Parts Aluminium Die Casting refers to the precision manufacture of aluminium alloy components—typically A380, A383, or Silafont-36 grades—through metal injection into hardened steel molds under pressures exceeding 1,000 bar, yielding near-net-shape parts with wall thicknesses below 3 millimetres for weight-critical automotive assemblies. Its primary purpose is to replace heavier ferrous castings and stamped steel assemblies in powertrain, chassis, and increasingly structural battery enclosures. Engine Components retain the largest volume share but carry thinning margins as internal combustion platforms decline. High Pressure Die Casting leads technology deployment for complex geometries at scale. Passenger Vehicles absorb the dominant share of output, though Commercial Trucks represent the fastest-growing application segment as electric truck platforms multiply.
ANSM and CNIL oversight intersects with EU REACH chemical compliance and the F-Gas Regulation governing foundry process emissions, collectively raising environmental compliance costs and reshaping supplier qualification criteria. The EU Green Deal carbon border adjustments and France's national low-carbon industry contracts are redirecting procurement toward foundries with verified Scope 1 and 2 reductions. Stakeholders must monitor how battery-electric platform standardization across French OEMs alters casting complexity requirements and supplier consolidation timelines.
Market Dynamics
Electric vehicle platform standardization across French OEMs is compressing casting complexity requirements while simultaneously expanding part size specifications for battery enclosures. This structural tension between simplification and scale-up is redrawing supplier qualification timelines and capital allocation priorities across the Greater Paris and Hauts-de-France foundry clusters.
Growth Catalysts
- EU CO2 fleet targets:Tightening emissions mandates force OEMs toward lightweight aluminium structural assemblies, expanding die-cast content per vehicle platform.
- France's national low-emission vehicle incentives:Purchase subsidies and tax advantages accelerate battery-electric vehicle adoption, multiplying demand for large-format battery tray castings.
- Silafont-36 alloy specifications:Advanced high-ductility aluminium grades enable thinner-wall castings for crash-critical EV structures, opening new application categories.
Market Restraints
- Primary aluminium price volatility:Energy-intensive smelting costs tied to European natural gas markets create margin compression for independent foundries without captive metal supply.
- ANSM process emission oversight:Stricter F-Gas Regulation compliance for die-casting cell emissions adds capital burden and extends environmental permitting timelines.
- Magnesium substitution threat:Thixomolding advances for seat frames and small structural brackets threaten to displace aluminium in sub-five-kilogram components.
Strategic Opportunities
- Hauts-de-France automotive cluster expansion:Proximity to Stellantis and Renault assembly plants creates geographic white space for dedicated EV-die-casting greenfield investments.
- Vacuum-assisted high-pressure die casting convergence:Combining vacuum degassing with traditional HPDC enables porosity-critical battery enclosure production at scale.
- France's national low-carbon industry contracts:Verified Scope 1 and 2 emission reductions unlock preferential procurement terms from state-backed OEM financing vehicles.
Industry Challenges
- Tooling engineer scarcity:Specialized die design expertise for large structural castings concentrates among aging specialists, constraining capacity expansion timelines.
- Heat treatment certification complexity:T7 temper specifications for crash-critical EV components require extended metallurgical validation cycles with ANSM documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Parts Aluminium Die Casting Market |
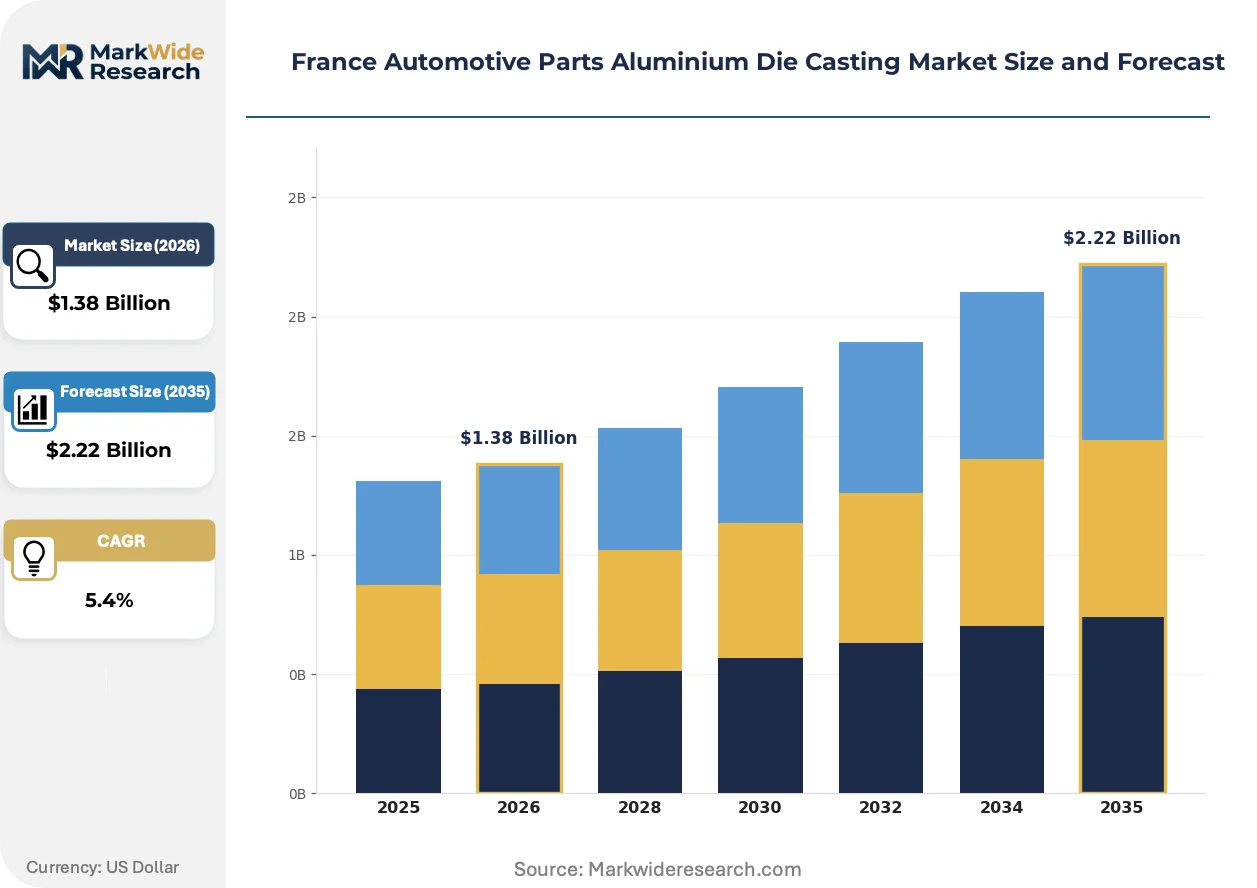
| Market Size in 2026 | $1.38 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Suspension Parts, Brake Components, Transmission Gears, Fuel System Parts Technology: High Pressure Die Casting, Gravity Die Casting, Low Pressure Die Casting, Squeeze Casting, Vacuum Die Casting Application: Passenger Vehicles, Commercial Trucks, Off-Road Vehicles, Agricultural Machines, Construction Equipment, Specialty Vehicles End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assembly Plants |
| Companies Covered | Rheinmetall Automotive, Fondarex SA, Martinrea Honsel, Linamar Corporation, Nemak, Ryobi Die Casting, Buhler Group, Alcoa, Georg Fischer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Parts Aluminium Die Casting Market Shifts & Advancements
Process intensification and regulatory stringency are converging to accelerate capital equipment refresh cycles across French foundry operations. The competitive frontier is shifting toward integrated process control rather than standalone casting capability.
Large-format high-pressure die casting for battery tray assemblies is electrifying the supplier landscape by collapsing multi-part welded assemblies into single castings. Renault and Stellantis procurement teams are specifying one-piece rear floor structures exceeding 1.5 meters in length. This format shift is compressing the viable supplier base to foundries with 4,000-ton-plus press capacity and in-house machining integration.
France's transposition of the EU Green Deal carbon border adjustment mechanism is tightening emission documentation requirements for imported primary aluminium. Foundries sourcing metal from non-EU smelters now face incremental compliance costs and supply qualification delays. The Hauts-de-France cluster is responding fastest through captive remelting investments and scrap-loop closure.
Consolidated platform sourcing contracts are displacing fragmented component-level procurement across French OEM supply chains. Battery-electric vehicle programs now specify single-source structural casting packages rather than distributed supplier panels. This concentration is most visible in the Greater Paris corridor, where Renault's ElectriCity manufacturing complex is bundling die-cast content into multi-year framework agreements.
France Automotive Parts Aluminium Die Casting Market Segmentation
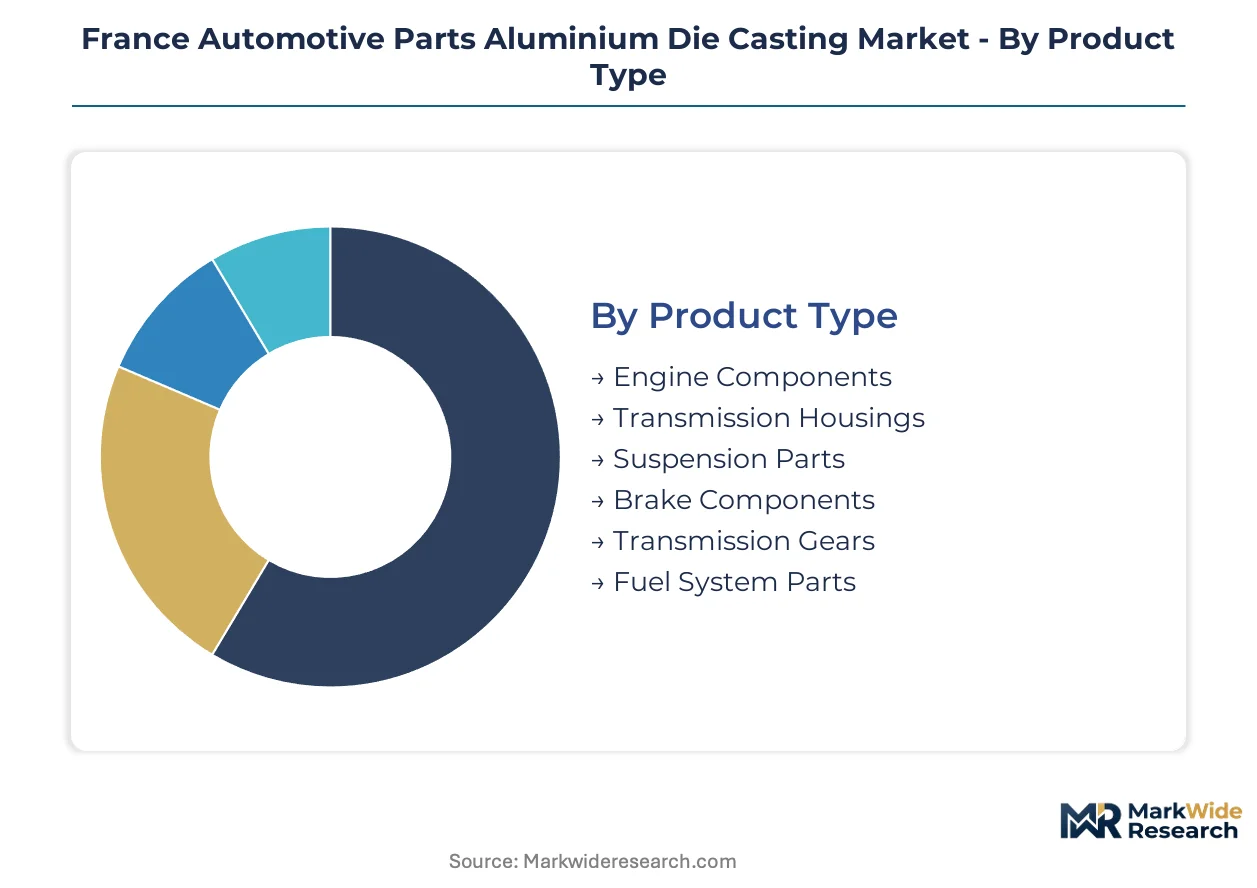
Segmentation in France's aluminium die casting market reveals how regulatory pressure and electrification are fragmenting legacy supply structures. Each dimension carries distinct certification burdens and capital requirements that determine supplier viability across the Greater Paris and Hauts-de-France corridors.
Product Type:
ANSM documentation requirements and T7 temper certifications apply unevenly across product categories, with crash-critical segments demanding extended metallurgical validation cycles that constrain supplier qualification timelines.
- Engine Components:Cylinder heads, engine blocks, and intake manifolds cast from A380 and A383 alloys retain the largest volume share. Demand concentrates in hybrid powertrain programs serving Renault and Stellantis assembly networks, though margins compress as internal combustion platforms decline.
- Transmission Housings:Clutch housings and gearbox casings require vacuum-assisted casting to achieve porosity specifications for fluid retention. Rheinmetall Automotive sustains dominance here through powertrain heritage and captive machining integration.
- Suspension Parts:Control arms and knuckles cast from Silafont-36 for ductility requirements.
- Brake Components:Caliper housings and master cylinder bodies with thermal conductivity specifications.
- Transmission Gears:Squeeze-cast gear blanks requiring near-net-shape precision.
- Fuel System Parts:Pump housings and filter bases facing demand erosion from electrification.
Leading the category by volume: Engine Components. Growing fastest: Transmission Housings.
Technology:
Capital intensity and process control sophistication stratify the technology landscape, with 4,000-ton-plus press capacity becoming the threshold for structural EV component contracts.
- High Pressure Die Casting:Metal injection exceeding 1,000 bar into hardened steel molds yields near-net-shape parts with wall thicknesses below 3 millimetres. Nemak leverages HPDC scale across Renault and Stellantis supply chains, though tooling engineer scarcity constrains capacity expansion timelines.
- Gravity Die Casting:Molten metal poured under gravity suits thicker-walled components with lower complexity requirements.
- Low Pressure Die Casting:Controlled metal rise from below reduces porosity for fluid-carrying applications.
- Squeeze Casting:Solidification under mechanical pressure eliminates shrinkage porosity for high-integrity gears.
- Vacuum Die Casting:Martinrea Honsel anchors market position through specialized vacuum-assisted casting for battery tray assemblies, combining vacuum degassing with traditional HPDC to enable porosity-critical battery enclosure production at scale.
HPDC dominates volume. Vacuum Die Casting climbs the fastest on EV structural demand.
Application:
Vehicle electrification intensity determines casting content per platform, with battery-electric architectures multiplying aluminium intensity despite powertrain simplification.
- Passenger Vehicles:Renault's ElectriCity manufacturing complex bundles die-cast content into multi-year framework agreements, absorbing the dominant share of French output. Platform standardization across French OEMs compresses casting complexity while expanding part size specifications for battery enclosures.
- Commercial Trucks:Electric truck platform multiplication drives the steepest expansion trajectory, with large-format battery tray castings exceeding 1.5 meters in length now specified for one-piece rear floor structures.
- Off-Road Vehicles:Construction and mining equipment with durability requirements.
- Agricultural Machines:Tractor transmission housings and hydraulic components.
- Construction Equipment:Excavator and loader structural castings.
- Specialty Vehicles:Ambulance and fire truck body structures with low volume, high customization.
Passenger Vehicles anchor volume. Commercial Trucks gain share fastest on electrification.
End User:
Procurement consolidation toward single-source structural casting packages is displacing fragmented component-level supply relationships across French OEM networks.
- OEM Manufacturers:Renault and Stellantis direct procurement of battery-electric platform castings concentrates demand among qualified suppliers with verified Scope 1 and 2 emission reductions.
- Tier-1 Suppliers:Rheinmetall Automotive and Martinrea Honsel intermediate between foundries and assembly plants, managing ANSM compliance documentation.
- Aftermarket Providers:Replacement engine and transmission components with lower regulatory scrutiny.
- Vehicle Assembly Plants:Renault's ElectriCity and Stellantis Sochaux facilities with just-in-sequence casting delivery requirements.
OEM Manufacturers command the volume. Tier-1 Suppliers expand most quickly on outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Paris industrial corridor anchors French aluminium die casting capacity, with Renault's ElectriCity complex and Stellantis assembly networks concentrating demand for large-format structural castings across the Île-de-France region.
Île-de-France
Renault's ElectriCity manufacturing hub in Flins drives procurement consolidation for battery tray castings exceeding 1.5 meters. ANSM oversight intersects with EU F-Gas Regulation compliance for die-casting cell emissions. The Greater Paris corridor bundles multi-year framework agreements, compressing supplier qualification timelines toward foundries with verified Scope 1 and 2 reductions.
Hauts-de-France
Proximity to Stellantis Douvrin and Renault Maubeuge plants generates geographic white space for dedicated EV-die-casting greenfield investments. France's national low-carbon industry contracts redirect procurement toward facilities with captive remelting capabilities. The Douai-Lens industrial basin attracts vacuum-assisted high-pressure die casting capacity for porosity-critical battery enclosures.
Auvergne-Rhône-Alpes
Silafont-36 alloy specifications for crash-critical EV structures concentrate metallurgical validation activity around Lyon-based testing laboratories. EU REACH chemical compliance tightens material documentation across the supply chain. The Saint-Étienne foundry cluster specializes in T7 temper certification for high-ductility suspension components.
Provence-Alpes-Côte d'Azur
Specialty vehicle manufacturers in the Var and Bouches-du-Rhône departments sustain demand for low-volume, high-customization castings. CNIL data governance requirements intersect with OEM traceability mandates for battery component sourcing. The Marseille-Fos port corridor facilitates primary aluminium import logistics for independent foundries without captive metal supply.
Nouvelle-Aquitaine
Agricultural machinery transmission housings anchor legacy demand in the Limoges and Poitiers industrial zones. EU Green Deal carbon border adjustments raise compliance costs for non-EU primary aluminium sourcing. The Bordeaux-Toulouse axis hosts squeeze-casting specialists serving construction equipment durability requirements.
France Automotive Parts Aluminium Die Casting Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated supplier base. Integrated foundries with 4,000-ton-plus press capacity and in-house machining capture structural EV contracts, while smaller operators concentrate on legacy engine components with thinning margins. Three archetypes dominate: powertrain heritage players leveraging transmission expertise, vacuum-casting specialists securing battery enclosure niches, and high-pressure scale operators serving consolidated OEM platforms. Competitive dynamics center on multi-year framework agreement capture and captive remelting investments that insulate against primary aluminium price volatility.
Within the integrated foundry tier, Rheinmetall Automotive and Martinrea Honsel exemplify divergent specialization strategies. Rheinmetall occupies a position tied to powertrain heritage and transmission housing scale, while Martinrea Honsel anchors the vacuum-assisted casting segment for battery tray applications. Nemak represents the high-pressure die casting archetype, serving consolidated Renault and Stellantis platform sourcing. Among equipment and materials suppliers, Buhler Group and Alcoa sit within the capital goods and primary metal tiers respectively, with Georg Fischer representing Swiss-based precision casting technology. Fondarex SA exemplifies mid-cap foundry positioning within French industrial clusters, while Linamar Corporation and Ryobi Die Casting represent North American and Japanese multinational presence in European automotive supply chains.
| Leading Market Players |
|---|
| Rheinmetall Automotive |
| Fondarex SA |
| Martinrea Honsel |
| Linamar Corporation |
| Nemak |
| Ryobi Die Casting |
| Buhler Group |
| Alcoa |
| Georg Fischer |
| Others |
Supply & Pricing Matrix
France's national low-carbon industry contracts gate qualified supply access and premium-tier pricing power by mandating verified Scope 1 and 2 emission reductions for OEM procurement eligibility. Foundries without captive remelting capabilities or ANSM-compliant environmental documentation face exclusion from multi-year framework agreements, compressing margins to commodity levels while certified suppliers command structural premiums.
Pricing Analysis
Throughput-based pricing anchored to press utilization rates and T7 temper certification outcomes dominates contract structures for large-format battery tray castings. Premium-mid-economy pricing differentiation separates foundries with 4,000-ton-plus press capacity and in-house machining integration from smaller operators serving legacy engine components. Cost compression in the engine component tier is intensifying because internal combustion platform volumes decline faster than fixed cost absorption allows. Tier-1 suppliers with vacuum-assisted casting capabilities exhibit lowest price sensitivity due to sole-source positioning for porosity-critical EV enclosures.
Supply Chain Analysis
Tooling engineer scarcity across the Greater Paris and Hauts-de-France corridors constrains capacity expansion timelines and inflates specialized die design costs. Primary aluminium sourcing draws from Norwegian smelters with verified low-carbon profiles and German remelting facilities serving captive loop closures. Single-source vulnerability concentrates in large-format press capacity, where only three qualified suppliers operate presses exceeding 4,000 tons within France. Distribution runs through Renault's ElectriCity and Stellantis Sochaux facilities with just-in-sequence casting delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU Green Deal carbon border adjustments force weaker independent foundries without captive metal supply toward exit or acquisition.
For Market Incumbents: Extend vacuum-assisted high-pressure die casting capabilities into the Hauts-de-France cluster to capture Stellantis Douvrin procurement consolidation. Deepen backward integration into captive remelting to insulate against primary aluminium price volatility tied to European natural gas markets. Secure ANSM T7 temper certifications ahead of competitor qualification timelines for crash-critical EV structural components. For New Entrants and Emerging Players: Launch via specialized Silafont-36 alloy processing for suspension control arms and knuckles in the Auvergne-Rhône-Alpes testing corridor. Target the electric commercial truck battery enclosure segment where format specifications exceed incumbent casting capacity. Enter through joint development agreements with Lyon-based metallurgical laboratories to accelerate T7 temper validation cycles. For Investors and Strategic Acquirers: Renault's ElectriCity bundling of multi-year framework agreements into single-source structural casting packages is the leading indicator that platform-level supplier consolidation is accelerating. Five-to-ten year viability favors foundries with verified low-carbon profiles and 4,000-ton-plus press capacity. Watch for ANSM documentation completion as the inflection signal for qualification timeline compression and premium pricing access.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Remelting Investment | EU Green Deal carbon border adjustments raise compliance costs for non-EU primary aluminium sourcing. |
| Vacuum-Assisted HPDC Capacity Expansion | Renault and Stellantis specify one-piece rear floor structures exceeding 1.5 meters for battery enclosures. |
| T7 Temper Certification Acceleration | ANSM documentation requirements for crash-critical EV components constrain supplier qualification timelines. |
| Hauts-de-France Greenfield Positioning | Proximity to Stellantis Douvrin and Renault Maubeuge plants creates geographic white space for EV-dedicated capacity. |
| Silafont-36 Alloy Specialization | Advanced high-ductility specifications enable thinner-wall castings for crash-critical EV suspension structures. |
Research Methodology
Trade statistics from Eurostat, French customs records, and EU F-Gas Regulation compliance filings formed the secondary backbone, cross-referenced with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, foundry operations managers, and ANSM regulatory affairs specialists. Bottom-up volume estimates derived from Renault and Stellantis production schedules triangulated against top-down aluminium consumption data from European smelter associations.
Bottom-up modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions fed into CAGR derivation through regression analysis of historical platform adoption curves and electrification intensity projections. Foundry capacity utilization rates, press tonnage distribution, and T7 temper certification timelines served as industry-specific forecast inputs throughout the projection horizon.
Primary aluminium price volatility, ANSM permitting delays, and magnesium substitution advances in sub-five-kilogram components are the dominant revision risks to volume and value assumptions. Material deviation in any of these triggers warrants pause and re-evaluation of supplier viability and pricing power assessments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Speed Bump Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
France Automotive Lubricants Market