
 Automotive All Wheel Drive Market | 2026-2036
Automotive All Wheel Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive All Wheel Drive Market Outlook
ISO 26262 functional safety certification is unwinding competitive access for Tier-2 suppliers lacking ASIL-D validation capabilities. BorgWarner Inc. leverages its clutch-module manufacturing scale to dominate North American light-truck AWD sourcing. ZF Friedrichshafen AG anchors European premium-vehicle torque-vectoring programs through integrated mechatronic architectures. Magna International Inc. extends its position in full-time AWD systems via manufacturing footprints in Canada, Austria, and China.
Automotive all wheel drive denotes a powertrain architecture distributing engine torque to all four wheels through mechanical, electronic, or hydraulic coupling systems, typically engaging multi-plate clutches, transfer cases, or electric axle drives to maintain traction across variable surfaces. The primary commercial purpose centers on enhancing vehicle stability, launch performance, and off-road capability while managing fuel consumption through selective torque apportionment. Full-time AWD systems retain established share in luxury SUVs and performance sedans where continuous torque distribution defines brand positioning. On-demand architectures capture expanding application in crossover vehicles as automakers prioritize weight reduction and efficiency compliance. Electronic torque-vectoring technology leads differentiation strategies among premium OEMs seeking dynamic handling advantages.
NHTSA rollover-resistance standards and EPA corporate average fuel economy mandates in the United States compel automakers to optimize AWD system mass and parasitic losses. ECE Regulation 13-H braking stability requirements and EU CO2 fleet targets in Europe shape electronic AWD calibration priorities for export-bound vehicles. China's MIIT new-energy vehicle technical standards and GB/T homologation protocols govern AWD integration into dual-motor electric platforms. Stakeholders must monitor regulatory divergence between thermal-efficiency mandates and electrification timelines to align R&D allocation across mechanical and electric axle architectures.
Market Dynamics
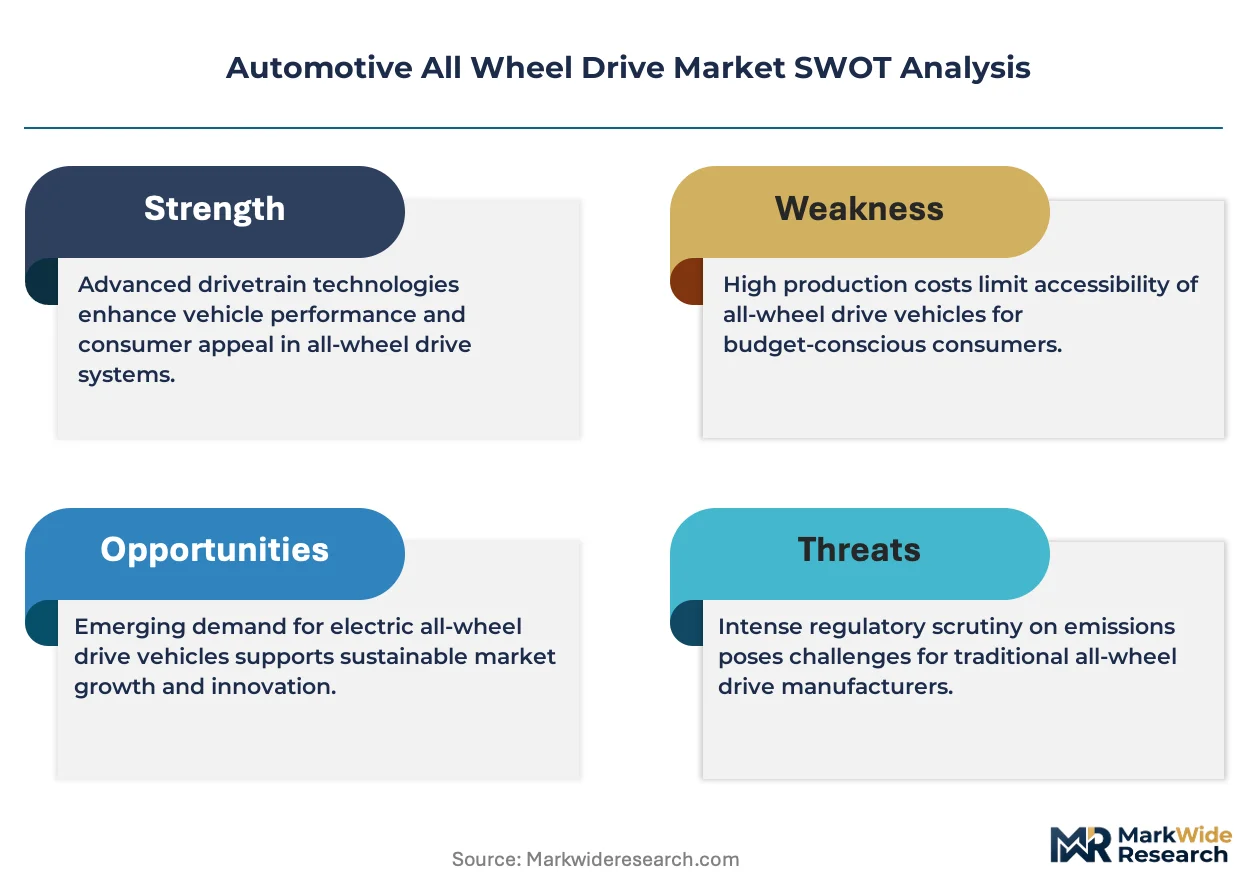
Electric axle architectures are compressing development cycles for mechanical AWD suppliers as OEMs prioritize dual-motor torque distribution over clutch-based systems. Tier-1 suppliers face capital reallocation toward mechatronic integration capabilities.
Growth Catalysts
- NHTSA Rollover-Resistance Mandates:US safety standards compel crossover manufacturers to fit on-demand AWD as standard equipment, expanding addressable volume in the light-truck segment.
- Dual-Motor EV Platforms:Chinese MIIT technical standards for new-energy vehicles accelerate adoption of software-defined torque vectoring without mechanical differentials.
- Performance Sedan Differentiation:European premium OEMs specify full-time torque-vectoring systems to maintain handling advantages against rear-wheel-drive competitors.
Market Restraints
- ASIL-D Certification Barriers:ISO 26262 functional safety requirements exclude Tier-2 clutch suppliers from torque-vectoring programs, concentrating sourcing among validated Tier-1s.
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings in Chinese processing facilities inflate electric axle motor costs, compressing margins on dual-motor AWD architectures.
- Lightweighting Trade-offs:Aluminum transfer case housings sacrifice durability ratings required for heavy-duty pickup applications, limiting material substitution in North American truck platforms.
Strategic Opportunities
- India Sub-4-Meter SUV Segment:Domestic OEMs lack localized AWD component sourcing, creating entry points for clutch-module suppliers establishing joint ventures with Pune and Chennai manufacturing clusters.
- EU Battery Passport Integration:CSRD supply-chain disclosure requirements favor AWD systems with embedded carbon accounting, rewarding suppliers with lifecycle transparency tools.
- Software-Defined Torque Mapping:Over-the-air calibration updates enable subscription revenue models for dynamic handling packages in premium electric crossovers.
Industry Challenges
- Mechatronics Talent Scarcity:Control algorithm engineers with combined mechanical-electronics expertise command premium compensation, constraining R&D team expansion at mid-cap suppliers.
- Legacy Powertrain Integration:Internal combustion AWD architectures require extensive recalibration to interface with hybrid electric axles, extending validation timelines by 8-14 months.
- Homologation Divergence:Separate EPA fuel-economy test cycles and WLTP protocols force redundant certification investments for global vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive All Wheel Drive Market |
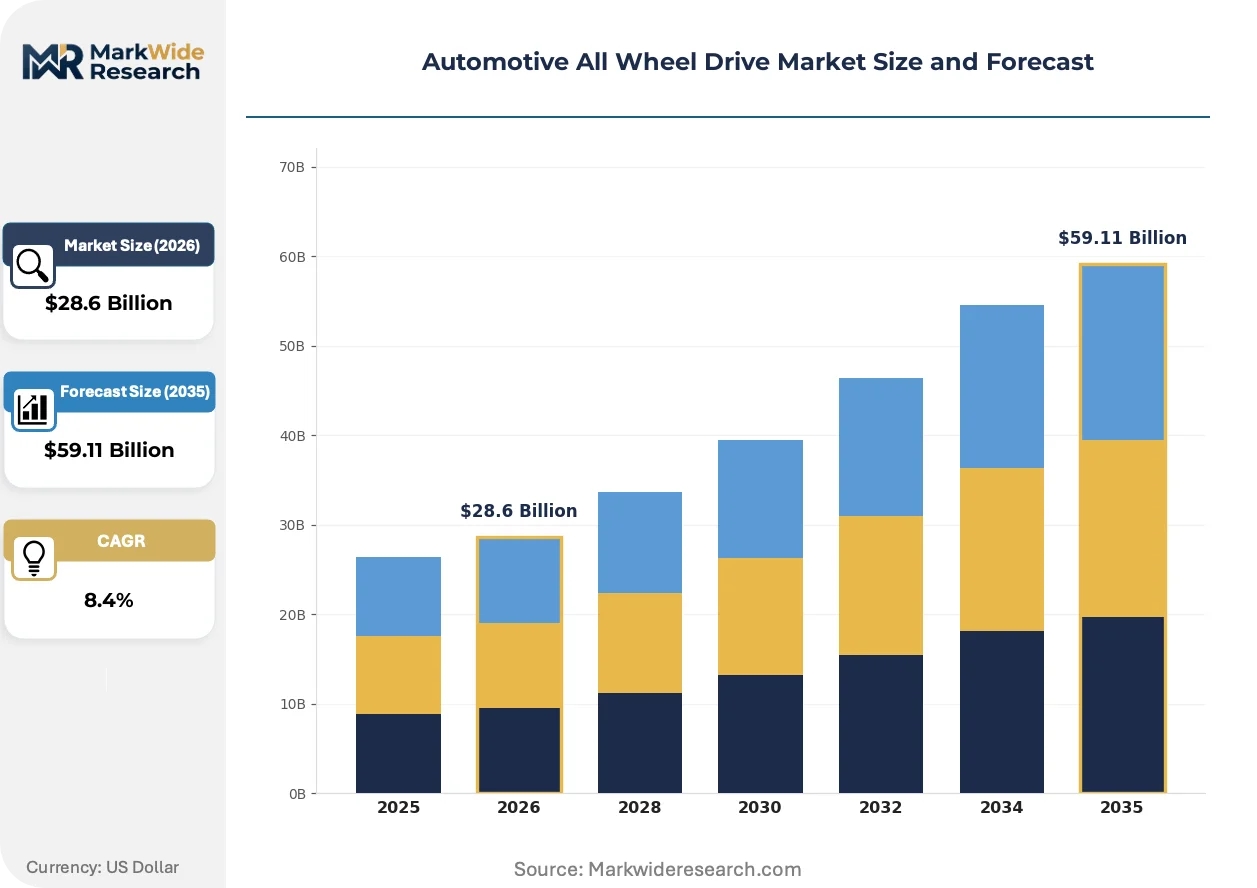
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drive Type: Full-Time, Part-Time, On-Demand, AWD with Torque Vectoring Vehicle Type: SUV, Sedan, Crossover, Truck Technology: Mechanical, Electronic, Adaptive, Hydraulic End User: Consumer, Fleet, Government, Commercial |
| Companies Covered | BorgWarner Inc., ZF Friedrichshafen AG, Magna International Inc., JTEKT Corporation, GKN Automotive, Continental AG, American Axle & Manufacturing, Dana Inc., Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive All Wheel Drive Market Strategic Shifts
Decoupling of mechanical drivetrains from vehicle control logic is redistributing value toward software and power electronics. Suppliers must reconfigure engineering organizations around mechatronic integration rather than discrete component manufacturing.
Multi-plate wet clutches with integrated position sensors are supplanting purely hydraulic actuation in on-demand AWD systems. Crossover OEMs in Germany and Japan specify these electromechanical units for sub-100-millisecond engagement speeds. The technology is compressing Tier-2 hydraulic component markets while elevating firmware development to primary supplier responsibility.
EPA corporate average fuel economy mandates and WLTP CO2 fleet targets are forcing mass reduction in full-time AWD hardware. European luxury SUV programs now specify hollow-shaft half-shafts and aluminum carrier housings to offset electric axle weight penalties. North American light-truck platforms lag this transition due to towing-capacity retention requirements.
Fleet procurement of AWD crossovers for last-mile delivery services is altering volume concentration toward commercial channel managers. Amazon Logistics and DHL Express specifications prioritize total cost of ownership over upfront acquisition cost, favoring on-demand architectures with predictive engagement algorithms. This pattern is most pronounced in German and British urban logistics networks where winter traction mandates intersect with electrification timelines.
Automotive All Wheel Drive Market Segmentation
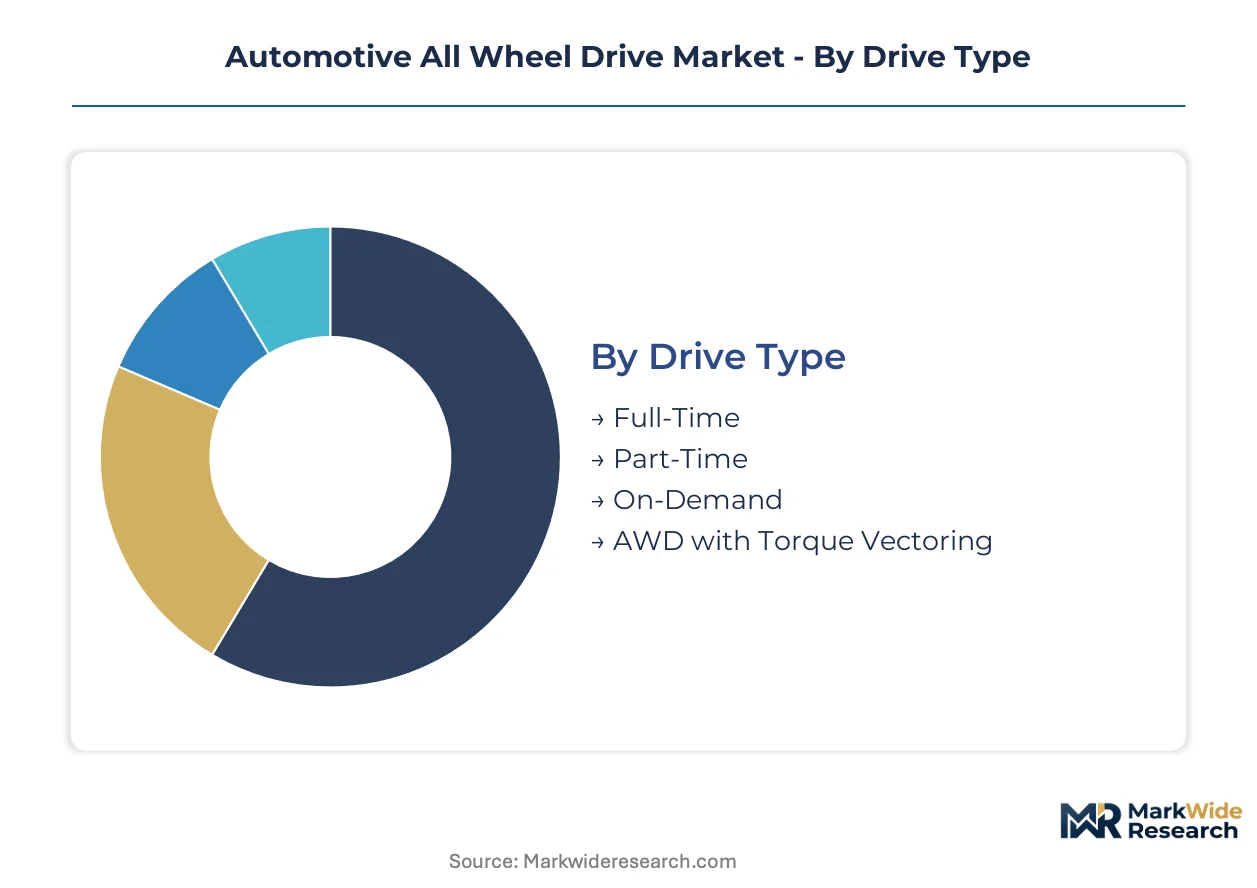
Segmentation in the automotive all wheel drive market reveals divergent technology investments across vehicle architectures. OEM sourcing decisions split between mechanical legacy systems and electrified torque-vectoring platforms, with regulatory pressure and application requirements determining allocation priorities.
Drive Type:
Domestic assembly lines in China, Germany, and Japan concentrate sourcing for full-time and torque-vectoring architectures, while export-oriented plants in Mexico and Thailand favor on-demand systems for fuel-economy compliance.
- Full-Time:Continuous torque distribution through center differentials defines premium SUV and performance sedan positioning. North American luxury manufacturers specify these systems for towing-capacity retention and brand differentiation in the light-truck segment.
- On-Demand:Electromechanical clutch modules engage rear axles only when slip detection triggers. Chinese crossover OEMs and European compact SUV programs prioritize this architecture to meet WLTP CO2 fleet targets without sacrificing all-weather capability.
- Part-Time:Driver-selectable engagement via transfer case dominates off-road specialty vehicles and select heavy-duty pickup configurations.
- AWD with Torque Vectoring:Dual-motor electric platforms in premium Chinese and German EV lineups deploy software-defined lateral torque distribution.
Full-Time commands the established base. The steepest expansion runs through AWD with Torque Vectoring.
Vehicle Type:
Cost tier segmentation separates mass-market crossover deployments from premium sedan and truck applications requiring validated durability ratings.
- SUV:Three-row and compact SUV architectures generate the highest AWD attachment rates globally, with full-time systems standard in luxury segments and on-demand architectures penetrating mass-market tiers.
- Crossover:Unibody platforms prioritize weight-optimized on-demand systems. Japanese and Korean OEMs specify sub-50-kilogram clutch modules to preserve cargo capacity and fuel efficiency.
- Sedan:Performance-oriented full-time AWD remains concentrated in German and Japanese premium nameplates.
- Truck:Body-on-frame platforms in North America retain part-time transfer cases for off-road and towing duty cycles.
SUV maintains volume leadership. Crossover is climbing the fastest as fleet procurement shifts toward compact utility vehicles.
Technology:
Supply concentration in mechatronic integration capabilities favors Tier-1 suppliers with in-house firmware development, compressing pure mechanical component markets.
- Electronic:Sensor-fused torque distribution algorithms enable predictive engagement before wheel slip occurs. German premium OEMs and Chinese EV platforms specify these systems for over-the-air calibration updates.
- Mechanical:Gear-based differentials and viscous couplings retain cost advantages in emerging-market truck applications and budget SUV segments.
- Adaptive:Multi-mode systems switching between full-time, on-demand, and torque-vectoring profiles based on drive mode selection.
- Hydraulic:Wet multi-plate clutch actuation persists in heavy-duty applications requiring sustained thermal capacity.
Mechanical retains the installed base. Electronic is gaining share fastest as electrification timelines accelerate.
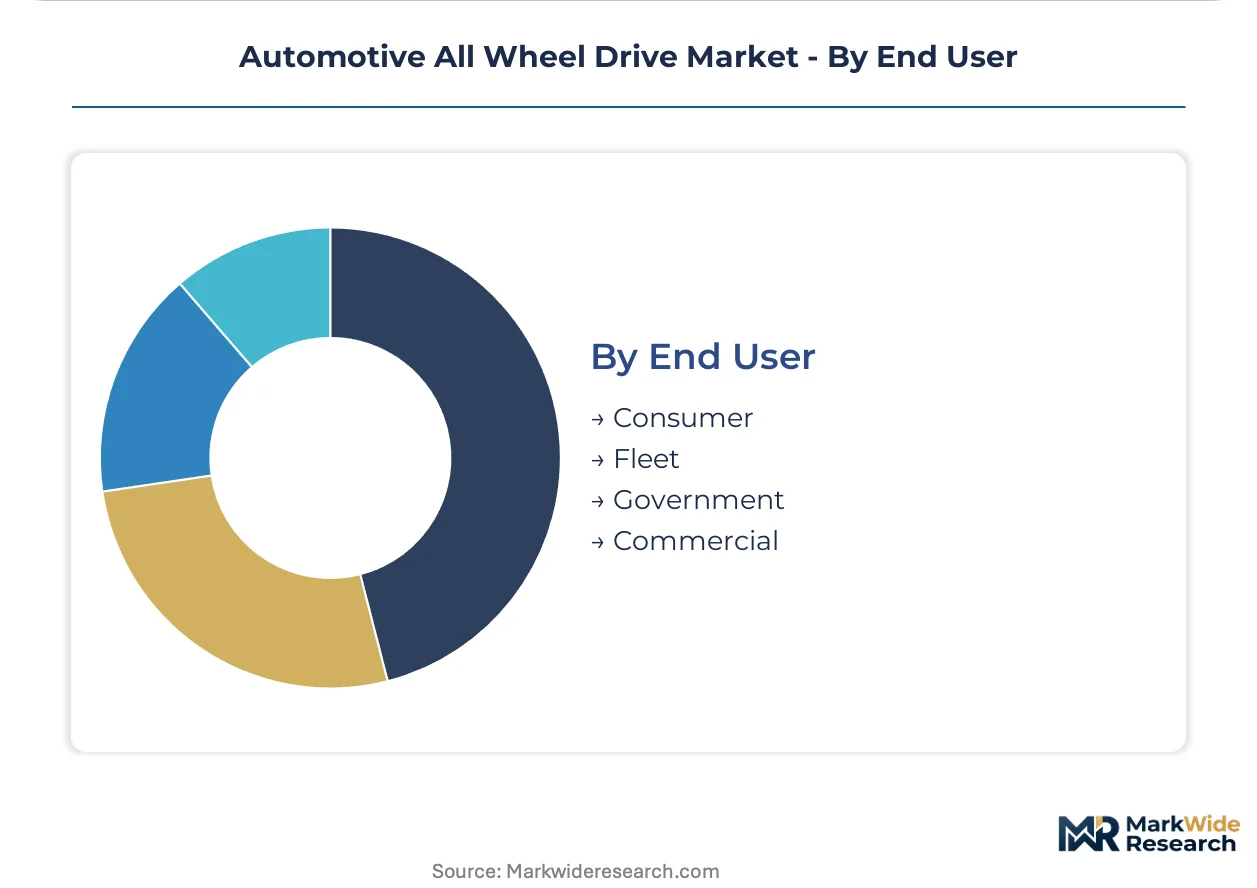
End User:
Procurement patterns diverge sharply between consumer preference for performance features and fleet prioritization of total cost of ownership.
- Fleet:Last-mile delivery operators in German and British urban logistics networks specify on-demand AWD with predictive algorithms. Amazon Logistics and DHL Express contracts prioritize warranty cost containment over upfront acquisition premiums.
- Consumer:Individual purchasers in snowy climates and premium segments drive full-time and torque-vectoring attachment rates.
- Commercial:Construction and utility fleet operators require part-time systems with validated durability under sustained load.
- Government:Police and emergency vehicle specifications mandate AWD for pursuit and all-weather response capability.
Consumer represents the largest revenue pool. Fleet is expanding most quickly as electrified delivery vehicle procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in AWD component exports, while the Rhine-Danube corridor sustains German manufacturing clusters and the I-35 corridor anchors North American light-truck assembly.
United States
NHTSA rollover-resistance mandates and EPA fuel-economy standards compel crossover manufacturers to fit on-demand AWD as standard equipment. The Detroit Three prioritize clutch-module sourcing for full-size SUV platforms. Michigan and Ohio manufacturing corridors concentrate Tier-1 supplier engineering centers serving light-truck assembly lines.
Germany
Premium OEM torque-vectoring specifications drive demand for integrated mechatronic architectures. ECE Regulation 13-H braking stability requirements shape electronic AWD calibration for export-bound vehicles. Baden-Württemberg and Bavaria host ZF Friedrichshafen AG and Continental AG development centers for dual-motor EV platforms.
China
MIIT new-energy vehicle technical standards accelerate software-defined torque vectoring in dual-motor electric platforms. GB/T homologation protocols govern AWD integration into domestic EV lineups. Yangtze River Delta manufacturing clusters concentrate electric axle motor production for BYD and NIO supply chains.
Japan
JIS standards and METI electrification roadmaps push torque-vectoring development for hybrid platforms. Toyota and Subaru full-time AWD architectures retain established share in domestic SUVs. Aichi and Kanagawa prefectures concentrate JTEKT Corporation and GKN Automotive joint-venture facilities.
Automotive All Wheel Drive Market Competitive Environment
Listed leaders compete with private specialists across clutch-module manufacturing scale and mechatronic integration depth. The supplier base consolidates around Tier-1s with ASIL-D validation capabilities while Tier-2 hydraulic component markets compress. Three archetypes dominate: integrated mechatronic system suppliers, clutch-module scale manufacturers, and electric axle motor specialists. M&A activity targets firmware development capabilities, while strategic partnerships lock in dual-motor EV platform sourcing.
Within the integrated system tier, ZF Friedrichshafen AG exemplifies European premium-vehicle torque-vectoring concentration, while BorgWarner Inc. anchors North American light-truck AWD sourcing through clutch-module manufacturing scale. Magna International Inc. occupies a position bridging full-time mechanical systems and emerging electric axle architectures across Canadian, Austrian, and Chinese manufacturing footprints.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| JTEKT Corporation |
| GKN Automotive |
| Continental AG |
| American Axle & Manufacturing |
| Dana Inc. |
| Eaton Corporation PLC |
| Others |
Value Chain & Pricing Dynamics
Clutch-module manufacturing scale at BorgWarner and ZF anchors price floors across North American and European sourcing corridors, compressing margins for mid-cap suppliers lacking comparable utilization rates. This concentration of production capacity in Michigan, Baden-Württemberg, and Yangtze River Delta clusters reinforces tiered pricing power while exposing buyers to volume-commitment thresholds that reshape procurement negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D validated torque-vectoring systems from on-demand clutch modules and mechanical part-time architectures. Price differentiation hinges on ISO 26262 certification grade and OEM volume scale, with Tier-1s commanding 40-60% premiums over Tier-2 hydraulic component suppliers. Cost compression in economy-tier mechanical systems is intensifying because Chinese crossover OEMs prioritize WLTP compliance over performance features. Fleet procurement managers at Amazon Logistics and DHL Express exhibit highest price sensitivity, while German premium OEMs remain least sensitive to upfront acquisition costs.
Supply Chain Analysis
Inbound logistics costs through the Port of Shanghai and Rotterdam-Antwerp corridor fluctuate with container availability on Asia-Europe trade lanes, compressing lead-time reliability for just-in-time assembly lines. Component manufacturing concentrates in China, Germany, and Japan, with electric axle motor production drawing from neodymium and dysprosium processing facilities in Chinese rare earth refining clusters. Single-source vulnerability around MIIT-compliant motor controllers threatens dual-motor EV platform ramp schedules. Distribution runs through OEM captive supply networks and Tier-1 direct ship programs to assembly plants in Mexico, Thailand, and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform electrification represents a high-growth disruption, with NHTSA rollover mandates and EPA fuel-economy standards accelerating the displacement of mechanical AWD architectures by software-defined torque vectoring.
For Market Incumbents: Consolidate clutch-module manufacturing scale through capacity rationalization in North American light-truck corridors while acquiring firmware development capabilities to defend against electric axle motor specialists. Prioritize ASIL-D certification investment to maintain sourcing relationships with premium OEMs as torque-vectoring programs consolidate among validated Tier-1s.
For New Entrants and Emerging Players: ISO 26262 fast-track validation partnerships with German TÜV or SGS laboratories unlock white-space entry into Indian sub-4-meter SUV segments where domestic OEMs lack localized AWD sourcing. Target Pune and Chennai manufacturing clusters through joint ventures with established clutch suppliers, leveraging predictive engagement algorithm development as the primary go-to-market angle for fleet procurement channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined torque-mapping providers offering over-the-air calibration subscriptions, positioning these archetypes for superior cash-flow quality across the analysis window. Monitor CSRD supply-chain disclosure adoption rates as the signal indicating which AWD suppliers will capture EU battery passport integration premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation timelines for dual-motor EV architectures at Chinese OEMs. |
| Battery Supply Agreement | Locks in rare earth magnet sourcing for electric axle motor production. |
| Software-Defined Vehicle Investment | Enables subscription revenue from torque-vectoring calibration updates. |
| Geographic Manufacturing Footprint | Positions suppliers near Yangtze River Delta EV assembly clusters. |
| Charging Infrastructure Partnership | Integrates AWD thermal management with fast-charging network specifications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed Tier-1 suppliers, and MIIT new-energy vehicle technical standards. Interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributors, and dealership operations managers informed demand-side validation. Bottom-up triangulation across clutch-module shipment volumes and top-down reconciliation against OEM platform production schedules anchored market sizing.
Segmentation dimensions modeled include drive type architecture, vehicle class tier, propulsion system configuration, content per vehicle, and regional production cluster concentration. CAGRs were derived from slope-log analysis of historical penetration rates projected across the analysis window, with electric vehicle adoption curves and EPA fuel-economy compliance timelines serving as primary forecast inputs alongside rare earth magnet price volatility assumptions.
Underlying assumptions cover NHTSA mandate enforcement timelines and MIIT technical standard adoption rates, with deviation risk concentrated in rare earth supply disruptions and WLTP protocol amendments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Hydraulic Lash Adjuster Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Tow Bar Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Automotive Windshield Washer System Market