
 Automotive Remanufacturing Market | 2026-2036
Automotive Remanufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Remanufacturing Market Analysis
North American transmission remanufacturing capacity is hardening as labor shortages constrain output expansion. Robert Bosch GmbH leverages its captive parts distribution to secure core returns across European markets. ZF Friedrichshafen AG anchors its competitive stance through automated disassembly lines that cut unit processing time. Denso Corporation specializes in alternator remanufacturing for hybrid powertrains, a segment where technical barriers limit competitor entry.
Automotive remanufacturing restores used components to original equipment performance specifications through systematic disassembly, cleaning, inspection, replacement of worn elements, and reassembly with new parts meeting OEM tolerances. The process typically achieves energy savings versus new production while preserving embedded material value in castings and forgings. Engines dominate product type value pools due to high core residual worth and complex machining requirements, while automated remanufacturing technology is displacing manual lines in high-volume facilities. Passenger vehicles anchor application demand, though heavy-duty trucks generate superior per-unit margins due to longer component lifecycles and stricter uptime requirements.
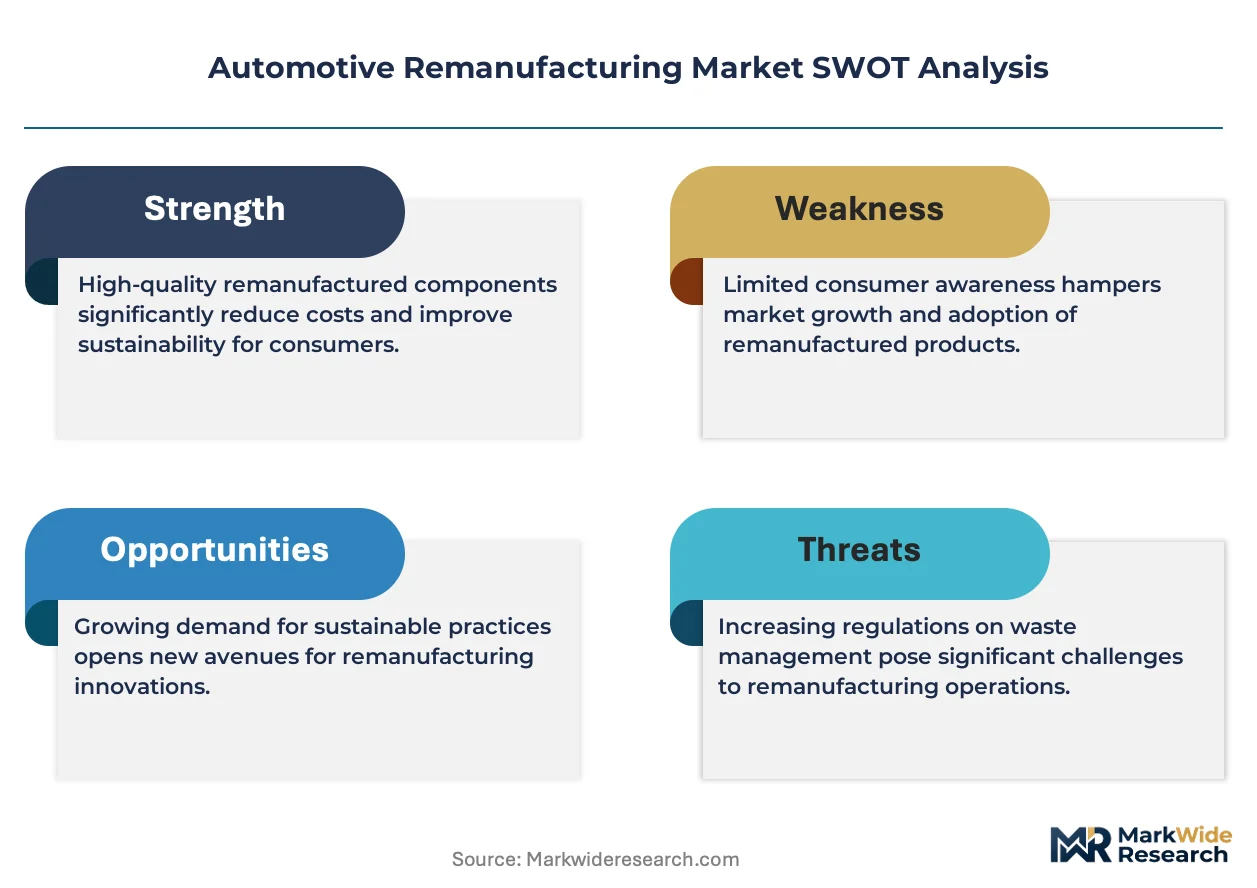
The EPA governs hazardous waste handling in US remanufacturing facilities, while REACH compliance in Europe restricts certain chemical cleaning agents and surface treatments. OEMs face divergent regulatory obligations across jurisdictions, fragmenting process standardization and raising compliance overhead. Stakeholders must track how carbon border adjustment mechanisms treat remanufactured versus newly manufactured components in trade classifications.
Market Dynamics
EU Green Deal circular economy mandates are forcing remanufacturers to reengineer core recovery logistics and material tracking systems. Fleet operators now demand total cost of ownership documentation that favors certified remanufactured components over new production.
Growth Catalysts
- REACH material recovery rules:The ECHA framework tightens chemical handling standards, pushing OEMs to formalize remanufacturing networks that preserve embedded material value in high-wear castings.
- Hybrid powertrain alternator demand:Technical complexity in electrified drivetrains creates protected margin pools where remanufacturing expertise substitutes for scarce new component supply.
- Stuttgart-Munich corridor concentration:Germany's automotive engineering density enables just-in-time core logistics that reduce inventory carrying costs for high-volume transmission rebuild programs.
Market Restraints
- Scrap metal price volatility:Ferrous input cost swings compress remanufacturer margins when core acquisition pricing lags commodity market movements.
- Labor pool constraints:North American transmission facilities face machinist shortages that harden capacity expansion regardless of equipment investment.
- Carbon border adjustment uncertainty:Trade classification ambiguity between remanufactured and newly manufactured components fragments cross-border shipment planning.
Strategic Opportunities
- Heavy-duty truck electrification:Battery pack remanufacturing for commercial fleets represents an underdeveloped service category with superior per-unit economics versus passenger vehicle work.
- Automated disassembly convergence:Machine vision paired with robotic component handling is compressing unit processing time in high-throughput facilities.
- India BIS quality certification:Formal standards adoption creates first-mover positioning for exporters serving organized aftermarket channels in price-sensitive segments.
Industry Challenges
- Core return logistics:Reverse supply chain coordination requires specialized containerization and tracking systems that many independent rebuilders lack capital to deploy.
- Skill transfer gaps:Manual inspection expertise in casting fatigue assessment does not translate directly to automated quality assurance protocol management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Remanufacturing Market |
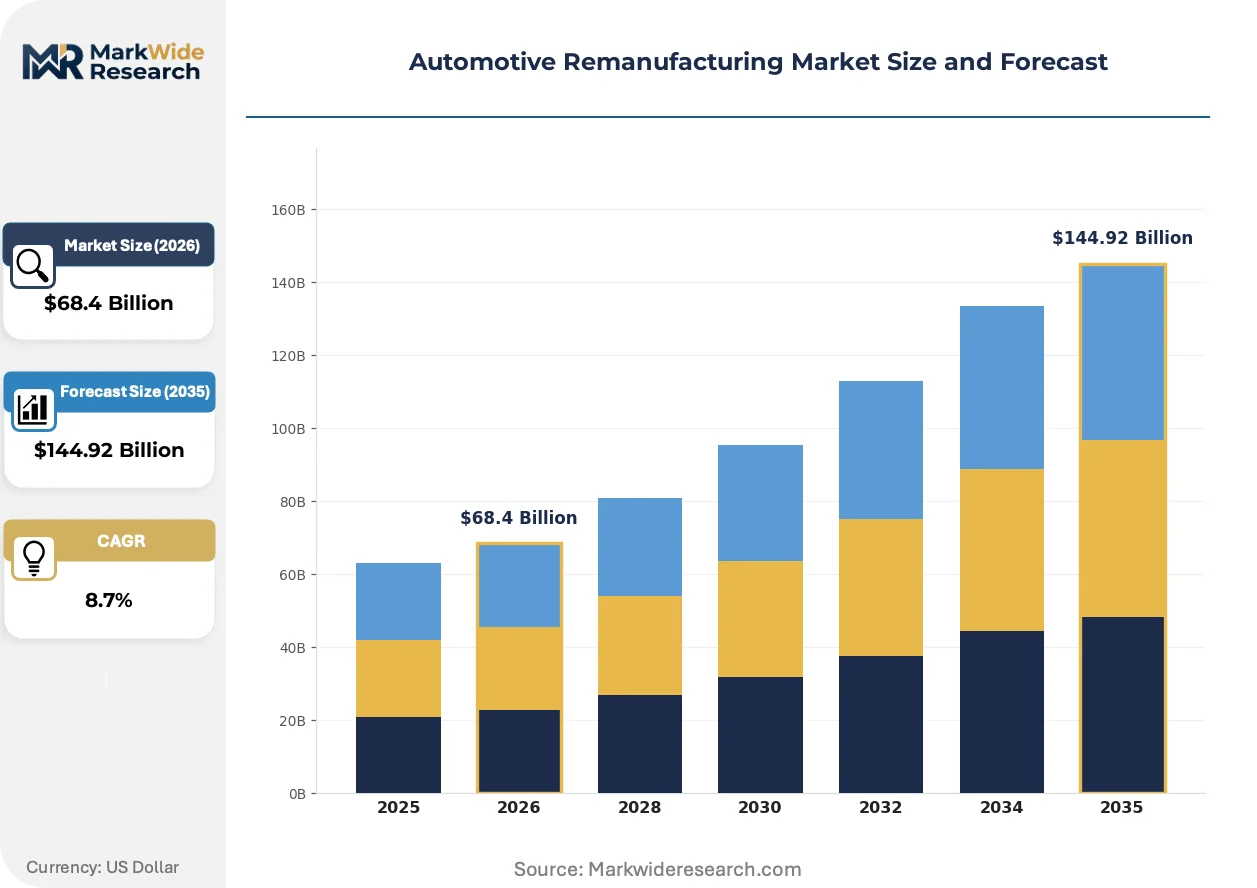
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engines, Transmissions, Turbochargers, Alternators Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles End User: OEMs, Aftermarket Providers, Dealers, Fleet Operators Technology: Manual Remanufacturing, Automated Remanufacturing, Hybrid Processes, CNC Machining |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, Valeo SA, BorgWarner Inc., Cardone Industries, Denso Corporation, Caterpillar Inc., Meritor Inc., Delphi Technologies PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Remanufacturing Market Emerging Trajectories
Digital thread technologies are threading through remanufacturing operations, connecting component history data to predictive wear modeling. This convergence is altering how facilities prioritize core acquisition and process routing decisions.
Machine vision inspection systems are absorbing quality assurance functions previously executed by experienced machinists. Tier-1 transmission remanufacturers in Germany deploy these systems to classify core condition within seconds of intake. The technology is absorbing variability in human judgment that previously caused inconsistent rebuild sequencing and warranty exposure.
EPA hazardous waste handling rules are tightening documentation requirements for chemical cleaning agents used in engine block reconditioning. US facilities must now track solvent batch usage through disposal with granular record retention. The regulation is compressing operational flexibility for smaller independent rebuilders lacking compliance infrastructure.
Fleet procurement departments are unbundling component sourcing from integrated maintenance contracts. Large commercial vehicle operators now negotiate direct remanufactured component supply agreements separate from service provider relationships. This pattern concentrates volume with certified suppliers capable of warranty backing across multi-state operating territories.
Automotive Remanufacturing Market Segmentation
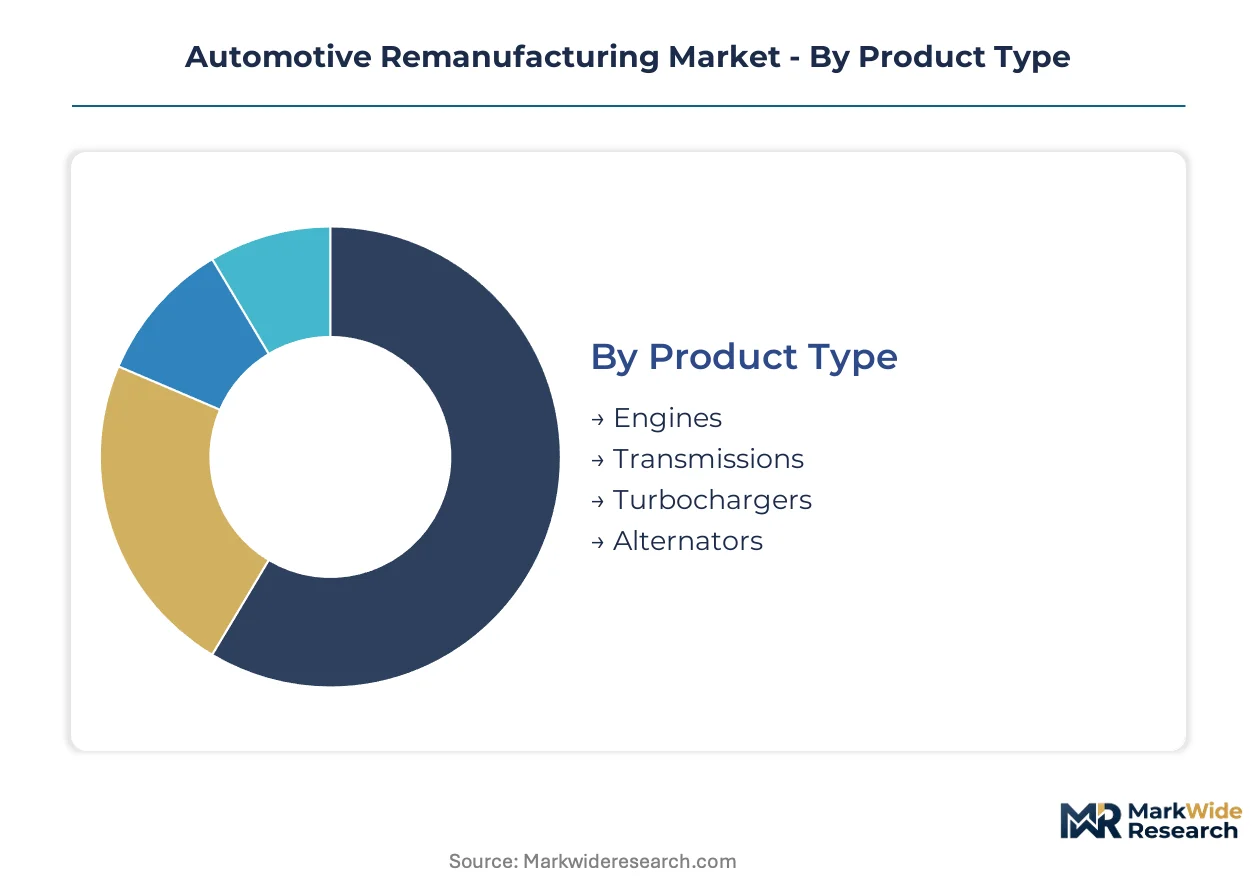
Segmentation in automotive remanufacturing reveals how technical complexity, buyer procurement power, and regulatory exposure concentrate value across distinct operational layers. Understanding these divisions exposes where margin pools thicken and where capital deployment risks misalignment.
Product Type:
Buyers differentiate by residual core value and machining intensity, with high-wear castings commanding premium recovery economics.
- Engines:Cast iron and aluminum block reconditioning preserves embedded material worth through cylinder boring, honing, and crankshaft regrinding. Demand clusters in Germany's industrial corridor around Stuttgart and Munich, where OEM captive networks justify dedicated core logistics infrastructure. EU Green Deal circular economy mandates tighten material recovery documentation for these high-mass components.
- Transmissions:Gearbox rebuilds involve precision spline inspection, synchro replacement, and torque converter reconditioning. North American facilities face machinist shortages that harden capacity expansion regardless of equipment investment, compressing output growth.
- Turbochargers:Rotating assembly balancing and bearing cartridge replacement restore boost performance specifications.
- Alternators:Stator rewinding and rectifier replacement for hybrid powertrains carries technical barriers that limit competitor entry.
Engines lead volumes today; alternators for hybrid drivetrains are gaining share fastest.
Application:
Vehicle duty cycles determine component lifecycle economics and uptime tolerance, separating price-sensitive operators from premium service buyers.
- Passenger Vehicles:High-volume, standardized component formats enable economies of scale in automated disassembly lines. Fleet procurement departments increasingly unbundle component sourcing from integrated maintenance contracts, concentrating volume with certified suppliers.
- Heavy-Duty Trucks:Extended service intervals and strict uptime requirements generate superior per-unit margins versus passenger work. Battery pack remanufacturing for commercial electrification represents an underdeveloped category with attractive economics.
- Commercial Vehicles:Light and medium-duty fleet operators demand total cost of ownership documentation favoring certified remanufactured components.
- Motorcycles:Smaller displacement engines and compact transmission formats require adapted tooling and lower batch sizes.
Passenger vehicles anchor current throughput; heavy-duty truck electrification programs are climbing the fastest.
End User:
Procurement sophistication and warranty backing capability separate institutional buyers from fragmented independent channels.
- OEMs:Captive remanufacturing networks formalize core return logistics and quality standardization. Robert Bosch GmbH leverages its parts distribution infrastructure to secure core returns across European markets.
- Fleet Operators:Large commercial vehicle operators negotiate direct supply agreements spanning multi-state operating territories, bypassing traditional service provider relationships.
- Aftermarket Providers:Independent rebuilders lack capital for specialized containerization and tracking systems that reverse supply chains demand.
- Dealers:Franchise service departments balance OEM certification requirements against local competitive pricing pressure.
OEMs dominate certified volume; fleet operators are expanding procurement autonomy most rapidly.
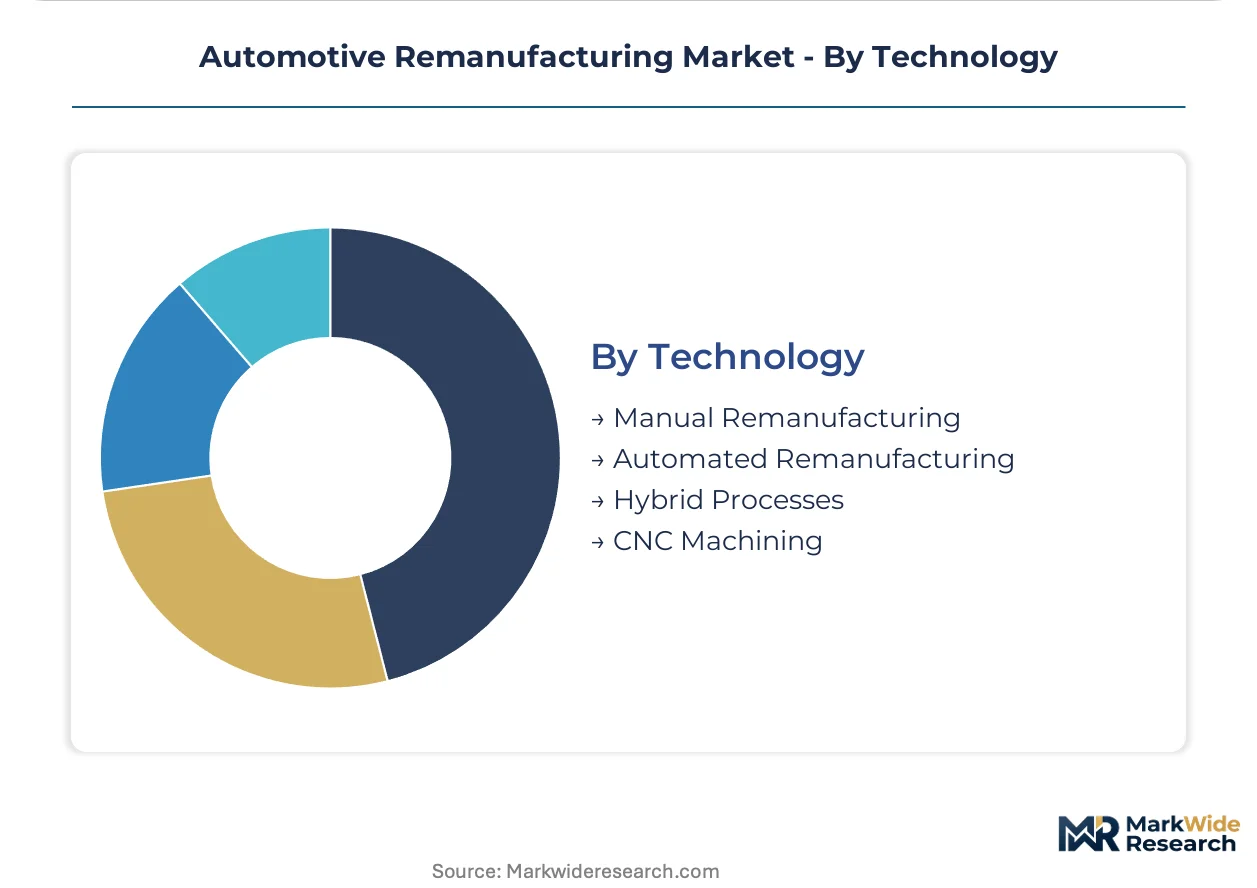
Technology:
Capital intensity and labor substitution potential divide facilities by scale viability and quality consistency.
- Automated Remanufacturing:Machine vision paired with robotic component handling compresses unit processing time in high-throughput facilities. ZF Friedrichshafen AG anchors its competitive stance through automated disassembly lines that cut cycle times.
- CNC Machining:Computer-controlled resurfacing and boring operations achieve OEM tolerance repeatability that manual methods cannot match.
- Manual Remanufacturing:Experienced machinist judgment in casting fatigue assessment retains relevance in low-volume, complex component work.
- Hybrid Processes:Semi-automated lines blend robotic handling with human inspection for mid-scale operations.
Automated systems lead investment flows; CNC machining integration is advancing most quickly in tier-1 facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's remanufacturing infrastructure outpaces France in core recovery density, while the United States confronts labor constraints that harden capacity expansion regardless of capital investment.
United States
EPA hazardous waste documentation rules tighten solvent tracking requirements for engine block reconditioning facilities. Fleet procurement departments unbundle component sourcing from integrated maintenance contracts, concentrating volume with certified suppliers. Transmission rebuild capacity clusters around Detroit and the industrial Midwest, where machinist shortages constrain output expansion.
Germany
EU Green Deal circular economy mandates force reengineering of core recovery logistics and material tracking systems. REACH compliance restricts chemical cleaning agents and surface treatments, fragmenting process standardization. OEM remanufacturing networks cluster around Stuttgart and Munich, enabling just-in-time core logistics that reduce inventory carrying costs.
China
Dual carbon goals accelerate formalization of remanufacturing standards under MIIT oversight. NMPA-aligned quality protocols create entry barriers for uncertified rebuilders serving organized aftermarket channels. Industrial remanufacturing parks concentrate in the Yangtze River Delta, where state-backed investment targets automotive component circularity.
India
BIS quality certification adoption creates first-mover positioning for exporters serving price-sensitive organized aftermarket channels. Commercial vehicle fleet operators demand total cost of ownership documentation favoring certified remanufactured components. Automotive remanufacturing activity concentrates in Maharashtra and Tamil Nadu, where component supplier density supports reverse logistics networks.
Japan
METI industrial circularity guidelines promote remanufacturing as material security strategy amid import dependency. JIS standards enforcement tightens quality consistency requirements for rebuilt powertrain components. Precision machining expertise clusters in the Nagoya industrial corridor, where tier-1 suppliers integrate remanufacturing into captive after-sales operations.
Automotive Remanufacturing Market Vendor Landscape
German producers anchor the premium-tier captive network segment; North American specialists hold fragmented independent rebuild channels. The vendor base splits between OEM-captive operations with integrated parts distribution and independent rebuilders lacking capital for specialized containerization systems. Three archetypes dominate: diversified automotive suppliers with captive remanufacturing divisions, dedicated transmission and engine rebuild specialists, and heavy-duty equipment OEMs with vertical service integration. Competitive moves concentrate on automated disassembly line deployment and strategic core logistics partnerships that secure reverse supply chain access.
Within the diversified supplier tier, Robert Bosch GmbH and ZF Friedrichshafen AG occupy positions shaped by their European manufacturing heritage and captive distribution infrastructure. Denso Corporation represents the Japanese specialist archetype, with its corporate structure reflecting precision component manufacturing lineage. These three entities exemplify how geographic origin and organizational form correlate with strategic positioning across automated versus manual process intensities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Valeo SA |
| BorgWarner Inc. |
| Cardone Industries |
| Denso Corporation |
| Caterpillar Inc. |
| Meritor Inc. |
| Delphi Technologies PLC |
| Others |
Supply Flow & Price Mechanics
Fleet procurement departments concentrate buying power across multi-state operating territories, forcing contract-based long-term offtake structures that lock in volume discounts against spot market volatility. This buyer concentration compresses margin buffers for independent rebuilders lacking certified warranty backing.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for transmission remanufacturing across European markets. Three-tier pricing structure across premium OEM-certified, standard independent, and economy grey-market levels differentiates by warranty backing and core traceability. Cost compression in the independent tier is intensifying because scrap metal price volatility outpaces core acquisition cost adjustments. Fleet operators exhibit lowest price sensitivity due to uptime guarantees, while aftermarket providers face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Nagoya anchor hub-and-spoke patterns for core collection and finished component redistribution. Germany, China, and the United States concentrate precision machining capacity for high-wear castings. The supply chain draws from ferrous scrap yards, OEM captive parts networks, and specialty bearing suppliers. Single-source vulnerability in German automated disassembly equipment creates chokepoint exposure. Distribution runs through OEM-captive networks for certified volume and independent jobbers for price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive remanufacturing functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany diverge from BIS certification economics in India, creating margin dispersion for operators with multi-country footprints.
For Market Incumbents: Acquire automated disassembly line technology to offset North American machinist shortages that harden capacity expansion. Secure core return logistics partnerships with fleet operators bypassing traditional service providers. Invest in REACH-compliant chemical handling infrastructure before ECHA enforcement tightens. Backward integration into captive parts distribution defends against Robert Bosch GmbH's network advantages. For New Entrants and Emerging Players: Capture battery pack remanufacturing for heavy-duty truck electrification, an underdeveloped category with superior per-unit economics versus passenger vehicle work. Target India's organized aftermarket channels where BIS quality certification creates first-mover positioning. Build direct procurement relationships with commercial vehicle fleets unbundling component sourcing from maintenance contracts. For Investors and Strategic Acquirers: Tier-1 automotive suppliers with captive remanufacturing divisions are the most active acquirer in this space, seeking automated processing capabilities. The five-to-ten year viability window favors operators with OEM certification networks and multi-state warranty infrastructure. Acquisition target archetypes include transmission specialists with established core logistics and hybrid powertrain alternator rebuilders. Watch carbon border adjustment mechanism rulings on remanufactured component trade classification as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Disassembly Line Deployment | ZF Friedrichshafen AG's robotic handling cuts unit processing time in Stuttgart-Munich corridor facilities. |
| Core Logistics Partnership Formation | Robert Bosch GmbH leverages parts distribution infrastructure to secure returns across European markets. |
| REACH Compliance Infrastructure Investment | ECHA chemical handling standards force formalization of remanufacturing networks preserving embedded material value. |
| Battery Pack Remanufacturing Capability Buildout | Heavy-duty truck electrification creates underdeveloped service category with superior per-unit economics. |
| Machine Vision Quality Assurance Integration | German tier-1 transmission facilities deploy systems classifying core condition within seconds of intake. |
Methodological Framework
Multiple input streams — executive interviews with remanufacturing operations directors, regulatory filings with EPA and ECHA, and customs trade data on core component flows — were reconciled to build demand estimates. Primary fieldwork engaged OEM captive network managers, independent rebuilder owners, fleet procurement officers, and aftermarket distribution channel heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and EU circular economy directive implementation reports. Bottom-up facility capacity modeling and top-down vehicle parc analysis were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, application vehicle class, technology intensity, and regional production cluster. CAGRs were derived from elasticity analysis against vehicle age distribution and fleet replacement cycles. Forecast inputs incorporated REACH enforcement timelines, carbon border adjustment mechanism development, and hybrid powertrain penetration curves.
Scrap metal price volatility, labor pool constraints in North American machining trades, and carbon border adjustment uncertainty are the dominant revision risks that could alter trajectory. Forecasts reflect documented assumptions about regulatory implementation pace and fleet electrification adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Wash System Market
Automotive Services
Americas MAP Market
Automotive Services
Cab Services Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Car Subscription Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Register Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Global Car Wash Market
Automotive Services
North America Car Wash Market