
 Argentina Automotive Adaptive Lighting System Market | 2026-2036
Argentina Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Adaptive Lighting System Market Outlook
Premium passenger vehicle OEMs is reorganizing procurement priorities around sensor-based headlamp modules in Argentina's automotive supply chain. Valeo Group leverages its European engineering base to sustain technology leadership in matrix LED architectures for local assembly partners. HELLA KGaA Hueck & Co. anchors its position through captive R&D partnerships with German-brand vehicle plants operating in Córdoba and Buenos Aires provinces. Hyundai Mobis competes by extending its integrated electronics-lamp module platform to regional OEM programs.
Automotive adaptive lighting systems modulate beam pattern, intensity, and direction in real time through camera, radar, or lidar sensor fusion, typically operating within 4500-6500 Kelvin color temperature ranges for LED variants to optimize road illumination without opposing glare. These systems serve the primary commercial purpose of reducing nighttime accident incidence while supporting vehicle brand differentiation in premium segments. Matrix LED technology dominates current value generation due to its balance of performance and cost scalability for mid-luxury vehicle platforms. Sensor-based technology represents the fastest-expanding architecture as Argentine assemblers integrate forward-facing cameras for combined ADAS-lighting functions. Passenger vehicles command the dominant application share, though commercial trucks exhibit rising specification rates for highway safety compliance.
Argentina's national automotive regulator enforces Mercosur-type approval frameworks that incorporate UNECE R48 and R123 lighting performance standards, compelling importers and local assemblers to certify adaptive beam functions prior to market release. The Secretariat of Industry and Productive Development administers import substitution incentives that favor local sourcing of electronic lighting control modules, reshaping supplier qualification criteria for Tier-1 participants. Stakeholders must monitor pending updates to Mercosur automotive safety harmonization protocols and calibrate product development cycles to align with anticipated beam-pattern digitization requirements.
Market Dynamics
Matrix LED architectures are decomposing the traditional headlamp supply chain in Argentina as premium OEMs demand integrated sensor-lamp modules rather than discrete component sourcing from Tier-1 suppliers.
Growth Catalysts
- Mercosur Safety Harmonization:Argentina's alignment with UNECE R48 and R123 lighting standards mandates adaptive beam certification, forcing technology adoption across all new vehicle registrations.
- Camera Sensor Fusion:Forward-facing camera integration for combined ADAS-lighting functions is accelerating specification rates for sensor-based headlamp architectures.
- Buenos Aires-Córdoba Cluster:Vehicle assembly concentration in these provinces creates geographic density that justifies localized electronics module production.
Market Restraints
- Semiconductor Input Volatility:LED driver ICs and sensor processing chips face price instability that compresses margin structures for lighting system integrators.
- European Supply Concentration:Core matrix LED intellectual property and engineering capacity remains captive to German and French parent operations, limiting Argentine supplier autonomy.
- UNECE R123 Compliance Friction:Type-approval timelines for adaptive beam functions extend product development cycles and delay revenue recognition for local assemblers.
Strategic Opportunities
- Import Substitution Incentives:The Secretariat of Industry and Productive Development offers preferential treatment for local sourcing of electronic lighting control modules, creating captive supply opportunities.
- Commercial Truck Specification:Highway safety compliance requirements for long-haul freight operators represent an underpenetrated application segment with rising adaptive lighting adoption.
- ADAS-Lighting Convergence:Integration of lidar and radar sensor fusion with headlamp modules enables new functional safety packages for mid-luxury vehicle platforms.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time beam pattern algorithms require specialized automotive lighting firmware engineers, a skill set concentrated in European engineering centers.
- Legacy Platform Integration Complexity:Retrofitting adaptive lighting into existing vehicle electrical architectures demands extensive harness redesign and validation cycles.
- Certification Timeline Compression:Accelerating Mercosur protocol updates force suppliers to parallel-track development and homologation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Adaptive Lighting System Market |
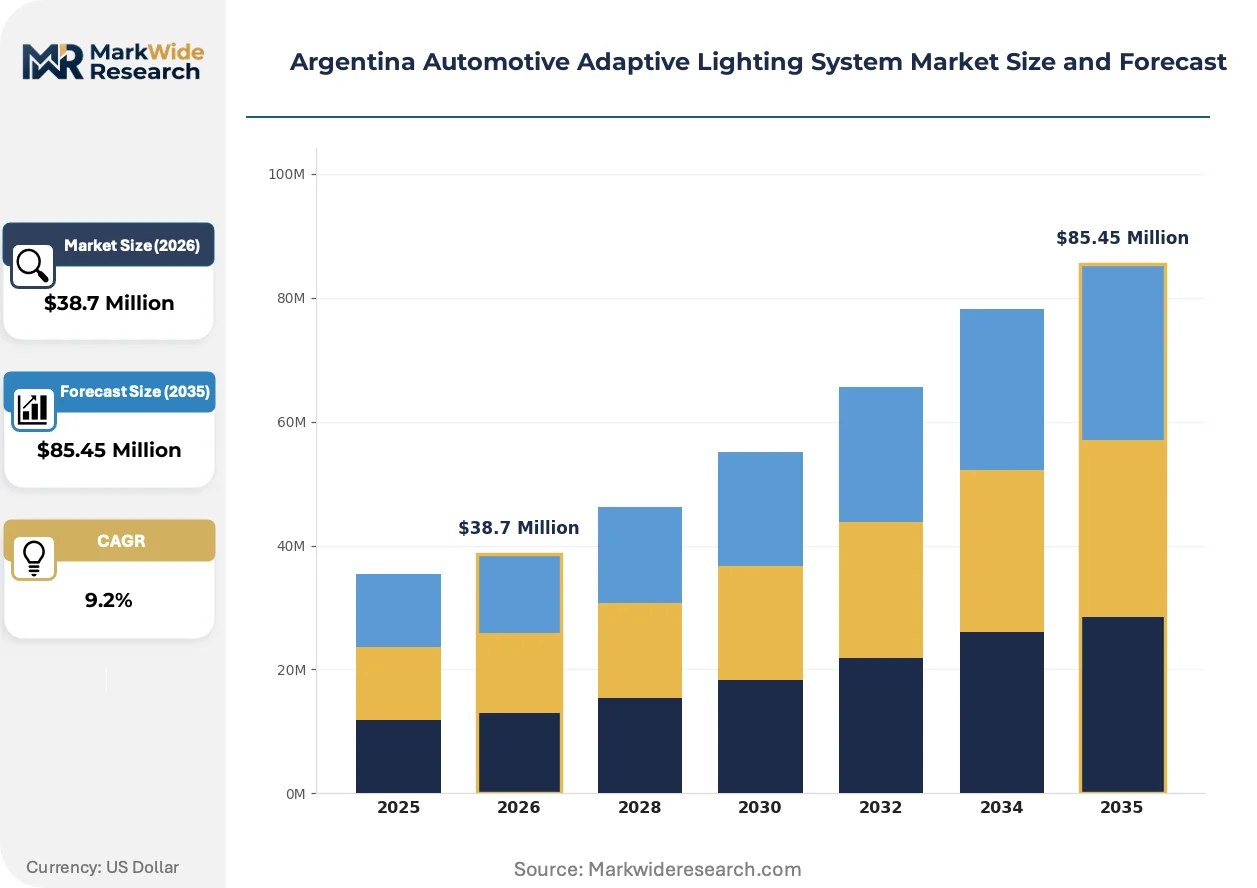
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $85.45 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Adaptive Xenon, Laser Lighting, Halogen End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Dynamic Lighting, Sensor-Based, Automatic Adjustment, Glare-Free Application: Passenger Vehicles, Commercial Trucks, Motorcycles, Recreational Vehicles |
| Companies Covered | HELLA KGaA Hueck & Co., Valeo Group, Hyundai Mobis, Magneti Marelli SpA, Koito Manufacturing Co. Ltd, Koninklijke Philips N.V., Stanley Electric Co. Ltd, Osram Licht AG, Texas Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Adaptive Lighting System Market Strategic Shifts
Digital beam pattern control is rewriting competitive boundaries in Argentina's automotive lighting sector, separating suppliers with full-stack sensor-lamp integration capabilities from component-only vendors.
Matrix LED technology is decomposing the conventional headlamp value chain by embedding pixel-level beam control directly into lamp modules. Premium passenger vehicle OEMs operating Córdoba and Buenos Aires assembly plants are specifying these architectures for mid-luxury platforms previously served by static adaptive systems. The technology is decomposing discrete supplier tiers as lamp manufacturers absorb sensor fusion and control electronics functions previously sourced separately.
Mercosur automotive safety harmonization protocols are accelerating type-approval requirements for adaptive beam technologies across Argentine vehicle registrations. Local assemblers must now certify dynamic leveling and cornering functions prior to market release, compressing development timelines. Passenger vehicle importers face the steepest compliance burden as they adapt European-homologated systems to Mercosur-specific testing protocols.
Fleet procurement managers are consolidating lighting system sourcing under single-source sensor-lamp module contracts rather than multi-vendor component assemblies. Tier-1 suppliers with captive electronics production are displacing pure-play lamp manufacturers in Buenos Aires Province assembly programs. This concentration is most visible among German-brand vehicle plants seeking simplified warranty administration and reduced integration risk.
Argentina Automotive Adaptive Lighting System Market Segmentation
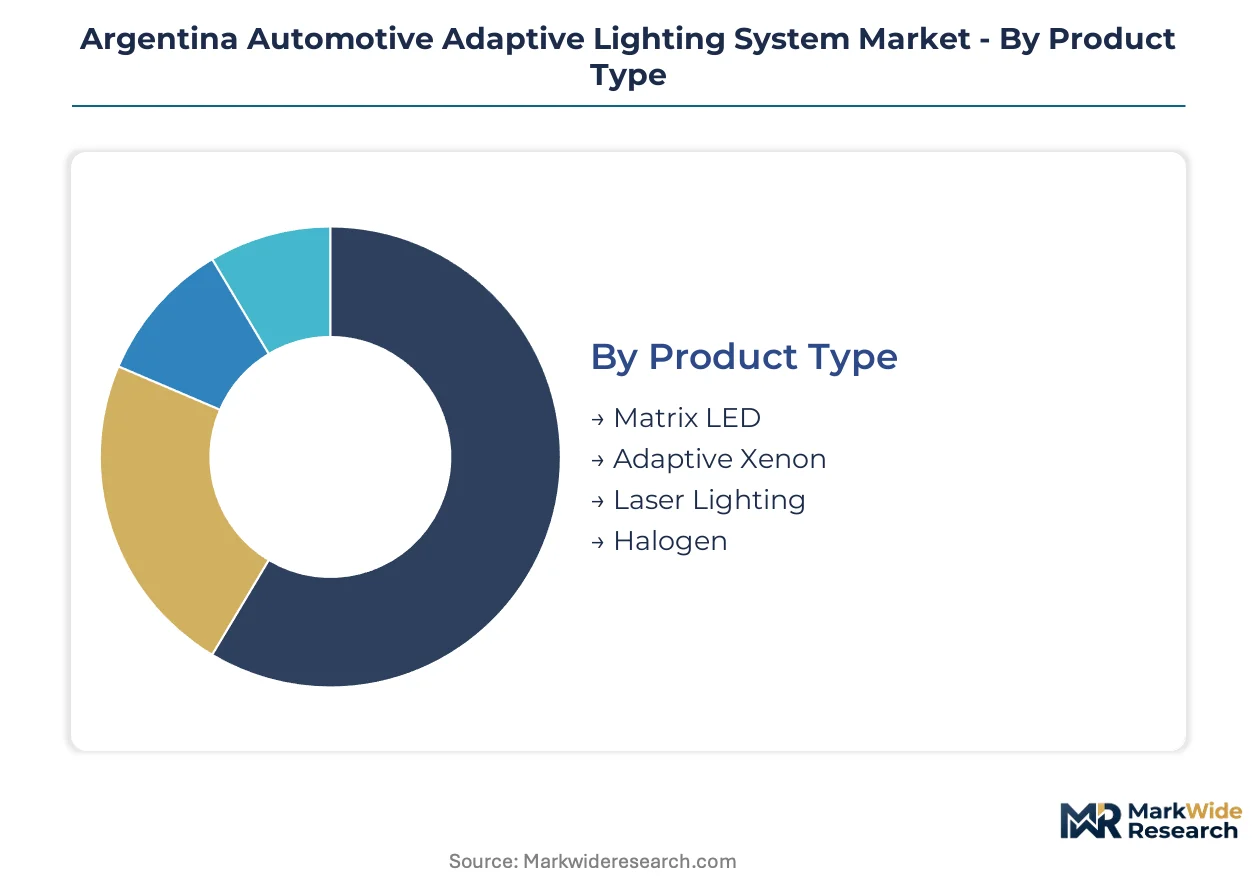
Adaptive lighting architectures fragment across multiple technical and commercial dimensions in Argentina. Procurement patterns diverge sharply between integrated OEM programs and fragmented aftermarket channels. Understanding these segment boundaries clarifies where technology premiums concentrate versus where price competition dominates.
Product Type:
Margin pools sit with pixel-level beam control architectures that command technology premiums from premium vehicle assemblers.
- Matrix LED:Pixel-level beam modulation enables selective dimming of individual segments to mask oncoming vehicles without full high-beam deactivation. Buenos Aires Province assembly plants specify these modules for mid-luxury German-brand platforms where ADAS integration justifies cost premiums.
- Adaptive Xenon:Motorized reflector assemblies pivot beam direction based on steering angle and vehicle speed, offering functional cornering illumination at lower cost than solid-state alternatives. Demand concentrates in Córdoba vehicle plants serving fleet procurement programs with constrained option budgets.
- Laser Lighting:Laser-excited phosphor architectures extend high-beam reach beyond LED limitations for ultra-premium applications.
- Halogen:Static leveling systems with minimal electronic content serve entry vehicle segments and commercial truck retrofits.
Matrix LED holds installed capacity. Laser Lighting is rotating up the share rankings.
End User:
Volume concentration tracks vehicle assembly geography, with procurement authority shifting toward integrated module sourcing.
- OEMs:German and Korean parent companies dictate lighting specifications for Argentine assembly subsidiaries, embedding adaptive functions into platform architectures prior to local production ramp. Their engineering centers in Europe and Asia control matrix LED intellectual property and sensor fusion algorithms.
- Tier-1 Suppliers:Valeo, HELLA, and Hyundai Mobis operate direct supply relationships with Córdoba and Buenos Aires assembly plants, consolidating previously discrete lamp and electronics sourcing under single-source contracts.
- Vehicle Assemblers:Local production facilities manage final integration and homologation testing under Mercosur type-approval frameworks.
- Aftermarket Providers:Independent distributors serve collision repair and retrofit demand with certified replacement modules.
Tier-1 Suppliers capture specification authority. Aftermarket Providers are gaining share fastest in the repair channel.
Technology:
Cost tier separation runs between sensor-fusion architectures and mechanical automation systems.
- Sensor-Based:Camera and radar inputs enable predictive beam adjustment before steering input, integrating with forward collision warning and lane-keeping systems. Argentine assemblers specify these architectures for combined ADAS-lighting function packages that streamline electronics sourcing.
- Dynamic Lighting:Steering-linked motorization adjusts beam direction without environmental sensing, occupying the mid-market cost position.
- Automatic Adjustment:Static load-leveling compensates for vehicle pitch changes during acceleration and braking.
- Glare-Free:Selective beam masking algorithms prevent opposing driver dazzle while maintaining road edge illumination.
Sensor-Based systems anchor premium platform specifications. Glare-Free functionality is climbing the fastest as a standalone option package.
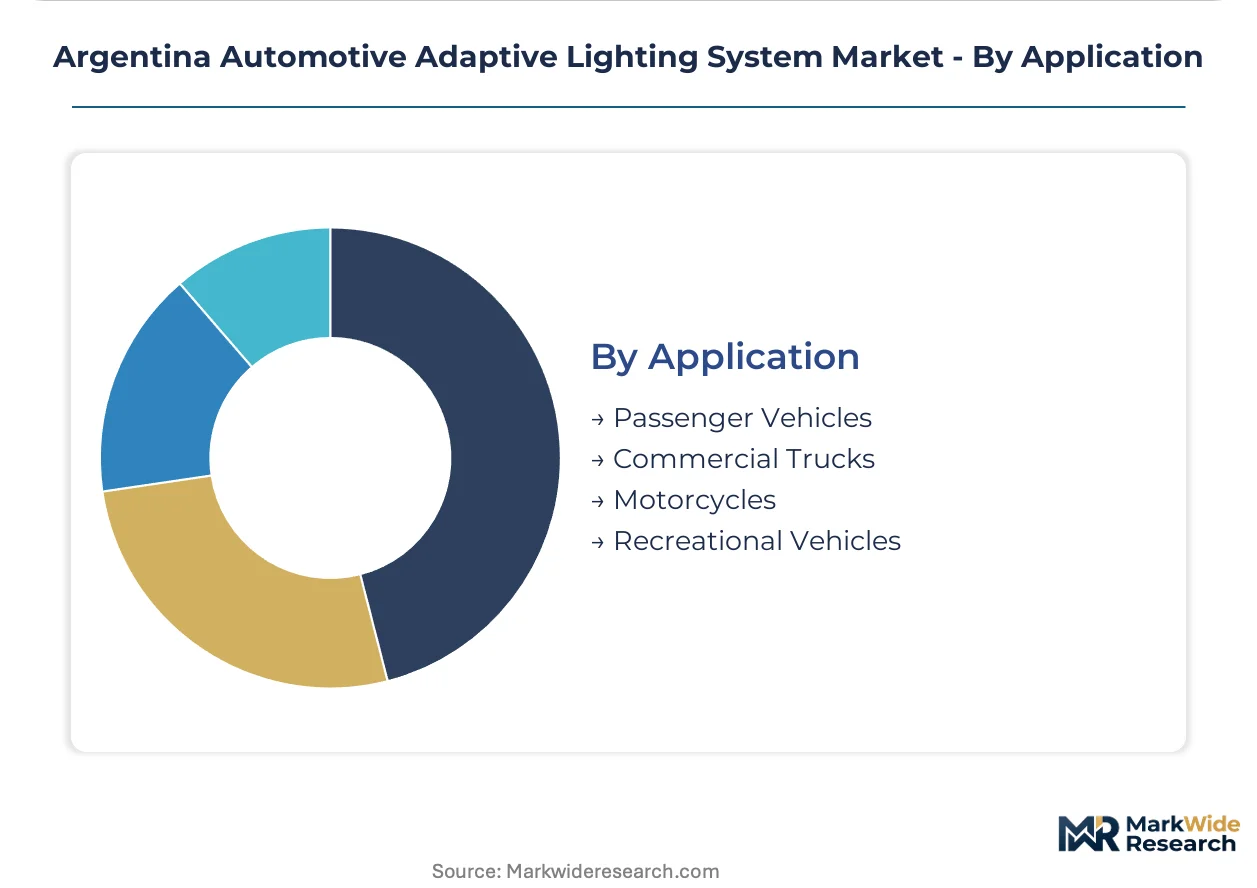
Application:
Customer type determines specification stringency, with safety compliance mandates driving commercial adoption.
- Passenger Vehicles:Premium and mid-luxury platforms specify full matrix LED with sensor fusion as brand differentiation elements. Buenos Aires Province consumers demonstrate willingness to pay for adaptive functions that reduce nighttime driving fatigue on unlit provincial routes.
- Commercial Trucks:Long-haul freight operators face emerging highway safety compliance requirements for dynamic leveling and cornering illumination on interstate corridors connecting Córdoba to Buenos Aires.
- Motorcycles:Lean-angle compensation and cornering lights address visibility constraints on winding mountain routes.
- Recreational Vehicles:Self-leveling systems accommodate variable load configurations and extended nighttime operation.
Passenger Vehicles dominate installed base. Commercial Trucks are expanding most quickly as fleet safety specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina exports automotive lighting modules to Brazilian assembly plants through the Mercosur trade corridor, while German engineering centers in Stuttgart and Munich supply matrix LED intellectual property to Córdoba production facilities.
Buenos Aires Province
Affluent consumer bases in Greater Buenos Aires drive specification rates for sensor-based headlamp modules on mid-luxury German-brand platforms. The Secretariat of Industry and Productive Development administers import substitution incentives that favor local sourcing of electronic lighting control modules. The Pacheco and General Pacheco industrial corridors host Volkswagen and Mercedes-Benz assembly plants integrating adaptive beam technologies.
Córdoba
Fleet procurement programs with constrained option budgets sustain demand for motorized reflector assemblies on commercial truck platforms. Argentina's national automotive regulator enforces Mercosur-type approval frameworks incorporating UNECE R48 and R123 lighting performance standards. The Córdoba Capital automotive cluster concentrates Renault and Fiat production facilities where dynamic leveling systems undergo homologation testing.
Santa Fe
Highway freight operators traversing the Rosario-Buenos Aires corridor face emerging safety compliance requirements for cornering illumination on long-haul routes. Provincial transport authorities align with national Mercosur harmonization protocols for adaptive beam certification. The Rosario industrial district hosts GM and Ford stamping plants where lighting module integration supports regional supply chain density.
Mendoza
Mountain route navigation demands lean-angle compensation systems for premium SUV platforms serving tourism and agricultural fleet operators. The national automotive regulator mandates UNECE R123 compliance for all new vehicle registrations entering the western provincial market. The Luján de Cuyo assembly corridor connects Chilean export channels with Argentine adaptive lighting module distribution.
Argentina Automotive Adaptive Lighting System Market Competitive Environment
Listed leaders compete with private specialists across intellectual property control and captive electronics production. The supplier base concentrates around three Tier-1 integrators that have absorbed previously discrete lamp and sensor sourcing functions. Strategic archetypes separate matrix LED patent holders, integrated electronics-lamp module platforms, and European engineering-dependent local assemblers. Dominant competitive moves include technology licensing from German parent operations and backward integration into LED driver IC sourcing.
Within the European engineering-dependent tier, HELLA KGaA Hueck & Co. and Valeo Group exemplify suppliers leveraging captive R&D partnerships with German-brand vehicle plants. Hyundai Mobis occupies a position representing integrated electronics-lamp module platforms extending to regional OEM programs. These three anchors demonstrate how patent control and sensor fusion capabilities determine specification authority in Buenos Aires and Córdoba assembly corridors.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Valeo Group |
| Hyundai Mobis |
| Magneti Marelli SpA |
| Koito Manufacturing Co. Ltd |
| Koninklijke Philips N.V. |
| Stanley Electric Co. Ltd |
| Osram Licht AG |
| Texas Instruments |
| Others |
Value Chain & Pricing Dynamics
Long-term module supply contracts between Tier-1 lighting integrators and Buenos Aires assembly plants lock in semiconductor allocation priority and dampen spot-market volatility for LED driver ICs. These agreements tether pricing visibility to Mercosur type-approval timelines, forcing suppliers to absorb certification delays into fixed-price structures while OEMs secure volume commitments for mid-luxury platform ramps.
Pricing Analysis
Matrix LED-to-Adaptive Xenon pricing gaps of approximately two-to-one separate premium sensor-fusion architectures from motorized reflector systems in Córdoba fleet procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and electronics content, with UNECE R123-compliant modules commanding sustained premiums. Cost compression in entry-tier halogen retrofits is intensifying because aftermarket distributors source unbranded Asian modules, eroding margin structures for established suppliers. Fleet procurement managers in commercial truck segments exhibit highest price sensitivity, while German-brand OEMs in Buenos Aires Province demonstrate lowest sensitivity due to platform-level integration requirements.
Supply Chain Analysis
Inventory buffers for LED driver ICs and CMOS image sensors currently stretch to twenty-six weeks, reflecting foundry allocation constraints that ripple through Argentine assembly schedules. Core supply concentrates in Germany, South Korea, and Japan, with matrix LED intellectual property and sensor fusion algorithms anchored in Stuttgart, Munich, and Seoul engineering centers. Argentine module assembly draws from Taiwanese wafer fabrication for processing chips, Chinese substrate manufacturing for LED packages, and European optical component specialists. Single-source vulnerability in automotive-grade semiconductor supply creates exposure to foundry allocation decisions. Distribution runs through captive Tier-1 logistics networks directly into Córdoba and Buenos Aires assembly plant docks, bypassing traditional aftermarket wholesale channels for OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's adaptive lighting sector sits at a platform-economics inflection where sensor-lamp module standardization across Mercosur assembly networks will determine which suppliers capture recurring specification authority. The interoperability shift toward combined ADAS-lighting function packages is collapsing previously discrete electronics sourcing tiers into unified procurement decisions.
For Market Incumbents: Fortify captive R&D partnerships with German-brand vehicle plants by embedding firmware engineering teams within Córdoba and Buenos Aires facilities, countering the threat of Korean integrated electronics-lamp module platforms that Hyundai Mobis is extending from Asian parent operations. Prioritize backward integration into LED driver IC sourcing through long-term foundry capacity reservations, securing allocation priority that emerging entrants cannot match during semiconductor supply crunches. For New Entrants and Emerging Players: Aftermarket calibration services for collision repair channels represent a service-layer gap where incumbents under-serve independent distributors lacking UNECE R123 homologation expertise. Target certified module refurbishment and software update capabilities for Buenos Aires Province repair networks, penetrating the fastest-expanding aftermarket channel without confronting Tier-1 OEM supply contracts directly. Pursue white-label partnerships with Chinese LED module manufacturers to undercut branded replacement pricing in price-sensitive fleet segments. For Investors and Strategic Acquirers: Capital is best deployed toward electronics-lamp module integrators with captive Mercosur homologation capabilities and established relationships with the Secretariat of Industry and Productive Development's import substitution incentive programs. Long-term viability across the analysis window hinges on suppliers' ability to absorb sensor fusion and control electronics functions previously sourced separately. Monitor pending Mercosur automotive safety harmonization protocol updates as the critical inflection signal—accelerated beam-pattern digitization requirements would force accelerated R&D cycles that favor incumbent balance sheet strength over emerging player agility.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Lamp Module Integration | Consolidates previously discrete electronics and optical sourcing under single-supplier contracts, simplifying warranty administration for Buenos Aires OEMs. |
| Local Electronics Control Module Production | Qualifies suppliers for Secretariat of Industry and Productive Development import substitution incentives, reshaping Tier-1 competitive positioning. |
| ADAS-Lighting Function Convergence | Enables combined forward-facing camera packages that streamline procurement for mid-luxury platforms across Córdoba assembly corridors. |
| Mercosur Homologation Pre-Certification | Compresses time-to-revenue for new vehicle registrations by parallel-tracking development and type-approval processes under UNECE R123. |
| Commercial Truck Safety Specification | Captures emerging highway compliance requirements for dynamic leveling on interstate corridors connecting Córdoba to Buenos Aires. |
Study Parameters
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement patterns anchors the qualitative findings in documented specification trends rather than aspirational technology roadmaps. Primary interviews with automotive lighting system architects, Mercosur homologation specialists, fleet procurement managers, and aftermarket distribution heads were combined with secondary validation from UNECE regulatory filings, vehicle production databases, and import substitution incentive program records. Bottom-up triangulation across module-level bill-of-materials analysis and top-down reconciliation with assembly plant capacity announcements ensures segmentation integrity.
Sensitivity analysis around semiconductor supply scenarios and Mercosur protocol implementation timelines frames the projection range without overstating point-estimate precision. The analytical framework models demand across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from fitted growth curves applied to disclosed platform production schedules and technology penetration assumptions, with LED adoption curves and ADAS bundling rates serving as primary forecast inputs.
Forecasts assume regulatory continuity in Mercosur automotive safety harmonization and Argentine import substitution frameworks; material policy shifts would require re-modeling technology adoption trajectories and supplier qualification criteria. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market