
 Automotive Coupling Replacement Kit Market | 2026-2036
Automotive Coupling Replacement Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coupling Replacement Kit Market Insights
EPA Phase 2 greenhouse-gas standards for medium- and heavy-duty engines is shifting the cost-of-entry calculus for coupling replacement kit suppliers, forcing redesigns that accommodate tighter driveline tolerances and reduced friction losses. ZF Friedrichshafen leverages its integrated powertrain engineering to bundle coupling kits with transmission service programs. Dana Incorporated anchors its position through captive distribution to commercial fleet operators. Timken competes on material science, sustaining margin pools in thermal-treated steel hubs.
An automotive coupling replacement kit comprises matched assemblies of hubs, sleeves, fasteners, and alignment hardware engineered to restore torque transmission between rotating shafts in vehicle drivetrains; typical kits specify torque ratings from 500 Nm to 50,000 Nm and incorporate surface-hardened alloy steel or composite elastomer elements manufactured through CNC machining and induction heat treatment. Flexible coupling kits dominate volume in passenger vehicle aftermarket channels where misalignment tolerance and NVH dampening command premium positioning. Gear coupling configurations lead commercial truck applications, with elastomeric variants gaining share in agricultural machinery where contamination resistance and field-serviceability reduce downtime costs.
NHTSA Federal Motor Vehicle Safety Standards govern structural integrity and labeling requirements for replacement driveline components sold in the United States, while ISO 1940 balancing grades define acceptable residual unbalance for high-speed coupling applications across export markets. The EU F-Gas Regulation indirectly shapes demand patterns as fleet operators extend vehicle replacement cycles, deferring full powertrain swaps in favor of component-level refurbishment. Stakeholders must monitor evolving harmonization between SAE J620 torque capacity standards and emerging electric axle architectures, as e-motor integration redefines coupling duty cycles and thermal envelopes.
Market Dynamics
Extended vehicle replacement cycles across North American commercial fleets are compressing coupling refurbishment intervals, forcing aftermarket suppliers to engineer kits compatible with aging driveline architectures while accommodating EPA Phase 2 emissions tolerances.
Growth Catalysts
- EPA Phase 2 greenhouse-gas standards:Tighter driveline tolerances in medium- and heavy-duty vehicles mandate precision-matched replacement components, elevating kit specifications across Class 6-8 truck segments.
- Fleet preventive maintenance programs:Commercial operators in the United States are systematizing driveline component swaps at 500,000-mile intervals, institutionalizing recurring kit demand.
- Induction heat treatment:Surface-hardened alloy steel manufacturing processes extend coupling service life, reducing total cost of ownership and justifying premium kit positioning.
Market Restraints
- Alloy steel input volatility:Thermal-treated hub production depends on nickel and chromium price stability, compressing margin pools when commodity markets spike.
- Captive distribution concentration:Dana Incorporated's direct fleet relationships lock independent distributors out of high-volume commercial channels, fragmenting aftermarket access.
- SAE J620 torque standard lag:Slow harmonization with electric axle architectures delays kit certification for e-motor integration, freezing supplier R&D allocation.
Strategic Opportunities
- Agricultural machinery elastomeric variants:Contamination-resistant coupling kits for field-serviceable equipment address downtime-sensitive harvest operations in the United States Corn Belt.
- ISO 1940 balancing grade adoption:Export markets demanding high-speed coupling residual unbalance certification create premium positioning for precision-manufactured kit suppliers.
- E-commerce direct-to-fleet channels:Digital procurement platforms bypass traditional jobber networks, capturing margin previously allocated to distribution intermediaries.
Industry Challenges
- NVH dampening engineering talent:Shortage of specialists in composite elastomer formulation and misalignment tolerance modeling constrains flexible coupling development pipelines.
- NHTSA Federal Motor Vehicle Safety Standards certification:Extended structural integrity testing timelines for replacement driveline components delay product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coupling Replacement Kit Market |
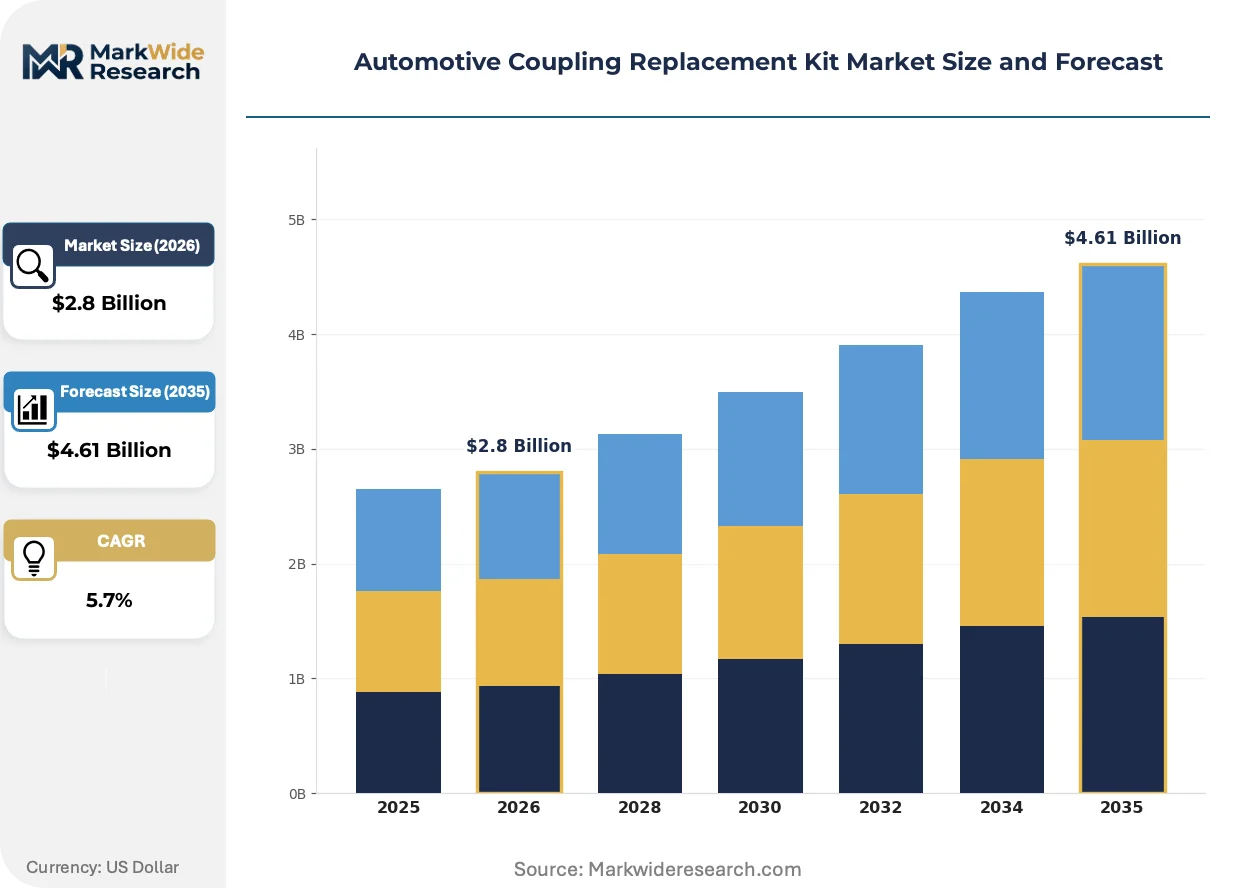
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Coupling, Rigid Coupling, Fluid Coupling, Gear Coupling, Elastomeric Coupling Application: Passenger Vehicles, Commercial Trucks, Agricultural Machinery, Construction Equipment, Material Handling Machines End User: OEMs, Aftermarket Suppliers, Vehicle Service Centers, Fleet Operators, Independent Garages Distribution Channel: Direct Sales, Authorized Dealers, Online Retailers, Auto Parts Stores, Industrial Distributors |
| Companies Covered | Aisin Seiki, ZF Friedrichshafen, Dana Incorporated, Timken, Regal Rexnord, Flender, Voith, SAF-Holland, JOST Werke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coupling Replacement Kit Market Trends and Innovations
Composite elastomer formulation is displacing conventional steel-sleeve architectures in passenger vehicle channels, while regulatory pressure on driveline efficiency accelerates material science investment across supplier engineering centers.
Surface-hardened alloy steel hub manufacturing is consolidating torque transmission reliability in commercial truck applications. Fleet operators spec these kits for 750,000-mile service intervals. The technology is consolidating supplier R&D budgets toward thermal treatment process automation.
EU F-Gas Regulation is extending heavy-duty vehicle replacement cycles across European Union member states. Fleet operators defer full powertrain swaps in favor of component-level refurbishment. Agricultural and construction equipment segments in Germany and France show strongest kit demand elasticity.
Direct digital procurement from fleet maintenance departments is compressing traditional jobber-distributor networks. United States Class 8 operators now specify kits through integrated fleet management platforms. Channel disintermediation is most visible in long-haul trucking verticals where telematics-enabled predictive maintenance triggers automated replenishment.
Automotive Coupling Replacement Kit Market Segmentation
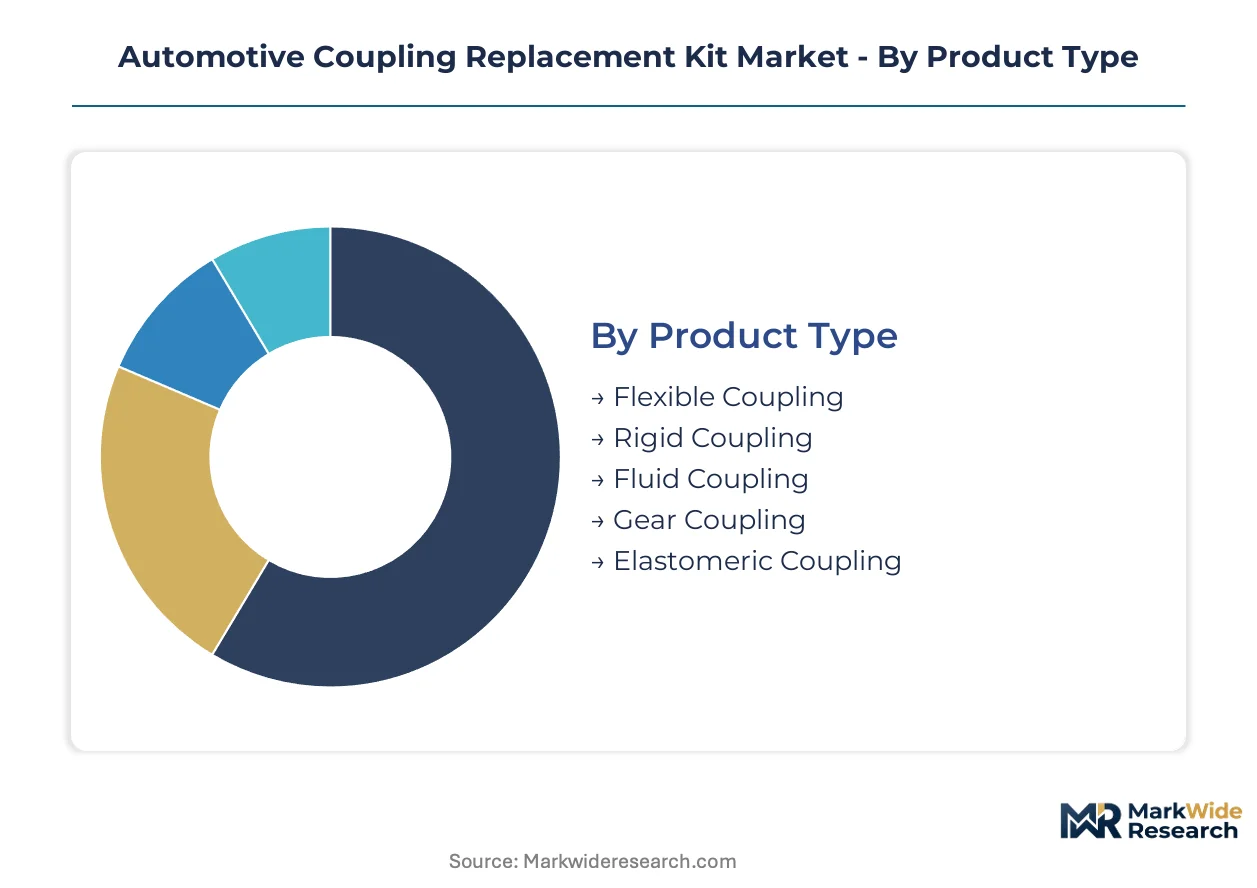
Segmentation in the Automotive Coupling Replacement Kit Market reveals how torque transmission requirements, vehicle duty cycles, and procurement pathways fragment demand across distinct technical and commercial configurations. Each dimension carries unique certification burdens, margin structures, and channel access patterns that suppliers must navigate.
Product Type:
NHTSA Federal Motor Vehicle Safety Standards apply differentially across product categories, with flexible and gear coupling kits facing distinct structural integrity testing timelines and ISO 1940 balancing grade requirements for high-speed applications.
- Flexible Coupling:Composite elastomer elements dampen NVH in passenger vehicle drivelines where misalignment tolerance commands premium positioning. Demand concentrates in United States aftermarket channels serving aging light-duty fleets with extended replacement cycles.
- Gear Coupling:Surface-hardened alloy steel hubs transmit torque up to 50,000 Nm in Class 6-8 commercial trucks. United States long-haul operators spec these kits for 750,000-mile service intervals under EPA Phase 2 emissions tolerances.
- Elastomeric Coupling:Contamination-resistant variants address agricultural machinery field-serviceability requirements.
- Fluid Coupling:Torque converter replacement kits serve heavy-duty construction equipment segments.
- Rigid Coupling:Precision-machined steel sleeves restore alignment in high-speed industrial powertrain applications.
Gear coupling sits at the top of the volume ranking, with elastomeric coupling climbing the fastest.
Application:
Cost tier stratification separates premium OEM-specified kits from economy aftermarket alternatives, with commercial trucks absorbing the highest per-unit expenditure due to torque rating requirements and preventive maintenance institutionalization.
- Commercial Trucks:Class 8 operators in the United States systematize driveline component swaps at 500,000-mile intervals. Fleet management platforms now trigger automated kit replenishment through telematics-enabled predictive maintenance.
- Agricultural Machinery:Field-serviceable coupling kits reduce harvest downtime in the United States Corn Belt. Contamination-resistant elastomeric variants gain share where equipment operates in abrasive soil and crop residue environments.
- Passenger Vehicles:Flexible coupling kits dominate volume in light-duty aftermarket channels.
- Construction Equipment:Fluid coupling replacements address hydraulic powertrain refurbishment cycles.
- Material Handling Machines:Rigid coupling kits restore precision in warehouse automation systems.
Commercial trucks command the highest kit expenditure per vehicle, with agricultural machinery expanding most quickly.
End User:
Procurement patterns diverge sharply between captive fleet relationships and fragmented independent channels, determining margin capture and technical support intensity.
- Fleet Operators:United States Class 8 trucking fleets bypass traditional jobber networks through direct digital procurement platforms. Integrated fleet management systems consolidate kit specification, pricing negotiation, and automated replenishment.
- Aftermarket Suppliers:Independent distributors compete on inventory breadth and same-day availability for vehicle service centers. Channel access fragmentation intensifies where Dana Incorporated's direct fleet relationships lock out high-volume commercial segments.
- OEMs:Powertrain manufacturers specify coupling kits for warranty service programs.
- Vehicle Service Centers:Franchise operations standardize kit selection through approved vendor programs.
- Independent Garages:Price-sensitive procurement favors economy-tier alternatives with shorter service life.
Fleet operators generate the largest transaction volumes, with aftermarket suppliers gaining share fastest through e-commerce channel development.
Distribution Channel:
Supply concentration in direct sales and authorized dealer networks shapes pricing transparency and technical service availability across end-user segments.
- Direct Sales:Captive distribution from Dana Incorporated and ZF Friedrichshafen locks in United States commercial fleet operators with bundled transmission service programs. Long-term contracts specify torque-rated kits aligned to vehicle telematics data.
- Online Retailers:Digital procurement platforms compress traditional jobber-distributor margins in passenger vehicle aftermarket channels. United States independent garages increasingly specify kits through integrated e-commerce interfaces with VIN-based fitment verification.
- Authorized Dealers:OEM-aligned networks control warranty-compliant kit distribution.
- Auto Parts Stores:Counter sales serve walk-in trade with immediate availability requirements.
- Industrial Distributors:Bulk procurement contracts address manufacturing and material handling equipment segments.
Direct sales retains the highest revenue concentration, with online retailers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in precision machining and thermal treatment anchor geographic production advantages. Regional demand patterns diverge sharply based on fleet composition, emissions enforcement intensity, and agricultural equipment density.
United States
Class 8 truck utilization rates and aging commercial fleets sustain above-average kit consumption. NHTSA Federal Motor Vehicle Safety Standards govern structural integrity and labeling requirements for replacement driveline components. The Midwest industrial corridor concentrates surface-hardened alloy steel hub manufacturing serving long-haul operators.
Germany
EU F-Gas Regulation extends heavy-duty vehicle replacement cycles across member states. Fleet operators defer full powertrain swaps in favor of component-level refurbishment. The Stuttgart powertrain cluster drives precision-manufactured kit development for export markets demanding ISO 1940 balancing grade certification.
China
Domestic commercial vehicle production scales and infrastructure investment sustain gear coupling demand in heavy-duty applications. MIIT standards govern driveline component quality certification for domestic and export markets. The Yangtze River Delta concentrates CNC machining capacity for alloy steel coupling sleeves.
India
Agricultural machinery density and field-serviceability requirements drive elastomeric coupling kit adoption. BIS standards regulate automotive component interchangeability and safety specifications. The Maharashtra-Pune industrial belt hosts flexible coupling manufacturing for tractor and harvester aftermarket channels.
Japan
Precision manufacturing heritage and JIS standards alignment support high-speed coupling residual unbalance certification. METI industrial policy incentivizes thermal treatment process automation in component manufacturing. The Aichi-Nagoya automotive cluster integrates coupling kit production with transmission system engineering.
Automotive Coupling Replacement Kit Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across torque transmission component manufacturing. The vendor base separates into three strategic archetypes: integrated powertrain engineers, captive distribution operators, and material science specialists. Consolidation pressures intensify as fleet operators demand bundled service programs and automated replenishment systems. Dominant competitive moves include backward integration into thermal treatment capacity and direct digital channel development bypassing traditional jobber networks.
Among German-based engineering conglomerates, ZF Friedrichshafen AG exemplifies integrated powertrain bundling strategies. Dana Incorporated occupies a position within the captive distribution archetype through direct fleet relationship models. Timken represents material science specialization anchored in thermal-treated steel hub manufacturing. These three anchors illustrate divergent paths for margin capture and channel access in commercial vehicle aftermarket segments.
| Leading Market Players |
|---|
| Aisin Seiki |
| ZF Friedrichshafen |
| Dana Incorporated |
| Timken |
| Regal Rexnord |
| Flender |
| Voith |
| SAF-Holland |
| JOST Werke |
| Others |
Pricing and Supply Chain Analysis
Precision induction heat treatment specialists in the Midwest industrial corridor command wage premiums that compress margin pools in economy-tier kit manufacturing while widening spreads to premium SAE J620-certified alternatives. Labor-cost differentials between thermal treatment automation engineers and conventional CNC machinists directly stratify pricing tiers across flexible, gear, and elastomeric coupling configurations.
Pricing Analysis
Bundled transmission service programs from integrated powertrain engineers capture premium positioning against unbundled component sales through independent distributors. Three-tier pricing structure across premium certified-grade, standard OEM-specified, and economy aftermarket levels separates fleet contract rates from jobber counter pricing. Cost compression in economy tiers intensifies as nickel and chromium input volatility feeds through thermal-treated hub production. Fleet operators exhibit lowest price sensitivity due to telematics-enabled total cost of ownership calculations, while independent garages prioritize immediate availability over specification grade.
Supply Chain Analysis
Freight cost escalation on alloy steel billet shipments from the Yangtze River Delta to Midwest machining centers is compressing margin pools for non-integrated suppliers. Production concentrates in Germany, China, and the United States, with CNC machining capacity clustering around Stuttgart, Shanghai-Ningbo, and Detroit-Toledo corridors. Raw material dependencies center on nickel-chromium alloy steel, composite elastomer formulations, and induction heat treatment consumables. Single-source vulnerability in surface-hardening equipment creates bottleneck risk for premium kit certification. Distribution runs through captive direct sales to fleet operators, authorized dealer networks, and emerging e-commerce platforms serving independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Coupling Replacement Kit Market functions as a stable compounder anchored by institutionalized preventive maintenance cycles in United States Class 8 commercial fleets. Extended vehicle replacement cycles compress refurbishment intervals into recurring revenue streams for component suppliers.
For Market Incumbents: Anchor market position through backward integration into captive induction heat treatment capacity in the Midwest industrial corridor, insulating margin pools from alloy steel input volatility. Deepen direct digital channel development to bypass jobber-distributor networks where Dana Incorporated's fleet relationships lock out independent competitors. Prioritize SAE J620 harmonization investment to preempt electric axle architecture certification delays.
For New Entrants and Emerging Players: Enter via contamination-resistant elastomeric coupling kits for United States Corn Belt agricultural machinery, where field-serviceability requirements and downtime-sensitive harvest operations create penetrable white space. Target e-commerce direct-to-fleet channels in long-haul trucking verticals where telematics-enabled predictive maintenance triggers automated replenishment. Pursue ISO 1940 balancing grade certification to access premium export positioning.
For Investors and Strategic Acquirers: Integrated powertrain engineering conglomerates represent the most active acquirer category in this space, seeking thermal treatment automation capabilities and captive fleet distribution relationships. Mid-term viability rests on component-level refurbishment preference over full powertrain replacement cycles. Monitor EPA Phase 2 enforcement intensity as inflection indicator for precision-matched kit specification upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Treatment | Captive induction hardening capacity insulates Timken and Dana from nickel-chromium price spikes. |
| Direct Digital Channel Development | E-commerce platforms bypass traditional jobber networks, capturing margin previously allocated to distribution intermediaries. |
| SAE J620 Harmonization Investment | Early certification for electric axle architectures unlocks e-motor integration kit demand. |
| ISO 1940 Balancing Grade Adoption | Precision-manufactured kits access premium export markets demanding residual unbalance certification. |
| Agricultural Elastomeric Variant Expansion | Contamination-resistant kits address downtime-sensitive harvest operations in the United States Corn Belt. |
Research Methodology
Bottom-up fleet operator demand modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with aftermarket distribution managers, Tier 1 supplier procurement leads, fleet maintenance directors, and thermal treatment process engineers combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, EPA Phase 2 compliance databases, vehicle production registries, and SEC supplier filings. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of coupling kit replacement intervals, fleet utilization rates, and commodity input cost trajectories informed projection framework development. Segmentation modeling spanned product type, application, end user, and distribution channel dimensions, with vehicle class and propulsion architecture introduced as cross-cutting variables. CAGRs derived from fitted trend extrapolation adjusted for regulatory enforcement intensity and technology substitution patterns. Forecast inputs incorporated EPA emissions timeline phasing, electric axle adoption curves, and preventive maintenance program institutionalization rates.
Inputs from fleet operator maintenance records and supplier shipment disclosures were available through the study window; gaps in independent garage procurement transaction data introduce uncertainty bands in aftermarket channel sizing. Forecasts reflect documented assumptions regarding replacement cycle compression and commodity price stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Vents Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Odometer Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Lubricants Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Automotive Oil and Air Filters Market