
 Global Automotive Junction Box Market | 2026-2036
Global Automotive Junction Box Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Junction Box Market Intelligence
The shift towards intelligent power distribution and smart fuses is narrowing the gap between traditional junction boxes and centralized domain controllers. Robert Bosch GmbH leverages its deep expertise in automotive electronics to develop integrated solutions for complex vehicle architectures. Meanwhile, Yazaki Corporation specializes in wiring harnesses and related components, while Lear Corporation differentiates through its focus on complete seating and E-systems, integrating power management directly into its product lines.
An automotive junction box is an enclosure that centralizes a vehicle's electrical protection and distribution components, including fuses and relays. It functions as the primary node for managing power flow from the battery to circuits controlling everything from lighting to engine management systems. Integrated Junction Box designs are gaining prominence, driven by demand from the Electric Vehicles application segment for consolidated power management. OEMs represent the largest end-user group, directly specifying junction box requirements to support new platform architectures.
Product design and reliability are governed by stringent standards, including ISO 26262 for functional safety and specific mandates from regulators like the NHTSA in the United States. In China, compliance with GB standards for electrical components is mandatory for market access, influencing material selection and testing protocols. Component suppliers must now decide whether to specialize in legacy fuse box designs or invest in the advanced capabilities required for smart, software-defined junction units.
Market Dynamics
The fundamental restructuring of vehicle electronic/electrical (E/E) architectures represents the central force shaping the market. A transition away from decentralized, domain-specific controllers toward zonal architectures compels a complete reimagining of the junction box's role from a passive fuse holder to an intelligent power distribution node.
Growth Catalysts
- Zonal E/E Architectures:The automotive industry's shift towards zonal designs, particularly within the Electric Vehicles segment, requires intelligent junction boxes that can manage complex power routing and provide diagnostic data, consolidating functions previously spread across the vehicle.
- Functional Safety Mandates:Stringent standards like ISO 26262 demand higher levels of system reliability and fail-safe operation. This pushes OEMs to adopt advanced junction boxes with built-in redundancy and self-diagnostic capabilities to ensure vehicle safety.
- OEM Demand Concentration:Concentrated demand from automotive manufacturing hubs in Germany, Japan, and South Korea for sophisticated power management solutions to support next-generation platforms provides a consistent impetus for innovation and product development by suppliers.
Market Restraints
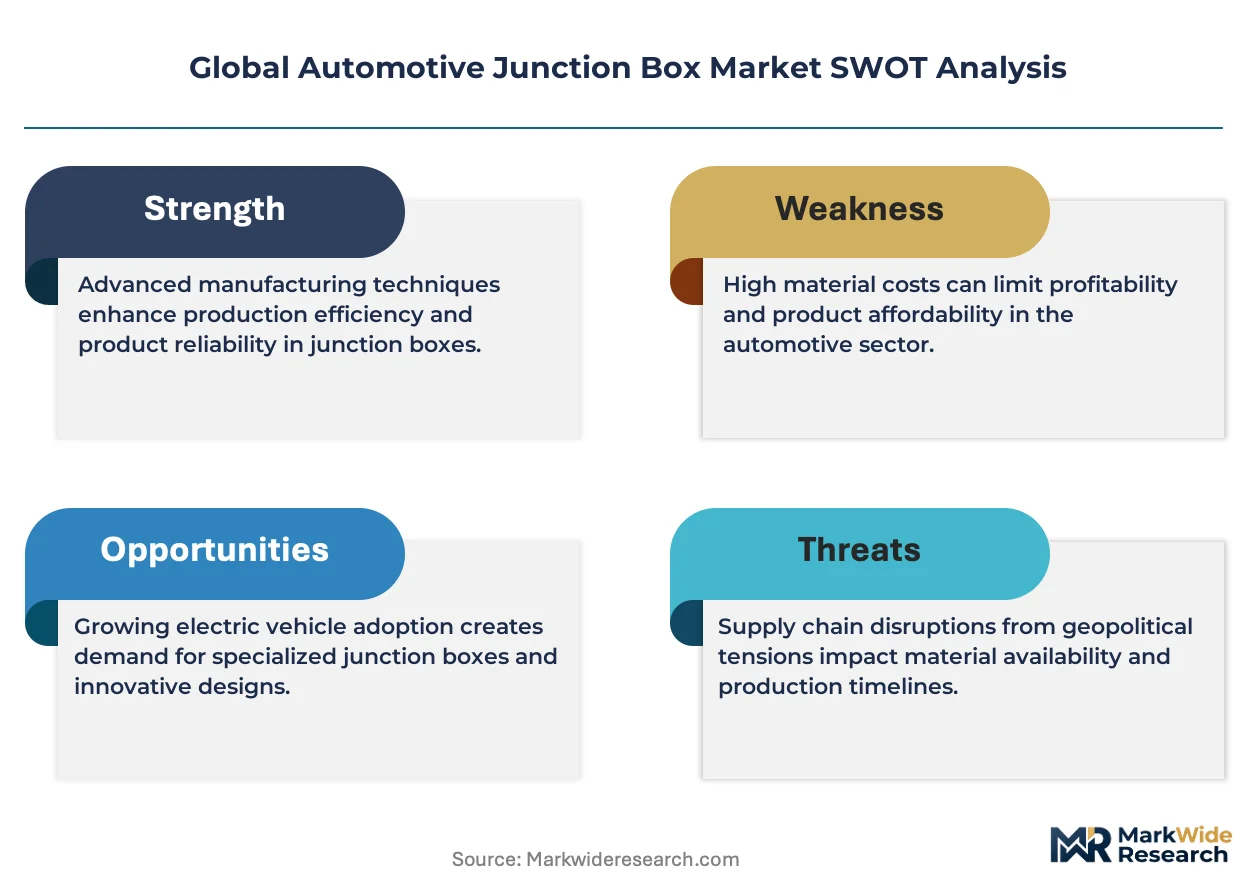
- High Development Costs:The integration of advanced semiconductors, software, and complex validation cycles for smart junction boxes significantly elevates research and development expenditures, creating a high barrier to entry for smaller component suppliers.
- Thermal Management Limitations:Increasing power density within a compact, integrated junction box creates significant thermal dissipation challenges. Managing heat effectively without compromising reliability or form factor is a primary engineering constraint for designers.
- Functional Absorption by Domain Controllers:The advancement of centralized vehicle computers presents a substitution threat. These powerful controllers could eventually absorb all power switching and protection functions, rendering standalone junction boxes redundant in future architectures.
Strategic Opportunities
- Power and Data Convergence:Integrating high-speed data networking capabilities, such as Ethernet switches, directly into the junction box creates a new product class of hybrid power and data distribution hubs, offering significant value in data-intensive vehicle platforms.
- Commercial Vehicle Electrification:The growing market for electric buses and trucks presents an opportunity for robust, high-voltage junction box solutions. These applications require specialized designs capable of handling significantly higher power loads and more demanding operating conditions than passenger cars.
- Policy-Driven EV Expansion:National policies, such as China's dual carbon goals, accelerate the transition to electric mobility. This creates a massive, state-supported addressable market for suppliers of advanced E/E components, including intelligent junction boxes.
Industry Challenges
- Legacy System Integration:Integrating new, software-defined junction boxes with existing wiring harnesses and legacy vehicle control units during transitional product cycles creates significant engineering complexity and potential for system-level conflicts.
- Lengthy Certification Cycles:Achieving compliance with functional safety standards like ISO 26262 and passing rigorous OEM-specific validation testing is a time-consuming and expensive process, which can delay the introduction of new technologies to the market.
- Specialized Engineering Talent Scarcity:A shortage of systems engineers possessing dual expertise in high-voltage power electronics and embedded software for automotive networks acts as a bottleneck, slowing down product development and innovation across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Junction Box Market |
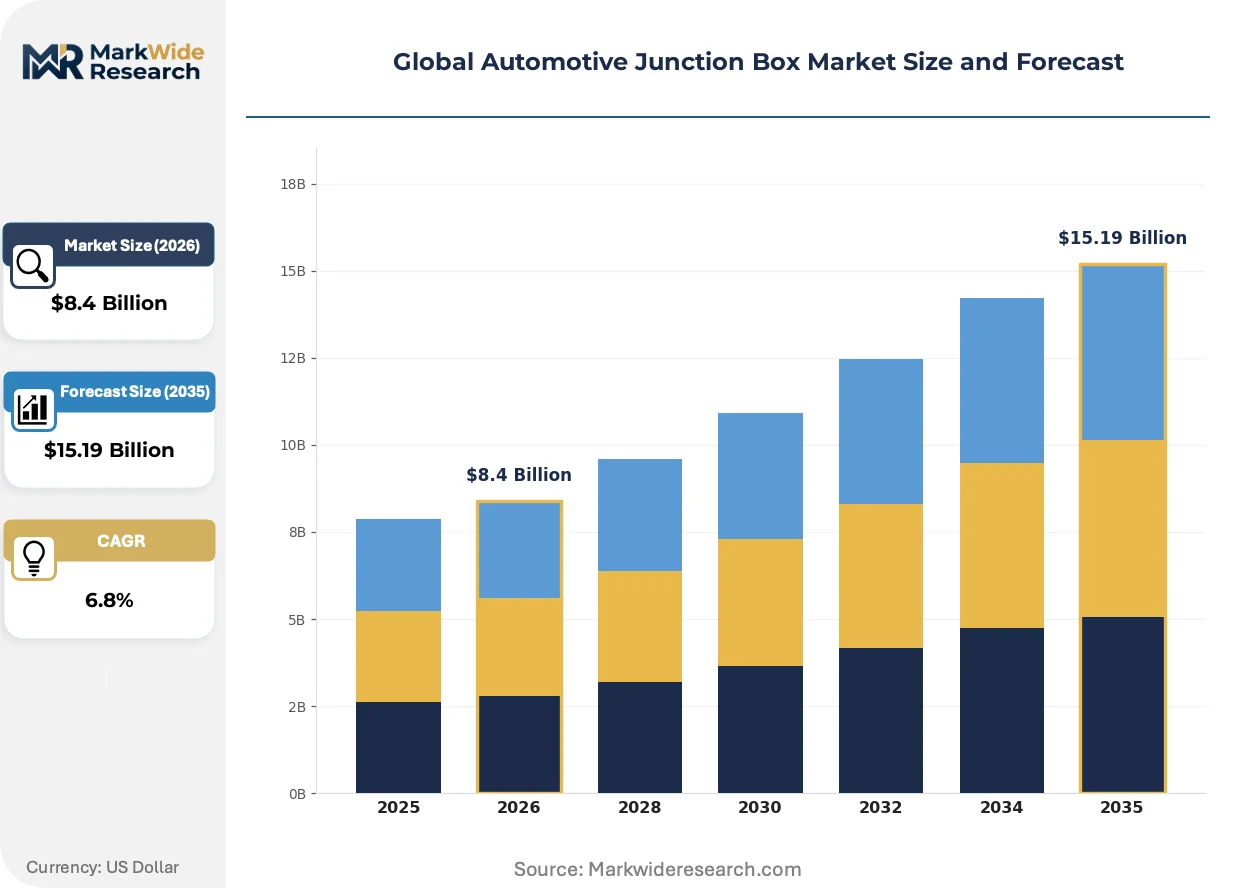
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Junction Box, Fuse Box, Distribution Box, Circuit Protection Box Technology: Blade Fuse, Mini Blade Fuse, Maxi Blade Fuse, Cartridge Fuse, Relay Technology Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Off-Highway Equipment End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Lear Corporation, Sumitomo Electric Industries, Robert Bosch GmbH, Aptiv PLC, Denso Corporation, Continental AG, TE Connectivity Ltd., BorgWarner Inc., Yazaki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Junction Box Market Strategic Shifts & Innovations
The market's evolution is defined by the component's transformation from a passive electrical housing into an active, intelligent node within the vehicle's nervous system. This shift elevates the junction box's role to a critical enabler of software-defined vehicle functionalities and advanced safety features.
Intelligent relays and resettable smart fuses form the technological core of modern junction box designs. These solid-state components provide software-controlled circuit protection and advanced diagnostics. OEMs in the Electric Vehicles segment are the primary adopters, specifying these features for new zonal E/E platforms. This technology is hybridizing the traditional junction box with the functions of a localized domain controller, merging power management with network intelligence.
Regulatory scrutiny from bodies like the NHTSA in the United States regarding electrical system fire risks in EVs is intensifying. This pressure compels automakers to incorporate more sophisticated monitoring and protection mechanisms within their power distribution systems. The Electric Vehicles segment is most impacted, driving the specification of junction boxes with advanced fault-prediction algorithms to satisfy functional safety requirements and mitigate recall risks.
Automaker purchasing behavior is pivoting from sourcing discrete components to procuring pre-validated, fully integrated power distribution modules. This change in procurement favors large Tier 1 suppliers capable of delivering a complete system, thereby disrupting the business model for smaller specialists focused on individual fuses or relays. This trend is most visible in Germany and South Korea, where OEMs are aggressively streamlining supply chains for next-generation vehicle architectures.
Global Automotive Junction Box Market Segmentation
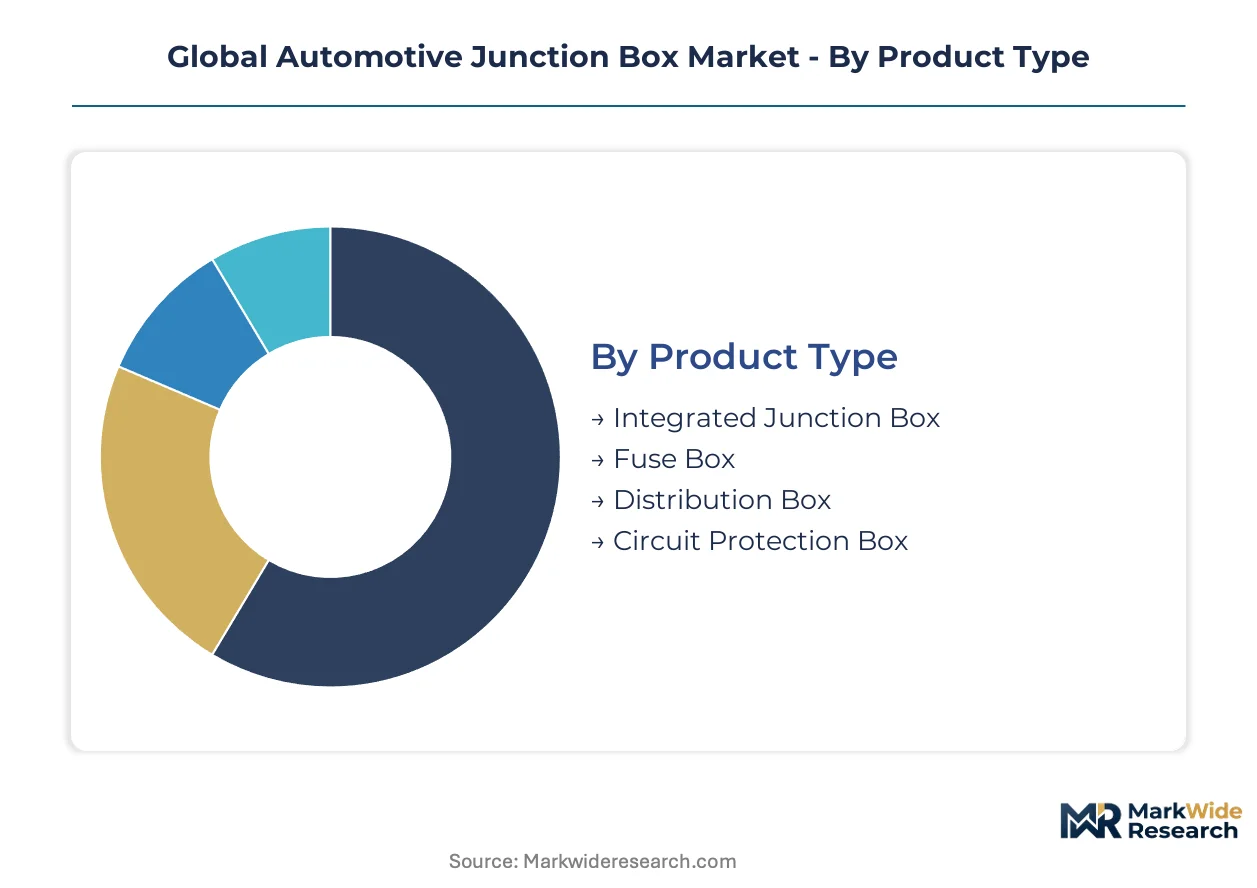
The global automotive junction box market is analyzed across various dimensions to understand its intricate structure and evolving dynamics. This segmentation provides clarity on technological advancements and demand patterns influencing component development. Understanding these divisions helps stakeholders identify key growth areas and strategic investment opportunities within power distribution systems.
Product Type:
Product type differentiation highlights the evolution from basic protection units to sophisticated power management modules. Designs address specific vehicle architectural needs.
- Integrated Junction Box:This unit combines fuses, relays, and electronic control units into a single housing, streamlining electrical architecture. Demand concentrates in Electric Vehicles for consolidated power management and efficient space utilization.
- Fuse Box:A traditional Fuse Box primarily houses fuses to protect circuits from overcurrents, acting as a passive distribution point. Passenger Cars represent significant demand, relying on these cost-effective units.
- Distribution Box:This box manages power routing to major vehicle systems, often incorporating relays and circuit breakers for robust performance.
- Circuit Protection Box:Specialized for safeguarding critical electrical circuits, often found in heavy-duty or off-highway applications requiring enhanced durability.
Fuse Box commands the established base. The steepest expansion runs through Integrated Junction Box.
Technology:
Technological advancements shape the performance, safety, and intelligence of circuit protection. Innovations dictate current handling capabilities and diagnostic features.
- Relay Technology:Involves electromechanical or solid-state switches controlling high-current circuits with low-current signals. Electric Vehicles drive demand for sophisticated relay solutions, enabling precise power control for high-voltage components.
- Cartridge Fuse:Designed for higher current applications with a cylindrical body and metal end caps, providing robust protection against sustained overloads. Commercial Vehicles and Off-Highway Equipment concentrate demand.
- Blade Fuse:Common in passenger cars, offering compact, color-coded protection for a wide range of low-to-medium current circuits.
- Mini Blade Fuse:Provides space-saving circuit protection, frequently utilized in constrained automotive electronic modules and accessory power feeds.
- Maxi Blade Fuse:Handles higher currents than standard blade fuses, typically protecting primary power distribution lines and larger vehicle components.
Relay Technology is gaining share fastest, while Blade Fuse remains a foundational component.
Application:
Application segments delineate specific vehicle types and operational environments. Each segment presents unique challenges regarding power density and functional requirements.
- Electric Vehicles:Junction boxes manage high-voltage power distribution, integrate thermal management, and enable advanced battery system communication, critical for safety. Global policy-driven EV expansion in China and Europe drives significant demand.
- Passenger Cars:These junction boxes provide centralized electrical protection for lighting, infotainment, and engine control units, balancing cost-effectiveness with reliability. This segment represents the largest volume concentration globally.
- Commercial Vehicles:Require robust junction boxes capable of handling heavy electrical loads and enduring demanding operating conditions for extended periods.
- Off-Highway Equipment:Junction boxes must withstand extreme environmental factors, providing reliable power distribution for heavy machinery in construction and agriculture.
Passenger Cars continue to dominate volume, but Electric Vehicles are expanding most quickly.
End User:
End-user categories define primary purchasers and integrators of automotive junction box components. Their procurement patterns shape supplier strategies and product offerings.
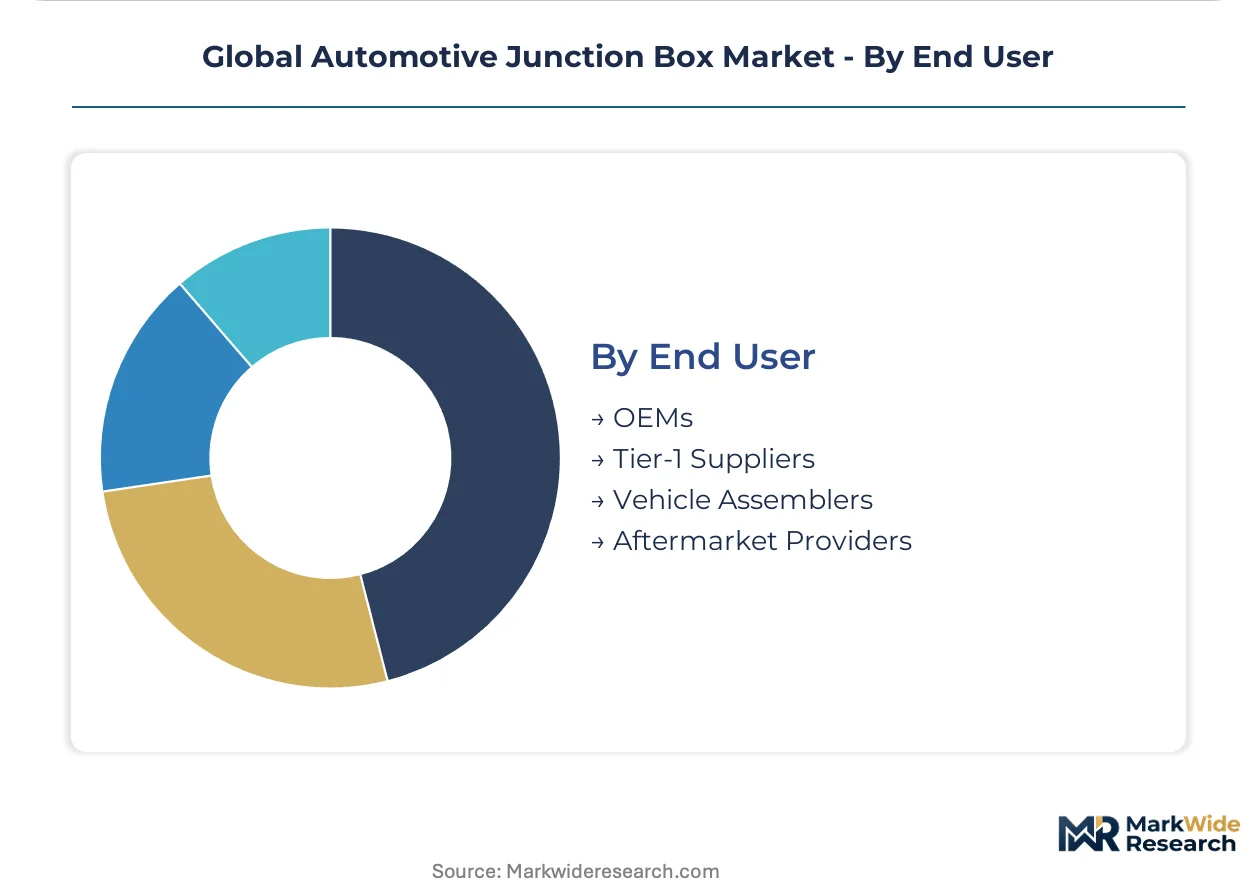
- OEMs:Original Equipment Manufacturers directly specify and integrate junction boxes into their vehicle platforms, requiring customized and validated solutions. Concentrated demand from Germany, Japan, and South Korea drives innovation for advanced E/E architectures.
- Tier-1 Suppliers:Develop and integrate complex E-systems and modules, often incorporating junction boxes as sub-components for OEMs. The shift towards pre-validated, integrated power distribution modules favors large Tier-1 suppliers.
- Vehicle Assemblers:Integrate pre-manufactured junction box units into final vehicle builds, focusing on efficient installation and quality control.
- Aftermarket Providers:Supply replacement junction boxes and related components for vehicle repairs and upgrades, catering to a diverse range of older vehicle models.
OEMs drive initial product specification, while Tier-1 Suppliers increasingly lead integrated module development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive industry drives significant demand for advanced junction box solutions, often exporting these critical components to major vehicle manufacturing hubs worldwide. This global trade reflects the complex interplay of innovation and concentrated market requirements. The market's evolution is heavily influenced by regional technological leadership and regulatory frameworks.
Germany
German OEMs require highly integrated junction boxes for advanced E/E architectures and premium vehicle platforms. Compliance with ISO 26262 functional safety standards is paramount for these critical components. The Stuttgart automotive cluster actively develops integrated power modules for future vehicle generations.
Japan
Japanese automakers prioritize reliable and compact junction box solutions for their high-volume passenger cars and growing EV fleets. Strict adherence to JIS standards ensures component quality and long-term durability. The Nagoya automotive cluster focuses on space-efficient designs for integrated power management units.
South Korea
South Korean vehicle manufacturers demand intelligent junction boxes for their rapidly expanding EV production and advanced connectivity features. National automotive safety regulations mandate stringent testing protocols for electrical system components. The Seoul metropolitan area actively integrates smart fuses and software-defined power distribution units.
China
China's vast Electric Vehicle market creates immense demand for high-voltage and integrated junction box solutions. Compliance with GB standards for electrical components is mandatory for market access, alongside dual carbon goals. The Yangtze River Delta region drives innovation in robust power distribution units for electric buses and trucks.
United States
United States vehicle manufacturers require advanced junction boxes for increasing EV production and robust commercial vehicle applications. NHTSA regulations and functional safety standards influence power distribution system design. Detroit and emerging EV manufacturing centers prioritize integrated power electronics and fault-prediction algorithms.
Global Automotive Junction Box Market Key Industry Players
Channel-controlling players compete with product-specialist players within the automotive junction box market, creating a tiered competitive landscape. Large Tier 1 suppliers dominate the integrated module segment, offering comprehensive power distribution units for new vehicle platforms. Smaller component firms often specialize in specific fuse or relay technologies, serving both legacy and advanced designs. Strategic partnerships and portfolio diversification are common competitive moves to address evolving E/E architectures and consolidate market share.
Among established automotive electronics providers, Germany-based Robert Bosch GmbH exemplifies a player leveraging deep expertise to develop integrated solutions for complex vehicle architectures. This firm focuses on advanced power distribution units that merge traditional functions with intelligent control. Japan's Yazaki Corporation occupies a position as a specialist in wiring harnesses and related components, including junction box integration for various vehicle types. Lear Corporation, a US-based firm, represents suppliers differentiating through comprehensive E-systems that integrate power management directly into broader product lines, catering to evolving OEM demands.
| Leading Market Players |
|---|
| Lear Corporation |
| Sumitomo Electric Industries |
| Robert Bosch GmbH |
| Aptiv PLC |
| Denso Corporation |
| Continental AG |
| TE Connectivity Ltd. |
| BorgWarner Inc. |
| Yazaki Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes significantly influence component costs, directly impacting the automotive junction box market's pricing structures. This dynamic shapes supply concentration and ultimately affects downstream price differentiation across vehicle segments.
Pricing Analysis
A significant pricing gap exists between legacy fuse box designs, current-generation integrated junction boxes, and next-generation smart, software-defined units. The dominant pricing model for OEMs involves contract-based long-term offtake agreements, driven by extensive validation cycles and platform customization. Price differentiation hinges on the level of functional safety certification, such as ISO 26262 compliance. Pricing softness reflects high development costs for advanced semiconductors and embedded software, making Passenger Car OEMs more price sensitive than Electric Vehicle and Commercial Vehicle manufacturers.
Supply Chain Analysis
The upstream feedstock for automotive junction boxes, particularly advanced semiconductors and specialized plastics, originates predominantly from East Asia. Geographic supply concentration centers in China for certain electronic components and polymer resins, and in Japan and South Korea for integrated circuit manufacturing. A significant supply chain risk involves single-source vulnerability for specialized microcontroller units required for smart junction boxes. Distribution runs through a dual model, with direct supply to OEMs for platform integration and through large Tier-1 suppliers who integrate these components into broader E-systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive junction box market represents an early-cycle expansion story, driven by the rapid adoption of zonal E/E architectures in Electric Vehicles. Policy-driven EV expansion in key regions provides a strong tailwind for advanced power distribution unit penetration.
For Market Incumbents: Harden core capabilities in integrated junction box design by accelerating investment in software-defined functionalities and advanced fault-prediction algorithms. Strategic acquisitions of niche technology firms specializing in smart fuses can mitigate the threat of functional absorption by centralized domain controllers. Leverage deep R&D expertise to develop high-density, integrated power modules that combine power and data distribution, reinforcing system-level value propositions for OEMs.
For New Entrants and Emerging Players: Establish a beachhead in the Commercial Vehicle electrification segment, focusing on robust, high-voltage junction box solutions for electric buses and trucks. Pursue white-space opportunities in power and data convergence by integrating high-speed Ethernet switches directly into distribution hubs. Commercial vehicle electrification is most penetrable due to its specialized requirements and demand for superior thermal management. A go-to-market strategy should emphasize these demanding niche applications.
For Investors and Strategic Acquirers: Niche technology firms specializing in embedded software for intelligent power distribution represent attractive acquisition targets. This market demonstrates strong long-term viability over a 5-10 year horizon, driven by the transition to Electric Vehicles and advanced E/E architectures. Look for companies with proven intellectual property in smart fuses or diagnostic algorithms. The key signal to watch is significant OEM platform wins for integrated zonal E/E architecture suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Investment in Software-Defined Capabilities | This initiative enables advanced diagnostics and remote updates for intelligent power distribution units in Electric Vehicles. |
| Strategic Partnerships with Semiconductor Suppliers | Securing access to critical microcontrollers and power electronics is vital for next-generation smart junction box development. |
| Expansion into Commercial Vehicle Electrification | Robust, high-voltage junction box solutions are essential for electric buses and trucks, serving a specialized market segment. |
| Acquisition of Functional Safety Expertise | Integrating ISO 26262 compliance and advanced validation processes enhances product reliability and OEM trust. |
| Development of Power and Data Convergence Modules | Hybrid power and data distribution hubs offer significant value in data-intensive vehicle platforms, supporting zonal architectures. |
Research Approach
The analysis maps key sub-sectors like Integrated Junction Boxes and Fuse Boxes, validated through primary interviews with OEM platform engineers. Stakeholders included Tier 1 procurement leads, E/E architects, and functional safety experts. Secondary validation drew from vehicle production databases, E/E architecture whitepapers, and regulatory filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and market sizing.
Assumptions for macroeconomic stability and Electric Vehicle adoption trends were held constant over the projection horizon. The analytical framework incorporated historical data and quantitative models. Segmentation modeled included Product Type, Technology, Application, End User, and E/E architecture complexity. Compound Annual Growth Rates were derived from volume and value projections, with EV production forecasts as a critical input.
Sensitivities concentrate around potential supply chain disruptions, rapid E/E architecture shifts, and evolving functional safety regulations. Forecasts reflect underlying assumptions, but these risk factors could necessitate revisions. Cross-checking against OEM technology roadmaps is advised before commitment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Global Body Control Modules Market