
 Automotive Electronics Sensor Aftermarket Market | 2026-2036
Automotive Electronics Sensor Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electronics Sensor Aftermarket Market Outlook
Sensor recalibration as a subscription-linked service layer is broadening what aftermarket providers sell beyond hardware replacement. Robert Bosch GmbH leverages its diagnostic equipment networks to capture recurring revenue from ADAS sensor alignment. Continental AG anchors its aftermarket position through proprietary calibration protocols tied to European OEM platforms. Denso Corporation specializes in temperature and pressure sensor replacements for hybrid powertrains across Asian markets.
The automotive electronics sensor aftermarket comprises replacement, repair, and recalibration of vehicle-mounted sensing devices that detect physical parameters including proximity, optical flow, thermal variation, and acoustic reflection, typically operating across temperature ranges from minus forty to one hundred fifty degrees Celsius and requiring ISO 26262 functional safety compliance for collision-critical applications. These components enable continued operation of advanced driver assistance systems, emission control feedback loops, and powertrain management in vehicles beyond original warranty periods. Smart sensors command margin premiums due to embedded signal processing and self-diagnostic capabilities that reduce installation errors. Collision avoidance applications generate the highest replacement frequency as front-facing radar and camera clusters sustain road debris damage. Repair shops represent the fastest-growing channel as independent technicians invest in OEM-grade calibration equipment.
The US NHTSA mandates automatic emergency braking on new vehicles, creating downstream replacement demand for radar and camera modules in the installed base. EPA emission standards enforce oxygen sensor replacement intervals that sustain demand for exhaust monitoring hardware. Japan's METI promotes connected vehicle infrastructure standards that require interoperable sensor protocols. Stakeholders must monitor how software-defined vehicle architectures shift warranty liability between OEMs and independent repair networks.
Market Dynamics
Software-defined vehicle architectures are fragmenting warranty liability between OEMs and independent repair networks, forcing aftermarket providers to recalibrate business models around recurring sensor alignment services rather than discrete hardware sales.
Growth Catalysts
- Fleet operator replacement cycles:Commercial vehicle mandates across multiple jurisdictions accelerate turnover of collision-avoidance sensors damaged by road debris and harsh operating conditions.
- EPA emission enforcement:Oxygen sensor replacement intervals mandated under federal standards sustain predictable demand for exhaust monitoring hardware in aging vehicle populations.
- Lidar fusion architectures:Multi-sensor redundancy requirements in next-generation ADAS platforms multiply calibration touchpoints per vehicle service event.
Market Restraints
- Semiconductor input volatility:MEMS foundry capacity constraints in Taiwan and South Korea create lead time unpredictability for pressure and inertial sensor modules.
- Proprietary calibration protocols:OEM-specific alignment software locks create technical barriers for independent repair shops lacking licensed diagnostic equipment.
- Inductive charging substitution:Wireless power transfer systems reduce physical connector wear, compressing replacement demand for traditional position sensors in charging infrastructure.
Strategic Opportunities
- Subscription-linked recalibration:Over-the-air diagnostic platforms enable recurring revenue capture from ADAS sensor alignment tied to vehicle software updates.
- India BIS standardization:Mandatory certification for automotive sensors creates first-mover advantage for aftermarket providers achieving compliance ahead of enforcement deadlines.
- Thermal sensor convergence:Battery management and cabin climate control applications are merging demand profiles for precision temperature sensing in electric powertrains.
Industry Challenges
- ISO 26262 functional safety certification:Collision-critical sensor categories require specialized audit timelines that delay product launches by 12-18 months.
- Legacy CAN bus integration:Mixed-protocol vehicle fleets complicate backward compatibility for smart sensors with embedded signal processing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electronics Sensor Aftermarket Market |
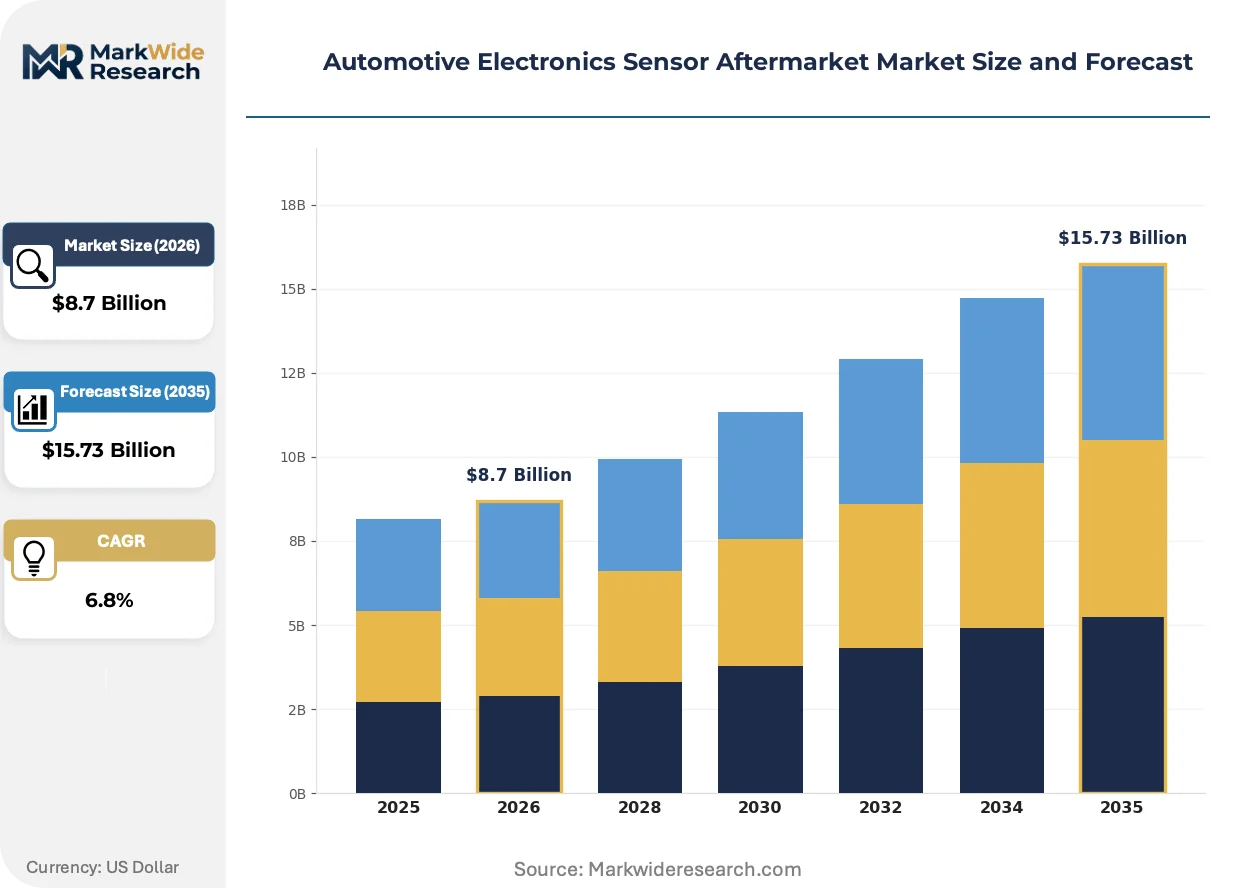
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radars, Cameras, Lidar, Ultrasonic Sensors End User: OEMs, Aftermarket Retailers, Fleet Operators, Repair Shops Technology: Active Sensors, Passive Sensors, Smart Sensors, Analog Sensors Application: Collision Avoidance, Parking Assistance, Lane Keeping, Traffic Monitoring |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, NXP Semiconductors, STMicroelectronics, Infineon Technologies AG, Sensata Technologies, BorgWarner Inc., Standard Motor Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electronics Sensor Aftermarket Market Strategic Shifts
Sensor intelligence migration from centralized ECUs to edge-processing nodes is redistributing diagnostic accountability across the aftermarket value chain. This shift demands new technical capabilities from repair networks while opening service revenue streams.
Solid-state lidar modules are absorbing photonic integration functions previously handled by discrete components. Tier 1 suppliers are adopting these devices for next-generation highway pilot systems. The technology is absorbing margin from mechanical scanning alternatives while compressing recalibration complexity into single-unit replacement protocols.
Japan's METI connected vehicle infrastructure standards are mandating interoperable sensor data protocols across OEM platforms. This regulatory push fragments proprietary diagnostic tool advantages held by manufacturer-captive service networks. European aftermarket providers are responding by certifying alignment equipment to multiple protocol specifications simultaneously.
Independent repair shops are consolidating procurement through cooperative buying groups to access OEM-grade calibration equipment. This channel formation displaces traditional parts distributor relationships in high-ADAS vehicle segments. Germany's KBA type-approval requirements for diagnostic tools accelerate this consolidation by raising capital barriers for standalone operators.
Automotive Electronics Sensor Aftermarket Market Segmentation
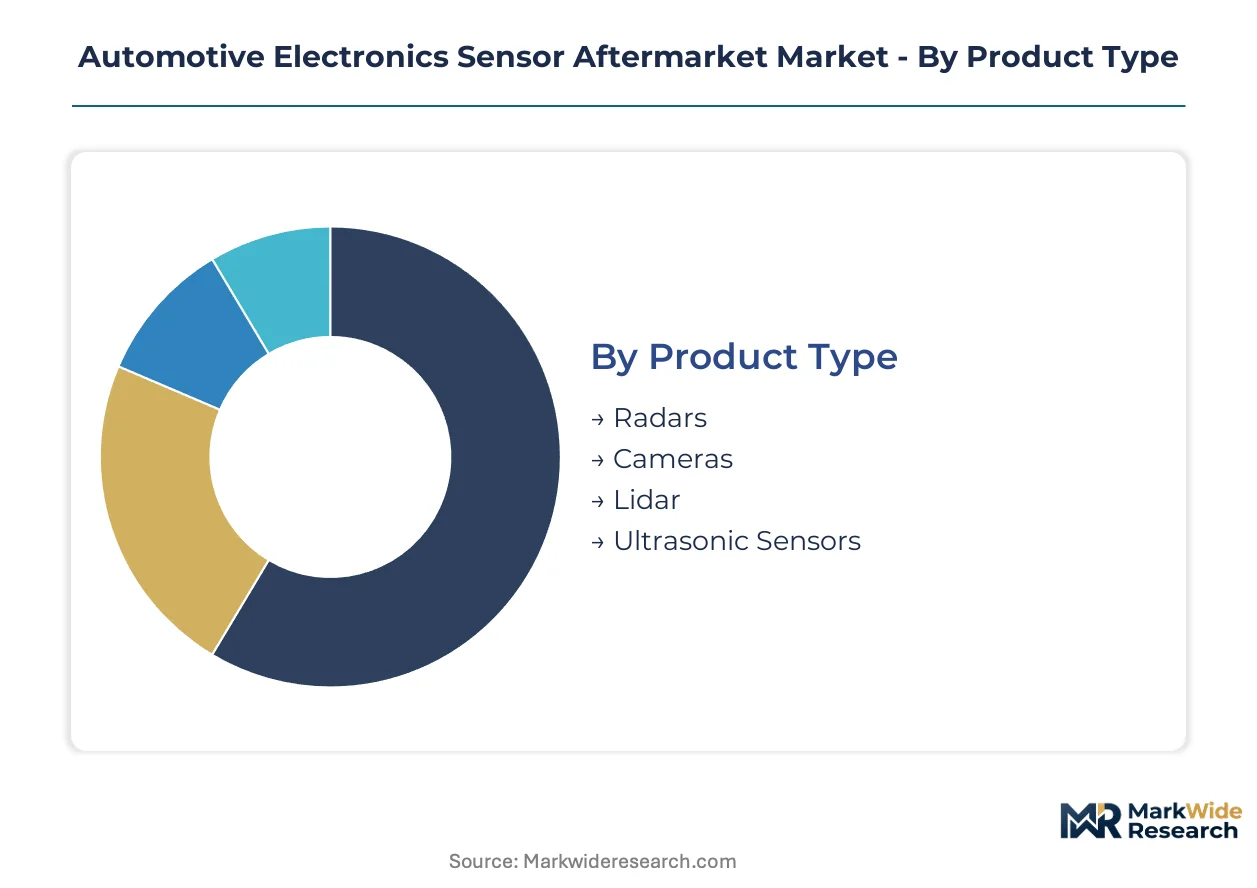
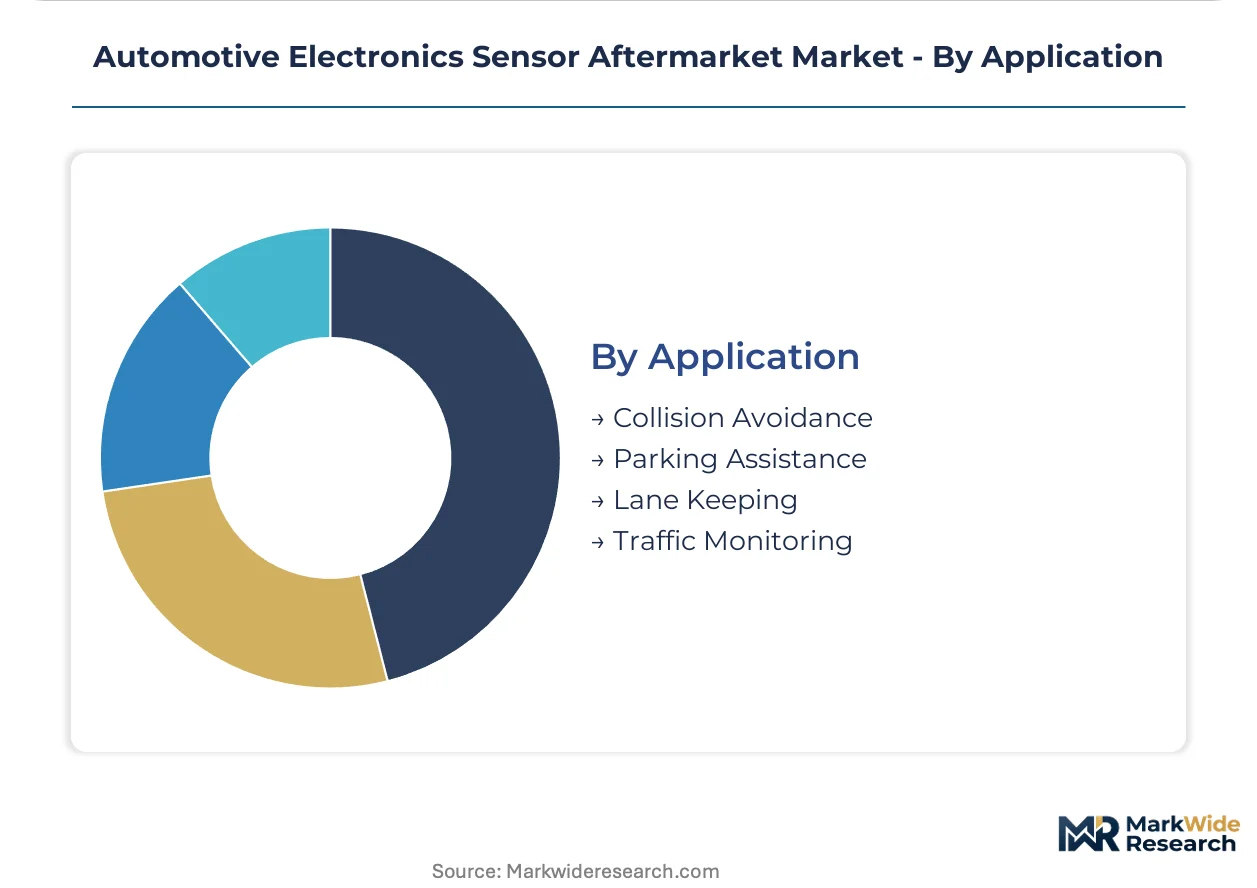
Sensor replacement demand fragments across multiple technical and commercial dimensions. Each segmentation layer reveals distinct margin profiles and capital requirements that aftermarket providers must navigate.
Product Type:
Radar and camera modules demand the heaviest upfront calibration equipment investment, while ultrasonic and lidar segments present diverging technical barriers to entry.
- Radars:Millimeter-wave units operating at 77 GHz for adaptive cruise control and automatic emergency braking. Front-facing radar clusters sustain the highest replacement frequency from road debris damage in Germany and the United States where NHTSA mandates drive collision-avoidance adoption.
- Cameras:CMOS-based optical modules with embedded image signal processors for lane detection and object classification. Multi-camera surround-view systems in premium vehicle segments multiply replacement touchpoints per incident.
- Lidar:Solid-state photonic integration replacing mechanical scanning architectures.
- Ultrasonic Sensors:Short-range acoustic proximity detection for parking assistance.
Radars absorb the bulk of installed capacity; lidar is expanding most quickly.
End User:
Procurement patterns diverge sharply between manufacturer-captive networks and independent service channels.
- OEMs:Authorized dealer networks performing warranty-period replacements with proprietary diagnostic protocols.
- Aftermarket Retailers:Parts distributors serving DIY installers and small independent garages.
- Fleet Operators:Commercial vehicle mandates across multiple jurisdictions accelerate turnover of collision-avoidance sensors damaged by harsh operating conditions and high-mileage duty cycles.
- Repair Shops:Independent technicians investing in OEM-grade calibration equipment to capture ADAS service revenue from aging vehicle populations.
Repair shops are gaining share fastest; OEMs retain warranty-period lock-in.
Technology:
Signal processing location determines aftermarket service complexity and margin capture potential.
- Active Sensors:Self-emitting detection systems including radar and lidar with onboard signal generation.
- Passive Sensors:Reception-only devices such as infrared and ambient light detectors.
- Smart Sensors:Edge-processing units with embedded diagnostics and self-calibration capabilities commanding margin premiums due to reduced installation error rates.
- Analog Sensors:Raw signal output devices requiring external ECU processing.
Smart sensors command the steepest price tiers; analog sensors face displacement pressure.
Application:
Functional safety criticality drives replacement urgency and regulatory enforcement intensity.
- Collision Avoidance:Front-facing radar and camera fusion for automatic emergency braking. EPA emission standards and NHTSA mandates in the United States create predictable replacement demand from regulatory enforcement.
- Parking Assistance:Ultrasonic and camera-based proximity guidance for low-speed maneuvering.
- Lane Keeping:Optical flow analysis for lateral position correction.
- Traffic Monitoring:Vehicle-to-infrastructure communication sensors supporting connected vehicle protocols mandated by Japan's METI standards.
Collision avoidance absorbs the bulk of replacement volume; traffic monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures diagnostic calibration equipment for export while the United States consumes the highest absolute volume of replacement sensors. Japan concentrates precision component fabrication for Asian supply chains.
United States
NHTSA automatic emergency braking mandates sustain replacement demand for radar and camera modules across aging vehicle fleets. EPA emission enforcement drives predictable oxygen sensor turnover intervals. Michigan's automotive corridor hosts independent repair shop consolidation as technicians acquire OEM-grade alignment equipment.
Germany
KBA type-approval requirements for diagnostic tools raise capital barriers and accelerate cooperative buying group formation among repair shops. EU Green Deal vehicle safety standards expand collision-avoidance sensor mandates. Stuttgart's Tier 1 supplier cluster anchors proprietary calibration protocol development for European OEM platforms.
Japan
METI connected vehicle infrastructure standards mandate interoperable sensor data protocols across manufacturer platforms. Aging vehicle populations in Tokyo-Osaka corridors generate sustained replacement demand for hybrid powertrain sensors. Nagoya's Chubu region concentrates temperature and pressure sensor fabrication for Asian aftermarket distribution.
China
MIIT intelligent vehicle regulations accelerate ADAS sensor penetration in domestic vehicle production. GB standards for automotive electronics create compliance thresholds for aftermarket component certification. Yangtze River Delta manufacturing clusters absorb MEMS foundry capacity for pressure and inertial sensor modules.
India
BIS mandatory certification for automotive sensors creates first-mover positioning for aftermarket providers achieving compliance ahead of enforcement deadlines. Commercial vehicle fleet expansion drives collision-avoidance sensor replacement cycles. Tamil Nadu's automotive belt hosts independent repair network formation as ADAS penetration deepens in premium vehicle segments.
Automotive Electronics Sensor Aftermarket Market Competitive Environment
Top-tier vendors anchor proprietary calibration protocol development, while mid-scale specialists compete on regional certification speed and cooperative equipment procurement. The structure concentrates around diagnostic equipment networks, precision component fabricators, and sensor module integrators. Strategic archetypes include full-system integrators with captive service networks, component specialists with MEMS fabrication depth, and regional distributors with repair shop channel control. Dominant competitive moves encompass diagnostic equipment leasing programs and multi-protocol calibration certification to neutralize OEM software lock-in.
Among European-anchored system integrators, Robert Bosch GmbH and Continental AG exemplify the full-service archetype through diagnostic network control and proprietary protocol alignment. Denso Corporation occupies a specialist position within Asian temperature and pressure sensor fabrication for hybrid powertrain applications.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies AG |
| Sensata Technologies |
| BorgWarner Inc. |
| Standard Motor Products |
| Others |
Value Chain & Pricing Dynamics
MEMS foundry engineers concentrated in Taiwan and South Korea command wage premiums that widen spreads between premium-tier smart sensors and economy-grade analog alternatives, compressing mid-market positioning as labor-cost differentials transmit through module pricing.
Pricing Analysis
Margin tightening in standard-tier sensor modules reflects MEMS foundry capacity constraints and semiconductor input volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified collision-critical units from basic exhaust monitoring hardware. Price differentiation hinges on functional safety certification grade and embedded signal processing capability. Fleet operators exhibit highest price sensitivity due to volume procurement and replacement cycle predictability, while OEM-captive dealer networks absorb premium-tier pricing for warranty-period installations.
Supply Chain Analysis
ISO 26262 functional safety certification gates supplier entry, stretching audit timelines and concentrating qualified production in Germany, Japan, and Taiwan. Raw material dependencies include silicon wafers, rare-earth magnetic components for radar modules, and specialized optical substrates for lidar photonic integration. Single-source vulnerability in Taiwan MEMS foundry capacity exposes lead time unpredictability for pressure and inertial sensors. Distribution runs through cooperative buying groups consolidating independent repair shop procurement alongside traditional parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where proprietary calibration protocol control and diagnostic equipment capital requirements force weaker independent operators into cooperative structures or exit.
For Market Incumbents:Acquire diagnostic equipment networks to cement recurring revenue capture from ADAS sensor recalibration services. Lock in proprietary calibration protocol licensing with European OEM platforms before METI-mandated interoperability standards fragment diagnostic tool advantages. Solid-state lidar substitution for mechanical scanning architectures threatens incumbent radar module positioning, requiring R&D pivot toward photonic integration capabilities.
For New Entrants and Emerging Players:Independent repair shops lacking OEM-grade calibration equipment represent the most penetrable buyer archetype in Germany and the United States. White-space exists in India BIS certification achievement ahead of enforcement deadlines and thermal sensor convergence for battery management applications. Go-to-market through cooperative buying group partnerships bypasses traditional distributor gatekeeping in high-ADAS vehicle segments.
For Investors and Strategic Acquirers:Re-rating potential sits with diagnostic equipment specialists given software-defined vehicle architectures multiplying calibration touchpoints per service event. Long-term viability favors providers with captive protocol licensing and recurring revenue streams over discrete hardware merchants. Watch NHTSA mandate expansion beyond automatic emergency braking as inflection indicator for collision-avoidance sensor replacement volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Equipment Network Acquisition | Captures recurring ADAS recalibration revenue from fleet operators and independent shops. |
| Multi-Protocol Calibration Certification | Neutralizes OEM software lock-in as Japan's METI mandates interoperable sensor data standards. |
| Solid-State Lidar Module Development | Absorbs margin from mechanical scanning alternatives while compressing recalibration complexity. |
| Cooperative Buying Group Formation | Consolidates independent repair shop procurement to access OEM-grade alignment equipment. |
| India BIS Compliance Investment | Creates first-mover positioning ahead of mandatory automotive sensor certification enforcement. |
Study Parameters
Multi-period observation of sensor replacement frequency, calibration service pricing, and fleet operator procurement patterns anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, dealership service operations, and independent repair shop owners. Secondary validation drew from NHTSA regulatory filings, EPA emission standard enforcement data, vehicle production databases, and IHS Markit registration statistics. Bottom-up sensor unit demand estimates triangulated against top-down aftermarket value projections.
Segment-weighting across product type, end user channel, technology tier, and application criticality shaped volume and value outputs over the projection horizon. CAGRs derived from fitted growth curves applied to replacement cycle modeling, ADAS penetration trajectories, and regulatory mandate implementation schedules. Industry-specific inputs included software-defined vehicle architecture adoption curves and MEMS foundry capacity utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization, OEM warranty liability fragmentation, and connected vehicle protocol standardization velocity. A model refresh is warranted upon material change in NHTSA mandate scope or Taiwan foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market