
 Automotive Cups and Glass Holder Market | 2026-2036
Automotive Cups and Glass Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cups and Glass Holder Market Outlook
Market Context
OEM supply contracts is rewriting how tier-one suppliers secure long-term holder programs across vehicle platforms. Magna International leverages its seating and interior integration capabilities to bundle cup holder modules with center console assemblies. Faurecia SA anchors European production through dedicated plastics manufacturing plants in France and Poland. Toyota Boshoku Corporation dominates Asia-Pacific sourcing by supplying integrated holder systems to Toyota Motor and affiliated OEMs.
Technical Definition and Segment Structure
Automotive cups and glass holders are interior cabin components engineered to secure beverage containers during vehicle motion, typically molded from ABS, polypropylene, or thermoplastic elastomers with spring-loaded retention mechanisms and anti-vibration damping elements. These devices serve the dual commercial purpose of reducing driver distraction and supporting premium interior differentiation strategies. Built-in holders integrated into center consoles capture the largest volume share, while composite material variants command premium positioning due to weight reduction credentials and tactile surface quality. SUVs generate outsized demand relative to their production share, as larger cabin architectures accommodate multiple holder positions and oversized container formats.
Regulatory Environment and Outlook
NHTSA guidelines in the United States and EU General Safety Regulation provisions shape holder stability requirements and placement restrictions to minimize driver distraction. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces cabin ergonomics standards that influence holder positioning within reach zones. Stakeholders must monitor evolving UN ECE vehicle interior safety protocols and decide whether to front-load compliance investments or pursue regional specification variants.
Market Dynamics
OEM consolidation around integrated center console modules is compressing standalone holder procurement, forcing suppliers to bundle retention systems with larger interior assemblies or exit direct sourcing relationships entirely.
Growth Catalysts
- Full-Size SUV Production Concentration:American automakers in Michigan and Texas are expanding light-truck platforms that accommodate multiple oversized holder positions, creating dedicated tooling demand for tier-one interior suppliers.
- NHTSA Distraction-Reduction Guidelines:Federal mandates for stable beverage retention within driver reach zones are mandating upgraded spring-loaded mechanisms and anti-spill damping systems across all new vehicle certifications.
- Lightweight Composite Adoption:Carbon-fiber-reinforced polypropylene compounds are displacing conventional ABS in premium segments, satisfying OEM weight-reduction targets while improving tactile surface quality.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and thermoplastic elastomer prices fluctuate with crude oil indices, compressing margin predictability for injection-molding specialists dependent on spot-market resin purchasing.
- Single-Source Tooling Concentration:Precision mold fabrication for complex retention mechanisms concentrates in southern Germany and Aichi Prefecture, creating geographic vulnerability to logistics disruptions or trade friction.
- Electronics Integration Complexity:Heated and cooled holder variants require thermal management subsystems that exceed traditional plastics suppliers' electrical engineering capabilities, raising barriers to premium segment participation.
Strategic Opportunities
- India Domestic Production Expansion:Maruti Suzuki and Hyundai Motor India are localizing center console manufacturing under the country's PLI scheme for auto components, opening qualification pathways for holder system suppliers.
- Aftermarket Retrofit Channels:E-commerce platforms and specialty retailers are creating direct-to-consumer distribution for universal-fit holder accessories, bypassing traditional tier-two supplier relationships.
- EU Circular Economy Mandates:The EU Green Deal's recycled content requirements for automotive plastics are incentivizing closed-loop polypropylene recovery systems that qualify suppliers for preferred sourcing status.
Industry Challenges
- Thermal-Mechanical Simulation Expertise Gap:Designing holders for extreme-temperature cycling requires finite element analysis capabilities that legacy toolmakers lack, forcing partnerships with specialized CAE consultancies.
- Homologation Timeline Compression:UN ECE interior safety protocol updates are accelerating certification deadlines, requiring parallel validation tracks that strain smaller suppliers' testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cups and Glass Holder Market |
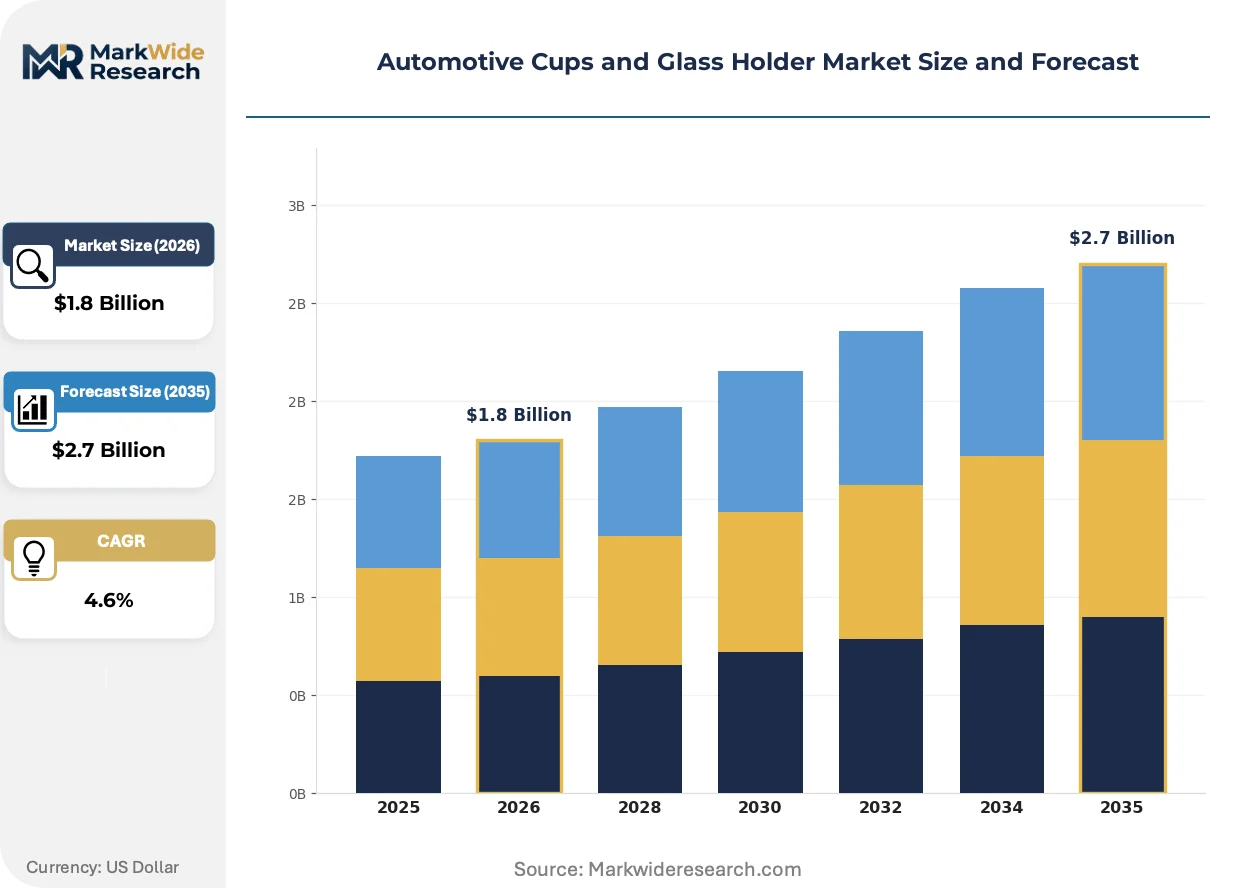
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Built-in Holders, Removable Holders, Adjustable Holders, Dual Holders Material: Plastic, Metal, Wood, Composite Vehicle Type: SUVs, Sedans, Hatchbacks, Trucks Installation Method: OEM Installation, Aftermarket Installation, Plug-and-Play, Integrated Systems |
| Companies Covered | Magna International Inc., Faurecia SA, Toyota Boshoku Corporation, Continental AG, Lear Corporation, Hyundai Mobis Co., Ltd., Denso Corporation, Gentex Corporation, Nifco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cups and Glass Holder Market Strategic Shifts
Active grille shutter integration and thermal management convergence are reshaping how cabin interior components interact with vehicle energy systems, creating new functional requirements for traditional convenience features.
Shape-memory alloy retention clips are migrating from aerospace applications into automotive cup holder mechanisms, providing adaptive clamping force that adjusts to container diameter without manual adjustment. Tier-one seating suppliers in Stuttgart and Toyota City are piloting these actuators for 2027 platform launches. This technology is migrating from premium flagship vehicles toward mass-market electric SUVs as OEMs seek differentiation through silent, motorized adjustment systems.
REACH substance restrictions on certain phthalate plasticizers are compelling reformulation of thermoplastic elastomer grips used in luxury holder liners, with ECHA compliance deadlines forcing compounders to validate alternative shore-hardness specifications by Q3 2025. European interior suppliers with captive compounding operations are capturing specification authority, while non-integrated competitors face raw-material qualification delays.
Fleet procurement managers at rental and ride-hailing operators are consolidating interior component specifications across vehicle classes, demanding standardized holder dimensions that accommodate standardized beverage formats from quick-service restaurant supply chains. This specification compression is eliminating custom holder variants for fleet-dedicated trims, most visible in Arizona and Florida where national rental operators maintain largest vehicle concentrations.
Automotive Cups and Glass Holder Market Segmentation
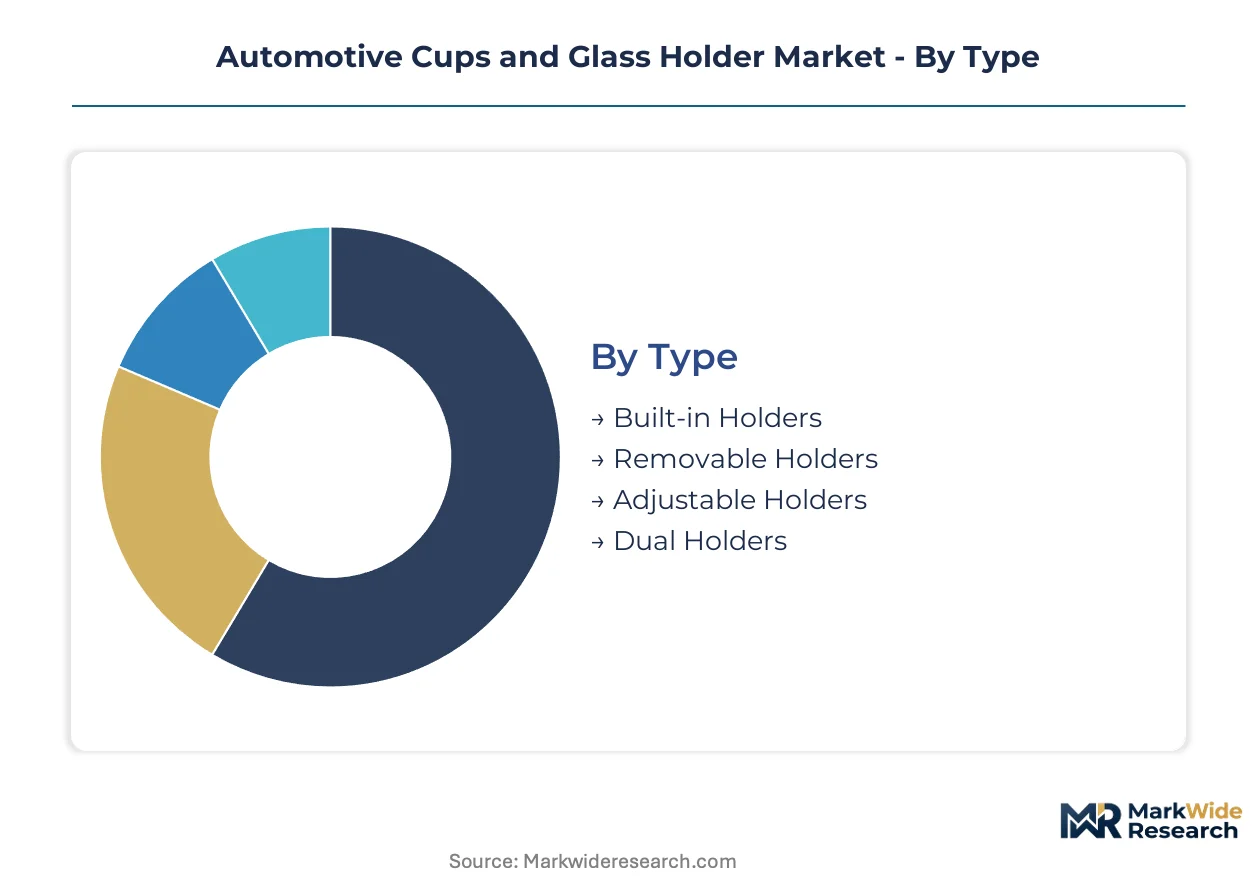
Holder segmentation dictates aftermarket service intensity, with built-in variants requiring center console disassembly for replacement while plug-and-play formats enable rapid field service. Material selection drives warranty claim frequency, as thermal cycling degrades certain compounds faster than others.
Type:
After-sales service intensity varies sharply across holder types, with integrated variants demanding specialized tooling and console removal procedures that inflate dealer labor charges.
- Built-in Holders:Molded permanently into center console assemblies during injection-molding cycles, these units utilize ABS or polypropylene substrates with integrated spring retention. Demand clusters in full-size SUVs from Michigan and Texas assembly plants, where multiple holder positions accommodate oversized beverage formats. Service replacement requires complete console removal, driving extended warranty cost concentration.
- Removable Holders:Designed for snap-fit attachment to air vents or seat rails, these accessories employ universal mounting brackets compatible with standardized rail dimensions. Growth concentrates in Arizona and Florida fleet operations, where rental operators specify interchangeable units for rapid cleaning and damage replacement. Lower service intensity supports aftermarket margin structures.
- Adjustable Holders:Feature sliding diameter mechanisms accommodating containers from standard cans to oversized tumblers.
- Dual Holders:Pair adjacent retention positions within single molded assemblies for front-row passenger convenience.
By volume, built-in holders lead. By growth pace, removable formats are expanding most quickly.
Material:
Cost tier stratification separates premium cabin finishes from mass-market utility, with composite and wood variants commanding specification authority in luxury segments.
- Plastic:Polypropylene and ABS dominate injection-molding throughput, offering cost efficiency at scale and color-matching flexibility for interior harmonization. Specifications from Toyota City and Stuttgart anchor global procurement volumes, with compounders qualifying shore-hardness ratings for tactile consistency. NHTSA distraction guidelines favor proven material stability under thermal cycling.
- Composite:Carbon-fiber-reinforced polypropylene compounds satisfy OEM weight-reduction targets while delivering premium surface aesthetics. Adoption concentrates in German premium SUVs, where gram-scale savings aggregate across interior component counts. REACH substance restrictions are accelerating reformulation timelines for European qualification.
- Metal:Aluminum and stainless-steel variants serve luxury applications requiring cold-touch thermal properties.
- Wood:Veneer-wrapped substrates appear in flagship sedan center consoles for tactile differentiation.
By volume, plastic leads. By specification climb, composites are gaining share fastest.
Vehicle Type:
Application architecture determines holder count per cabin, with larger platforms accommodating multiple retention positions across rows.
- SUVs:Three-row architectures generate outsized holder demand relative to production share, with center consoles, rear-seat armrests, and third-row side panels each integrating retention systems. American light-truck platforms from Michigan and Texas specify up to eight positions per vehicle. NHTSA reach-zone guidelines shape placement geometry for driver-accessible units.
- Sedans:Traditional three-box designs concentrate holders in front-center consoles and rear armrest drop-downs.
- Hatchbacks:Compact cabin dimensions limit holder count to two front positions in most configurations.
- Trucks:Commercial and personal-use pickups integrate oversized holders for insulated beverage containers, with Texas production volumes driving tooling specialization.
By volume, SUVs lead. By growth pace, trucks are climbing the fastest.
Installation Method:
Customer type separates captive OEM supply from independent aftermarket channels, with procurement patterns diverging on specification control and price sensitivity.
- OEM Installation:Tier-one suppliers bundle holder modules with center console assemblies under long-term platform contracts, with Faurecia in France and Poland and Magna in North America anchoring integrated supply. Toyota Boshoku captures Asia-Pacific sourcing through affiliated OEM relationships. Homologation timelines compress qualification windows for new entrants.
- Aftermarket Installation:Specialty retailers and e-commerce platforms distribute universal-fit accessories direct to consumers, bypassing traditional tier-two relationships. Arizona and Florida fleet operators drive standardization demand across vehicle classes.
- Plug-and-Play:Tool-free attachment systems enable consumer installation without professional service intervention.
- Integrated Systems:Holder functions merge with wireless charging pads and thermal management subsystems in premium console architectures.
By volume, OEM installation leads. By channel expansion, aftermarket formats are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European supply chains for interior component imports, while the Port of Long Beach handles Pacific Rim resin shipments feeding North American injection-molding operations.
United States
Full-size SUV and light-truck production in Michigan and Texas generates concentrated demand for multi-position holder systems. NHTSA distraction-reduction guidelines mandate stable retention mechanisms within driver reach zones. Detroit-area tier-one suppliers bundle holder modules with center console assemblies under long-term platform contracts.
Germany
Premium SUV architectures from Stuttgart and Munich drive specification authority for carbon-fiber-reinforced composite holders. REACH substance restrictions on phthalate plasticizers compel thermoplastic elastomer reformulation by Q3 2025. Southern German precision mold fabricators concentrate tooling capacity for complex retention mechanisms.
Japan
Ministry of Land, Infrastructure, Transport and Tourism cabin ergonomics standards dictate holder positioning within defined reach zones. Toyota City and Nagoya anchor Asia-Pacific sourcing through affiliated OEM supply relationships. Aichi Prefecture mold specialists face geographic vulnerability to logistics disruptions.
India
Maruti Suzuki and Hyundai Motor India localize center console manufacturing under the PLI scheme for auto components. BIS certification requirements shape material qualification timelines for imported compounds. Tamil Nadu and Gujarat assembly plants open qualification pathways for integrated holder system suppliers.
China
Domestic EV platform launches accelerate demand for premium interior differentiation features. MIIT vehicle safety protocols influence holder stability testing requirements. Yangtze River Delta injection-molding clusters compete on scale for polypropylene component supply.
Automotive Cups and Glass Holder Market Competitive Environment
On the supply side, the industry is consolidating around integrated center console modules, compressing standalone holder procurement and forcing suppliers to bundle retention systems with larger interior assemblies. Three archetypes dominate: tier-one seating and interior integrators, captive OEM-affiliated suppliers, and specialized plastics compounders. Competitive moves center on backward integration into resin compounding and strategic partnerships with thermal management subsystem specialists.
Within the tier-one integrator tier, Magna International and Faurecia SA exemplify platform-scale supply archetypes, while Toyota Boshoku Corporation occupies a position as the captive-affiliated model. These three represent contrasting geographic anchors—North American, European, and Asia-Pacific respectively—and illustrate how regional production gravity shapes competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Magna International Inc. |
| Faurecia SA |
| Toyota Boshoku Corporation |
| Continental AG |
| Lear Corporation |
| Hyundai Mobis Co., Ltd. |
| Denso Corporation |
| Gentex Corporation |
| Nifco Inc. |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility in polypropylene and ABS resin markets compresses margin predictability for injection-molding specialists and simultaneously determines both pricing tier spreads and supply chain shape. This dual pressure forces compounders to index contract pricing to crude oil benchmarks while concentrating procurement relationships with resin suppliers in Texas and Louisiana.
Pricing Analysis
Volume-discount tiering structures dominate OEM procurement, with platform-scale contracts from Michigan and Texas assembly plants commanding standard-tier pricing while German premium SUV programs absorb premium-tier carbon-fiber-reinforced composite premiums. Price differentiation stems from material grade certification and after-sales service bundling. Cost compression in mass-market plastic variants is intensifying because spot-market resin purchasing exposes molders to crude oil index swings. Fleet operators in Arizona and Florida exhibit highest price sensitivity, while captive OEM-affiliated suppliers face lowest negotiation leverage.
Supply Chain Analysis
Contract-manufacturing concentration rests with Magna International in Ontario, Faurecia SA in France and Poland, and Toyota Boshoku in Aichi Prefecture, each anchoring regional capacity for integrated center console assemblies. Geographic supply concentration centers on Germany, Japan, and the United States for precision mold fabrication. Raw material dependencies draw from Saudi Arabian and Qatari polypropylene feedstock, Texas-sourced ABS resins, and Japanese carbon-fiber precursors. Single-source tooling vulnerability in southern Germany and Aichi Prefecture creates geographic concentration risk. Distribution runs through tier-one supplier direct-ship programs to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shape-memory alloy retention mechanisms and thermal management subsystem integration constitute a technological inflection that redefines competitive boundaries across the analysis window.
For Market Incumbents: Pre-empt displacement by electronics-integrated holder variants through backward integration into thermal management capabilities or strategic partnerships with HVAC subsystem specialists. Defend against standalone holder procurement compression by bundling retention systems with center console assemblies under long-term platform contracts. Lock in resin compounding capacity in Texas and Louisiana to secure margin predictability against petrochemical volatility. For New Entrants and Emerging Players: Build out aftermarket retrofit channels targeting Arizona and Florida fleet operators with standardized holder dimensions for rapid field replacement. The most penetrable white space sits in India domestic production expansion under PLI scheme localization requirements. Pursue direct-to-consumer e-commerce distribution to bypass entrenched tier-two supplier relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors tier-one interior integrators with captive OEM relationships and backward resin compounding capabilities. Long-term viability hinges on qualification for heated-cooled holder thermal management subsystems. Target acquisition archetypes include specialized CAE consultancies with thermal-mechanical simulation expertise. Monitor UN ECE interior safety protocol updates as inflection indicators for compliance investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling costs for multi-position holder systems across SUV architectures from Michigan and Texas. |
| Backward Integration into Resin Compounding | Captures margin from polypropylene feedstock volatility while qualifying for EU Green Deal recycled content mandates. |
| Geographic Manufacturing Footprint | Localizes production in Tamil Nadu and Gujarat to capture Maruti Suzuki and Hyundai Motor India PLI scheme volumes. |
| Software-Defined Vehicle Investment | Enables motorized shape-memory alloy retention systems with silent diameter adjustment for premium differentiation. |
| Thermal Management Partnership | Accesses heated-cooled holder capabilities beyond traditional plastics suppliers' electrical engineering limitations. |
Study Parameters
The analysis maps built-in, removable, and adjustable holder types, each validated through tier-one supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA guideline filings, and UN ECE protocol documentation. Bottom-up triangulation across resin consumption volumes and top-down reconciliation against center console assembly shipments anchored market sizing.
The assumption-set framing held fixed NHTSA distraction-reduction guideline enforcement timelines and EU REACH substance restriction deadlines while varying crude oil index trajectories and EV platform launch cadences. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster throughout the forecast period. CAGRs derived from weighted average of historical injection-molding capacity expansion and projected SUV production mix shifts. Industry-specific inputs included spring-loaded mechanism adoption rates and carbon-fiber-reinforced polypropylene penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by electronics subsystem specialists would shift outcomes beyond modeled ranges. Quarterly review of resin price indices, UN ECE protocol revision timelines, and PLI scheme qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Flooring Market