
 Automotive Connectivity Market | 2026-2036
Automotive Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Connectivity Market Analysis
The EU Green Deal is pivoting automotive connectivity investment toward emissions monitoring and energy optimization platforms. BMW leverages its embedded telematics architecture to sustain competitive positioning in premium electric vehicle segments. Harman specializes in integrated infotainment and connectivity hardware that anchors its relationships with multiple OEM programs. Ford operates a proprietary connected fleet ecosystem that differentiates its commercial vehicle offerings from tier-1 alternatives.
Automotive connectivity denotes the integration of wireless communication modules, antenna systems, and software stacks that enable data exchange between vehicles, infrastructure, and cloud platforms, typically operating across sub-6 GHz and mmWave spectrum bands with latency requirements under 10 milliseconds for safety-critical V2X functions. 5G technology leads current infrastructure deployment due to its bandwidth capacity for over-the-air update payloads, while V2X represents the fastest-growing segment as municipalities and highway authorities mandate cooperative intelligent transport systems. Infotainment systems constitute the most mature product category with established margin pools, whereas telematics units capture expanding value as fleet operators demand real-time asset tracking and predictive maintenance analytics.
The European Telecommunications Standards Institute, the U.S. FCC, and China's MIIT each govern spectrum allocation and device certification for connected vehicle systems, with ETSI's C-V2X standards directly shaping OEM product roadmaps and market access timelines in Europe. The U.S. FCC's 5.9 GHz band reconfiguration is forcing hardware redesigns for domestic deployment. Stakeholders must monitor regulatory divergence between C-V2X and DSRC technology mandates as this fragmentation threatens interoperability and supplier scale economics.
Market Dynamics
The EU Green Deal's emissions mandates are compressing OEM timelines for V2X deployment, forcing simultaneous investment in telematics hardware and cloud analytics infrastructure to avoid regulatory penalties.
Growth Catalysts
- EU Green Deal mandates:Emissions monitoring requirements are accelerating fleet operator procurement of real-time energy optimization platforms across commercial vehicle segments.
- 5G infrastructure rollout:Bandwidth capacity for over-the-air update payloads is enabling predictive maintenance analytics that reduce unplanned downtime.
- German engineering clusters:Concentrated automotive R&D procurement in Stuttgart and Munich is pulling connectivity module demand from tier-1 suppliers.
Market Restraints
- Semiconductor input volatility:mmWave RF component shortages constrain antenna system production cycles and inflate bill-of-material costs.
- Spectrum fragmentation:Divergence between ETSI C-V2X and FCC 5.9 GHz reconfiguration forces redundant hardware designs that erode supplier scale economics.
- DSRC substitution threat:Legacy roadside communication infrastructure in North American municipalities delays C-V2X adoption timelines.
Strategic Opportunities
- Cooperative intelligent transport systems:Highway authority mandates for V2X interoperability are opening municipal procurement channels previously closed to automotive suppliers.
- Edge-to-cloud convergence:Integration of vehicle-side computing with centralized analytics platforms enables subscription-based software revenue models.
- Fleet operator channel expansion:Direct B2B platform sales bypass traditional OEM tiering and capture higher-margin service contracts.
Industry Challenges
- Embedded systems integration:Legacy vehicle architectures require extensive redesign to accommodate sub-10 millisecond latency requirements for safety-critical functions.
- Multi-standard certification:Parallel ETSI, FCC, and MIIT approval processes extend product launch timelines and inflate compliance overhead.
- Cross-functional talent scarcity:Shortage of engineers combining RF antenna design with automotive functional safety expertise constrains R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Connectivity Market |
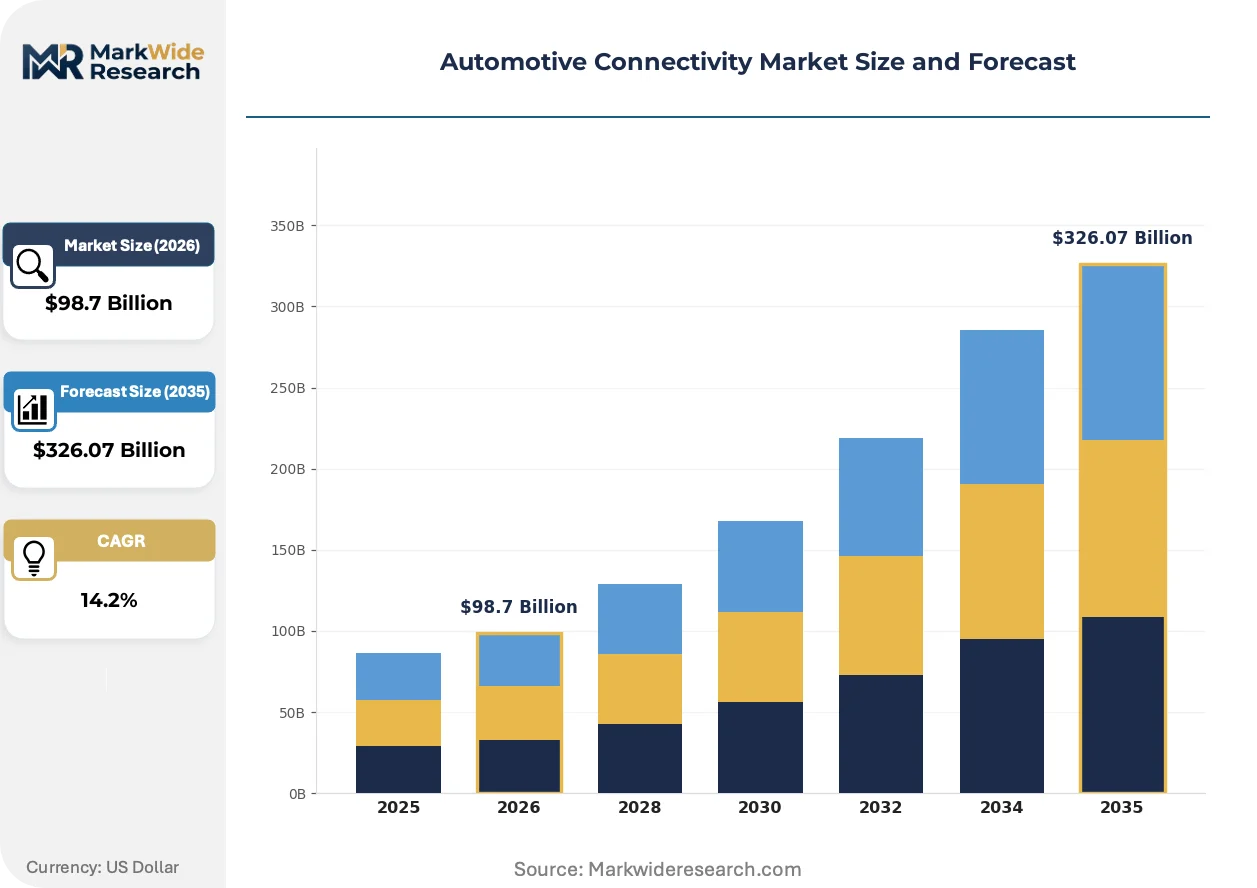
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $326.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, Wi-Fi, 5G, V2X Product Type: Infotainment Systems, Telematics Units, ADAS, Onboard Diagnostics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Application: Driver Assistance, Vehicle Tracking, Remote Diagnostics, Over-the-Air Updates |
| Companies Covered | Vodafone Group, Sibros, Verizon Connect, Telefonica, Ford, Harman, BMW, TomTom, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Connectivity Market Emerging Trajectories
V2X communication architectures are undergoing fundamental redesign as latency requirements tighten and spectrum allocation fragments across regulatory jurisdictions. Three forces are compressing competitive timelines.
Cellular vehicle-to-everything technology enables direct communication between vehicles, infrastructure, and vulnerable road users without network dependency. Municipalities in the Netherlands and Austria are deploying C-V2X roadside units ahead of 2026 mandates. This capability is converging with edge computing platforms to enable real-time hazard warnings that bypass cloud latency entirely.
The EU AI Act's risk classification framework is imposing documentation and transparency requirements on automated driving systems that rely on V2X inputs. OEMs must now maintain algorithmic audit trails for safety-critical connectivity functions. Premium electric vehicle programs face the steepest compliance burden as they integrate the most complex sensor fusion architectures.
Fleet operators are consolidating vendor relationships around platforms that combine telematics, predictive maintenance, and energy management in unified dashboards. This behavior is displacing point-solution procurement that characterized early connected vehicle adoption. Commercial vehicle lessors in Germany and France are driving this consolidation fastest, using scale to demand API standardization across mixed-brand fleets.
Automotive Connectivity Market Segmentation
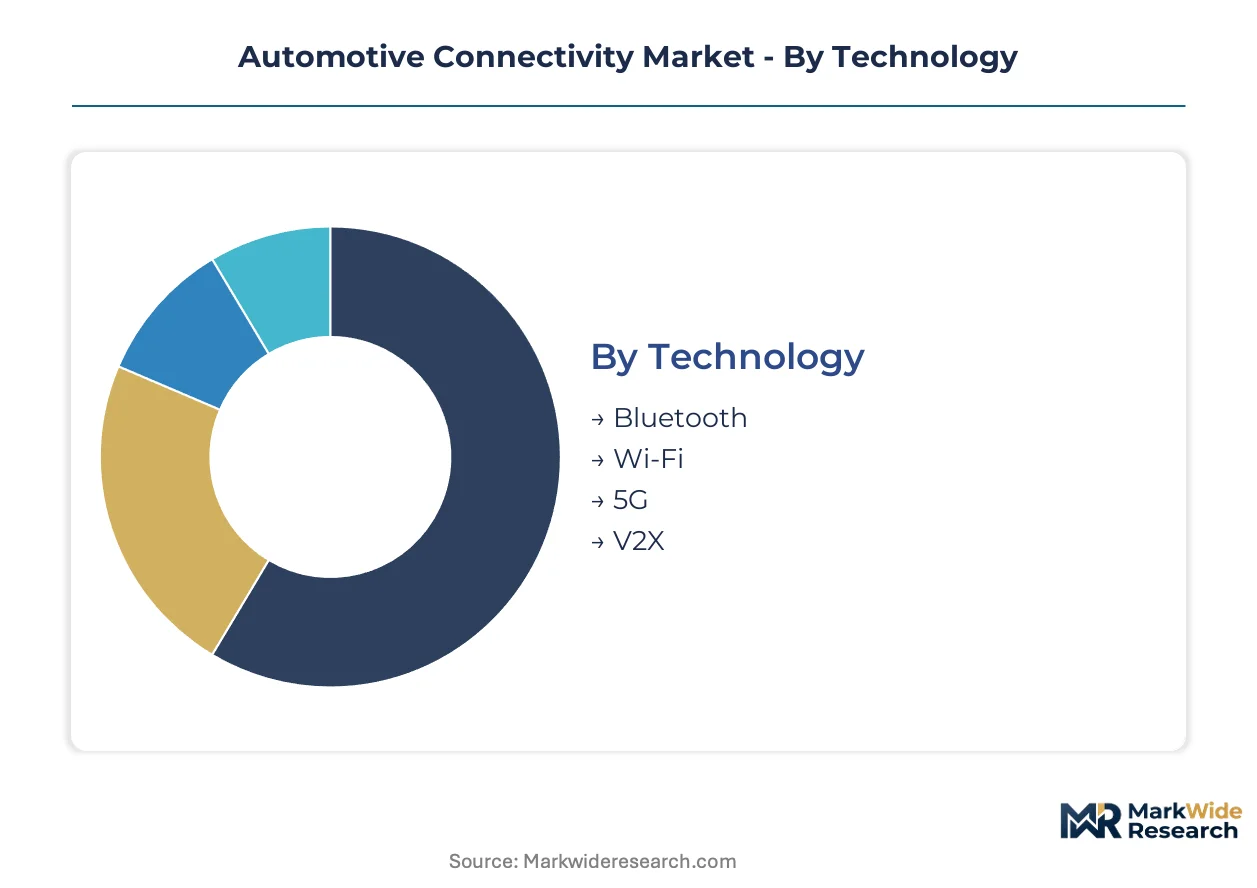
Technology architecture determines procurement patterns across automotive connectivity, with bandwidth requirements and latency thresholds separating premium from standard deployments. Product maturity varies sharply by segment, creating divergent margin structures and supplier consolidation pressures.
Technology:
Procurement budgets diverge based on whether buyers prioritize established interoperability or next-generation throughput capacity.
- 5G:Cellular modules operating across sub-6 GHz and mmWave bands deliver the bandwidth density required for over-the-air update payloads exceeding 1 gigabyte. German OEMs in Stuttgart and Munich are pulling 5G module demand fastest as they integrate predictive maintenance analytics into premium electric vehicle programs.
- V2X:Direct vehicle-to-everything communication enables sub-10 millisecond latency for safety-critical functions without network dependency. Netherlands and Austrian municipalities are deploying C-V2X roadside units ahead of regulatory mandates, opening municipal procurement channels previously closed to automotive suppliers.
- Bluetooth:Short-range wireless protocol dominates cabin device pairing and smartphone integration for entry-level vehicle segments.
- Wi-Fi:In-vehicle hotspot functionality serves passenger entertainment and dealer service bay diagnostics.
Volume sits with Bluetooth and Wi-Fi for near-term production; growth tilts toward 5G and V2X as latency requirements tighten.
Product Type:
Margin concentration follows software content, with hardware-centric categories facing commoditization pressure.
- Telematics Units:Embedded cellular modules combine GPS positioning with CAN bus integration to transmit vehicle health data to cloud platforms. Fleet operators in Germany and France are consolidating procurement around unified telematics dashboards, displacing point-solution vendors.
- Infotainment Systems:Integrated display, audio, and connectivity hardware constitutes the most mature product category with established margin pools. Harman and similar tier-1 suppliers anchor OEM relationships through multi-program infotainment contracts.
- ADAS:Sensor fusion platforms require high-bandwidth connectivity for camera and radar data aggregation.
- Onboard Diagnostics:Regulatory-mandated emissions monitoring hardware is expanding under EU Green Deal compliance timelines.
Infotainment systems capture current revenue concentration; telematics units and ADAS are climbing the fastest as fleet digitization accelerates.
End User:
Channel power determines pricing leverage, with direct fleet relationships commanding superior terms against tiered supply structures.
- Fleet Operators:Commercial vehicle lessors demand API-standardized platforms spanning mixed-brand assets, bypassing traditional OEM tiering to capture higher-margin service contracts. B2B platform sales in Germany are consolidating vendor relationships fastest.
- OEMs:Vehicle manufacturers specify connectivity architecture at platform design stage, locking in multi-year module supply agreements. BMW leverages embedded telematics to sustain competitive positioning in premium electric segments.
- Tier-1 Suppliers:Integrated module manufacturers serve as procurement intermediaries between semiconductor vendors and vehicle programs.
- Aftermarket Providers:Retrofit connectivity solutions address legacy vehicle fleets outside OEM warranty coverage.
OEMs anchor procurement volume; fleet operators represent the steepest expansion trajectory as direct platform sales displace tiered distribution.
Application:
Functional criticality separates safety-mandated deployments from convenience-driven upgrades.
- Over-the-Air Updates:Remote software distribution eliminates dealer visits for feature activation and security patching. 5G bandwidth capacity enables payload sizes that support full operating system refreshes.
- Remote Diagnostics:Real-time fault code transmission enables predictive maintenance analytics that reduce unplanned commercial vehicle downtime.
- Driver Assistance:V2X-dependent cooperative intelligent transport systems face regulatory fragmentation between ETSI C-V2X and FCC 5.9 GHz standards.
- Vehicle Tracking:GPS-based asset location serves insurance, theft recovery, and logistics optimization use cases.
Vehicle tracking holds installed base dominance; over-the-air updates and remote diagnostics are gaining share fastest as software-defined vehicle architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the highest connectivity module volumes while China scales manufacturing fastest. Production-consumption gaps widen as European OEMs source Asian semiconductor components. Regulatory divergence between ETSI, FCC, and MIIT standards fragments procurement patterns.
United States
Fleet operators in the Midwest and Southeast are consolidating telematics procurement around unified platforms. The FCC's 5.9 GHz band reconfiguration forces hardware redesigns for domestic V2X deployment. Detroit's automotive engineering clusters anchor tier-1 supplier relationships for embedded connectivity modules.
Germany
Commercial vehicle lessors demand API-standardized platforms spanning mixed-brand fleets. The EU Green Deal accelerates emissions monitoring hardware procurement across Baden-Württemberg and Bavaria. Stuttgart and Munich pull 5G module demand fastest as premium electric vehicle programs integrate predictive maintenance analytics.
China
Domestic OEMs scale C-V2X deployment ahead of municipal mandates in Yangtze River Delta megacities. MIIT governs spectrum allocation and device certification with GB standards shaping product roadmaps. Shenzhen and Shanghai concentrate module manufacturing and R&D investment for export markets.
Japan
METI drives cooperative intelligent transport system pilots in Kanto and Kansai corridors. Domestic OEMs prioritize sub-10 millisecond latency architectures for safety-critical functions. Nagoya's automotive supplier density supports integrated telematics and infotainment development.
Netherlands
Municipalities deploy C-V2X roadside units ahead of 2026 regulatory mandates. Eindhoven's engineering ecosystem anchors V2X interoperability testing and certification. Randstad logistics operators pilot real-time energy optimization platforms for commercial vehicle fleets.
Automotive Connectivity Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with embedded automotive relationships. Tier-1 suppliers and telecommunications operators fragment the mid-market while specialized connectivity platforms occupy niche positions. Strategic archetypes include integrated infotainment-hardware specialists, proprietary fleet-ecosystem operators, and embedded telematics architects. Dominant competitive moves center on multi-program OEM contracts and direct B2B platform sales that bypass traditional tiering.
Among diversified automotive suppliers, Harman and BMW occupy positions exemplifying the integrated hardware-software archetype, while Ford anchors the proprietary fleet-ecosystem tier. Vodafone Group represents the telecommunications operator segment leveraging cellular infrastructure for automotive data services. These entities illustrate how market position depends on whether players control end-user relationships, manufacturing scale, or network infrastructure assets.
| Leading Market Players |
|---|
| Vodafone Group |
| Sibros |
| Verizon Connect |
| Telefonica |
| Ford |
| Harman |
| BMW |
| TomTom |
| AT&T |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement consolidation in Germany and France anchors the dominant subscription-based SaaS pricing model, compressing margins for point-solution vendors while rewarding platform-scale providers with multi-year service contracts.
Pricing Analysis
Price erosion across standard connectivity modules traces to semiconductor input volatility and redundant hardware designs forced by spectrum fragmentation between ETSI C-V2X and FCC standards. Three-tier pricing structure across premium, standard, and economy levels separates safety-critical V2X systems from infotainment hardware and basic telematics units. Cost-down pressure on entry-level Bluetooth and Wi-Fi modules accelerates because automotive OEMs demand annual cost reductions for mature product categories. Fleet operators exhibit the highest price sensitivity, negotiating API-standardized platforms across mixed-brand assets, while premium electric vehicle programs show lowest sensitivity due to embedded software content differentiation.
Supply Chain Analysis
mmWave RF component supply rests on Taiwanese and South Korean specialty semiconductor foundries, with antenna system production concentrated in Shenzhen and Shanghai manufacturing clusters. Raw material dependencies span gallium nitride substrates, high-frequency laminates, and automotive-grade cellular baseband processors. Single-source vulnerability in mmWave RF front-end components constrains production cycles and inflates bill-of-material costs when foundry capacity tightens. Distribution runs through tier-1 module suppliers serving as procurement intermediaries between semiconductor vendors and OEM platform engineering teams, with direct B2B platform sales to fleet operators bypassing traditional tiering in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive connectivity sits in a technology-transition phase as 5G and C-V2X architectures displace legacy 4G telematics and DSRC roadside communication systems, compressing competitive timelines for hardware-software integration.
For Market Incumbents: Deepen embedded software content in telematics units to defend against margin compression from commoditized connectivity hardware. Secure multi-program OEM contracts for 5G module supply across premium electric vehicle platforms in Stuttgart and Munich engineering clusters. Invest in certification engineering resources to accelerate parallel ETSI, FCC, and MIIT approval processes and compress product launch timelines.
For New Entrants and Emerging Players: Launch via direct B2B platform sales to commercial vehicle lessors in Germany and France, bypassing tier-1 supplier intermediaries to capture higher-margin service contracts. Target municipal procurement channels for C-V2X roadside units in the Netherlands and Austria ahead of regulatory mandates. Build API-standardized dashboards that consolidate telematics, predictive maintenance, and energy management for mixed-brand fleet operators.
For Investors and Strategic Acquirers: The window for entry favors specialized connectivity platforms with embedded automotive relationships and software-defined vehicle integration capabilities. Long-term viability hinges on controlling end-user relationships rather than manufacturing scale alone. Watch the pace of EU Green Deal emissions monitoring hardware procurement across Baden-Württemberg and Bavaria as the inflection indicator for fleet digitization acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces redundant hardware designs for ETSI and FCC spectrum mandates, preserving supplier scale economics. |
| Software-Defined Vehicle Investment | Enables subscription-based revenue models through over-the-air update capabilities and predictive maintenance analytics. |
| Battery Supply Agreement | Secures energy optimization platform integration for premium electric vehicle programs in German engineering clusters. |
| Geographic Manufacturing Footprint | Localizes 5G module production in Shenzhen and Shanghai to serve Asian OEM scale requirements and export markets. |
| Charging Infrastructure Partnership | Opens municipal procurement channels for C-V2X roadside units through cooperative intelligent transport system pilots. |
Methodological Framework
Multi-period observation of vehicle production databases, IHS Markit registration data, and hyperscaler capex disclosures anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator logistics directors. Primary fieldwork combined with secondary validation from SEC filings, ETSI standards documentation, FCC rulemaking dockets, and MIIT GB standard publications. Bottom-up module shipment tracking and top-down automotive electronics spend analysis provided triangulation across data sources.
Segment-weighting across technology architecture, product type, end user channel, and application functional criticality shaped the analytical framework over the projection horizon. Vehicle class, propulsion architecture, and content per vehicle dimensions modeled demand variation across OEM tiers and regional production clusters. CAGRs derived from logistic diffusion curves for 5G and V2X adoption, calibrated against fleet operator procurement surveys and regulatory mandate timelines. Forecast inputs incorporated semiconductor supply constraints and spectrum allocation decisions across ETSI, FCC, and MIIT jurisdictions.
The model assumes a particular technology adoption path; alternative pathways for DSRC persistence in North American municipalities or accelerated C-V2X deployment in Yangtze River Delta megacities would alter the outlook. Forecasts reflect documented assumptions about 5G infrastructure rollout pace, EU Green Deal compliance timelines, and mmWave RF component supply normalization. A small set of triggers—semiconductor input volatility, spectrum reconfiguration decisions, and fleet operator consolidation behavior—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market