
 Asia Pacific Gasoline Injection Technologies Market | 2026-2036
Asia Pacific Gasoline Injection Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Gasoline Injection Technologies Market Outlook
Software-defined calibration services is expanding as a recurring revenue layer atop hardware sales, allowing suppliers to monetize engine mapping updates over vehicle lifecycles. Bosch leverages its embedded software stack to lock in multi-year service contracts with Asian OEMs. Denso Corporation anchors its position through captive semiconductor supply for injector driver ICs. Continental AG competes on integrated powertrain-electronics bundles that reduce OEM assembly complexity.
Asia Pacific gasoline injection technologies encompass precision fuel delivery systems that atomize gasoline at pressures ranging from 3.5 bar in port fuel injection to over 350 bar in advanced direct injection architectures, serving the fundamental purpose of optimizing combustion efficiency while minimizing particulate and hydrocarbon emissions. Direct injection technology leads value generation due to its compatibility with downsized turbocharged engines, though dual injection systems represent the fastest-growing configuration as OEMs seek to mitigate carbon deposit and particulate number challenges inherent to standalone direct injection. The aftermarket provider channel occupies a distinct margin pool driven by injector replacement cycles and refurbishment demand across aging vehicle parcs in Southeast Asia.
China's MIIT administers fuel consumption limits and new energy vehicle credit mandates that compel gasoline engine efficiency gains, while Japan's METI oversees harmonized standards through JIS certification frameworks for automotive components. India's BIS enforces emission-related component testing that conditions market access for imported injection systems. Stakeholders must monitor how China's dual carbon trajectory and India's pending CAFE-equivalent regulations recalibrate the competitive priority between incremental gasoline efficiency and hybrid electrification strategies.
Market Dynamics
China's MIIT fuel economy mandates and dual carbon goals are compressing development cycles for gasoline injection architectures, forcing suppliers to accelerate dual injection system deployment while managing semiconductor sourcing constraints for injector driver ICs.
Growth Catalysts
- MIIT Fuel Consumption Limits:China's corporate average fuel consumption regulations compel passenger vehicle OEMs to adopt advanced direct injection paired with turbocharging, creating sustained hardware refresh demand across domestic engine platforms.
- Dual Injection Configuration:The fastest-growing system architecture combines port and direct injection to mitigate particulate number emissions and intake valve carbon deposits, solving inherent limitations of standalone direct injection.
- Yangtze River Delta Cluster:Tier-1 suppliers concentrated in Shanghai, Jiangsu and Zhejiang provinces integrate injection system production with domestic turbocharger manufacturing, shortening OEM qualification timelines.
Market Restraints
- Semiconductor Supply Concentration:Captive production of injector driver integrated circuits by Denso and Bosch creates allocation bottlenecks during foundry capacity constraints, extending lead times for second-tier suppliers.
- High-Pressure Pump Cost Structure:Advanced direct injection systems require 350+ bar fuel pumps with precision-machined plungers and diamond-like carbon coatings, elevating bill-of-material costs relative to port fuel injection alternatives.
- Hybrid Electrification Substitution:Battery-electric and plug-in hybrid powertrains eliminate or reduce gasoline injection content per vehicle, compressing addressable market growth as China's new energy vehicle credit mandates accelerate electrification.
Strategic Opportunities
- India CAFE-Equivalent Trajectory:Pending corporate average fuel efficiency regulations will force domestic OEMs to upgrade from carburetion and basic port injection, opening retrofit and new platform opportunities for precision fuel delivery systems.
- Software-Defined Calibration Services:Over-the-air engine mapping updates enable suppliers to monetize recurring revenue streams across vehicle lifecycles, decoupling value capture from initial hardware sales.
- Southeast Asia Aftermarket Refurbishment:Aging vehicle parcs in Indonesia, Thailand and Vietnam generate injector replacement and remanufacturing demand outside OEM warranty channels, establishing margin pools distinct from new equipment supply.
Industry Challenges
- Calibration Engineer Talent Scarcity:Combustion optimization for dual injection strategies requires specialized expertise in computational fluid dynamics and engine mapping that outpaces regional university pipeline output.
- GB Standards Compliance Timeline:China's national standard updates for particulate number measurement and real-driving emissions testing compress certification windows, forcing parallel validation tracks that strain development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Gasoline Injection Technologies Market |
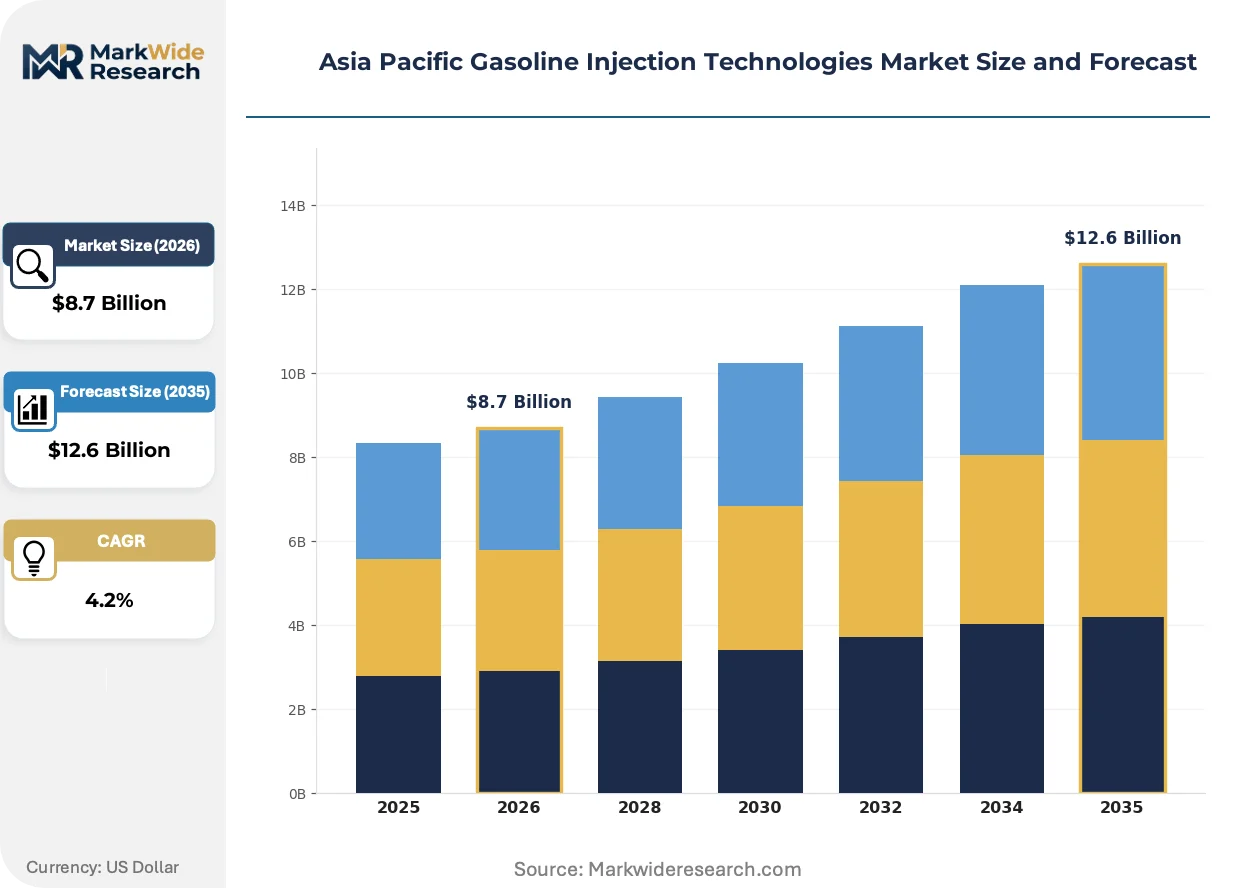
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Port Fuel Injection, Direct Injection, Dual Injection, Gasoline Common Rail Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Off-Road Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Fuel Type: Conventional Gasoline, Ethanol Blends, Premium Gasoline, Others |
| Companies Covered | Bosch, Denso Corporation, Continental AG, Delphi Technologies, Hitachi Astemo, Magneti Marelli, KEIHIN, Infineon Technologies AG, Stanadyne Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Gasoline Injection Technologies Market Strategic Shifts
Gasoline injection technology evolution centers on software-hardware convergence, with calibration intelligence and pressure architecture advances reshaping competitive differentiation beyond mechanical component precision.
Dual injection systems are integrating port and direct injection strategies into unified control architectures managed by single engine control units. Chinese and Japanese passenger vehicle OEMs are adopting these configurations fastest for downsized turbocharged engines. This convergence is compressing the market opportunity for standalone direct injection suppliers while elevating software calibration capabilities as the primary vendor selection criterion.
METI harmonization through JIS certification frameworks is aligning Japanese automotive component standards with emerging Chinese GB protocols for injector durability and emissions performance. This regulatory convergence reduces duplicate testing burdens for suppliers serving both markets. Korean and Australian OEMs sourcing from regional tier-1 suppliers are adapting procurement specifications to recognize cross-certified components.
Service unbundling is separating hardware supply from calibration update subscriptions across Asian OEM procurement contracts. Tier-1 suppliers now compete on multi-year software service attachments rather than unit pricing alone. This behavioral shift is most visible in China's state-owned automotive groups, where centralized fleet management platforms enable standardized over-the-air parameter updates across distributed vehicle populations.
Asia Pacific Gasoline Injection Technologies Market Segmentation
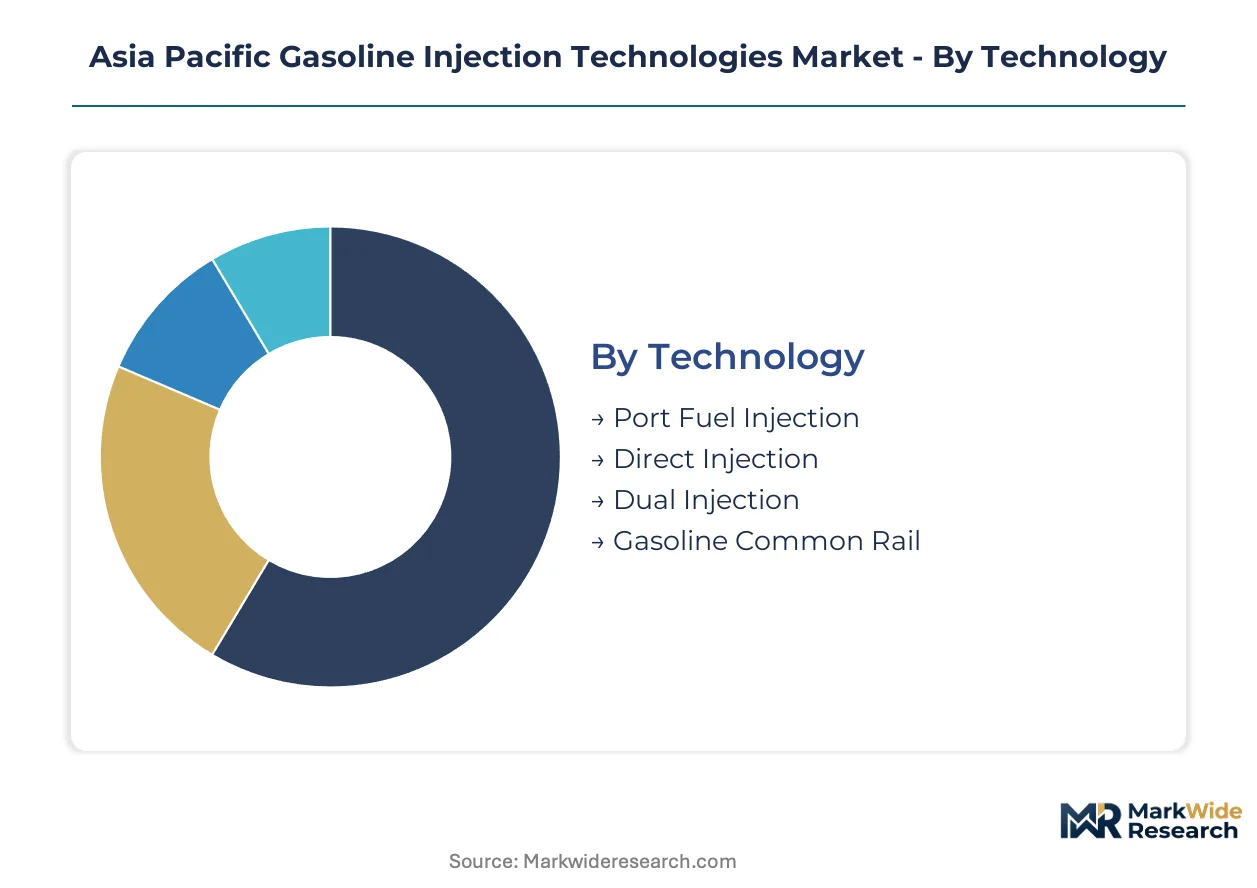
Technology choices in Asia Pacific gasoline injection determine regulatory compliance pathways, with MIIT fuel economy mandates and JIS certification frameworks imposing distinct validation requirements on each configuration. Application and end-user segmentation reveals divergent margin structures, from OEM volume contracts to aftermarket refurbishment cycles across aging Southeast Asian vehicle parcs.
Technology:
MIIT corporate average fuel consumption regulations and JIS certification frameworks impose differentiated testing burdens across injection architectures, with 350+ bar direct injection systems facing extended particulate number validation timelines.
- Port Fuel Injection:Conventional multi-point injection systems operating at 3.5-6 bar pressure, utilizing solenoid-actuated injectors mounted in intake manifolds. Demand concentrates in India's entry-level passenger vehicle segment and Southeast Asian motorcycle production as BIS emission testing and cost constraints delay direct injection adoption.
- Direct Injection:High-pressure systems delivering gasoline directly into combustion chambers at 200-350+ bar, enabling stratified charge operation and turbocharger pairing. China's Yangtze River Delta automotive cluster anchors demand as domestic OEMs pursue MIIT fuel consumption compliance through downsized turbocharged engine platforms.
- Dual Injection:Unified control architectures combining port and direct injection strategies to mitigate carbon deposit and particulate number emissions. Japanese passenger vehicle OEMs lead deployment under METI harmonization with emerging GB protocols.
- Gasoline Common Rail:Adapted diesel-derived architecture enabling ultra-high pressure distribution and multiple injection events per cycle. Limited adoption concentrates in performance-oriented engine platforms requiring precise fuel metering.
Port Fuel Injection sits at the top of the volume ranking, with Dual Injection climbing the fastest.
Application:
Cost tier differentiation separates premium powertrain integration from price-sensitive mass-market configurations, with hardware complexity and software calibration requirements widening the investment gap between segments.
- Passenger Vehicles:Dominant application spanning compact sedans through luxury SUVs, requiring sophisticated injection strategies for turbocharged downsizing. China's state-owned automotive groups and Japanese OEMs drive specification intensity as MIIT mandates and METI frameworks compress development cycles.
- Commercial Vehicles:Light commercial vans and pickup trucks utilizing robust injection hardware for durability under high-load operation. Demand clusters in Thailand's pickup manufacturing hub and Indonesia's commercial fleet renewal programs.
- Motorcycles:Single-cylinder and parallel-twin engines favoring simplified port fuel injection for cost containment. India and Vietnam anchor volume as two-wheeler electrification pressures gasoline injection content per unit.
- Off-Road Vehicles:Agricultural machinery and construction equipment requiring sealed injector designs for contaminated operating environments. Australia's mining equipment sector and China's agricultural mechanization programs generate specialized demand.
Passenger Vehicles command the largest hardware allocation, though Commercial Vehicles demonstrate the steepest expansion trajectory in Southeast Asian production hubs.
End User:
Customer type determines procurement pattern divergence, with centralized fleet platforms enabling software service attachments distinct from fragmented aftermarket transactions.
- OEMs:Volume-contracted tier-1 supply with multi-year platform commitments and integrated powertrain-electronics bundling. Chinese and Japanese manufacturers dominate procurement as domestic content requirements strengthen regional supplier relationships.
- Aftermarket Providers:Independent distributors and remanufacturers serving injector replacement cycles outside warranty channels. Indonesia, Thailand, and Vietnam's aging vehicle parcs generate margin pools distinct from new equipment supply.
- Fleet Operators:Centralized procurement by ride-hailing and logistics platforms enabling standardized calibration updates across distributed vehicle populations. China's state-owned automotive groups leverage fleet scale for over-the-air parameter management.
- Repair Shops:Fragmented service channel requiring diagnostic tooling compatibility and technical training support. Southeast Asian independent workshops drive refurbishment demand as vehicle ownership periods extend.
OEMs retain dominant volume share, with Fleet Operators gaining share fastest through centralized procurement platforms.
Fuel Type:
Regional fuel quality standards and biofuel mandates reshape injector material specifications and calibration maps across national markets.
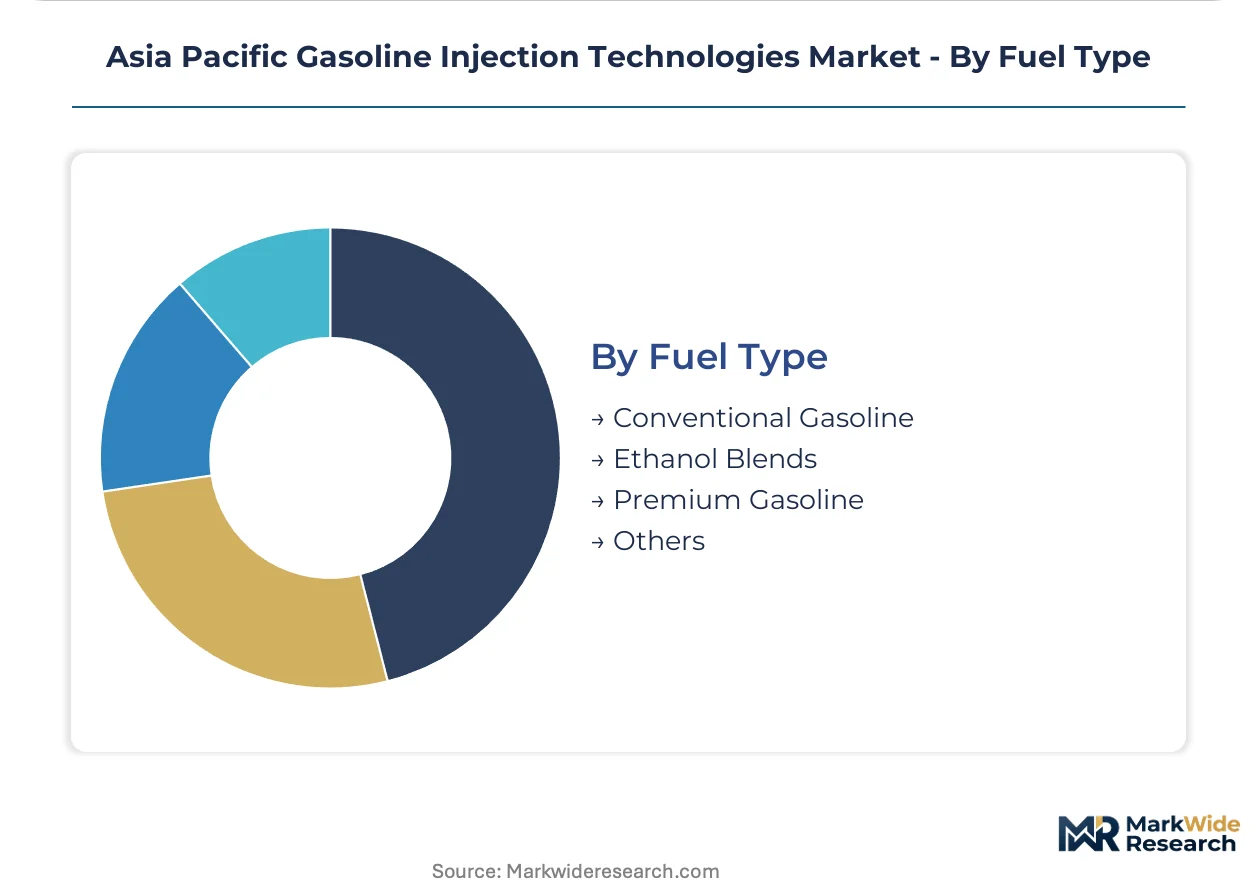
- Conventional Gasoline:Standard 91-95 RON fuels requiring baseline injector compatibility across all technology configurations. Prevails in markets with limited ethanol infrastructure.
- Ethanol Blends:E10-E85 formulations demanding corrosion-resistant injector materials and modified sealing compounds. Brazil's ANVISA fuel quality regulations and Thailand's national biofuel program drive specification requirements.
- Premium Gasoline:98+ RON fuels enabling advanced ignition timing and higher compression ratios in performance applications. Concentrates in premium passenger vehicle segments across Australia, Japan, and South Korea.
- Others:Emerging synthetic and renewable gasoline formulations requiring calibration adaptability. Limited commercial deployment under regulatory evaluation.
Conventional Gasoline maintains volume leadership, with Ethanol Blends expanding most quickly in biofuel-mandated Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforcement compresses development cycles faster than India's BIS testing timelines permit, creating divergent supplier investment priorities across the region's two largest automotive markets.
China
Passenger vehicle OEMs in the Yangtze River Delta cluster integrate dual injection systems with domestic turbocharger manufacturing to satisfy MIIT corporate average fuel consumption regulations. The Shanghai-Jiangsu-Zhejiang corridor anchors tier-1 supplier concentration as state-owned automotive groups deploy centralized fleet management platforms for over-the-air calibration updates.
Japan
METI harmonization through JIS certification frameworks aligns injector durability standards with emerging Chinese GB protocols, reducing duplicate testing burdens for suppliers serving both markets. Kansai and Chubu industrial regions concentrate precision machining capacity for high-pressure pump components.
India
Entry-level passenger vehicles and two-wheeler production sustain port fuel injection demand as BIS emission-related component testing conditions market access for imported systems. Maharashtra and Tamil Nadu automotive corridors await pending CAFE-equivalent regulations that would force domestic OEMs to upgrade from carburetion.
Thailand
Pickup manufacturing hubs and national biofuel programs drive specification requirements for ethanol-blend compatible injector materials. Bangkok-anchored tier-1 suppliers balance OEM volume contracts with aftermarket refurbishment demand from aging commercial fleets.
Indonesia
Aging vehicle parcs generate injector replacement cycles outside warranty channels, establishing margin pools for independent distributors and remanufacturers. Java-based repair shops drive diagnostic tooling compatibility requirements as vehicle ownership periods extend.
Asia Pacific Gasoline Injection Technologies Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated powertrain-electronics bundling consolidating OEM procurement decisions while semiconductor-captive suppliers capture allocation priority during foundry constraints. Three archetypes dominate: vertically integrated conglomerates with captive semiconductor production, modular system integrators competing on assembly complexity reduction, and software-focused vendors monetizing calibration subscriptions. Geographic expansion through Yangtze River Delta production bases and strategic partnerships for dual injection system co-development represent the dominant competitive moves.
Within the vertically integrated tier, Bosch, Denso Corporation, and Continental AG exemplify divergent strategic positioning. Bosch leverages embedded software stacks to anchor multi-year service contracts with Asian OEMs. Denso Corporation occupies a position defined by captive semiconductor supply for injector driver ICs. Continental AG represents the integrated powertrain-electronics bundling archetype that reduces OEM assembly complexity.
| Leading Market Players |
|---|
| Bosch |
| Denso Corporation |
| Continental AG |
| Delphi Technologies |
| Hitachi Astemo |
| Magneti Marelli |
| KEIHIN |
| Infineon Technologies AG |
| Stanadyne Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Japan's Kansai region anchor precision machining capacity for high-pressure pump plungers, translating captive process knowledge into pricing discipline that resists commoditization pressures from Chinese volume manufacturers. This ownership pattern concentrates supply-side bargaining power among semiconductor-captive conglomerates while fragmenting second-tier injector assembly, creating divergent margin pools across the hardware stack.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for port fuel injection hardware as domestic tier-1 suppliers achieve scale economies in solenoid actuator production. Three-tier pricing structure across premium calibration-integrated bundles, standard direct injection systems, and economy port injection configurations stratifies the market, with premium tiers capturing software service attachments. Pricing pressure stems from hybrid electrification substitution compressing gasoline content per vehicle, with Indian entry-level OEMs exhibiting highest price sensitivity due to pending CAFE-equivalent regulatory uncertainty.
Supply Chain Analysis
Regional distribution centers in Shanghai, Bangkok, and Jakarta orchestrate hub-and-spoke patterns for injector refurbishment parts serving Southeast Asian aftermarket channels. Manufacturing concentrates in China, Japan, and South Korea, with precision-machined plungers and diamond-like carbon coatings drawing from specialized foundry capacity in Japan's Chubu region. Single-source vulnerability in injector driver ICs—where Denso and Bosch maintain captive semiconductor production—creates allocation bottlenecks during foundry constraints. Distribution runs through tier-1 supplier direct OEM contracts for new equipment, diverging to independent distributor networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific gasoline injection technologies function as a geographic-arbitrage play where India's delayed CAFE-equivalent timeline against China's MIIT enforcement creates a 3-5 year window for cost-optimized port injection platforms before regulatory convergence.
For Market Incumbents: Deploy software-defined calibration service contracts to lock in recurring revenue streams as hardware margins compress under hybrid electrification substitution. Denso and Bosch should extend captive semiconductor allocation priority to allied tier-2 suppliers during foundry constraints, consolidating channel control against modular system integrators. Securing JIS-GB cross-certification alignment ahead of METI harmonization completion will preempt duplicate testing burdens for dual injection architectures. For New Entrants and Emerging Players: Aftermarket diagnostic tooling for dual injection systems represents the most penetrable white-space target, as Southeast Asian repair shops face capability gaps in carbon deposit remediation and injector remanufacturing. India's pending corporate average fuel efficiency regulations open retrofit opportunities for precision fuel delivery upgrades from carburetion and basic port injection. A channel partnership with Yangtze River Delta turbocharger manufacturers offers the fastest OEM qualification pathway for new platform integration. For Investors and Strategic Acquirers: Chinese state-owned automotive groups are the most active acquirer in this space, seeking vertical integration into injector driver IC design to secure supply allocation. The 5-10 year viability window hinges on gasoline engine platform persistence against battery-electric substitution in China's passenger vehicle parc. Watch for MIIT fuel consumption limit stringency revisions as the critical inflection signal—tightening would accelerate dual injection adoption, while relaxation would extend port injection runway.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Injection System Co-Development | Japanese OEMs partner with Yangtze River Delta suppliers to compress MIIT compliance timelines. |
| Captive Semiconductor Capacity Expansion | Denso's in-house injector driver IC production insulates against foundry allocation bottlenecks. |
| Software Calibration Subscription Launch | Bosch monetizes over-the-air engine mapping updates across Chinese state-owned fleet platforms. |
| Aftermarket Refurbishment Network Buildout | Indonesian distributors capture margin pools from aging vehicle parc injector replacement cycles. |
| JIS-GB Cross-Certification Investment | Continental AG reduces duplicate testing burdens under METI harmonization frameworks. |
Study Parameters
Coverage spans China, Japan, India, Thailand, and Indonesia, with primary inputs from each market combining structured interviews with OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributors, and fleet operations managers with secondary validation. Secondary sources include MIIT corporate average fuel consumption filings, JIS certification registry data, BIS emission testing protocols, vehicle production databases, and IHS Markit registration statistics. Bottom-up segment sizing triangulates against top-down market value reconstruction across technology, application, and end-user dimensions.
Granularity-level modeling disaggregates volume and value outputs across port fuel injection, direct injection, dual injection, and gasoline common rail configurations, with further subdivision by passenger vehicle, commercial vehicle, motorcycle, and off-road application categories. CAGRs derive from regression analysis of historical technology adoption curves against regulatory enforcement timelines, incorporating OEM platform refresh cycles and semiconductor supply elasticity as industry-specific forecast inputs.
The model holds under sustained MIIT fuel economy enforcement and METI-JIS harmonization progress; deviation in India's CAFE-equivalent implementation timing or accelerated battery-electric penetration in China would shift technology mix assumptions. Forecasts reflect documented assumptions around regulatory stringency and supply allocation stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Crate Engines Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Automotive Powertrain Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Automotive Camshaft Market
Powertrain
Automotive Powertrain Components Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Automotive Camless Engine Market
Powertrain
Transmission Fluids Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Car Oil Filter Market
Powertrain
Truck Auxiliary Power Units Market