
 Electric LCV Market | 2026-2036
Electric LCV Market Size, Share, and Industry Trends Forecast 2026-2036
Electric LCV Market Foresight
Multi-source battery supply is consolidating as tier-one automakers reduce dependency on single-cell producers. BYD Group leverages captive lithium-iron-phosphate cell production to control cost curves across its commercial van portfolio. Ford Motor Company sustains North American competitiveness through integrated vertical assembly at its Rouge Electric Vehicle Center. Stellantis NV anchors European volume through shared-platform architectures spanning Fiat, Peugeot, and Opel electric LCV nameplates.
An electric light commercial vehicle is a battery-powered freight or service vehicle with a gross vehicle weight rating typically below 3.5 tonnes, utilizing lithium-ion battery packs ranging from 20 kWh to 100 kWh and regenerative braking systems to maximize urban range. Its primary commercial purpose is zero-emission goods distribution, tradesman transport, and municipal service operations in dense urban environments where noise and air quality restrictions apply. Panel van configurations dominate current volume owing to standardized cargo dimensions favored by parcel carriers, while 60 kWh and 100 kWh battery tiers capture disproportionate margin pools as fleet operators prioritize range certainty over acquisition cost. DC fast charging infrastructure determines operational viability for logistics companies running multi-shift schedules, creating structural preference for vehicles accepting 150 kW or higher charge rates.
The EU Green Deal and F-Gas Regulation shape powertrain cooling requirements and refrigerant choices across European electric LCV production lines. EPA tailpipe standards and NHTSA fuel economy rules in the United States compel domestic manufacturers to expand battery-electric offerings beyond compliance-car volumes. Fleet managers and component suppliers must monitor charging infrastructure build-out rates and battery raw material sourcing agreements as the primary variables determining achievable deployment timelines.
Market Dynamics
Fleet operators now face a structural squeeze between EU Green Deal mandates requiring zero-emission vehicle adoption and lithium supply bottlenecks constraining battery pack availability for commercial van production.
Growth Catalysts
- Urban Low-Emission Zones:Municipal access restrictions in London, Paris, and Berlin block diesel van entry, forcing parcel carriers to electrify last-mile delivery fleets.
- EU Green Deal:The framework's transport decarbonization targets accelerate ICE phase-out timelines across member states, compressing fleet replacement cycles.
- DC Fast Charging Infrastructure:150 kW and higher charge rate deployment along logistics corridors enables multi-shift electric LCV operations previously limited by dwell time constraints.
Market Restraints
- Lithium Price Volatility:Spodumene concentrate and lithium carbonate cost swings compress battery pack margins, forcing automakers to absorb input spikes or pass through to fleet buyers.
- Single-Source Cell Dependency:Concentrated cathode active material production in China creates supply vulnerability for European and North American electric van assembly lines.
- Payload-Range Tradeoff:Higher battery capacity adds curb weight, reducing available cargo mass below thresholds required by heavy freight operators.
Strategic Opportunities
- Swappable Battery Architectures:Battery-as-a-service models eliminate upfront capital barriers for small fleet operators in Spain and Italy, expanding addressable market beyond large logistics enterprises.
- Vehicle-to-Grid Integration:Bidirectional charging capabilities allow parked electric LCVs to provide grid stabilization services, creating secondary revenue streams for fleet asset owners.
- Refrigerated Van Electrification:F-Gas Regulation phase-down creates replacement demand for diesel-powered refrigeration units in cold-chain logistics, favoring electric compressor systems.
Industry Challenges
- High-Voltage Technician Shortage:Fleet maintenance departments lack certified personnel for battery pack diagnostics and thermal management system repairs, extending vehicle downtime.
- Depot Charging Infrastructure Capex:Warehouse electrical upgrades, transformer capacity expansion, and smart load management systems require capital deployment that strains SME fleet balance sheets.
- Homologation Timeline Compression:Accelerated model launch schedules compress validation cycles for crash safety, electromagnetic compatibility, and battery thermal runaway testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric LCV Market |
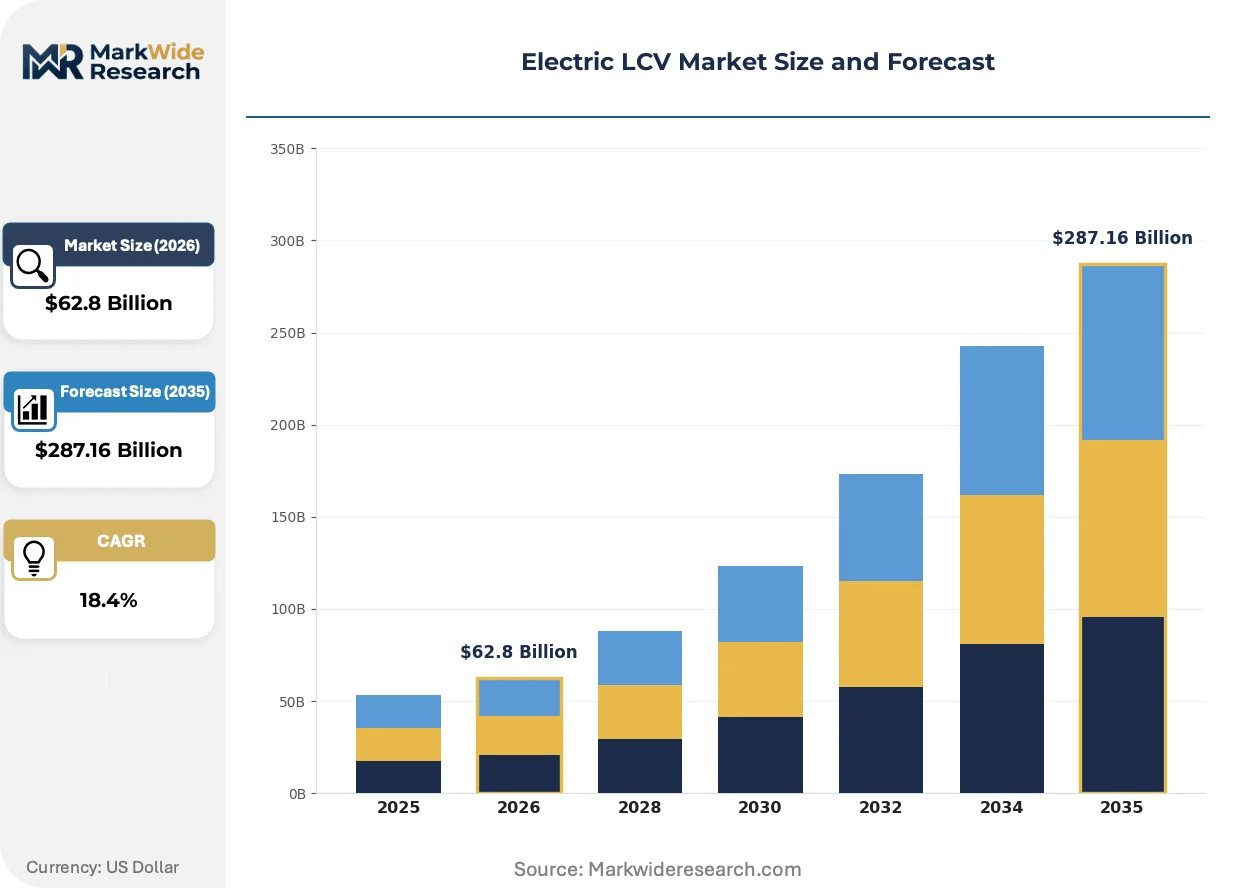
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $287.16 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Panel Van, Pickup Truck, Chassis Cab, Box Truck Battery Capacity: 20 kWh, 40 kWh, 60 kWh, 100 kWh Charging Type: AC Charging, DC Fast Charging, Wireless Charging, Fleet Charging End User: Logistics Companies, E-commerce Retailers, Municipal Services, Small Businesses |
| Companies Covered | BYD Group, Ford Motor Company, Renault Group, General Motors, Volkswagen AG, Stellantis NV, Mercedes-Benz Group AG, AB VOLVO, Wuling Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric LCV Market Shifts & Advancements
Solid-state battery prototyping and thermal management advances are compressing the performance gap between electric and diesel commercial vans, while regulatory pressure on refrigerants and charging standards locks in technical specifications.
Lithium-iron-phosphate cell chemistry is converging with commercial vehicle thermal management systems to reduce battery degradation under high-duty-cycle operations. Parcel carriers operating 200,000 km annual mileage are adopting LFP packs for their superior cycle life and reduced cooling requirements. This convergence is compressing total cost of ownership parity timelines against diesel equivalents in high-utilization segments.
The EU F-Gas Regulation mandates refrigerant phase-down in transport refrigeration units, forcing cold-chain operators to adopt electric compressor systems or pay escalating carbon-equivalent levies. Equipment suppliers must redesign rooftop refrigeration units for compatibility with electric LCV high-voltage architectures. German and French refrigerated van fleets face the steepest compliance deadlines under national implementation schedules.
Leasing structures now dominate electric LCV acquisition as fleet managers transfer residual value risk and battery degradation exposure to financial intermediaries. Full-service lease packages bundle vehicle, charging infrastructure, and energy costs into per-kilometer rates. This shift is most visible in the United Kingdom and Netherlands, where tax treatment favors off-balance-sheet fleet financing over direct purchase models.
Electric LCV Market Segmentation
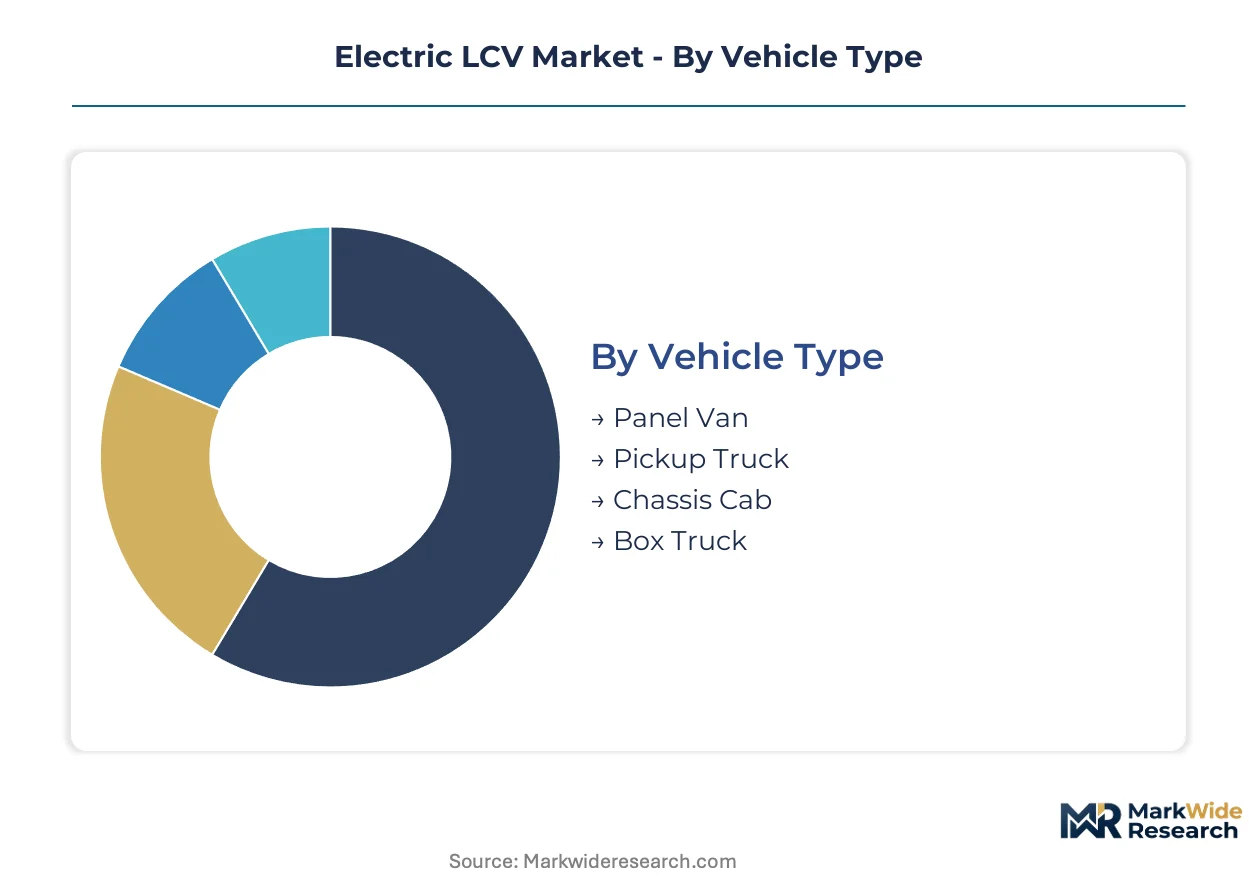
Electric LCV segmentation reveals how fleet operators balance payload requirements against charging infrastructure constraints. Each dimension—vehicle architecture, energy storage, power delivery, and buyer type—creates distinct margin pools and competitive dynamics.
Vehicle Type:
The customization-to-standardization spectrum runs from purpose-built municipal chassis to mass-market panel configurations serving parcel networks.
- Panel Van:Enclosed cargo bays with standardized dimensions dominate parcel carrier procurement. DHL Express and Amazon Logistics specify these units for urban last-mile routes where load height and cubic capacity matter more than maximum payload.
- Pickup Truck:Open-bed configurations serve tradesmen and construction fleets requiring tool accessibility and irregular load shapes. Demand concentrates in North American markets where contractor preference for bed utility resists van-format adoption.
- Chassis Cab:Incomplete vehicles awaiting aftermarket body installation allow bespoke upfitting for specialized municipal and utility applications. German waste management fleets favor these for compactor and sweeper attachments.
- Box Truck:Rigid bodies with separate cabs maximize cubic capacity for furniture and appliance delivery. French retail logistics operators deploy these for bulky goods routes exceeding panel van dimensional limits.
Most installed capacity flows through Panel Van configurations. Expansion is steepest in Chassis Cab segments as municipal electrification accelerates.
Battery Capacity:
Cost tier stratification separates entry-level urban delivery from extended-range intercity operations, with mid-tier packs capturing disproportionate fleet procurement volume.
- 20 kWh:Compact packs suit micro-delivery routes under 80 kilometers. British grocery delivery startups deploy these for hyperlocal store-to-door circuits where overnight depot charging eliminates range anxiety.
- 40 kWh:Mid-range configurations balance acquisition cost against operational flexibility. Italian small fleet operators favor this tier for mixed urban-suburban service territories where single-shift duty cycles predominate.
- 60 kWh:Extended-range packs enable full-shift operation without midday charging. Spanish parcel carriers specify these for regional distribution centers serving multiple urban zones.
- 100 kWh:Maximum-capacity systems support refrigerated transport and heavy payload applications. Cold-chain logistics operators in the Netherlands accept weight penalties for thermal management energy reserves.
Procurement volumes peak at 60 kWh. Steepest expansion trajectory belongs to 100 kWh as refrigerated electrification gains regulatory momentum.
Charging Type:
Application context determines infrastructure investment—depot-based fleets prioritize capital efficiency while corridor operators demand speed.
- AC Charging:Level 2 overnight depot systems minimize electricity demand charges. Small business fleets with predictable return-to-base patterns achieve lowest total cost of ownership through this approach.
- DC Fast Charging:150 kW and higher rates enable opportunity charging between delivery waves. Multi-shift logistics operators in Germany deploy corridor networks for extended range without battery oversizing.
- Wireless Charging:Inductive pads at loading docks eliminate connector wear and driver intervention. Pilot deployments in Swedish municipal bus depots suggest transferability to commercial van applications.
- Fleet Charging:Managed charging software coordinates hundreds of vehicles against grid capacity constraints. Large e-commerce retailers in the United Kingdom negotiate time-of-use tariffs through aggregated load management.
Capital deployment concentrates in Fleet Charging infrastructure. Wireless installations are gaining share fastest as automation requirements intensify.
End User:
Customer type segmentation separates price-sensitive owner-operators from sophisticated fleet managers with structured procurement processes.
- Logistics Companies:Professional fleet operators with centralized procurement and standardized vehicle specifications. DPD and FedEx European divisions negotiate multi-thousand unit contracts with battery degradation guarantees.
- E-commerce Retailers:Vertically integrated delivery networks with captive route optimization software. Amazon and Zalando specify telematics integration for real-time delivery promise management.
- Municipal Services:Public sector buyers with extended replacement cycles and domestic content requirements. French departmental councils prioritize Stellantis and Renault offerings under national industrial policy.
- Small Businesses:Owner-operators and tradesmen with single-vehicle or small fleet holdings. British electricians and plumbers dominate this segment, leasing through dealer networks to preserve balance sheet capacity.
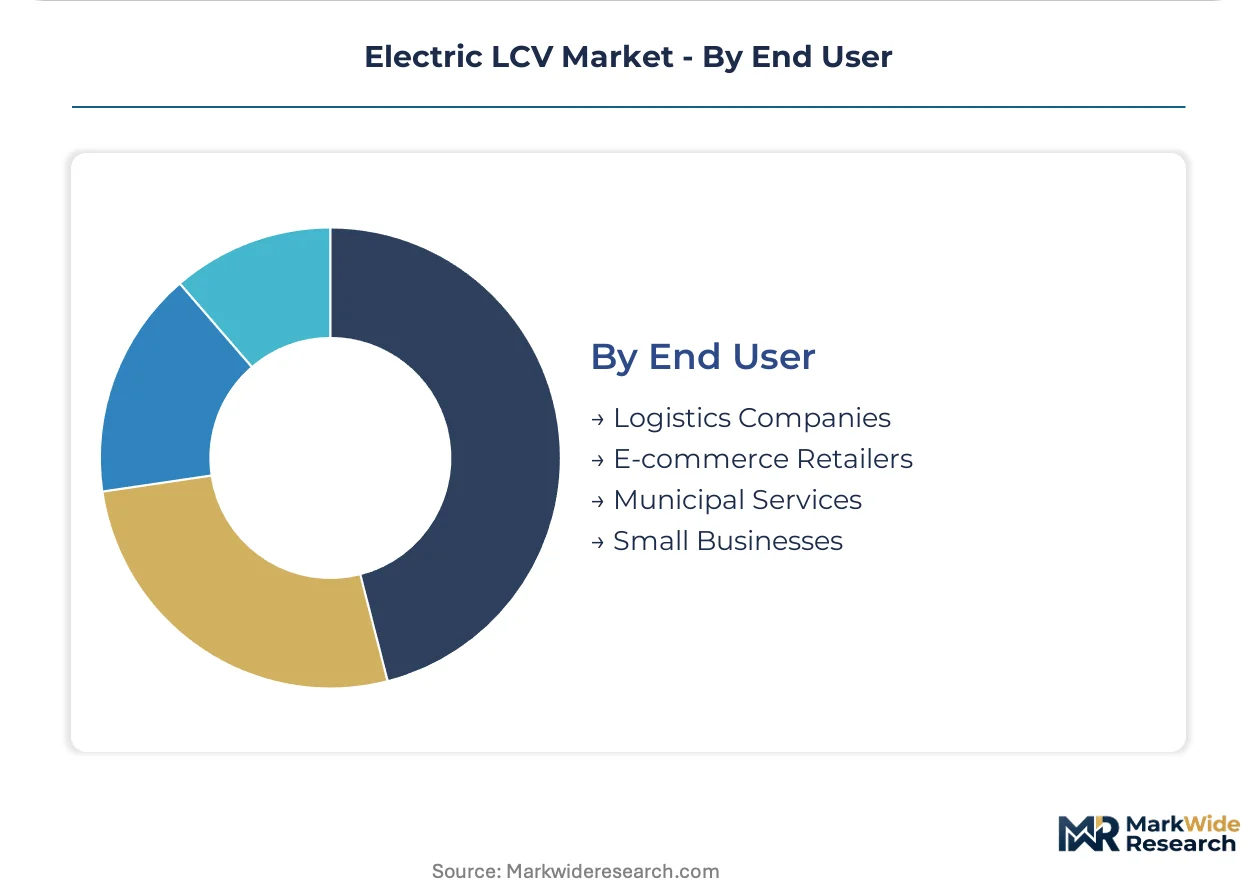
Logistics Companies account for dominant procurement volume. E-commerce Retailers show the steepest demand acceleration as in-house delivery networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor hosts the densest concentration of electric LCV assembly and fleet deployment infrastructure. The country's automotive engineering heritage and stringent urban emissions frameworks position it as the primary demand center for battery-electric commercial vans. National regulations and municipal access restrictions across multiple countries are compressing electrification timelines.
Germany
DHL Express and Deutsche Post operate Europe's largest electric van fleet from distribution hubs in Cologne and Bonn. The KBA enforces strict type-approval standards for commercial vehicle electrification under national implementation of EU Green Deal targets. Bavaria's Munich-Stuttgart manufacturing belt concentrates Stellantis and Mercedes-Benz assembly lines serving pan-European logistics contracts.
United Kingdom
Amazon Logistics and Royal Mail have committed to fully electric last-mile delivery fleets across Greater London and Birmingham metropolitan zones. The UK's ZEV mandate requires van manufacturers to sell increasing percentages of zero-emission vehicles annually through 2030. The Midlands logistics corridor connecting Coventry to Leicester hosts the country's densest depot charging infrastructure deployment.
France
La Poste and Chronopost operate national parcel networks with standardized Renault and Stellantis electric van specifications. The French government's ecological bonus scheme subsidizes commercial fleet electrification through direct purchase incentives and lease support. The Île-de-France region surrounding Paris enforces the country's strictest low-emission zone access restrictions, forcing diesel van retirement.
Netherlands
Coolblue and Picnic deploy refrigerated electric vans from automated fulfillment centers in Utrecht and Eindhoven. The Dutch government's Environmental Investment Allowance permits accelerated depreciation for zero-emission commercial vehicles. The Randstad conurbation linking Amsterdam, Rotterdam, and The Hague exhibits the highest per-capita DC fast charging density for logistics applications.
Spain
Correos and SEUR expand electric van operations across Madrid and Barcelona urban distribution networks. The country's Moves III program channels public investment into commercial fleet electrification and charging infrastructure. Catalonia's Barcelona metropolitan area hosts pilot deployments of swappable battery architectures for small fleet operators.
Electric LCV Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-as-a-service and vehicle-to-grid integration models. The market exhibits moderate consolidation with five automotive groups controlling approximately seventy percent of European and North American volume. Three strategic archetypes dominate: integrated battery manufacturers leveraging captive cell supply, legacy automakers retooling combustion-era assembly plants, and commercial vehicle specialists with municipal service expertise. Competitive dynamics center on backward integration into lithium-iron-phosphate cell production and strategic partnerships with charging infrastructure operators.
Within the integrated battery tier, BYD Group and Stellantis NV exemplify contrasting approaches to supply chain control. BYD anchors the Chinese market through captive lithium-iron-phosphate production. Stellantis occupies a central position in European volume through shared-platform architectures spanning multiple brand nameplates. Ford Motor Company represents the legacy automaker archetype with North American assembly integration.
| Leading Market Players |
|---|
| BYD Group |
| Ford Motor Company |
| Renault Group |
| General Motors |
| Volkswagen AG |
| Stellantis NV |
| Mercedes-Benz Group AG |
| AB VOLVO |
| Wuling Motors |
| Others |
Supply & Pricing Matrix
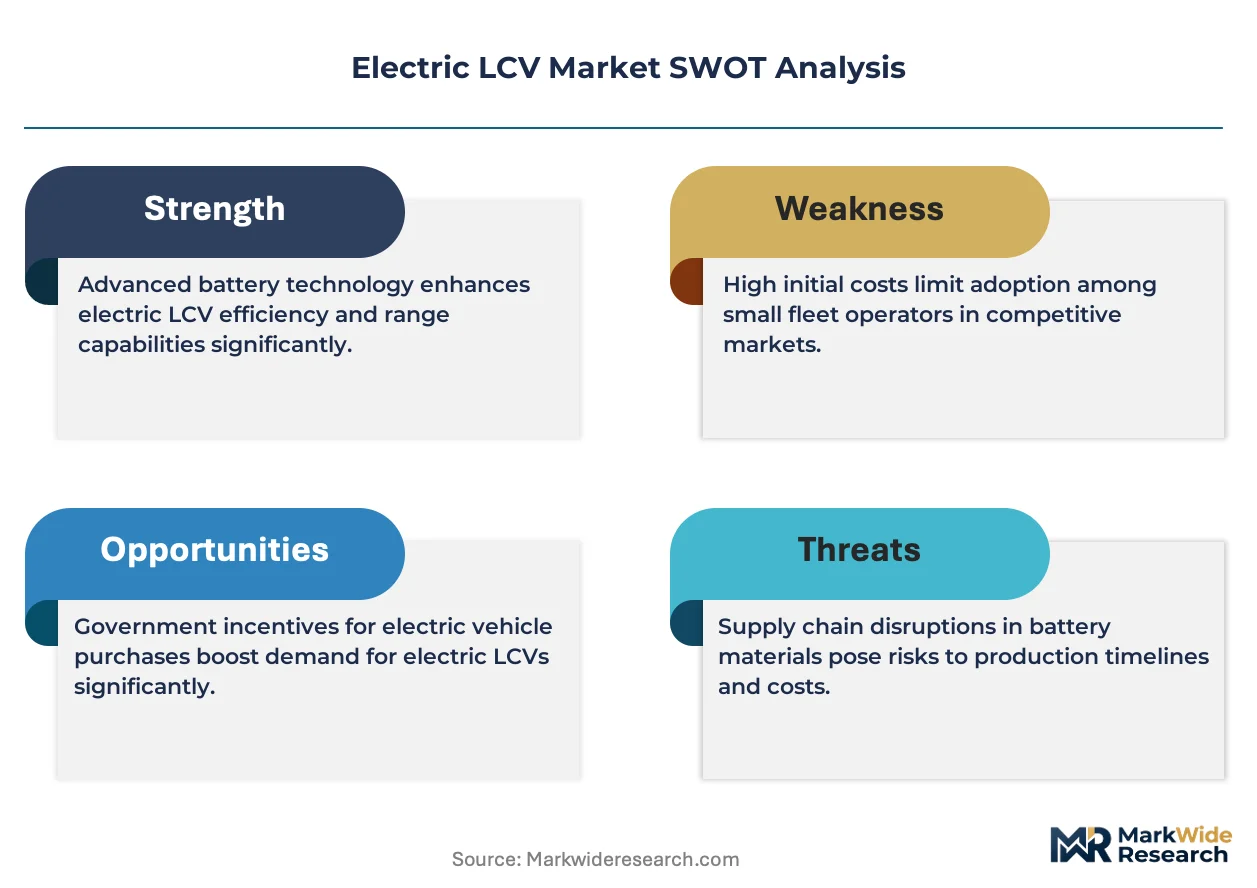
EU Green Deal compliance requirements gate qualified battery cell supply and premium-tier pricing access for electric LCV manufacturers, compressing margin pools for non-integrated assemblers while rewarding producers with captive lithium-iron-phosphate production. Fleet buyers face tiered cost structures where 100 kWh refrigerated configurations command substantial premiums over 40 kWh urban delivery variants, reflecting both raw material intensity and thermal management complexity.
Pricing Analysis
Input-cost pass-through from spodumene concentrate and lithium carbonate volatility shapes contract structures across battery capacity tiers. Three-tier pricing structure across premium, standard, and economy levels separates 100 kWh refrigerated vans with active thermal management from 60 kWh extended-range units and 40 kWh entry configurations. Pricing pressure stems from Chinese cathode active material concentration forcing European automakers to absorb margin compression or surrender fleet share. Small business owner-operators exhibit highest price sensitivity, while logistics companies with centralized procurement accept lifecycle-cost premiums for range certainty.
Supply Chain Analysis
Certified high-voltage technician scarcity in Germany, Poland, and Hungary constrains assembly line expansion and aftermarket service network buildout. Cell production concentrates in China, South Korea, and Japan, with European pack assembly drawing from Australian spodumene and Chilean lithium brine. Single-source dependency on Chinese cathode active material creates tariff exposure vulnerability for Stellantis and Mercedes-Benz European van programs. Distribution runs through captive OEM service networks for large fleet contracts, while independent dealer channels serve small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric LCV market functions as a stable compounder where regulatory mandates for urban zero-emission zones create predictable fleet replacement demand across European and North American logistics corridors.
For Market Incumbents: Acquire lithium-iron-phosphate cell production capacity to secure cost curves against Chinese supply concentration. Ford Motor Company and Stellantis NV must expand backward integration into cathode active material processing or risk margin erosion from input volatility. Defensive positioning requires charging infrastructure partnerships with corridor operators to lock multi-shift fleet contracts. For New Entrants and Emerging Players: Capture battery-as-a-service white space in Spain and Italy where small fleet operators face upfront capital barriers. Swappable architecture deployments in Barcelona metropolitan pilots demonstrate penetrable segments outside large logistics enterprise procurement. Go-to-market leverage rests on per-kilometer full-service lease bundling vehicle, energy, and depot infrastructure costs. For Investors and Strategic Acquirers: Roll-up economics work for municipal service specialists with chassis cab expertise because public sector replacement cycles extend and domestic content requirements fragment national procurement. Five-to-ten-year viability hinges on vehicle-to-grid integration capabilities creating secondary revenue streams. Watch DC fast charging corridor buildout rates as inflection signal for multi-shift operational viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | BYD Group's captive LFP production secures cost advantage for European van exports. |
| Platform Standardization | Stellantis shared architectures across Fiat, Peugeot, and Opel reduce per-unit engineering overhead. |
| Charging Infrastructure Partnership | Amazon Logistics corridor networks enable 150 kW opportunity charging for extended-range operations. |
| Software-Defined Vehicle Investment | Telematics integration supports real-time delivery promise management for e-commerce retailers. |
| Geographic Manufacturing Footprint | Rouge Electric Vehicle Center vertical assembly sustains Ford North American competitiveness. |
Research Methodology
Bottom-up fleet operator modeling reconciled against top-down battery pack production tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet charging infrastructure operators, and logistics company fleet managers combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC manufacturer filings, and EU Green Deal implementation schedules. Triangulation between demand-side deployment timelines and supply-side cell capacity announcements ensures consistency across bottom-up and top-down approaches.
Input-output matrices map battery capacity segmentation, vehicle architecture type, charging infrastructure tier, and end-user category against production volume and value outputs across the projection horizon. CAGRs derive from logistic curve adoption modeling for fleet electrification penetration, cross-referenced against regulatory mandate timelines and charging infrastructure deployment trajectories. Forecast inputs include lithium price scenario analysis and DC fast charging corridor buildout assumptions.
Raw material price shocks, charging infrastructure deployment delays, and high-voltage technician certification bottlenecks are the dominant revision risks to modeled fleet adoption timelines. Forecasts reflect documented assumptions regarding EU member state ICE phase-out enforcement and national subsidy program continuity. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Van Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
UAE Commercial Vehicles Market