
 Global Automotive FPC Market | 2026-2036
Global Automotive FPC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive FPC Market Analysis
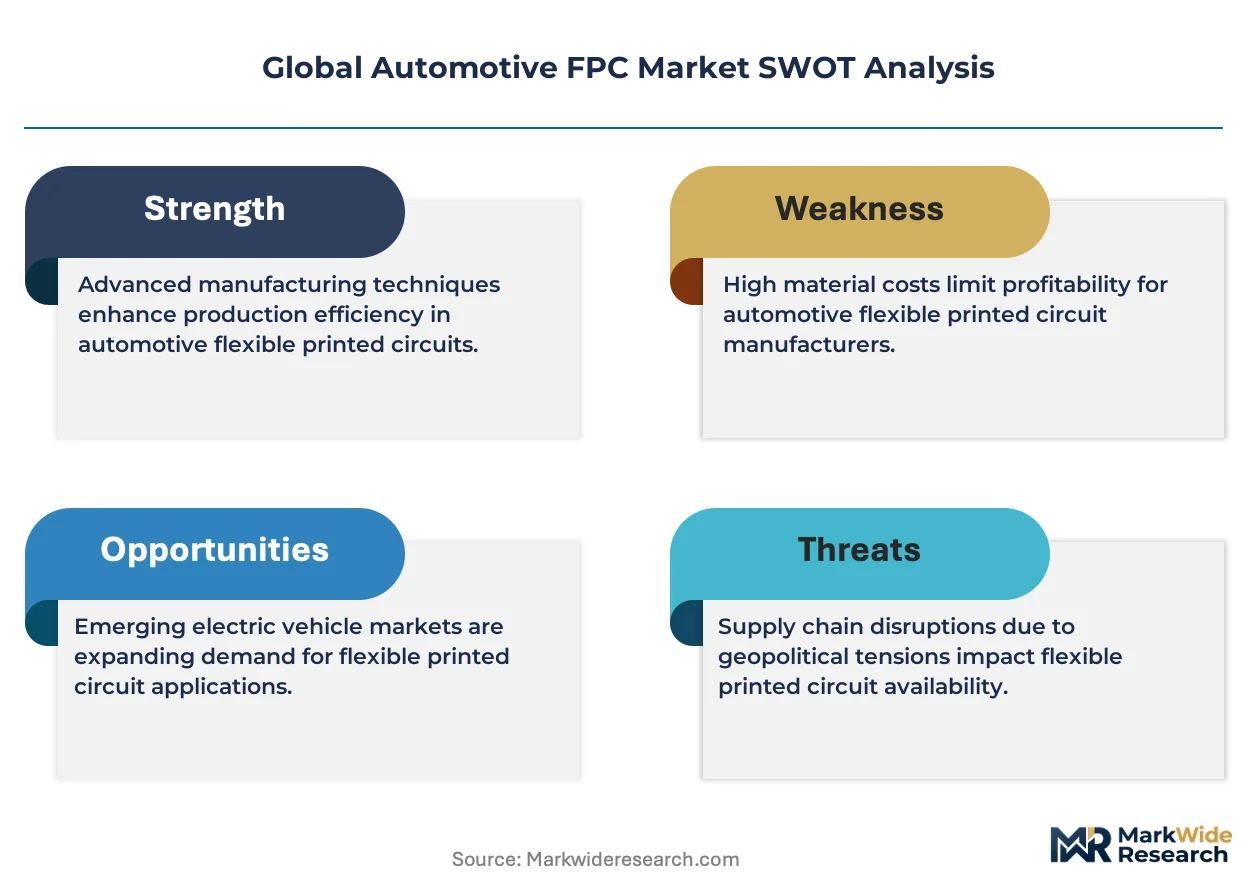
Capital-intensity divergence between high-volume roll-to-roll specialists and precision etching houses is rotating competitive advantage toward firms with captive copper-clad laminate supply. Nippon Mektron leverages its integrated polyimide film operations to sustain margin capture across multi-layer automotive grades. Zhen Ding Tech. Group anchors its position through massive substrate capacity in Taiwan and mainland China. Shennan Circuits Company Limited differentiates via HDI-flex expertise serving domestic EV platforms.
Automotive flexible printed circuit (FPC) refers to bendable interconnect substrates fabricated from polyimide or polyester films with etched copper traces, typically achieving bend radii below 3mm and operating temperatures up to 150°C. These circuits replace wire harnesses in space-constrained vehicle zones, transmitting power and signals through dynamic flexing environments. Multi-layer FPC configurations command the thickest margin pools due to laser-drilled microvia complexity and automotive-grade reliability testing. ADAS application segments are expanding fastest as camera modules and radar units proliferate across vehicle platforms. Rigid-flex hybrids retain dominance in powertrain battery management systems where mechanical stability meets spatial adaptation.
FDA material biocompatibility standards indirectly influence FPC substrate selection where circuits contact cabin air systems, while EPA REACH-compliant flame retardants constrain adhesive chemistry choices in European-bound vehicles. China's GB/T automotive electronics standards and MIIT NEV certification protocols mandate specific thermal cycling performance for FPCs in battery packs. Stakeholders must monitor how IEC 60664 insulation coordination requirements evolve for 800V architectures.
Market Dynamics
Battery electric vehicle platforms are accelerating FPC adoption for cell monitoring and thermal management, compressing design cycles and forcing suppliers to co-locate near battery pack assembly hubs in Germany, Japan, and South Korea.
Growth Catalysts
- China's NEV mandate:MIIT certification protocols mandate specific thermal cycling performance for FPCs in battery packs, creating guaranteed demand volumes for qualified suppliers.
- ADAS proliferation:Camera modules and radar units across vehicle platforms require multi-layer FPC configurations with laser-drilled microvia complexity.
- Polyimide film supply:Captive copper-clad laminate production in Taiwan and mainland China anchors substrate availability for high-volume roll-to-roll specialists.
Market Restraints
- Copper price volatility:Raw material cost swings compress margins for etching houses without backward integration into laminate supply.
- Regional supply concentration:Dense clustering of automotive electronics Tier-1 manufacturing in Germany, Japan, and South Korea creates geographic dependency risk.
- REACH-compliant chemistry constraints:ECHA flame retardant restrictions limit adhesive formulation options for European-bound vehicle programs.
Strategic Opportunities
- 800V architecture migration:IEC 60664 insulation coordination evolution creates specification white space for high-voltage FPC designs.
- Biocompatibility-adjacent cabin applications:FDA material standards indirectly influence substrate selection where circuits contact air systems, opening medical-grade crossover demand.
- Domestic EV platform localization:China's GB/T automotive electronics standards favor suppliers with in-country HDI-flex expertise.
Industry Challenges
- Automotive-grade reliability testing timelines:Extended qualification cycles for multi-layer configurations delay revenue recognition.
- Microvia laser drilling capex intensity:Precision equipment requirements strain mid-scale etching house balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive FPC Market |
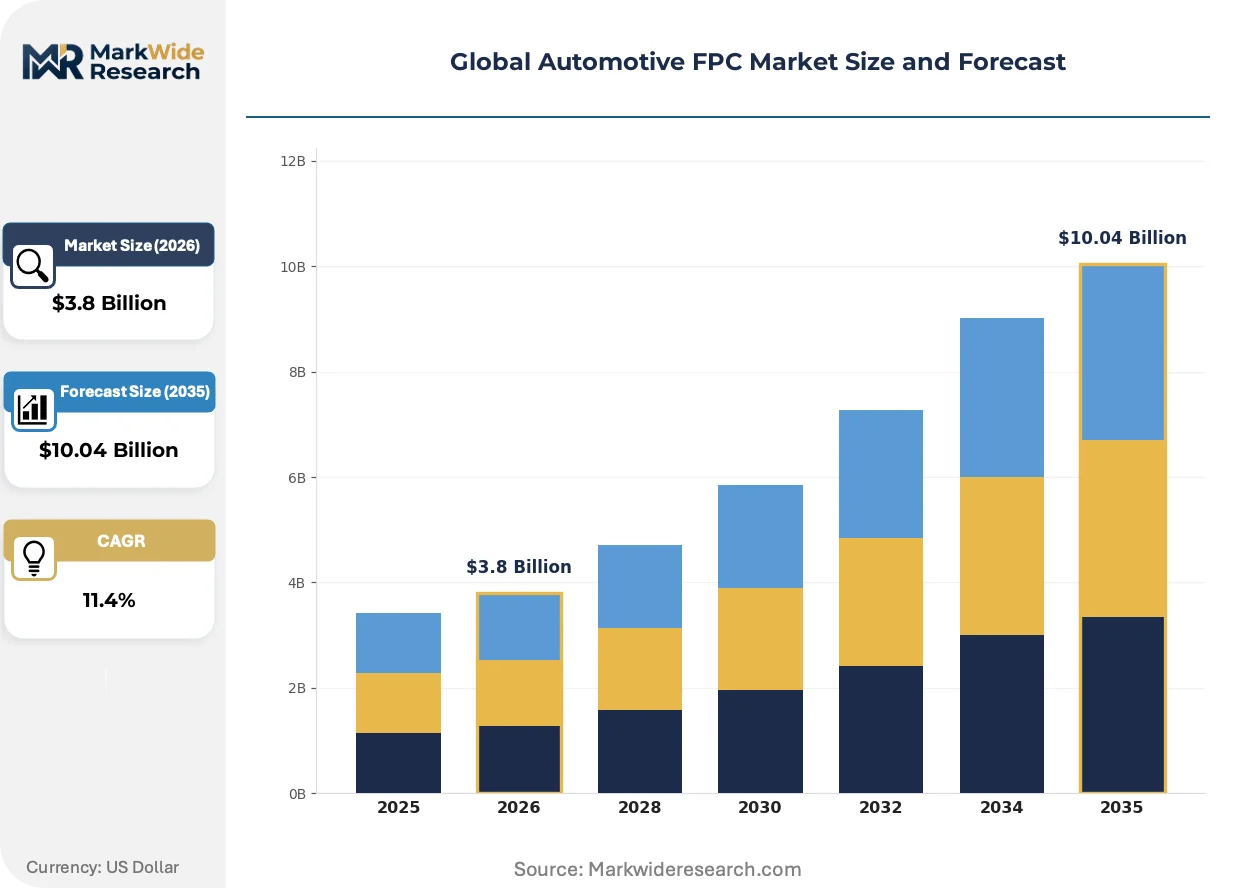
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Flex, Rigid-Flex, Multi-layer Application: Instrument Cluster, Infotainment System, ADAS, Powertrain End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Distributors Technology: Printed Circuit Board, Embedded Technologies, Hybrid Technologies, Thin Film |
| Companies Covered | Compeq Manufacturing Co., Ltd., Nan Ya PCB Co., Ltd., Nippon Mektron, Ltd., IBIDEN Co., Ltd., Shennan Circuits Company Limited, Zhen Ding Tech. Group, Suzhou Dongshan Precision Manufacturing Co., Ltd., TTM Technologies Inc., Unimicron Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive FPC Market Emerging Trajectories
Flexible printed circuit technology is fragmenting across specialization axes as battery electric vehicle platforms demand divergent performance envelopes from powertrain and cabin applications.
Embedded die packaging is decomposing traditional wire-bond interconnects in battery management systems. Cell monitoring unit manufacturers in South Korea are adopting chip-on-flex configurations at accelerated cadence. This integration is decomposing separate substrate and component supply chains into consolidated module sourcing.
Europe's F-Gas Regulation and EU Green Deal carbon accounting rules are pressuring adhesive chemistry suppliers to eliminate high-GWP process agents. FPC laminators serving German OEMs are reformulating polyimide-to-copper bonding layers. Battery pack manufacturers in Stuttgart and Munich are auditing scope-three emissions from Taiwanese substrate suppliers.
Direct sourcing contracts between battery cell producers and FPC specialists are bypassing traditional wire harness Tier-1 intermediaries. CATL and BYD are negotiating specification control directly with Shennan Circuits and Nippon Mektron for cell monitoring ribbons. This channel compression is most advanced in China's Yangtze River Delta NEV manufacturing corridor.
Global Automotive FPC Market Segmentation
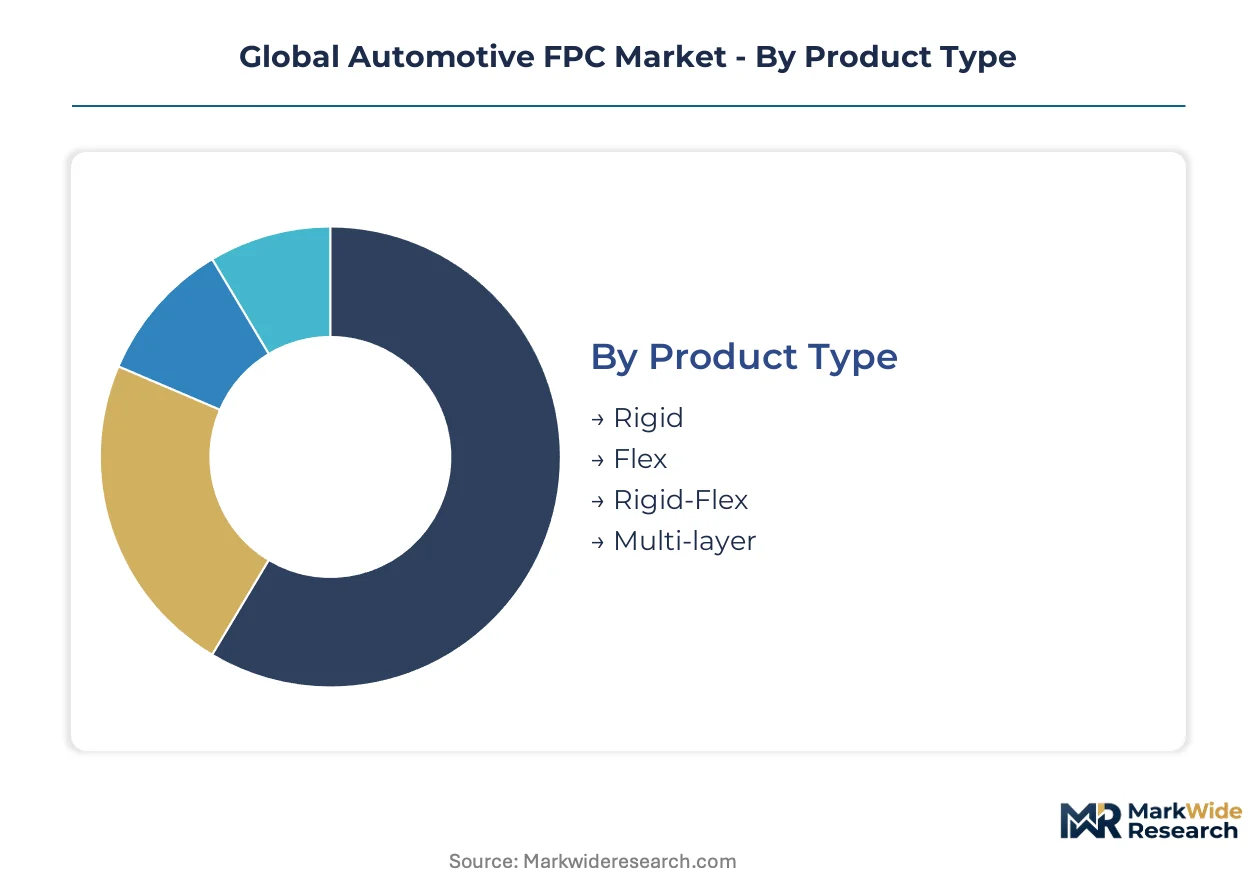
Automotive FPC segmentation reveals how substrate technologies and integration patterns map onto divergent supply chain configurations across vehicle electrification and cockpit digitization trends. Understanding these boundaries clarifies where margin pools concentrate and which qualification barriers protect incumbent positions.
Product Type:
Domestic Chinese EV platforms favor rigid-flex and multi-layer configurations for battery pack integration, while export-oriented European programs still specify discrete flex circuits for cabin applications.
- Rigid:Conventional epoxy-glass substrates with limited flexing capability serve legacy instrument cluster backplanes where mechanical stability outweighs spatial constraints. German OEMs in Stuttgart and Wolfsburg retain rigid specifications for dashboard architectures undergoing minimal redesign.
- Flex:Single-layer polyimide circuits achieve bend radii below 3mm for door panel and seat control modules. South Korean Tier-1 manufacturers in Seoul and Ulsan drive flex demand through compact camera gimbal interconnects for ADAS platforms.
- Rigid-Flex:Hybrid constructions anchor battery management systems where mechanical mounting meets dynamic flexing requirements. CATL and BYD procurement teams in Ningbo and Shenzhen specify rigid-flex for cell monitoring unit consolidation.
- Multi-layer:Laser-drilled microvia configurations with 4+ copper layers command premium positioning for radar signal integrity and high-speed camera data transmission.
Rigid-Flex holds the largest share; momentum sits with Multi-layer as 800V architectures proliferate.
Application:
Cost tiers separate safety-critical powertrain applications from discretionary infotainment systems, with ADAS occupying an intermediate qualification tier.
- Instrument Cluster:Rigid substrates dominate digital display backplanes where thermal cycling demands remain moderate. Japanese OEMs in Toyota City and Hiroshima specify proven rigid-FPC hybrids for cluster consolidation.
- Infotainment System:Consumer-grade reliability standards permit polyester film alternatives to automotive polyimide. Chinese domestic brands in Guangzhou and Hangzhou prioritize cost compression over extended temperature ratings.
- ADAS:Multi-layer microvia configurations with controlled impedance govern camera and radar module interconnects. South Korean electronics houses in Suwon and Pyeongtaek drive specification tightening for 4D imaging radar deployments.
- Powertrain:Rigid-flex and embedded die technologies converge in battery pack cell monitoring ribbons where thermal runaway protection mandates 150°C continuous operation. Ningde and Shenzhen battery assembly corridors concentrate powertrain FPC demand.
Powertrain commands the steepest expansion trajectory; Instrument Cluster retains volume leadership through replacement cycles.
End User:
Procurement patterns diverge between battery cell producers sourcing direct and wire harness intermediaries defending module integration roles.
- OEMs:Volkswagen, BMW, and Mercedes-Benz technical centers in Munich and Stuttgart exercise direct specification control for flagship EV architectures. Their captive engineering teams mandate supplier co-location near battery pack assembly.
- Aftermarket Suppliers:Repair and retrofit channels favor standardized flex configurations with reduced qualification overhead. European distributors in Hamburg and Rotterdam stock inventory for aging vehicle parc maintenance.
- Tier-1 Manufacturers:Bosch, Continental, and Denso module houses in Karlsruhe, Hanover, and Kariya consolidate FPC sourcing into wire harness and sensor assembly contracts. Their specification leverage shapes laminate grade requirements.
- Distributors:Arrow and Avnet operations in Singapore and Hong Kong channel prototype volumes to design houses, though automotive qualification limits their addressable market.
Tier-1 Manufacturers hold the largest share; momentum sits with OEMs as direct sourcing contracts proliferate.
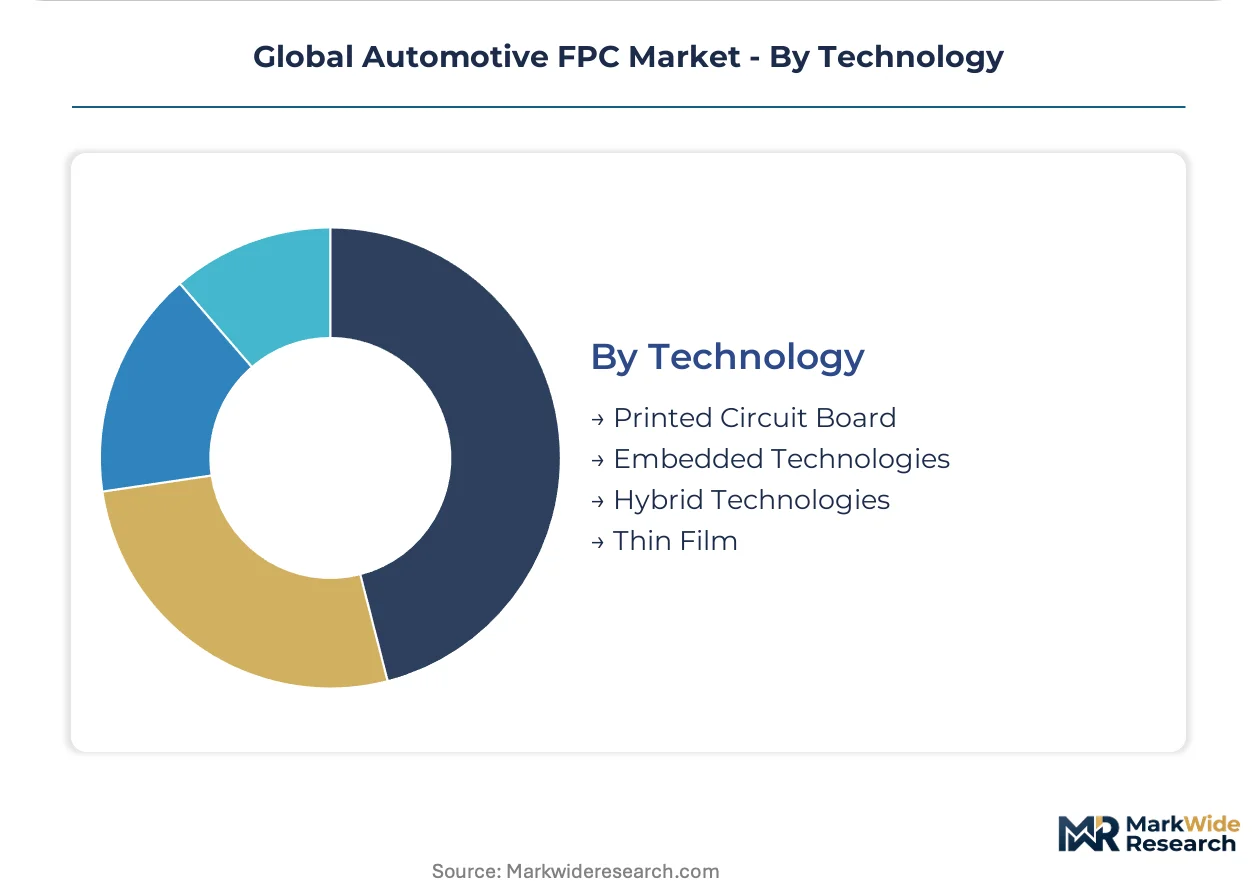
Technology:
Supply concentration in Taiwanese and Japanese substrate production governs which technology platforms achieve scale.
- Printed Circuit Board:Etched copper on polyimide film remains the baseline for automotive qualification. Nippon Mektron's integrated film operations in Japan and Taiwan anchor PCB-FPC substrate availability.
- Embedded Technologies:Chip-on-flex and die-attach configurations decompose separate component and substrate supply chains. South Korean battery management system producers in Incheon and Seoul accelerate embedded die adoption.
- Hybrid Technologies:Combinations of FPC with rigid PCB and connector systems serve complex module integration requirements. German OEMs specify hybrid architectures for zonal E/E domain controllers.
- Thin Film:Sputtered metal on flexible substrates enables ultra-lightweight sensor applications. Emerging transparent conductive oxide variants target capacitive touch surfaces in next-generation cockpits.
Printed Circuit Board holds the largest share; Embedded Technologies gain share fastest through battery pack integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in polyimide film and copper-clad laminates concentrate manufacturing advantage in East Asian production clusters. Germany and South Korea remain net importers of substrate materials while maintaining dense concentrations of automotive electronics assembly.
China
CATL and BYD procurement teams in Ningbo and Shenzhen drive rigid-flex specifications for cell monitoring ribbons. MIIT NEV certification protocols mandate thermal cycling performance standards that filter supplier qualification pools. The Yangtze River Delta manufacturing corridor concentrates domestic EV platform localization demand for HDI-flex expertise.
Germany
Volkswagen, BMW, and Mercedes-Benz technical centers in Munich and Stuttgart exercise direct specification control for flagship EV architectures. EU Green Deal carbon accounting rules pressure laminators to reformulate polyimide-to-copper bonding layers. Stuttgart and Munich battery pack manufacturers audit scope-three emissions from Taiwanese substrate suppliers.
Japan
Toyota and Honda engineering teams in Toyota City and Hiroshima specify rigid-FPC hybrids for instrument cluster consolidation. METI industrial policy supports captive polyimide film production for automotive-grade reliability. Nippon Mektron's integrated operations anchor substrate availability for multi-layer automotive grades.
South Korea
LG Energy Solution and Samsung SDI cell monitoring unit manufacturers in Incheon and Seoul accelerate chip-on-flex adoption. MFDS-equivalent automotive electronics standards govern battery management system interconnect specifications. Suwon and Pyeongtaek electronics houses drive multi-layer microvia tightening for 4D imaging radar deployments.
United States
Ford and GM battery engineering centers in Michigan and California specify FPC thermal management for domestic EV platform launches. EPA REACH-compliant flame retardant constraints limit adhesive chemistry options for European-bound vehicle programs. Detroit-area Tier-1 module houses consolidate FPC sourcing into wire harness assembly contracts.
Global Automotive FPC Market Vendor Landscape
Concentration sits with integrated polyimide film producers and roll-to-roll specialists possessing captive copper-clad laminate supply. The vendor base stratifies across three tiers: high-volume substrate-integrated fabricators, precision etching houses serving ADAS modules, and regional specialists capturing domestic EV platform localization. Strategic moves center on backward integration into film production and co-location partnerships near battery pack assembly hubs.
Among Taiwan and Japan-based fabricators, Nippon Mektron, Ltd. exemplifies the integrated-film archetype through polyimide operations spanning both markets. Zhen Ding Tech. Group anchors the high-volume substrate tier with massive capacity positioning. Shennan Circuits Company Limited occupies a specialist position serving domestic Chinese EV platforms with HDI-flex expertise.
| Leading Market Players |
|---|
| Compeq Manufacturing Co., Ltd. |
| Nan Ya PCB Co., Ltd. |
| Nippon Mektron, Ltd. |
| IBIDEN Co., Ltd. |
| Shennan Circuits Company Limited |
| Zhen Ding Tech. Group |
| Suzhou Dongshan Precision Manufacturing Co., Ltd. |
| TTM Technologies Inc. |
| Unimicron Technology Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between CATL, BYD, and Taiwanese substrate producers lock in multi-year polyimide film supply while freezing copper-clad laminate pricing bands, stripping spot-market volatility from qualified supplier relationships and compressing margin visibility for etching houses without backward integration.
Pricing Analysis
Industrial OEM buyers anchor a contract-heavy pricing structure that stratifies across automotive-grade certification tiers. Pricing separates AEC-Q200 qualified multi-layer configurations from commercial-grade flex circuits through thermal cycling test documentation and MIIT NEV protocol compliance. Cost compression in standard-grade polyester alternatives is intensifying because Chinese domestic brands prioritize cost over extended temperature ratings. Tier-1 module houses in Germany and South Korea exhibit lowest price sensitivity due to specification lock-in, while aftermarket distributors in Rotterdam and Hamburg face acute margin pressure from inventory carrying costs.
Supply Chain Analysis
Polyimide film production concentration in Japan and Taiwan underwrites substrate availability for automotive-grade FPC fabrication. Raw material flows draw from copper mining operations in Chile and Indonesia, polyimide resin synthesis in Aichi Prefecture, and rolled annealed copper foil processing in Kaohsiung. Single-source vulnerability sits with Nippon Mektron's integrated film operations spanning both markets. Distribution runs through direct procurement contracts between battery cell producers and FPC specialists, bypassing traditional wire harness intermediaries in China's Yangtze River Delta corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-drilled microvia capability scarcity concentrates margin capture among fabricators possessing precision etching equipment, leaving mid-scale houses exposed to equipment financing strain and extended qualification timelines.
For Market Incumbents: Compound defensive positioning through captive polyimide film production and co-location partnerships near Stuttgart and Munich battery pack assembly hubs. Threat exposure from embedded die packaging adoption by South Korean battery management system producers demands accelerated chip-on-flex R&D investment. Backward integration into copper-clad laminate supply remains the critical margin defense lever against copper price volatility. For New Entrants and Emerging Players: Differentiate on HDI-flex expertise serving domestic Chinese EV platforms subject to GB/T automotive electronics standards. White-space concentration sits with rigid-flex configurations for cell monitoring ribbons in Ningde and Shenzhen manufacturing corridors. Go-to-market traction requires MIIT NEV certification protocol qualification as table stakes for CATL and BYD procurement consideration. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated substrate-fabricator archetypes over standalone etching houses. Long-term viability hinges on 800V architecture migration creating specification white space for high-voltage insulation designs. Acquisition targeting should prioritize firms with captive copper-clad laminate supply and established automotive-grade reliability testing infrastructure. Signal to monitor: IEC 60664 insulation coordination requirement evolution for 800V battery pack applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Film | Nippon Mektron's captive supply anchors margin capture across multi-layer automotive grades. |
| Co-location Partnership Near Battery Hubs | Volkswagen and BMW technical centers mandate supplier proximity to Stuttgart pack assembly. |
| Chip-on-Flex Packaging Investment | LG Energy Solution and Samsung SDI accelerate embedded die adoption for cell monitoring. |
| MIIT NEV Certification Qualification | GB/T thermal cycling standards filter supplier pools for Yangtze River Delta EV platforms. |
| REACH-Compliant Adhesive Reformulation | ECHA flame retardant restrictions force laminator chemistry changes for European-bound vehicles. |
Methodological Framework
The analysis maps rigid-flex, multi-layer, and embedded die sub-sectors, each validated through procurement directors at CATL and BYD, Tier-1 module engineering leads at Bosch and Denso, and polyimide film operations managers in Japan and Taiwan. Secondary triangulation draws from MIIT NEV certification protocol documentation, EU Green Deal carbon accounting rule filings, IEC 60664 insulation coordination drafts, and vehicle production databases. Bottom-up segment sizing and top-down macro constraint checks ensure cross-validation consistency.
Output consistency was verified against external benchmarks including customs data for copper-clad laminate trade flows and automotive electronics import records. The analytical framework models across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derive from segment-level volume build-ups incorporating battery pack FPC penetration assumptions and ADAS module proliferation curves. Key inputs include OEM platform launch timelines and MIIT NEV certification qualification rates.
The analysis sits within stated boundaries; outcomes outside sustained battery electric vehicle platform rollout and 800V architecture migration would require recalibration. Forecasts reflect documented assumptions around polyimide film supply concentration and copper price trajectory stability. Specific risk factors capable of revising projections include ECHA adhesive chemistry restriction tightening, single-source substrate supply disruption, and extended automotive-grade reliability testing timeline elongation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market