
 Automotive Fuse Market | 2026-2036
Automotive Fuse Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuse Market Analysis
The gap between premium smart fuse portfolios and commodity blade fuse supply is expanding across automotive electrical systems. Littelfuse Inc. leverages its vertically integrated semiconductor fuse production to capture high-voltage EV contracts. Eaton Corporation plc anchors its position through broad distribution reach into commercial vehicle OEM channels. Sensata Technologies Inc. differentiates via integrated sensing and protection modules that combine fuse function with real-time diagnostics.
An automotive fuse is a sacrificial overcurrent protection device comprising a metal element that melts at a calibrated temperature to interrupt fault currents, typically rated from 32V to 800V DC depending on vehicle architecture. Its primary purpose is to prevent thermal runaway, wire harness damage, and fire propagation in increasingly dense automotive electrical networks. Blade fuses still dominate volume shipments for internal combustion and entry electrified vehicles, yet smart fuses are capturing margin pools as OEMs demand self-diagnostic and resettable functionality. Safety system applications impose the most stringent trip-time tolerances, creating specification premiums that commodity suppliers cannot meet.
NHTSA in the United States, UNECE WP.29 in Europe, and China's MIIT collectively shape fuse standards through vehicle-level functional safety mandates and high-voltage system regulations. These frameworks force suppliers to validate fuses across temperature cycling, vibration, and short-circuit profiles that exceed legacy automotive grades. Stakeholders must decide whether to absorb the capital intensity of smart fuse development or cede that tier to integrated electronics specialists.
Market Dynamics
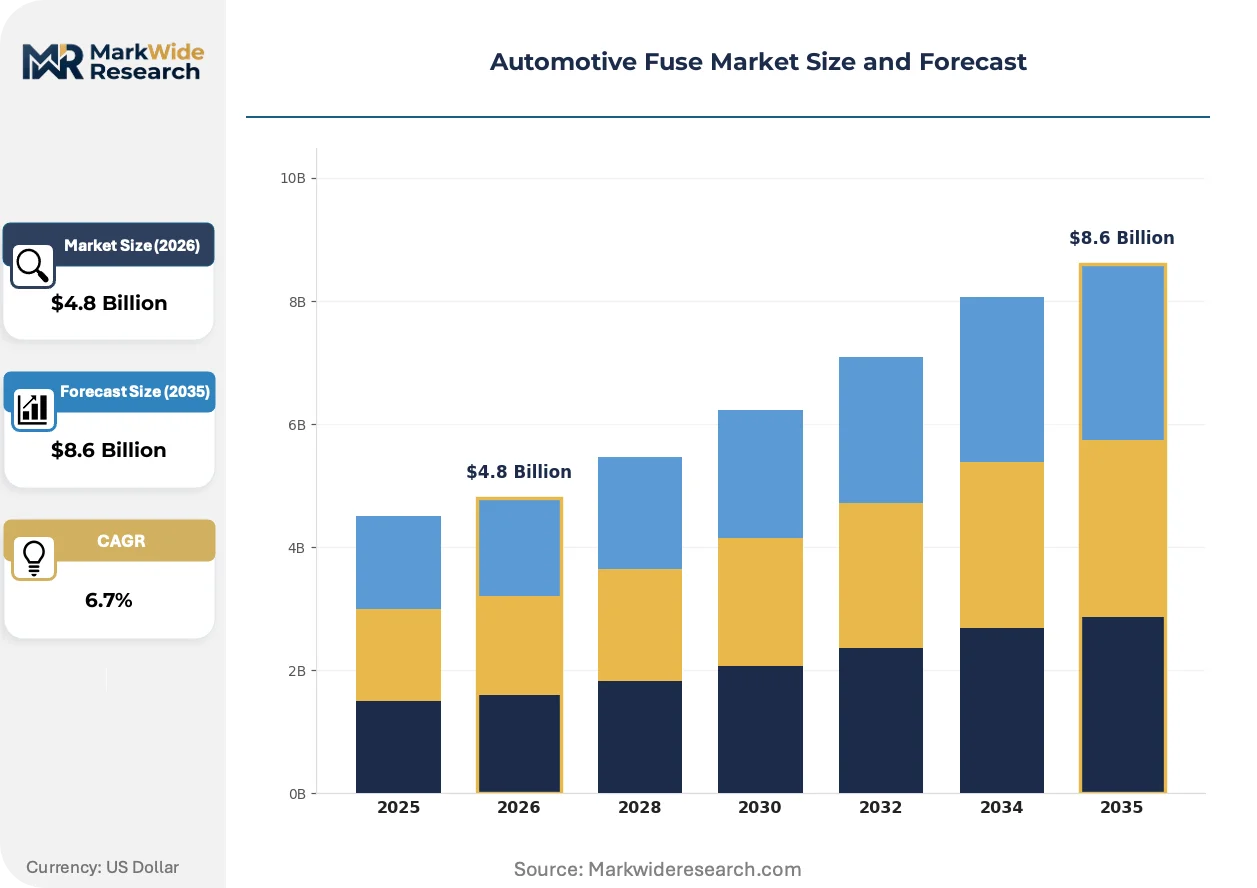
The automotive fuse market is undergoing fundamental restructuring as 800V EV architectures displace 400V systems, forcing suppliers to recalibrate thermal management and arc-quenching capabilities across their product portfolios.
Growth Catalysts
- UN ECE WP.29:Functional safety mandates for high-voltage systems are compelling OEMs to specify fuses with validated fault-clearance times under thermal runaway conditions.
- Silicon carbide inverters:Wide-bandgap semiconductors generate faster current transients, requiring fuse elements with sub-millisecond response characteristics.
- China:MIIT production quotas for NEVs are concentrating demand for 750V-rated fuses in battery pack and charging infrastructure applications.
Market Restraints
- Silver price volatility:Fuse element alloys depend on precious metal inputs, compressing margins when commodity markets spike.
- Single-source ceramic substrates:High-temperature fuse bodies rely on alumina suppliers concentrated in East Asia, creating geographic vulnerability.
- Technical limitation:Conventional melting-element designs cannot self-reset, forcing trade-offs between protection speed and serviceability in sealed battery packs.
Strategic Opportunities
- India:PLI scheme incentives for domestic EV manufacturing are opening procurement channels for localized fuse production.
- Bidirectional charging:Vehicle-to-grid applications require fuses rated for sustained AC current flow in reverse direction.
- ISO 26262:ASIL-D compliance certification creates premium positioning for suppliers validating fuses within functional safety chains.
Industry Challenges
- High-voltage safety engineering talent:OEMs and tier-ones compete for specialists capable of designing arc containment for 800V fault conditions.
- Test equipment capex:Validating fuses to AEC-Q200 and LV 123 standards requires investment in short-circuit laboratories capable of megawatt-level power dissipation.
- Legacy 12V integration:Smart fuse architectures must communicate with decades-old LIN bus protocols without compromising diagnostic latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuse Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Fuses, Glass Fuses, Ceramic Fuses, PTC Fuses Application: Lighting Systems, Power Distribution, Infotainment Systems, Safety Systems End User: OEMs, Aftermarket Retailers, Service Centers, Fleet Operators Technology: Traditional Fuses, Smart Fuses, Fuse Links, Resettable Fuses |
| Companies Covered | AEM Components Inc., MTA Spa, Littelfuse Inc., Sensata Technologies Inc., SCHURTER Holding AG, Eaton Corporation plc, Pacific Engineering Corporation, SIBA GmbH, Mersen S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuse Market Emerging Trajectories
Semiconductor-enabled protection logic is displacing passive thermal elements across premium vehicle segments. This convergence of power electronics and sensing is compressing the traditional fuse-relay hierarchy into integrated solid-state modules.
Pyrofuse technology is integrating explosive disconnect mechanisms with current-sensing electronics to sever battery pack circuits within microseconds of collision detection. German and Chinese OEMs are adopting these systems in flagship EV platforms. The technology is integrating arcless interruption capability that conventional melting elements cannot achieve, enabling higher voltage ratings without contact erosion.
REACH substance restrictions on lead and cadmium are forcing reformulation of fuse element alloys and ceramic body compositions. European suppliers face accelerated material qualification timelines to maintain CE marking compliance. High-voltage commercial vehicles bear the heaviest compliance burden, as their fuse ratings require larger material volumes subject to substance thresholds.
Fleet operators are consolidating fuse procurement through direct contracts with tier-two component manufacturers, bypassing traditional distribution channels. This disintermediation pressures distributors to add value through inventory financing and technical support. The pattern is most pronounced in North American commercial vehicle segments, where large fleet owners negotiate specification standardization across multiple OEM platforms.
Automotive Fuse Market Segmentation
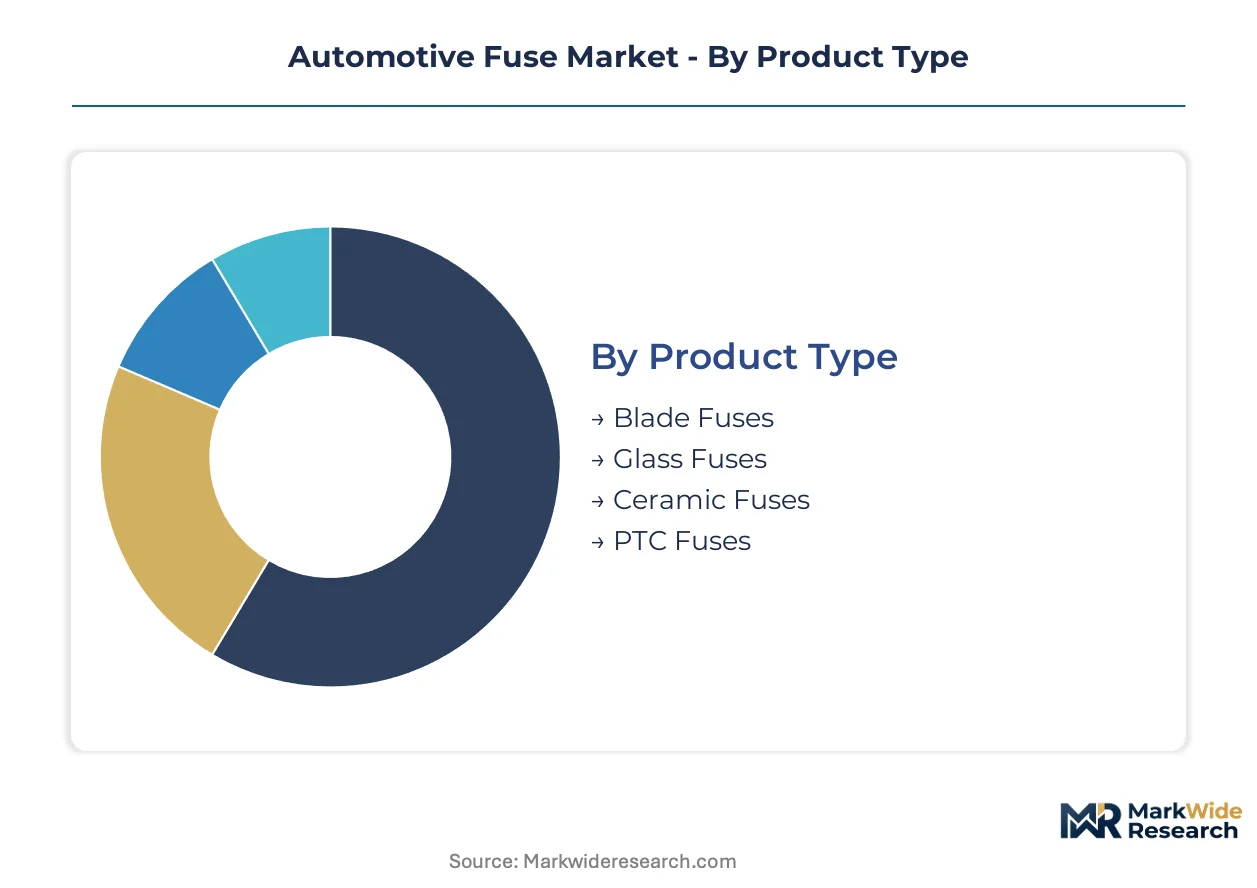
Automotive fuse segmentation reveals how protection requirements diverge across electrical architectures. Voltage ratings, trip characteristics, and diagnostic capabilities create distinct procurement patterns that suppliers must address through specialized product portfolios.
Product Type:
Buyers differentiate by thermal tolerance, arc-quenching performance, and integration density within constrained packaging volumes.
- Blade Fuses:Polyamide-bodied plug-in devices with zinc or silver-alloy elements dominate 12V and 48V circuits in internal combustion and mild-hybrid vehicles. Chinese and German OEMs specify these for high-volume power distribution modules where cost sensitivity exceeds diagnostic requirements.
- PTC Fuses:Polymeric positive temperature coefficient devices self-reset upon cooling, eliminating service access needs in sealed battery pack enclosures. MIIT production quotas for NEVs in China are accelerating procurement for 750V-rated PTC arrays in cell monitoring unit protection.
- Glass Fuses:Cylindrical silica enclosures with calibrated wire elements serve legacy accessory circuits and aftermarket replacement demand.
- Ceramic Fuses:Alumina-bodied high-rupture designs withstand thermal shock in engine compartment applications.
Blade fuses lead volumes today; PTC fuses are gaining share fastest.
Application:
Functional safety requirements and voltage exposure determine specification stringency across vehicle electrical domains.
- Safety Systems:Airbag deployment circuits, anti-lock braking, and steer-by-wire demand sub-millisecond trip tolerances under ISO 26262 ASIL-D constraints. German OEMs validate these through KBA-certified test protocols for arc containment.
- Power Distribution:Battery junction boxes and DC-DC converters require coordinated fuse coordination across 400V and 800V architectures. NHTSA high-voltage system mandates in the United States are forcing redesigns of pyrofuse integration with collision detection electronics.
- Lighting Systems:LED driver protection emphasizes inrush current tolerance and compact form factors for headlamp assemblies.
- Infotainment Systems:Low-voltage signal protection prioritizes resettable functionality to minimize dashboard service events.
Power distribution commands the largest procurement spend; safety systems extract the highest unit margins.
End User:
Volume scale and technical integration depth separate procurement behaviors across the value chain.
- OEMs:Tier-one suppliers negotiate multi-year fuse supply agreements tied to platform electrical architecture roadmaps. Direct sourcing of smart fuse modules bypasses traditional distribution for high-voltage EV programs.
- Fleet Operators:North American commercial vehicle fleets standardize specifications across multiple OEM platforms, consolidating procurement through direct tier-two contracts with inventory financing requirements.
- Aftermarket Retailers:Multi-brand blade fuse assortments serve aging vehicle parc maintenance through automotive parts distributors.
- Service Centers:Diagnostic-equipped facilities replace fuses within warranty repair workflows.
OEMs dominate absolute volume; fleet operators are expanding procurement fastest through disintermediation.
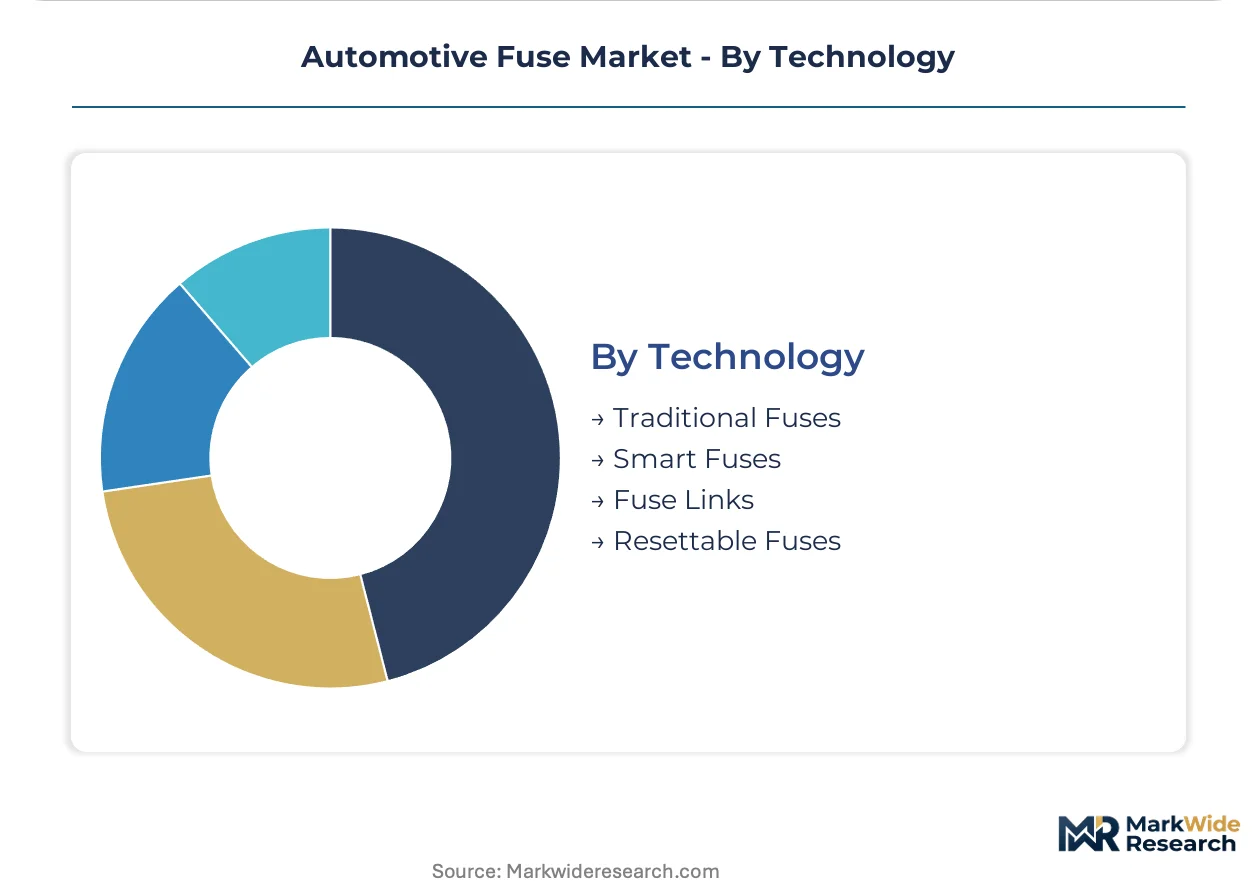
Technology:
Passive versus active protection architectures define the competitive technology frontier.
- Smart Fuses:Semiconductor-enabled modules integrate current sensing, diagnostic communication, and solid-state interruption. Littelfuse and Sensata are capturing premium positioning as OEMs demand LIN bus reporting and self-reset capability for sealed battery enclosures.
- Traditional Fuses:Melting-element designs persist in cost-optimized 12V circuits where diagnostic latency requirements remain minimal. REACH substance restrictions on lead and cadmium are forcing European suppliers to reformulate element alloys.
- Fuse Links:Bolt-down high-current designs serve commercial vehicle starter and alternator circuits.
- Resettable Fuses:Polymeric and bimetallic self-resetting devices reduce warranty exposure in inaccessible harness locations.
Traditional fuses anchor current volume; smart fuses are climbing the fastest toward majority margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium fuse engineering for 800V EV architectures, while China scales volume production for domestic NEV quotas. The United States, Japan, and India complete the five-country demand map through distinct regulatory and industrial pathways.
China
MIIT production quotas for NEVs are pulling 750V-rated fuse demand into battery pack and charging infrastructure applications. GB standards for high-voltage safety mandate validated fault-clearance times under thermal runaway conditions. The Yangtze River Delta cluster around Shanghai hosts concentrated fuse manufacturing for both domestic OEMs and export markets.
Germany
KBA-certified test protocols for arc containment are shaping procurement specifications across European OEM platforms. REACH substance restrictions on lead and cadmium are accelerating alloy reformulation timelines for fuse element suppliers. The Baden-Württemberg industrial corridor anchors pyrofuse development for flagship EV platforms from Stuttgart-based manufacturers.
United States
NHTSA mandates on high-voltage system protection are forcing redesigns of fuse integration with collision detection electronics. The IRA domestic content provisions are incentivizing localized fuse production for EV supply chains. Michigan and Ohio manufacturing clusters are expanding short-circuit laboratory capacity to meet AEC-Q200 validation requirements.
Japan
METI technology roadmaps for solid-state batteries are extending fuse voltage ratings toward next-generation cell chemistries. JIS standards for automotive electrical components impose stringent vibration and temperature cycling requirements. The Nagoya-Chubu region maintains concentrated fuse engineering for Toyota and Honda electrification programs.
India
PLI scheme incentives for domestic EV manufacturing are opening procurement channels for localized fuse production. BIS certification requirements for automotive electrical safety are tightening import substitution timelines. The Tamil Nadu-Gujarat manufacturing belt is attracting tier-two fuse suppliers to serve Maruti Suzuki and Tata Motors electrification roadmaps.
Automotive Fuse Market Vendor Landscape
Top-tier vendors anchor premium smart fuse development, while commodity blade fuse suppliers compete on scale and distribution reach. The vendor base stratifies across three tiers: integrated electronics specialists with semiconductor capabilities, diversified electrical component conglomerates with broad OEM relationships, and regional specialists serving aftermarket and commercial vehicle channels. Dominant competitive moves include backward integration into ceramic substrate production and strategic partnerships with silicon carbide inverter manufacturers.
Within the integrated protection tier, Littelfuse Inc. and Sensata Technologies Inc. exemplify the convergence of fuse function with real-time diagnostics and LIN bus communication. Eaton Corporation plc occupies a position among diversified electrical component suppliers leveraging distribution scale into commercial vehicle OEM channels. These three companies represent distinct archetypes: semiconductor-enabled smart fuse integration, sensing-module convergence, and broad-reach electrical systems distribution.
| Leading Market Players |
|---|
| AEM Components Inc. |
| MTA Spa |
| Littelfuse Inc. |
| Sensata Technologies Inc. |
| SCHURTER Holding AG |
| Eaton Corporation plc |
| Pacific Engineering Corporation |
| SIBA GmbH |
| Mersen S.A. |
| Others |
Supply Flow & Price Mechanics
Silver alloy element costs cascade through automotive fuse pricing tiers, with precious metal volatility compressing margins for commodity blade fuse suppliers while smart fuse manufacturers absorb input spikes through semiconductor-enabled premium positioning. NHTSA and UNECE certification requirements add fixed compliance costs that stratify procurement across OEM direct sourcing and aftermarket distribution channels.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard blade fuses, forcing European and North American suppliers toward ASIL-D certified premium tiers. Three-tier pricing structure across premium smart fuses, certified standard fuses, and economy blade fuses separates OEM direct contracts from fleet procurement and aftermarket retail. Cost compression in commodity 12V segments intensifies because Chinese producers leverage integrated ceramic substrate manufacturing. Fleet operators exhibit highest price sensitivity through consolidated tier-two direct sourcing, while German OEMs prioritize validated fault-clearance performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East Asian alumina ceramic substrate suppliers concentrated in China and Japan, constraining high-temperature fuse body production globally. Raw material dependencies span silver-copper element alloys, polyamide molding compounds, and semiconductor-grade silicon for smart fuse logic. Geographic supply concentration in China, Germany, and the United States anchors pyrofuse development and 800V validation capacity. Tariff exposure on ceramic substrates and precious metals threatens margin stability for non-integrated suppliers. Distribution runs through tier-one automotive electrical suppliers into OEM battery junction box programs, bypassing traditional channels for high-voltage EV architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive fuse demand compounds through regulatory ratcheting, with UN ECE WP.29 functional safety mandates and NHTSA high-voltage system rules creating non-discretionary procurement obligations across OEM platforms.
For Market Incumbents: Lock in pyrofuse development partnerships with German and Chinese flagship EV programs before silicon carbide inverter adoption accelerates sub-millisecond response requirements. Backward integration into ceramic substrate production reduces East Asian supply vulnerability. Defensive consolidation of short-circuit laboratory capacity in Michigan and Ohio manufacturing clusters protects AEC-Q200 validation positioning against emerging test equipment specialists. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for localized 750V fuse production serving Maruti Suzuki and Tata Motors electrification roadmaps. Target sealed battery pack PTC fuse arrays where self-reset functionality eliminates service access needs. Pursue direct fleet procurement contracts in North American commercial vehicle segments, bypassing distributor markups through inventory financing capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where semiconductor-enabled protection logic converges with legacy fuse manufacturing, creating acquisition opportunities for integrated electronics specialists. Five-to-ten year viability favors suppliers with validated ASIL-D certification pipelines and captive ceramic substrate supply. Watch for inflection when 800V platform adoption crosses threshold penetration in German and Chinese OEM lineups, triggering pyrofuse specification cascade.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrofuse Technology Integration | Microsecond arcless interruption meets German KBA collision detection requirements for 800V battery packs. |
| Ceramic Substrate Backward Integration | Captive alumina supply secures production continuity against East Asian geographic concentration risks. |
| ASIL-D Certification Investment | ISO 26262 validation unlocks premium positioning in safety system procurement from Stuttgart-based OEMs. |
| India PLI Manufacturing Footprint | Localized production captures BIS-certified procurement from domestic EV quotas under MIIT-aligned schemes. |
| Silicon Carbide Inverter Partnership | Sub-millisecond fuse response coordination with wide-bandgap semiconductors addresses thermal runaway transients. |
Methodological Framework
Multiple input streams — primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, and aftermarket distribution heads; secondary validation through NHTSA regulatory filings, UNECE WP.29 documentation, and vehicle production databases; plus customs records on silver alloy and ceramic substrate trade flows — were reconciled through bottom-up segment sizing and top-down market cross-checks across the projection horizon.
Historical shipment data was cross-referenced against expert panel inputs from fuse engineering specialists and high-voltage safety consultants to anchor growth assumptions. Segmentation dimensions modeled include voltage rating tier, propulsion architecture, application safety criticality, and regional regulatory cluster. CAGRs were derived from production volume trajectories weighted by content-per-vehicle escalations in 400V-to-800V transitions and smart fuse penetration curves.
Revisions become necessary when MIIT NEV quota adjustments, REACH substance restriction expansions, or silicon carbide inverter adoption curves materialize differently than baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market