
 Automotive AR Head-Up Display Market | 2026-2036
Automotive AR Head-Up Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive AR Head-Up Display Market Outlook
The performance gap between premium embedded AR HUD systems and retrofitted commodity displays is broadening. Panasonic Holdings Corporation leverages its display panel verticality to sustain cost advantages in high-brightness projector modules. Continental AG anchors European OEM supply chains through dedicated engineering centers in Stuttgart and Ingolstadt. Nippon Seiki Co., Ltd. dominates Japanese domestic fitment rates through long-term contracts with Toyota and Honda.
Automotive AR head-up displays overlay real-time navigation, hazard warnings, and vehicle telemetry directly within the driver's forward field of view using combiner optics or windshield projection at focal distances exceeding two meters. Embedded systems command the dominant revenue share due to thermal management integration and calibration complexity that aftermarket providers cannot replicate. Projection technology leads unit shipments while holographic displays capture emerging interest for depth-perception enhancement in premium segments. OEMs represent the most concentrated end-user channel, with fleet operators representing a nascent but structurally important growth vector as commercial vehicle safety mandates tighten.
FDA guidelines on driver distraction metrics influence HUD field-of-view specifications for vehicles sold in the United States, while EU Green Deal vehicle safety requirements under the General Safety Regulation mandate intelligent speed assistance integration that AR HUDs natively support. China's MIIT issues GB standards for in-vehicle display luminance that directly shape export-bound product design cycles. Stakeholders must monitor diverging regional compliance timelines to avoid platform fragmentation that would erode scale economics across product generations.
Market Dynamics
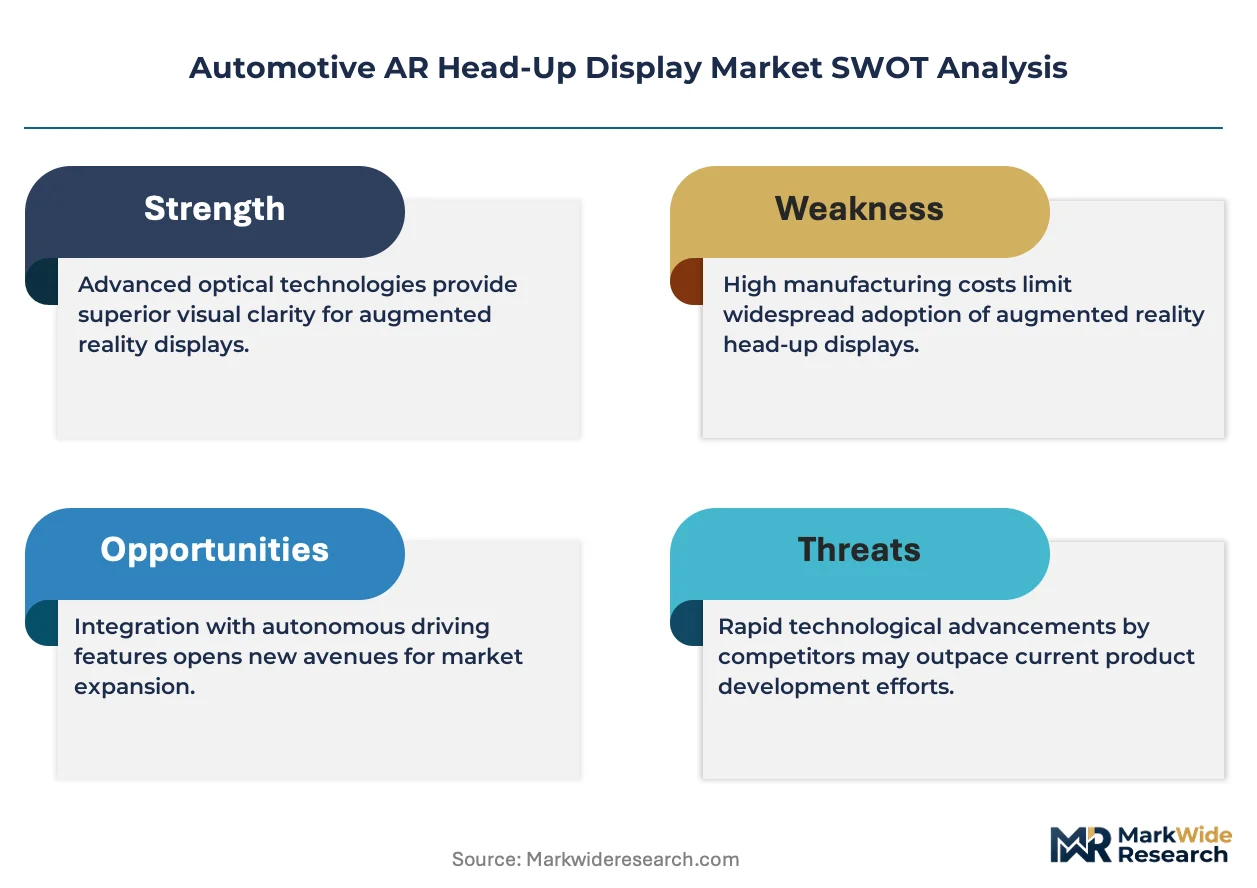
Windshield projection technology is absorbing capital allocation previously directed toward combiner-based systems, as thermal integration requirements and calibration precision reshape supplier capability thresholds.
Growth Catalysts
- EU General Safety Regulation:Intelligent speed assistance mandates create direct demand pull for AR HUD integration in vehicles sold across European markets.
- Holographic waveguide optics:Depth-perception enhancement capabilities are expanding addressable premium segments beyond conventional navigation overlays.
- German automotive corridor:Co-location of Tier 1 engineering centers with OEM R&D facilities compresses development cycles and accelerates platform adoption.
Market Restraints
- High-brightness projector module costs:DLP and laser phosphor component volatility constrains margin expansion for mid-tier system integrators.
- Japanese domestic supplier concentration:Long-term contractual lock-in between Nippon Seiki and domestic OEMs limits market entry for European and North American competitors.
- Windshield optical distortion:Lamination tolerances and wedge-angle calibration complexity create yield losses that aftermarket providers cannot economically resolve.
Strategic Opportunities
- Commercial vehicle fleet operators:Tightening safety mandates for heavy-duty trucks in North America and Europe create a structurally distinct demand channel with higher unit economics.
- China MIIT GB standard harmonization:Export-bound luminance compliance requirements are forcing design standardization that benefits scaled manufacturers with multi-market platforms.
- LiDAR fusion interfaces:Convergence of augmented reality overlays with real-time environmental sensing is opening premium positioning for integrated perception-stack suppliers.
Industry Challenges
- Optomechanical engineering talent scarcity:Specialized expertise in freeform mirror design and waveguide fabrication concentrates within Stuttgart and Nagoya metro areas, constraining geographic expansion of development centers.
- Multi-homologation certification timelines:Divergent FDA driver distraction metrics, EU GSR compliance pathways, and China MIIT testing protocols force parallel validation tracks that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive AR Head-Up Display Market |
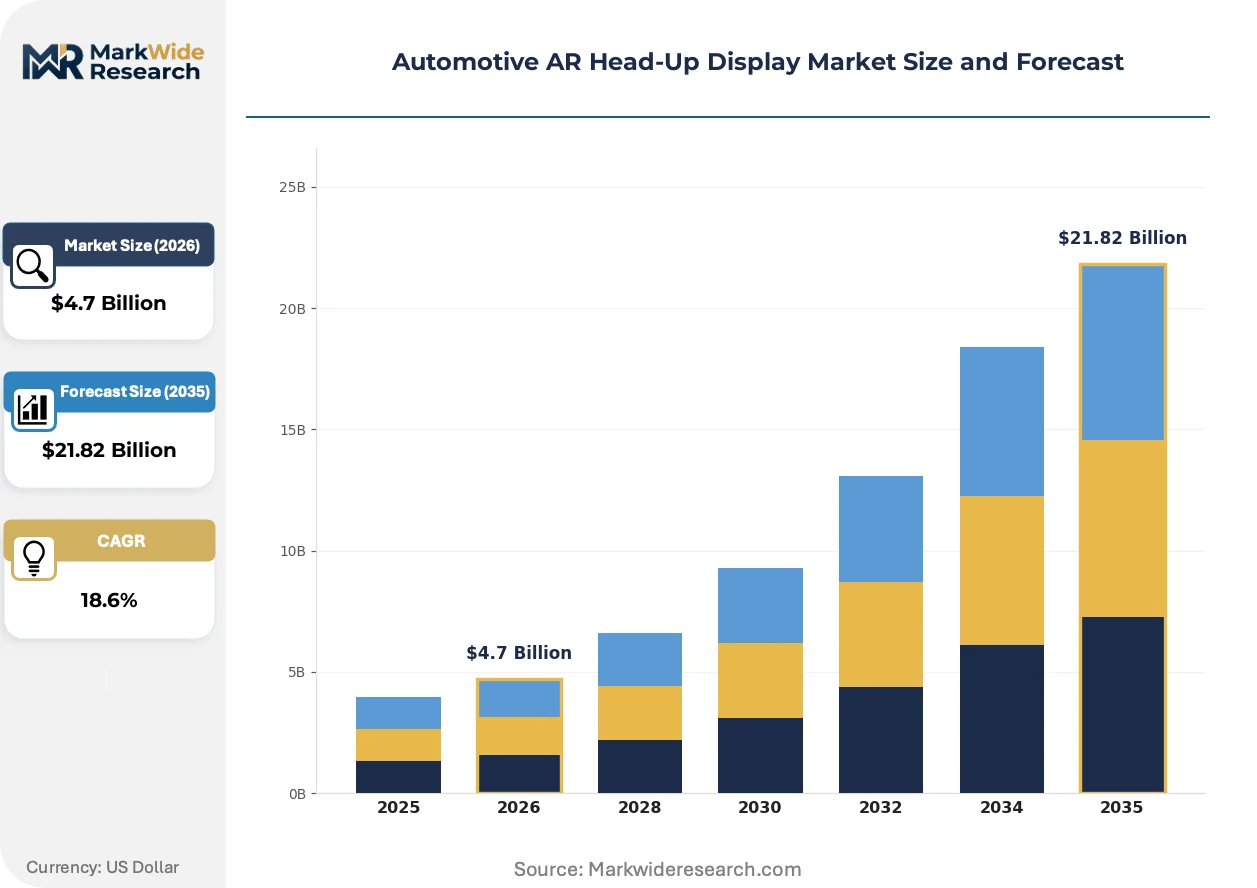
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Retrofitted Displays, Smart Glasses, Transparent OLEDs Use Case: Navigation Assistance, Safety Alerts, Driver Information, Entertainment Features Technology: Augmented Reality, Projection Technology, 3D Mapping, Holographic Displays End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers |
| Companies Covered | Panasonic Holdings Corporation, Nippon Seiki Co., Ltd., Continental AG, Robert Bosch GmbH, Valeo, DENSO Corporation, Harman International Industries, Envisics Ltd., Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive AR Head-Up Display Market Strategic Shifts
Active matrix LED and laser scanning projection architectures are redefining brightness thresholds and color gamut specifications, compressing the performance gap between embedded and aftermarket display categories.
Waveguide-based holographic combiners are absorbing development resources from conventional mirror-based projection systems. Premium German and Japanese OEMs are adopting these architectures for flagship vehicle launches scheduled across 2026-2028 model years. The technology is absorbing margin pressure from conventional DLP modules by enabling thinner dashboard packaging and reduced optical path complexity.
The EU General Safety Regulation's intelligent speed assistance mandate is forcing HUD field-of-view expansion to accommodate regulatory information display requirements. Tier 1 suppliers are redesigning optical engines to meet minimum angular coverage specifications without compromising ergonomic sightline constraints. Commercial vehicle segments in Germany and France are experiencing the most acute compliance-driven procurement acceleration.
Fleet procurement is consolidating around integrated safety-stack contracts that bundle AR HUD hardware with ADAS software licensing. Heavy-duty truck operators in North America are displacing standalone aftermarket displays with factory-embedded systems to satisfy insurer risk-adjustment protocols. This pattern is most visible across long-haul logistics corridors linking Detroit to Dallas-Fort Worth.
Automotive AR Head-Up Display Market Segmentation
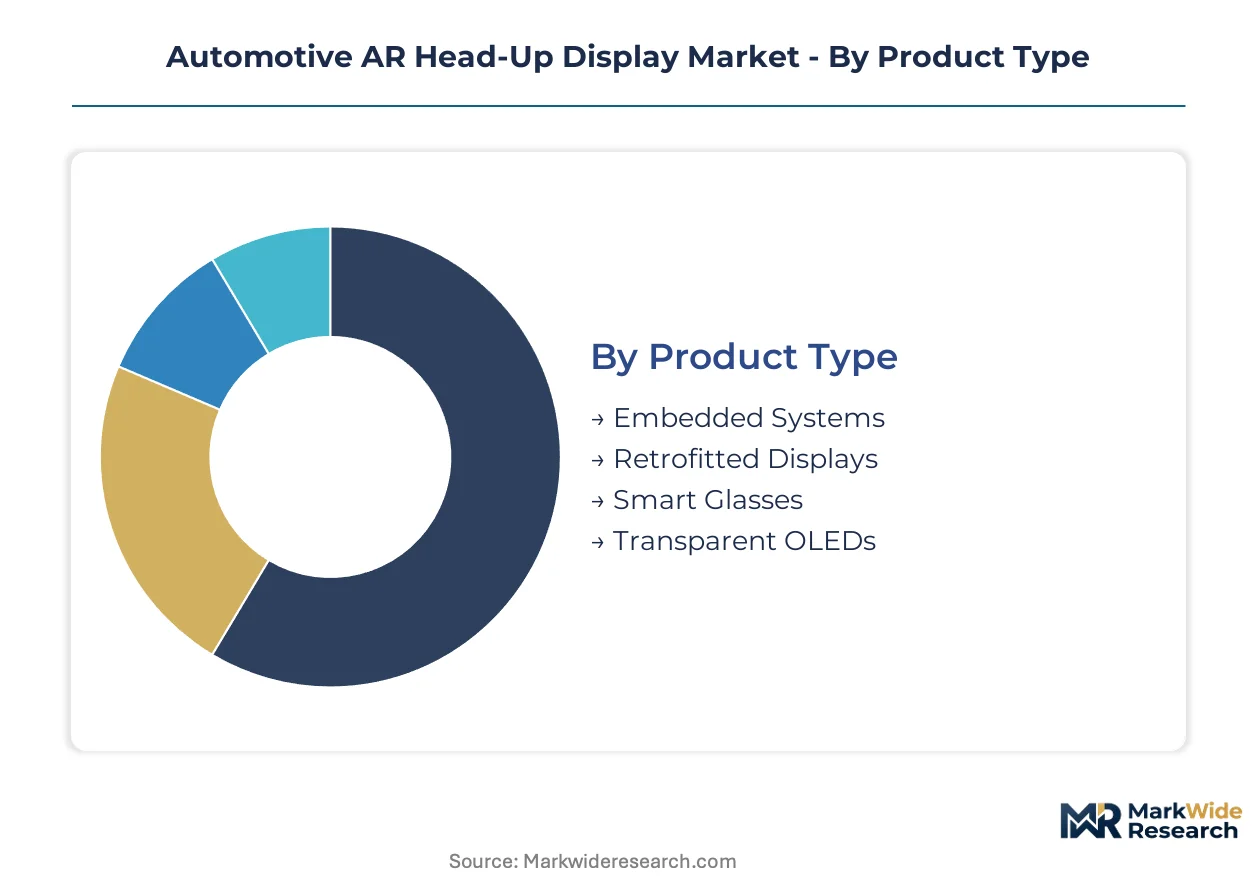
Automotive AR HUD segmentation reveals how certification burdens and thermal integration requirements concentrate value capture. Product architecture and end-user channel fundamentally determine which suppliers can meet homologation standards across FDA, EU GSR, and China MIIT jurisdictions.
Product Type:
EU General Safety Regulation intelligent speed assistance mandates and FDA driver distraction metrics impose divergent testing protocols on each product architecture, fragmenting development resource allocation.
- Embedded Systems:Factory-integrated units with dedicated thermal management and windshield-integrated projection optics. Demand clusters in German premium passenger vehicle manufacturing where OEMs mandate calibration precision exceeding aftermarket capabilities. EU GSR compliance timelines accelerate procurement from Stuttgart and Ingolstadt engineering corridors.
- Retrofitted Displays:Aftermarket combiner-based units attaching to existing dashboard surfaces. Japanese domestic market penetration faces structural constraints from Nippon Seiki's long-term OEM contracts limiting independent channel development. Price positioning targets individual consumers in markets without embedded system availability.
- Smart Glasses:Wearable AR displays supplementing or replacing fixed HUD installations. Niche adoption concentrates among fleet operators testing pilot programs in North American long-haul logistics corridors.
- Transparent OLEDs:Emerging windshield-embedded display substrates enabling full-windshield information overlay. Development partnerships between Korean panel manufacturers and German Tier 1 suppliers drive prototype deployment.
Leading the category by volume: Embedded Systems. Growing fastest: Transparent OLEDs.
Use Case:
Functional application determines field-of-view specifications and luminance thresholds that shape hardware cost structures across premium and standard tiers.
- Navigation Assistance:Real-time route guidance with turn-by-turn overlay projection. German automotive corridor OEMs specify minimum angular coverage to satisfy EU GSR intelligent speed assistance display requirements.
- Safety Alerts:Hazard warnings and collision avoidance cues requiring sub-100ms latency. Heavy-duty truck fleet operators in North America prioritize this function for insurer risk-adjustment protocol compliance.
- Driver Information:Vehicle telemetry including speed, fuel level, and battery status. Standard fitment across Japanese domestic market vehicles through Nippon Seiki's Toyota and Honda contracts.
- Entertainment Features:Passenger-visible media and connectivity interfaces. Regulatory constraints from FDA distraction metrics limit deployment in US-bound vehicles.
Dominant by procurement volume: Navigation Assistance. Expanding most quickly: Safety Alerts.
Technology:
Optical architecture selection determines supplier capability thresholds and manufacturing location concentration.
- Augmented Reality:Spatially registered overlays aligning virtual information with physical road geometry. Premium German OEM flagship launches anchor demand through 2026-2028 model year cycles.
- Projection Technology:DLP and laser phosphor-based image generation dominating current unit shipments. Panasonic's display panel verticality sustains cost advantages in high-brightness module production.
- 3D Mapping:Depth-perception enhancement through stereoscopic or varifocal display techniques. Holographic waveguide development concentrates in Stuttgart and Nagoya metro area engineering clusters.
- Holographic Displays:Waveguide-based combiners enabling thinner dashboard packaging. Absorbing capital allocation from conventional mirror systems as premium OEMs adopt for flagship vehicles.
Highest volume technology: Projection Technology. Steepest expansion trajectory: Holographic Displays.
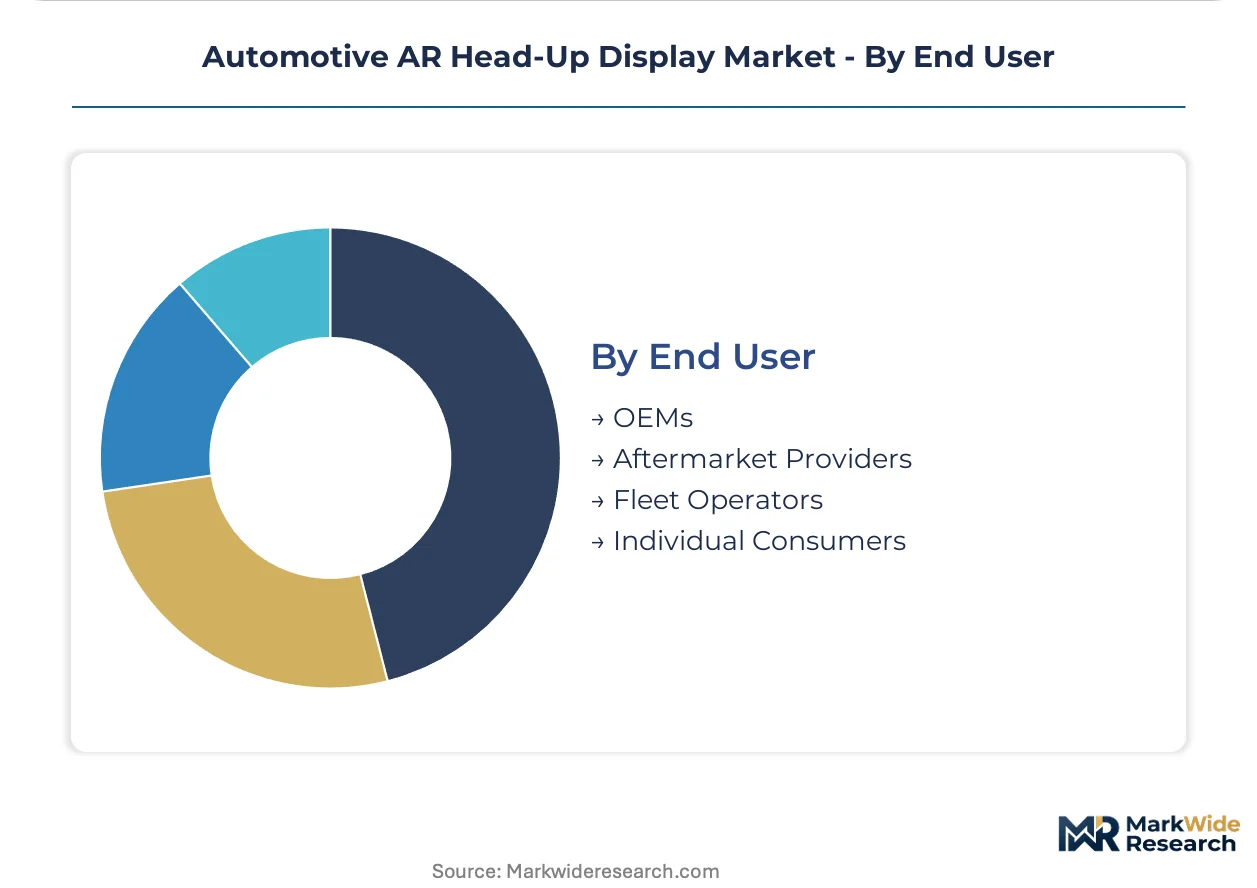
End User:
Channel structure dictates margin capture and contract duration, with fleet procurement consolidating around integrated safety-stack bundles.
- OEMs:Original equipment manufacturers specifying factory-embedded systems through multi-year platform contracts. Continental AG anchors European supply chains through dedicated engineering center co-location.
- Aftermarket Providers:Independent distributors serving vehicle owners without factory HUD options. Yield losses from windshield optical distortion calibration complexity constrain viable geographic markets.
- Fleet Operators:Commercial vehicle owners procuring embedded systems for regulatory compliance and insurance optimization. North American heavy-duty truck corridors show fastest adoption acceleration.
- Individual Consumers:Retail purchasers of retrofitted displays. Price sensitivity and installation complexity limit addressable market relative to embedded alternatives.
Revenue concentration leader: OEMs. Gaining share fastest: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the global Automotive AR Head-Up Display Market through its dense concentration of Tier 1 engineering centers and OEM headquarters. The German automotive corridor generates disproportionate procurement volume as embedded system mandates tighten across European and export markets.
United States
Heavy-duty truck fleet operators across the Detroit-to-Dallas-Fort Worth logistics corridor are accelerating embedded AR HUD procurement to satisfy insurer risk-adjustment protocols. FDA driver distraction metrics shape field-of-view specifications for vehicles sold domestically. Michigan-based engineering clusters concentrate ADAS-HUD integration development for North American OEM platforms.
Germany
EU General Safety Regulation intelligent speed assistance mandates create direct regulatory pull for windshield projection systems across premium passenger vehicle lines. Stuttgart and Ingolstadt host co-located Tier 1 engineering centers that compress OEM development cycles. Continental AG anchors European supply chains through dedicated facilities in these metro areas.
Japan
Long-term contractual lock-in between Nippon Seiki and domestic OEMs sustains near-complete fitment penetration across Toyota and Honda vehicle lines. METI industrial policy supports display technology advancement through targeted R&D consortia. Nagoya metro area engineering clusters concentrate holographic waveguide development for 2026-2028 flagship launches.
China
MIIT GB standards for in-vehicle display luminance force design standardization among export-bound manufacturers. Yangtze River Delta panel producers partner with German Tier 1 suppliers on transparent OLED windshield prototypes. Domestic OEM procurement concentrates in Shanghai-Suzhou corridor engineering centers serving both local and export platforms.
South Korea
Display panel verticality sustains cost advantages in high-brightness module production for global OEM supply chains. Seoul Capital Area engineering centers develop active matrix LED architectures redefining brightness thresholds. Korean manufacturers supply projection components to German and Japanese Tier 1 integrators under multi-year platform contracts.
Automotive AR Head-Up Display Market Competitive Environment
Premium-margin players sit above commodity-margin players across calibration precision and thermal integration capabilities. The market structure consolidates around three strategic archetypes: diversified electronics conglomerates with display panel verticality, dedicated automotive Tier 1 suppliers with OEM co-location advantages, and specialized holographic optics developers. Dominant competitive moves include strategic partnerships for waveguide fabrication capacity and backward integration into high-brightness projector module production.
Within the diversified electronics tier, Panasonic Holdings Corporation exemplifies vertical integration advantages through captive display panel supply. Among dedicated automotive Tier 1 specialists, Continental AG and Nippon Seiki Co., Ltd. occupy positions anchored by long-term OEM engineering center co-location. These three entities represent distinct competitive vectors: conglomerate scale economies, European supply chain integration, and Japanese domestic market contractual density.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Nippon Seiki Co., Ltd. |
| Continental AG |
| Robert Bosch GmbH |
| Valeo |
| DENSO Corporation |
| Harman International Industries |
| Envisics Ltd. |
| Visteon Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned German Tier 1 specialists anchor premium pricing discipline through engineering center co-location with Stuttgart OEM headquarters, while sovereign-backed Korean panel producers compress mid-tier margins through captive high-brightness module supply. This ownership-financing split concentrates pricing power upstream with vertically integrated display conglomerates and downstream with OEM-embedded system integrators, squeezing standalone aftermarket providers between yield-loss penalties and brand-premium exclusion.
Pricing Analysis
Outcome-based pricing tied to EU GSR intelligent speed assistance compliance certification anchors premium tiers, with three-tier pricing structure across premium, standard, and economy levels separating embedded windshield systems from retrofitted combiner units and generic aftermarket displays. Price differentiation rests on calibration precision grade and thermal integration depth, with OEM-specified systems commanding substantial premiums over aftermarket alternatives. Pricing pressure stems from DLP and laser phosphor component volatility constraining mid-tier system integrator margins. Fleet operators show lowest price sensitivity due to insurer risk-adjustment protocol compliance requirements, while individual consumers in unserved markets exhibit highest sensitivity to installation complexity and upfront hardware costs.
Supply Chain Analysis
Refurbishment flows for high-brightness projector modules remain underdeveloped, creating stranded asset risk for aftermarket providers unable to recover calibration-intensive optical components. Manufacturing concentrates in Germany, Japan, and South Korea, with Stuttgart and Nagoya metro areas hosting irreplaceable optomechanical engineering clusters. Supply draws from Texas Instruments DLP chipsets, laser phosphor light sources, and precision freeform mirror substrates. Single-source vulnerability concentrates in specialized waveguide fabrication capacity located exclusively within Stuttgart and Nagoya engineering corridors. Distribution runs through OEM platform contracts for embedded systems and independent automotive electronics distributors for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as multi-homologation certification timelines force parallel FDA, EU GSR, and China MIIT validation tracks that extend product launch windows beyond smaller competitors' capital endurance.
For Market Incumbents: Hedge against holographic waveguide technology displacement by securing exclusive fabrication partnerships with Nagoya and Stuttgart optics specialists before 2026-2028 flagship launch cycles lock in supplier relationships. Defensive moves include backward integration into high-brightness projector module production and capacity expansion within German automotive corridor engineering centers to compress OEM development cycles. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the most penetrable route into North American heavy-duty truck logistics corridors, where standalone aftermarket display displacement creates immediate embedded system substitution demand. White-space targets include commercial vehicle safety-stack bundling and LiDAR fusion interface development for premium positioning. A software-defined vehicle integration angle bypasses Nippon Seiki's Japanese domestic contractual lock-in. For Investors and Strategic Acquirers: First waveguide-based holographic combiner adoption by German flagship OEMs is the leading indicator that premium segment architecture shifts are accelerating, signaling acquisition timing for specialized optics developers ahead of mainstream platform standardization. Long-term viability favors scaled manufacturers with multi-market platform capabilities across EU GSR, FDA, and China MIIT compliance jurisdictions. Acquisition target archetype: holographic waveguide specialists with captive Stuttgart or Nagoya engineering talent.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Fabrication Partnership | Secures exclusive access to Stuttgart and Nagoya optomechanical engineering clusters for holographic combiner production. |
| Multi-Market Platform Standardization | Enables simultaneous EU GSR, FDA, and China MIIT compliance without parallel validation track duplication. |
| Fleet Safety-Stack Integration | Captures North American heavy-duty truck procurement consolidating around ADAS software licensing bundles. |
| Backward Integration into Projector Modules | Reduces DLP and laser phosphor component volatility exposure through in-house high-brightness module production. |
| LiDAR Fusion Interface Development | Positions integrated perception-stack suppliers for premium OEM positioning as environmental sensing converges with AR overlays. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, and EU regulatory filings, complemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator safety managers. Secondary validation drew from SEC filings of diversified electronics conglomerates, customs records of high-brightness projector module trade flows, and China MIIT GB standard documentation. Bottom-up unit shipment modeling triangulated against top-down OEM platform contract value aggregation.
Segmentation outputs across the projection horizon reflect vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs were derived from S-curve adoption modeling calibrated to EU GSR mandate implementation phases and FDA driver distraction metric evolution. Industry-specific forecast inputs included windshield optical distortion yield loss rates and holographic waveguide development timeline acceleration signals from German and Japanese flagship launch schedules.
The model holds under stable regulatory compliance timeline assumptions; deviation in EU GSR enforcement intensity, FDA field-of-view specification revisions, or China MIIT luminance standard harmonization pace would shift embedded system penetration trajectories. Practitioners should monitor holographic waveguide prototype deployment announcements and fleet operator pilot program expansions for early signals of architecture transition acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Vehicle Intercom System Market