
 Germany Automotive Camera Market | 2026-2036
Germany Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Camera Market Foresight
ISO 26262 functional safety qualification is collapsing the supplier base for high-stakes camera modules. Robert Bosch GmbH leverages its in-house semiconductor fabrication to control image sensor supply chains. Continental AG sustains dominance through integrated radar-camera fusion platforms for highway assist functions.
An automotive camera is an electro-optical sensor assembly comprising a lens stack, solid-state imager, and signal processing unit, typically resolving 1.3 to 8 megapixels at frame rates between 30 and 60 Hz, engineered to deliver real-time visual data for machine perception and human display. CMOS technology leads unit economics due to lower power draw and on-chip integration potential, while time-of-flight variants capture the fastest-growing niche for cabin occupancy detection. Front view cameras anchor the largest revenue pool through mandatory integration with emergency braking and lane keeping systems.
The KBA enforces UN ECE R79 and R152 compliance for steering and automatic emergency braking, compelling OEMs to source cameras with certified object tracking latency below 120 milliseconds. The EU AI Act adds algorithmic transparency requirements for autonomous driving perception stacks, forcing suppliers to document training data provenance and edge-case performance. Stakeholders must weigh captive sensor development against module sourcing as regulatory verification burdens intensify.
Market Dynamics
ISO 26262 functional safety qualification is collapsing the supplier base for high-stakes camera modules, concentrating procurement power among vertically integrated Tier 1s with captive semiconductor fabrication and in-house verification labs.
Growth Catalysts
- KBA mandate for advanced driver assistance systems:Regulatory pressure from Germany's Federal Motor Transport Authority compels OEMs to integrate emergency braking and lane keeping systems, standardizing multi-camera architectures across vehicle classes.
- Surround view system penetration in premium SUVs:Bavarian and Baden-Württemberg assembly plants are scaling 360-degree camera production to meet OEM demand for parking assistance and low-speed maneuvering automation.
- CMOS imager unit economics:Lower power draw and on-chip integration potential are accelerating CMOS adoption over CCD technology in forward-facing and cabin-monitoring applications.
Market Restraints
- Image sensor supply concentration:Dependence on Asian wafer foundries creates vulnerability to geopolitical disruption and capacity allocation decisions outside German regulatory reach.
- Time-of-flight module cost structure:VCSEL arrays and SPAD receivers for cabin occupancy detection carry 3-4x BOM premiums versus standard 2D cameras, constraining mass-market deployment.
- EU AI Act algorithmic transparency requirements:Documentation burdens for training data provenance and edge-case performance are extending development timelines and verification costs for perception stack suppliers.
Strategic Opportunities
- Radar-camera fusion platform expansion:Highway assist functions are driving integration opportunities between forward-facing cameras and long-range radar modules, consolidating sensor processing at the domain controller level.
- Cabin monitoring regulatory tailwinds:Euro NCAP 2026 protocols for child presence detection and driver distraction monitoring are creating mandated demand for infrared-capable interior cameras.
- Baden-Württemberg production cluster leverage:Stuttgart-Ostfildern camera module concentration offers logistics advantages for just-in-sequence delivery to Mercedes-Benz, Porsche, and Audi assembly networks.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise is concentrated among senior specialists at Robert Bosch GmbH and Continental AG, constraining talent mobility and verification throughput.
- UN ECE R79/R152 latency compliance:Object tracking pipelines must achieve certified response below 120 milliseconds, requiring hardware-software co-optimization that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Camera Market |
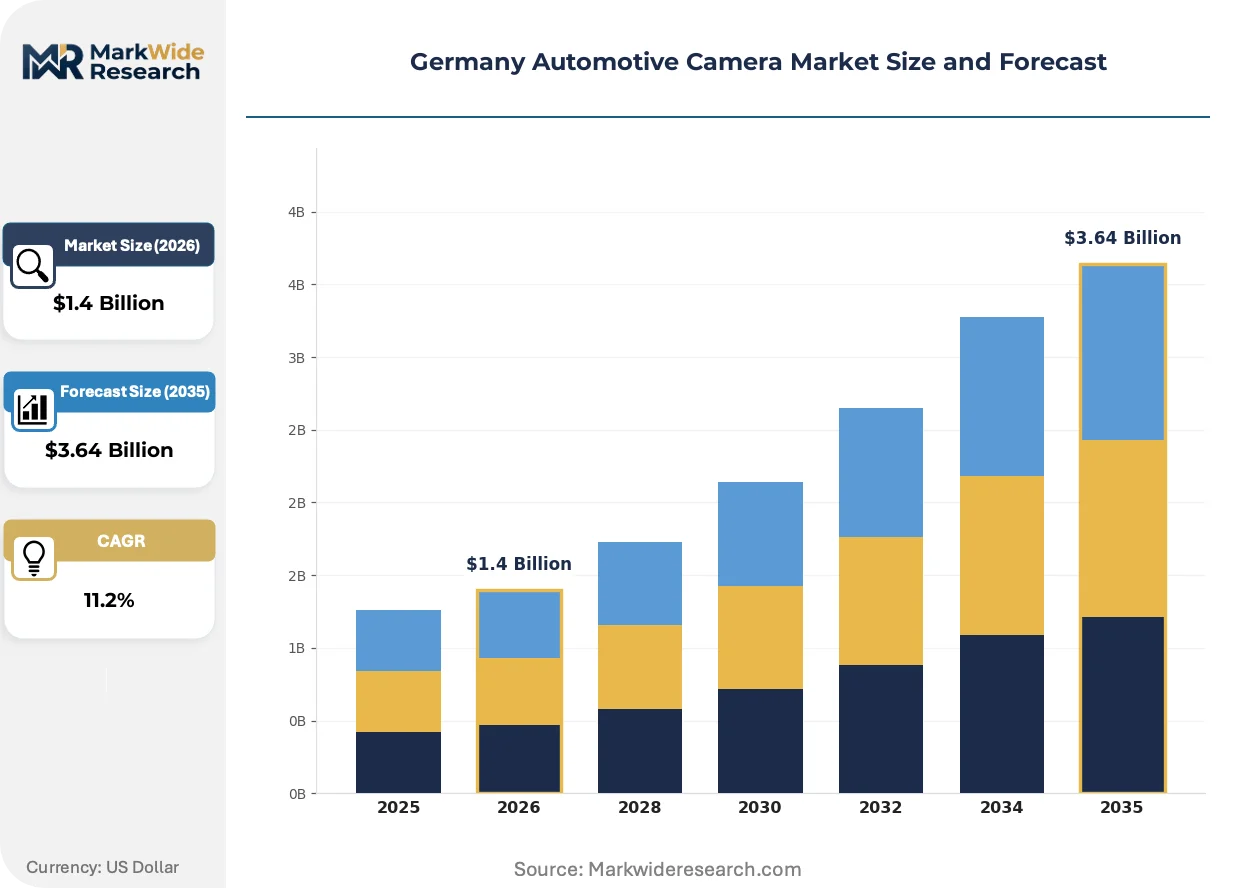
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front View Camera, Rear View Camera, Surround View Camera, Interior Monitoring Camera, Side View Camera Technology: CCD, CMOS, Infrared, Time-of-Flight, Ultrasonic Application: Driver Assistance Systems, Parking Assistance, Autonomous Driving, Safety Surveillance, Fleet Management End User: Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Magna International Inc., ZF Friedrichshafen AG, Valeo SA, HELLA GmbH & Co. KGaA, Garmin Ltd., Aptiv, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Camera Market Shifts & Advancements
Silicon-level integration and regulatory algorithmic governance are compressing development models, while procurement concentration around integrated sensor-fusion platforms is reshaping supplier relationships.
Time-of-flight CMOS sensors with vertical-cavity surface-emitting laser illumination are supplanting traditional 2D RGB cameras for cabin occupancy detection, enabling depth-resolved passenger counting and gesture recognition. Tier 1 suppliers in Baden-Württemberg are qualifying these modules for 2026 Euro NCAP child presence mandates. The shift is compressing the addressable market for standalone infrared cameras while expanding ASP pools for fused depth-RGB assemblies.
Germany's KBA enforcement of UN ECE R79 and R152 is mandating certified object tracking latency below 120 milliseconds for steering and automatic emergency braking systems. This regulatory floor is disqualifying software-only perception stacks and favoring hardware-accelerated neural network inference at the edge. Front view camera modules with dedicated NPU co-processors are capturing preference share in RFQs from Munich and Stuttgart-based OEMs.
Module procurement is consolidating around integrated radar-camera fusion platforms for highway assist functions, displacing discrete sensor sourcing. Tier 1 suppliers with captive radar and camera production are capturing sole-source positions in platform RFQs. Bavarian OEMs are driving this consolidation through technical specification documents that mandate synchronized sensor fusion at the domain controller rather than the sensor edge.
Germany Automotive Camera Market Segmentation
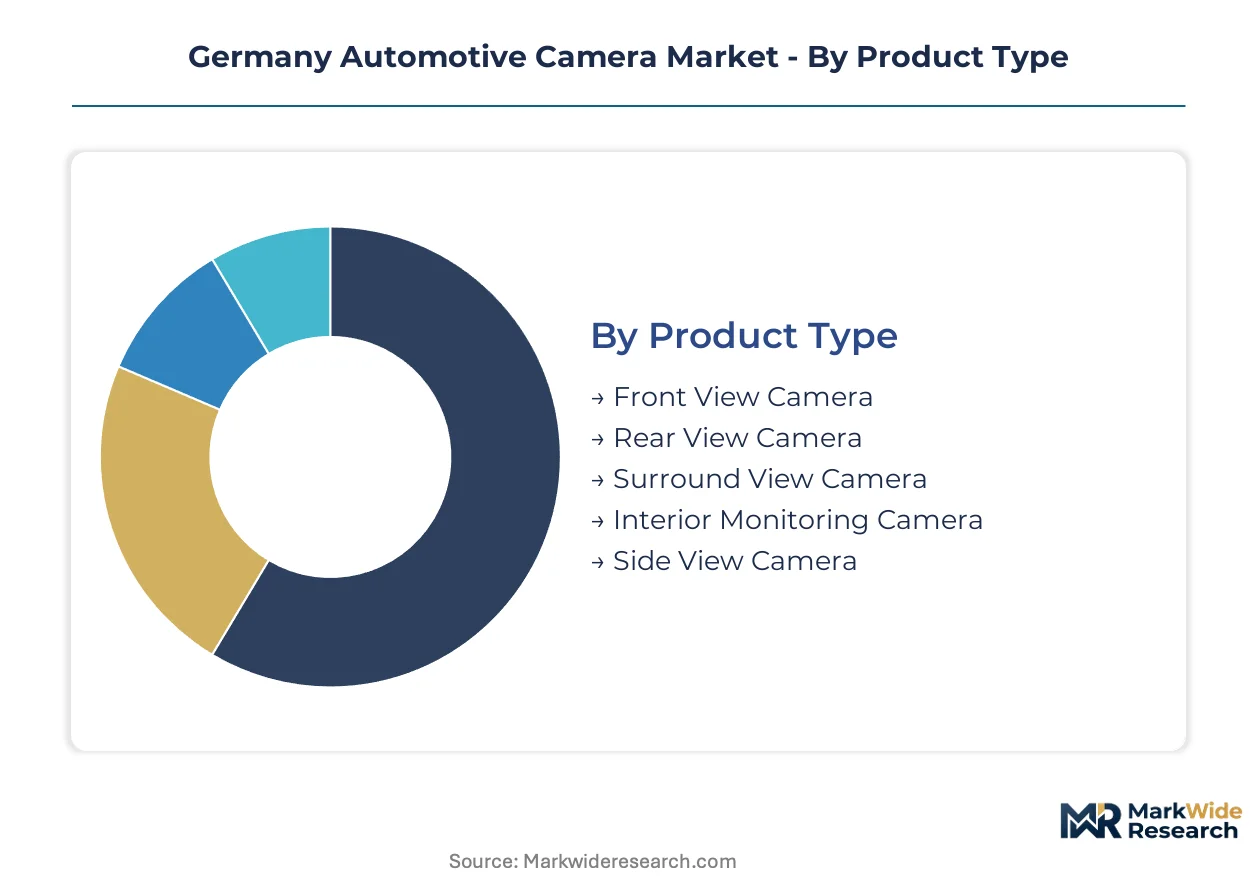
German OEM procurement patterns fragment across sensor mounting positions, imaging technologies, and regulatory-driven application tiers. Bavarian and Baden-Württemberg assembly networks concentrate demand for specific camera architectures tied to mandated ADAS functions.
Product Type:
Domestic production clusters in Stuttgart-Ostfildern and Ingolstadt supply primarily to German OEM assembly networks, while export demand pulls surround view and interior monitoring modules to broader European markets.
- Front View Camera:These modules integrate 1.3 to 8 megapixel CMOS sensors with dedicated NPU co-processors for real-time object detection. KBA enforcement of UN ECE R152 emergency braking mandates concentrates procurement from Munich and Stuttgart-based OEMs requiring certified sub-120 millisecond latency.
- Surround View Camera:Four-camera arrays generating stitched 360-degree video streams anchor premium SUV production at Bavarian plants. Parking assistance automation and low-speed maneuvering protocols standardize multi-camera architectures across Mercedes-Benz, BMW, and Audi vehicle classes.
- Rear View Camera:Single-lens modules for backup visibility dominate volume shipments to mass-market vehicle assemblers.
- Interior Monitoring Camera:Infrared-capable sensors for driver distraction and child presence detection gain traction ahead of Euro NCAP 2026 protocols.
- Side View Camera:Mirror-replacement and blind-spot monitoring applications remain niche outside commercial vehicle specifications.
Front view cameras hold the largest share; momentum sits with interior monitoring cameras.
Technology:
Cost tier differentiation separates mature 2D imaging from emerging depth-sensing modalities carrying 3-4x BOM premiums.
- CMOS:Lower power draw and on-chip integration potential accelerate adoption across forward-facing and cabin-monitoring applications. Robert Bosch GmbH and Continental AG leverage captive semiconductor fabrication to control CMOS sensor supply chains for German OEM platforms.
- Time-of-Flight:VCSEL-illuminated depth sensors enable passenger counting and gesture recognition through spatial mapping. Baden-Württemberg Tier 1 suppliers qualify these modules for 2026 Euro NCAP child presence mandates, compressing the addressable market for standalone infrared alternatives.
- CCD:Legacy technology persists in specialized industrial vehicle applications requiring high dynamic range.
- Infrared:Near-IR sensors support nighttime cabin monitoring without visible light distraction.
- Ultrasonic:Acoustic ranging complements camera arrays in parking assistance fusion stacks.
CMOS technology anchors volume production; time-of-flight sensors are climbing the fastest.
Application:
Customer type stratification separates regulatory-mandated installations from discretionary feature upgrades.
- Driver Assistance Systems:Lane keeping and adaptive cruise control integration demands multi-megapixel forward cameras with hardware-accelerated neural inference. KBA UN ECE R79 compliance requirements disqualify software-only perception stacks.
- Parking Assistance:Ultrasonic-camera fusion dominates low-speed automation with surround view penetration scaling across SUV platforms.
- Autonomous Driving:L3+ perception stacks require redundant sensor arrays with ASIL-D functional safety certification.
- Safety Surveillance:Event recording and collision documentation drive aftermarket retrofit demand.
- Fleet Management:Commercial vehicle operators integrate driver behavior monitoring for insurance premium optimization.
Driver assistance systems command the dominant revenue pool; autonomous driving applications show steepest expansion trajectory.
End User:
Supply concentration varies sharply between captive Tier 1 production and fragmented aftermarket distribution.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG maintain integrated radar-camera fusion platforms for highway assist functions. In-house verification labs and ISO 26262 ASIL-D certification expertise create procurement barriers for smaller competitors.
- Vehicle Manufacturers:Mercedes-Benz, BMW, and Audi specify synchronized sensor fusion at domain controllers rather than sensor edges.
- Vehicle Assemblers:Contract manufacturers rely on just-in-sequence delivery from Baden-Württemberg module clusters.
- Aftermarket Providers:Independent distributors serve retrofit demand for safety surveillance and fleet management applications.
Tier-1 suppliers capture platform-level procurement; aftermarket providers address fragmented retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA mandate for advanced driver assistance systems is cascading procurement requirements across neighboring European markets. OEMs in adjacent countries are aligning camera specifications with German regulatory standards to maintain cross-border platform compatibility.
France
Paris-based OEMs are accelerating surround view system adoption in premium electric SUVs. ANSM and CNIL oversight of biometric data processing is shaping interior camera deployment protocols for driver monitoring. The Île-de-France cluster around Paris-Saclay hosts specialized computer vision labs supplying algorithmic components to Tier 1 integrators.
Italy
Lombardy-based luxury vehicle manufacturers are specifying front view cameras with sub-120 millisecond latency for highway assist functions. CE marking and EU AI Act compliance documentation is extending supplier qualification timelines for perception stack vendors. The Turin-Piedmont automotive corridor is consolidating camera module testing facilities for Euro NCAP validation.
United Kingdom
Midlands-based vehicle assemblers are retrofitting production lines for multi-camera ADAS architectures ahead of anticipated regulatory alignment. The UK's national automotive regulator is evaluating UN ECE R79 and R152 adoption timelines post-EU transition. The West Midlands battery and sensor cluster is attracting camera module suppliers seeking proximity to Jaguar Land Rover and Aston Martin engineering centers.
Spain
Catalan automotive plants are scaling production of entry-segment vehicles with standardized rear view and parking assistance cameras. Spanish national regulators are harmonizing type approval processes with German KBA certification requirements. The Martorell manufacturing complex near Barcelona is integrating surround view systems for SEAT and Cupra SUV platforms.
Poland
Lower Silesian vehicle assembly facilities are absorbing overflow demand for camera-equipped compact cars from German OEMs. Polish industrial development incentives are attracting module packaging operations from Baden-Württemberg suppliers. The Bielsko-Biała production zone is specializing in cost-optimized rear view camera assemblies for mass-market European distribution.
Germany Automotive Camera Market Competitive Landscape
Player mix skews toward vertically integrated Tier 1s with captive semiconductor fabrication and in-house functional safety verification. The supplier base concentrates around three strategic archetypes: diversified automotive electronics conglomerates with radar-camera fusion platforms, specialized camera module manufacturers with regional logistics advantages, and technology licensors supplying image processing algorithms. Competitive moves center on backward integration into image sensor supply chains and consolidation of domain controller-level sensor fusion capabilities.
Within the diversified electronics tier, Robert Bosch GmbH and Continental AG exemplify vertically integrated positioning with captive semiconductor operations and ISO 26262 ASIL-D certification expertise. Denso Corporation represents the specialized module manufacturer archetype with established supply relationships to German OEM assembly networks. These three anchors illustrate the procurement consolidation dynamics reshaping RFQ structures across Bavarian and Baden-Württemberg production clusters.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Magna International Inc. |
| ZF Friedrichshafen AG |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Garmin Ltd. |
| Aptiv |
| Others |
Supply & Pricing Matrix
CMOS sensor substitution for legacy CCD technology is redrawing procurement geography toward Asian wafer foundries while compressing module-level margins through commoditization of 2D imaging components. This input transition simultaneously concentrates supply risk outside German regulatory reach and intensifies price competition among Tier 1 suppliers bidding for standardized forward-facing camera platforms.
Pricing Analysis
Certification level creates the primary spread across German automotive camera procurement, with ISO 26262 ASIL-D qualified modules commanding substantial premiums over ASIL-B alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks functional safety grade, megapixel resolution, and NPU co-processor integration. Pricing pressure stems from CMOS imager commoditization and OEM platform standardization mandates. Mass-market vehicle assemblers exhibit highest price sensitivity, while premium SUV programs tolerate ASP elevation for surround view sophistication.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for VCSEL arrays and specialized optical components sourced from Taiwan and South Korea. German camera module production draws from Taiwanese wafer foundries for CMOS sensors, Japanese suppliers for precision lens stacks, and Chinese packaging operations for cost-optimized rear view units. Single-source vulnerability concentrates in advanced image sensor supply. Distribution runs through just-in-sequence delivery networks anchored by Baden-Württemberg production clusters serving Stuttgart and Ingolstadt assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German automotive camera demand follows a cyclical recovery pattern tied to Euro NCAP protocol refreshes that mandate technology upgrades across vehicle fleets. KBA enforcement timelines for UN ECE R79 and R152 compliance create predictable replacement cycles for perception stack hardware.
For Market Incumbents: Shield ASIL-D certification moats through accelerated investment in in-house semiconductor fabrication and functional safety engineer retention programs. Emerging Chinese module suppliers with cost-optimized CMOS sourcing threaten mid-tier contract positions. Prioritize backward integration into image sensor supply chains to control BOM volatility and secure allocation priority during capacity constraints.
For New Entrants and Emerging Players: Lead with specialized cabin monitoring solutions targeting Euro NCAP 2026 child presence detection mandates, where time-of-flight expertise gaps exist among established Tier 1s. Interior camera applications for driver distraction monitoring represent the most penetrable segment given algorithmic differentiation opportunities. Pursue direct engineering relationships with Stuttgart-based OEM platform teams rather than competing for highway assist fusion platform slots.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized camera module manufacturers possessing Baden-Württemberg production footprints and established just-in-sequence logistics contracts. Five-to-ten year viability hinges on successful navigation of EU AI Act algorithmic transparency requirements and captive sensor development economics. Monitor KBA type approval velocity as the critical inflection signal for perception stack hardware replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Camera Fusion Platform Consolidation | Domain controller-level integration captures sole-source positions with Munich and Stuttgart OEMs. |
| Time-of-Flight Module Qualification | Baden-Württemberg suppliers securing Euro NCAP 2026 child presence mandates expand ASP pools. |
| In-House Semiconductor Fabrication | Captive CMOS sensor production insulates Robert Bosch GmbH from Asian foundry allocation decisions. |
| Functional Safety Engineer Acquisition | ISO 26262 ASIL-D expertise concentration at Continental AG creates talent arbitrage opportunities. |
| Algorithmic Transparency Documentation | EU AI Act compliance investment separates viable perception stack suppliers from disqualified competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and KBA regulatory affairs specialists. Secondary validation incorporated UN ECE regulatory filings, KBA type approval databases, vehicle production statistics from IHS Markit, and SEC disclosures from listed automotive electronics suppliers. Bottom-up unit shipment estimates triangulated against top-down OEM platform content projections.
Across the analysis window, volume and value outputs reflect segmentation modeling across camera mounting position, imaging technology, application tier, and end-user category. CAGRs were derived from regression analysis of historical ADAS mandate adoption curves and projected Euro NCAP protocol phase-ins. Industry-specific forecast inputs included KBA enforcement timelines for UN ECE R79 and R152, Euro NCAP 2026 child presence detection protocols, and CMOS sensor foundry capacity expansion announcements.
Forecasts assume regulatory continuity in German KBA and EU AI Act regimes; material policy shifts would require re-modeling of perception stack compliance costs and development timelines. Specific risks include geopolitical disruption to Taiwanese wafer supply, accelerated L3+ autonomous driving deployment altering sensor redundancy requirements, and VCSEL component shortages constraining time-of-flight module availability. Recalibration cycles align with material shifts in regulatory enforcement schedules and foundry capacity allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market