
 North America Automotive Camera Market | 2026-2036
North America Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Camera Market Analytics
A capital-intensity divergence between integrated sensor suppliers and modular component vendors is bifurcating competitive dynamics in the North America automotive camera landscape. Magna International leverages its captive electronics manufacturing footprint to control cost structures across Canadian and U.S. assembly corridors. Mobileye sustains algorithm-hardware co-development pipelines that anchor premium positioning in forward-facing camera modules. Robert Bosch GmbH competes through deep ties to German-parent R&D networks while operating substantial Michigan-based validation facilities.
An automotive camera captures optical images through solid-state imaging sensors—typically CMOS arrays operating between 1.2 and 8 megapixels with dynamic range exceeding 120 dB—to enable machine-vision functions including lane-keeping, collision avoidance, and parking assistance. These devices translate photonic data into digital signals processed by embedded neural accelerators, forming the perceptual layer of modern advanced driver-assistance systems. Rearview camera installations dominate unit volume given NHTSA-mandated fitment on light vehicles, while surround-view configurations command premium pricing through multi-camera synchronization and stitched-image processing demands. Thermal camera penetration remains narrow but occupies critical margin pools in commercial-vehicle night-vision applications where CMOS performance degrades.
NHTSA, Transport Canada, and FMVSS 111 collectively mandate minimum field-of-view and response-latency standards that dictate sensor selection and lens-design parameters for rear-visibility systems. The EPA and California Air Resources Board indirectly shape camera demand through emissions regulations that encourage lightweighting and aerodynamic optimization, functions supported by parking-assist and surround-view systems that reduce low-speed collision damage and repair-cycle carbon intensity. Stakeholders must monitor evolving NHTSA notice-of-proposed-rulemaking activity on automatic emergency braking expansion, as this regulatory trajectory will determine whether forward-facing stereo-camera architectures displace single-sensor configurations in mid-vehicle segments.
Market Dynamics
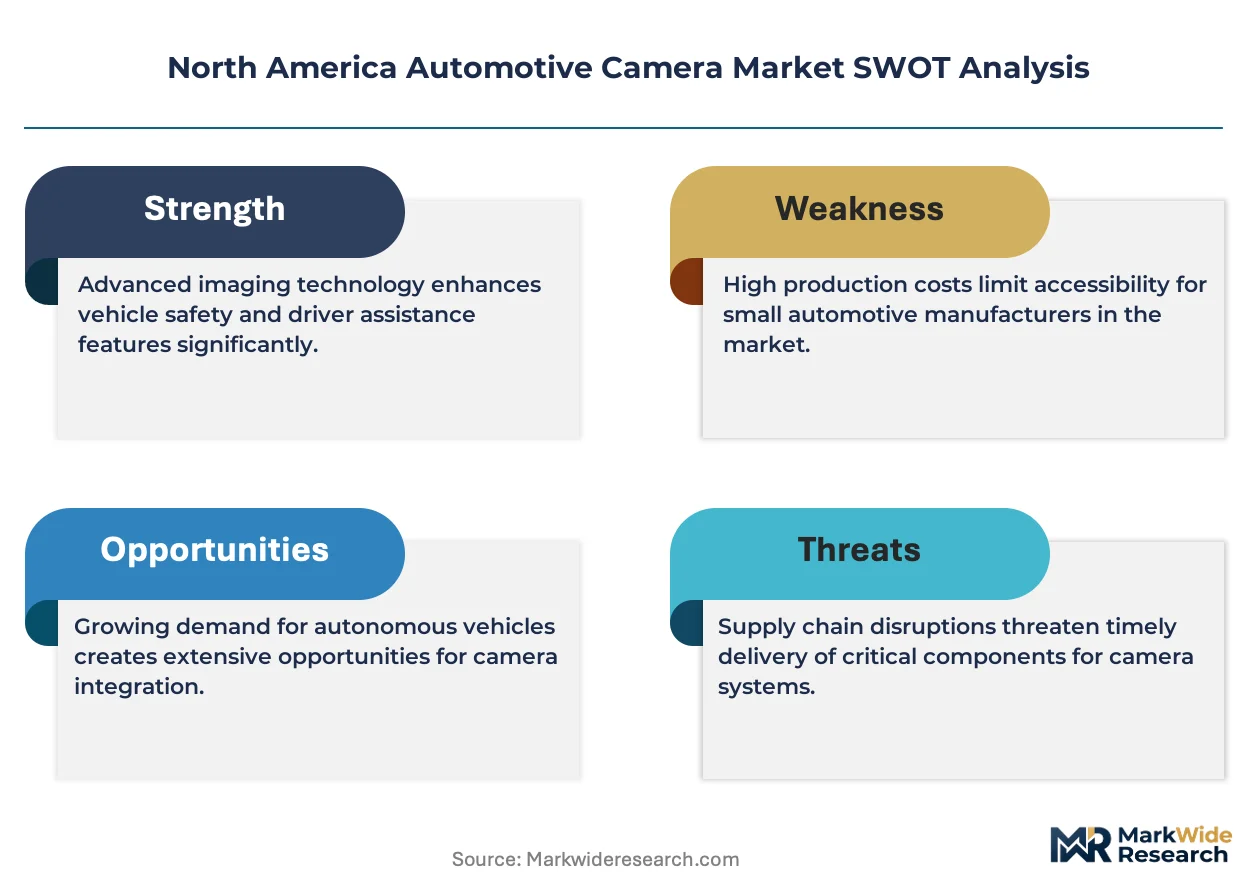
Integrated sensor suppliers and modular component vendors are diverging on capital intensity, splitting competitive dynamics across the North America automotive camera landscape. This structural tension between captive manufacturing and outsourced assembly is redrawing supplier relationships from Michigan to Ontario.
Growth Catalysts
- NHTSA Rear-Visibility Mandate:FMVSS 111 compliance requirements sustain baseline demand for rearview camera modules across light-vehicle production corridors in Michigan and Ontario.
- ADAS Platform Expansion:Light-truck and SUV segments are absorbing forward-facing stereo-camera architectures as standard equipment on premium trim configurations.
- California Technology Clusters:Silicon Valley machine-vision R&D pipelines are feeding algorithm-hardware co-development for next-generation surround-view systems.
Market Restraints
- CMOS Sensor Supply Concentration:Wafer fabrication for automotive-grade image sensors concentrates in East Asian foundries, exposing North American module assemblers to geopolitical friction.
- Thermal Camera Cost Structure:Uncooled microbolometer arrays for commercial-vehicle night vision carry 4-6x unit cost premiums versus CMOS equivalents, capping addressable volume.
- FMVSS 111 Latency Standards:Response-time thresholds for rear-visibility systems constrain lens-design flexibility and eliminate lower-cost sensor options from qualification.
Strategic Opportunities
- Automatic Emergency Braking Expansion:Pending NHTSA notice-of-proposed-rulemaking activity could mandate forward-facing stereo configurations across mid-vehicle segments currently served by single-sensor designs.
- Commercial Fleet Night Vision:Underpenetrated long-haul trucking applications in Texas and Alberta corridors present expansion paths for thermal camera modules.
- Neural Accelerator Integration:Convergence between embedded AI processors and CMOS sensors is enabling edge-computing camera modules that reduce central ECU dependency.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-B compliance timelines for surround-view systems extend 18-24 months, compressing product refresh cycles.
- Legacy CAN Bus Integration:Parking-assist camera modules face protocol translation complexity when interfacing with decade-old vehicle electrical architectures still prevalent in fleet segments.
- Optics Talent Scarcity:Automotive lens design expertise concentrates among a narrow cohort of Michigan and Rochester-trained engineers, constraining supplier scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Camera Market |
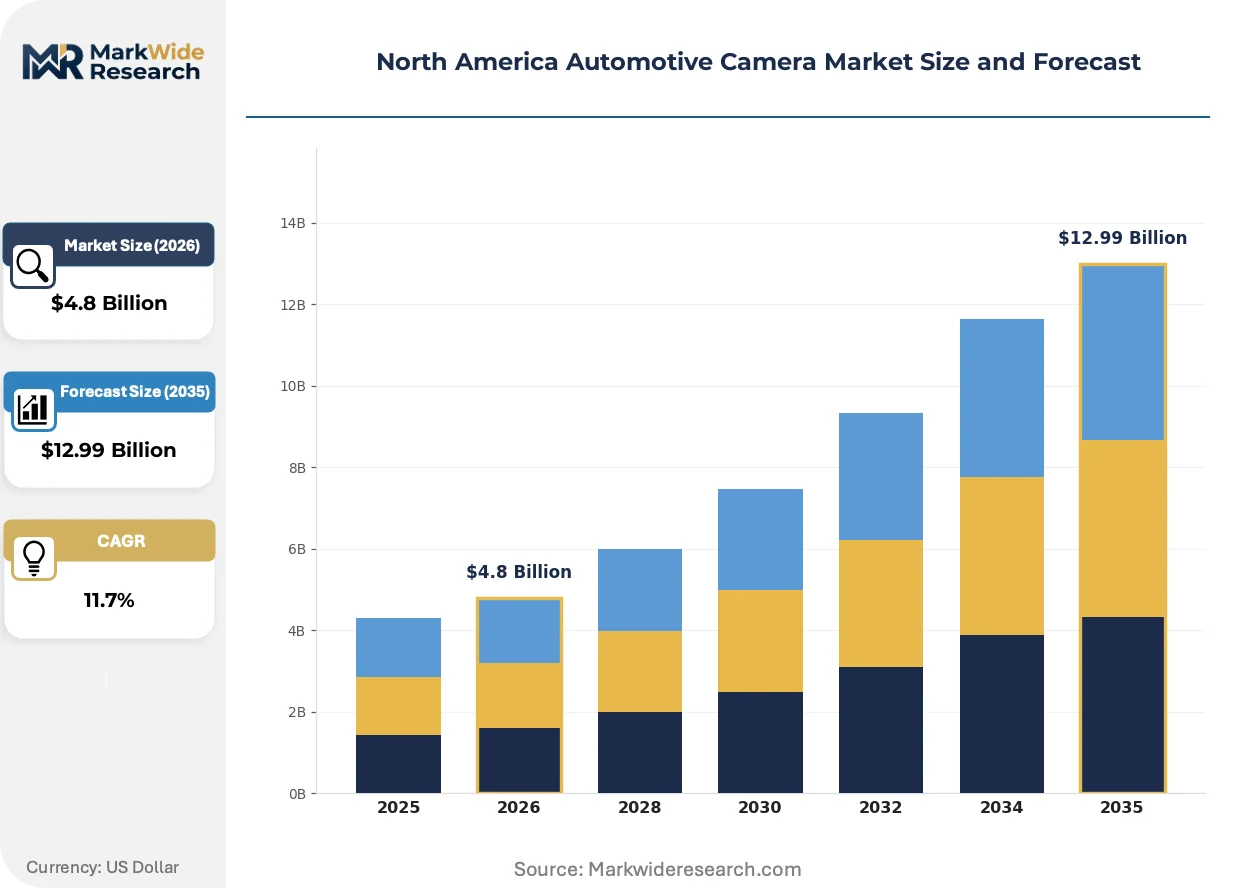
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Camera, Surround View Camera, Dashboard Camera, Thermal Camera Technology: CCD, CMOS, LiDAR, Radar End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Valeo S.A., Mobileye, Magna International, Aptiv PLC, ZF Friedrichshafen AG, Continental AG, Denso Corporation, Gentex Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Camera Market Evolving Landscape
Resolution escalation and processing localization are redefining camera module architecture. Suppliers now embed neural accelerators directly at the sensor node, reducing data transmission loads while enabling real-time decision-making.
Solid-state lidar is bifurcating the perceptual sensor stack. Forward-facing camera modules in premium light-truck platforms now fuse photonic data with point-cloud outputs for redundant object detection. Tier-1 suppliers in Michigan and Ontario are dual-sourcing CMOS and lidar subsystems to hedge against single-sensor failure modes. This convergence is compressing standalone camera margins while expanding system-level contract values.
NHTSA's advancing automatic emergency braking rulemaking is accelerating stereo-camera adoption. The proposed expansion beyond current voluntary commitments would mandate dual-sensor forward visibility across vehicle weight classes. Mid-segment SUVs and crossovers in the 3,500-5,500 pound GVWR range face the steepest compliance trajectory, driving engineering resource allocation toward stereo calibration and synchronization algorithms.
Fleet procurement patterns are consolidating around integrated ADAS bundles. Large commercial operators in Alberta and Texas oilfield corridors now specify surround-view and forward-collision systems as single-source contracts rather than discrete component purchases. This bundling is compressing modular component vendor access while elevating full-system integrators with captive validation facilities in Michigan and California.
North America Automotive Camera Market Segmentation
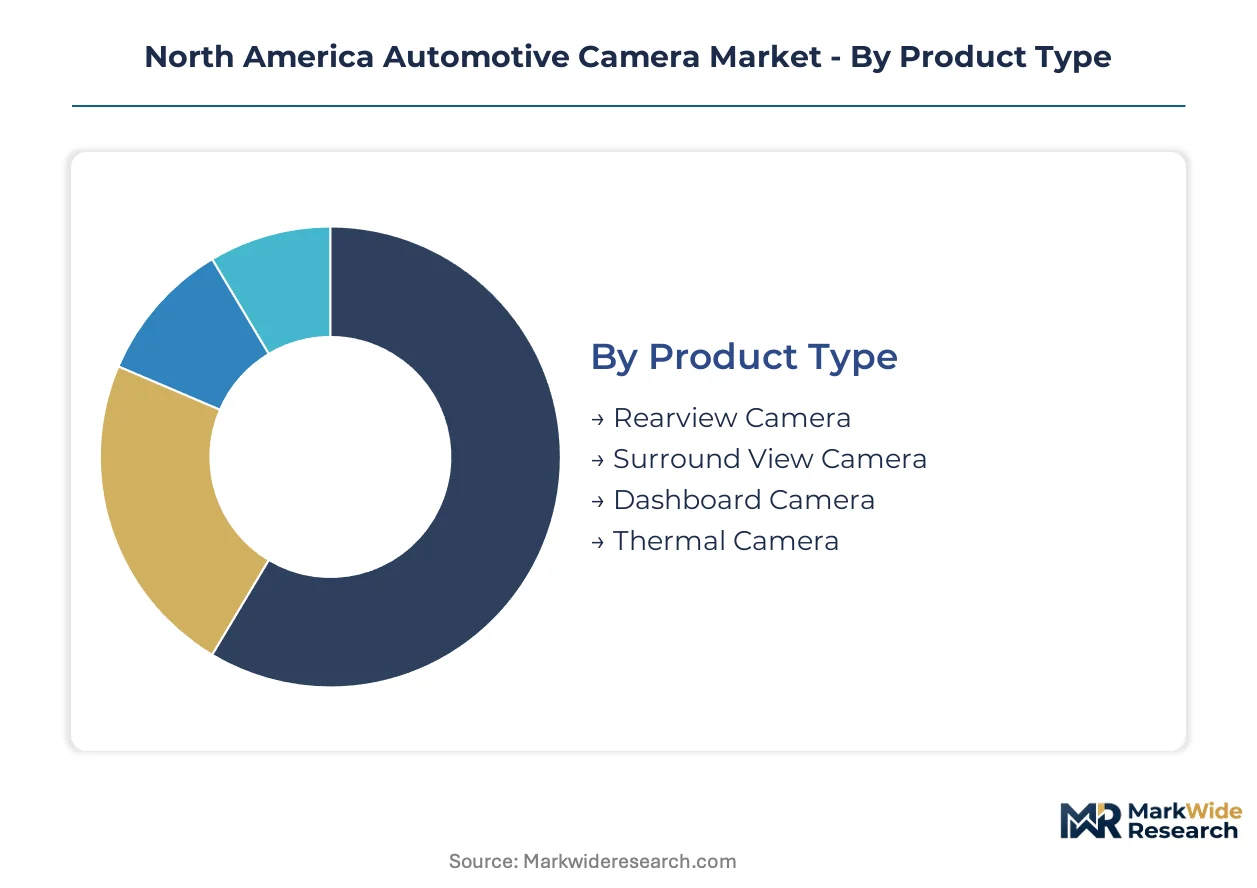
Camera module specifications diverge sharply across vehicle platforms in North America. Product architecture, sensor technology, and supply channel each create distinct margin pools that suppliers must navigate simultaneously.
Product Type:
Margin concentration tracks directly with image processing complexity and multi-camera synchronization requirements.
- Surround View Camera:Four-to-six camera arrays generate stitched 360-degree imagery through real-time calibration algorithms. Premium SUV and light-truck configurations in Michigan and Ontario assembly plants specify these systems as standard equipment on high-margin trim levels, with neural accelerator integration driving module cost escalation.
- Rearview Camera:Single-sensor modules operating under NHTSA FMVSS 111 mandates deliver baseline compliance across all light-vehicle production. Unit volumes concentrate in Ontario and Mexico border assembly corridors where supplier park proximity compresses logistics costs for this price-sensitive category.
- Dashboard Camera:Windshield-mounted recording devices serve aftermarket fleet liability management.
- Thermal Camera:Uncooled microbolometer arrays penetrate commercial-vehicle night vision where CMOS dynamic range fails.
Surround View Camera holds installed capacity. Rearview Camera is rotating up the share rankings.
Technology:
Sensor selection determines qualification pathways and foundry dependency exposure across module assembly networks.
- CMOS:Dominant solid-state imaging technology leveraging rolling-shutter and global-shutter variants with 120+ dB dynamic range for automotive machine vision. NHTSA automatic emergency braking rulemaking is accelerating demand for dual-CMOS stereo configurations in forward-facing modules across mid-segment SUVs.
- LiDAR:Solid-state point-cloud sensors are fusing with camera outputs in premium perceptual stacks. Michigan-based Tier-1 validation facilities now run joint calibration protocols for CMOS-lidar convergence in next-generation forward-collision systems.
- CCD:Legacy charge-coupled devices retain niche industrial inspection applications.
- Radar:Complements camera data in sensor fusion architectures for redundant object detection.
CMOS commands volume leadership. LiDAR is climbing the fastest among emerging sensor categories.
End User:
Channel structure shapes pricing power and technical specification authority in divergent ways.
- OEMs:Vehicle manufacturers in Detroit and California technology corridors dictate camera module specifications through platform-level ADAS integration contracts. Direct procurement relationships with Magna International and Robert Bosch GmbH bypass Tier-1 intermediaries for high-volume programs.
- Tier-1 Suppliers:Module assemblers with captive electronics manufacturing in Ontario and Michigan intermediate between sensor foundries and OEM assembly plants. These suppliers absorb ISO 26262 functional safety certification burdens while managing CMOS wafer allocation from East Asian sources.
- Aftermarket Providers:Independent distributors serve fleet retrofit demand for dashcam and parking-assist upgrades.
- Dealers:Franchise networks push accessory camera bundles at vehicle delivery.
OEMs hold specification authority. Tier-1 Suppliers are gaining share fastest through integrated manufacturing investments.
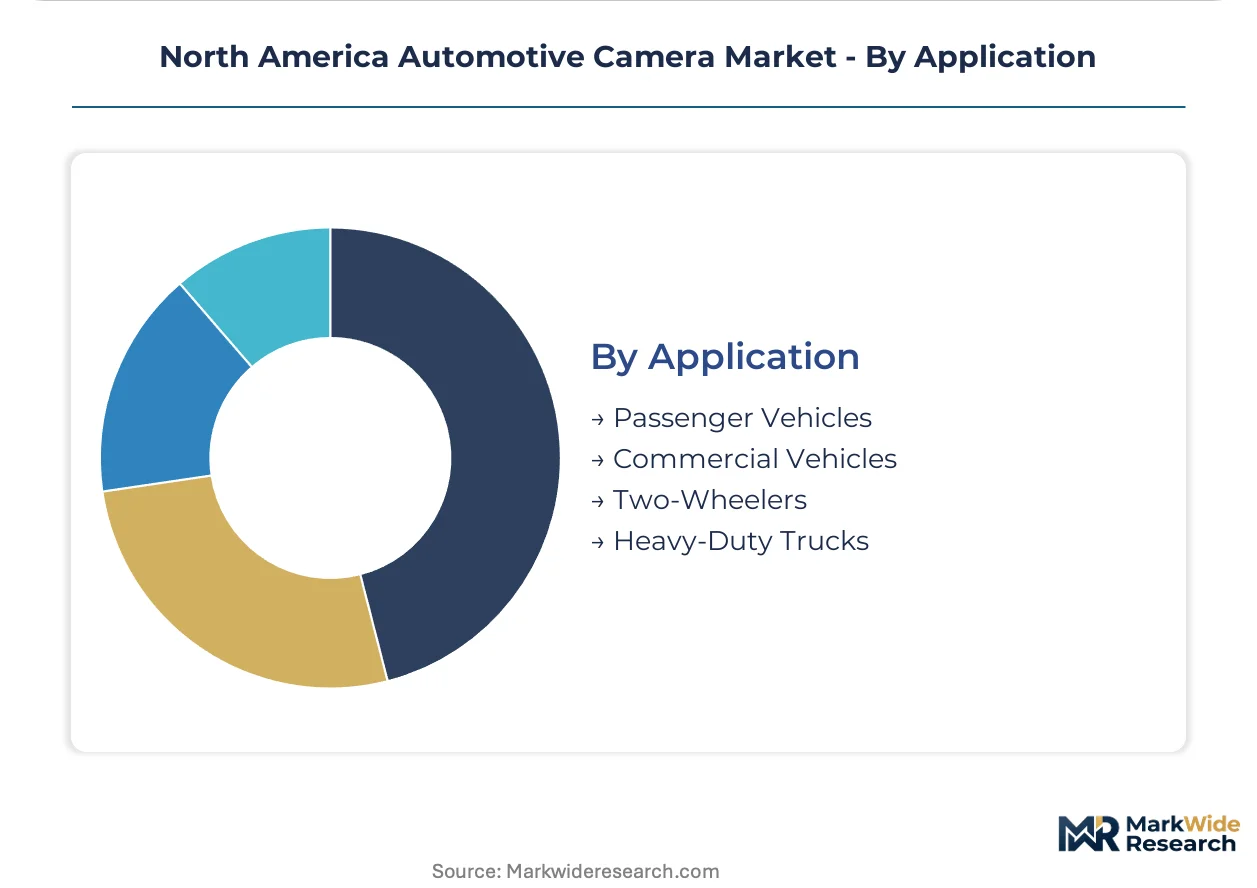
Application:
Vehicle weight class and duty cycle create fundamentally different performance and durability requirements.
- Passenger Vehicles:Light-duty cars, SUVs, and crossovers absorb the majority of surround-view and forward-facing stereo camera volumes. California and Michigan consumer preferences for premium ADAS trim configurations sustain margin premiums in this segment.
- Heavy-Duty Trucks:Long-haul commercial platforms in Texas and Alberta oilfield corridors specify thermal camera modules for night-vision compliance. FMCSA safety regulations and fleet insurance requirements are expanding addressable volume for multi-sensor perceptual stacks in this category.
- Commercial Vehicles:Delivery vans and regional freight trucks adopt mid-tier camera configurations.
- Two-Wheelers:Motorcycle rear-visibility systems remain underpenetrated in North American markets.
Passenger Vehicles anchor volume scale. Heavy-Duty Trucks is rotating up the share rankings through fleet safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the region. Mexican assembly plants prioritize cost-optimized rearview modules for export volumes, while California technology corridors absorb premium-priced stereo-camera architectures with minimal price sensitivity.
United States
NHTSA automatic emergency braking rulemaking and FMVSS 111 rear-visibility mandates sustain baseline demand across light-truck and SUV production. EPA emissions regulations indirectly shape camera specifications through aerodynamic optimization requirements. Michigan-based validation facilities and California machine-vision R&D clusters anchor the technology development pipeline.
Canada
Ontario vehicle assembly corridors concentrate surround-view camera demand for premium SUV platforms exported to U.S. markets. Transport Canada harmonizes with NHTSA safety standards while maintaining distinct winter-performance testing protocols. Magna International's captive electronics manufacturing in Ontario controls cost structures for cross-border supply chains.
Mexico
Border assembly plants in Nuevo León and Baja California absorb high-volume rearview camera production for U.S. market compliance. Mexican automotive manufacturing incentives support module assembly operations serving Detroit Three platform programs. Supplier park proximity to assembly corridors compresses logistics costs for price-sensitive FMVSS 111 categories.
North America Automotive Camera Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America automotive camera landscape. Tier-1 suppliers with captive electronics manufacturing control cost structures across Ontario and Michigan corridors, while algorithm-hardware co-development specialists anchor premium forward-facing modules. Strategic moves concentrate on backward integration into sensor sourcing and joint calibration protocols for multi-sensor perceptual stacks.
Within the integrated manufacturing tier, Magna International and Robert Bosch GmbH exemplify archetypes combining captive validation facilities with cross-border supply chain control. Mobileye occupies a distinct position in algorithm-hardware co-development for premium forward-facing camera modules, anchoring the technology-intensive segment of the competitive spectrum.
| Leading Market Players |
|---|
| Valeo S.A. |
| Mobileye |
| Magna International |
| Aptiv PLC |
| ZF Friedrichshafen AG |
| Continental AG |
| Denso Corporation |
| Gentex Corporation |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
FMVSS 111 certification requirements gate both supplier qualification and price tiering simultaneously across North American automotive camera procurement. OEMs extract compliance premiums from certified module vendors while squeezing uncertified competitors into aftermarket segments.
Pricing Analysis
After-sales service contracts and over-the-air software updates now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates surround-view arrays with neural accelerators from basic rearview compliance modules. Price differentiation hinges on ISO 26262 ASIL-B certification status and embedded AI processing capability. Cost compression in rearview categories is intensifying because Mexican assembly corridors prioritize logistics-minimized sourcing. Fleet procurement teams exhibit highest price sensitivity, while California technology clusters absorb premium stereo-camera configurations with minimal negotiation.
Supply Chain Analysis
Inventory buffers for CMOS wafers stretch 16-20 weeks as East Asian foundry allocation tightens. Wafer fabrication concentrates in Taiwan, South Korea, and Japan, while module assembly localizes in Ontario, Michigan, and Nuevo León. Automotive-grade image sensors draw from silicon ingots, specialized lens glass, and neural accelerator ASICs. Single-source vulnerability around 8-megapixel CMOS arrays exposes Tier-1 assemblers to geopolitical friction. Distribution runs through captive OEM supply parks and cross-border Tier-1 validation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined camera architectures transform hardware into recurring revenue platforms as over-the-air calibration and feature-unlock subscriptions outpace module ASP growth. Service-attach layers now capture margin pools previously locked in one-time equipment sales.
For Market Incumbents: Consolidate backward integration into CMOS sensor sourcing to hedge East Asian foundry concentration. Lock exclusive validation partnerships with Michigan-based OEM platform teams before solid-state lidar convergence accelerates. Defensive certification investments in ISO 26262 ASIL-D ratings will raise barriers against modular component vendors.
For New Entrants and Emerging Players: Transport Canada winter-performance fast-tracks offer accelerated qualification pathways versus NHTSA timelines. Target Alberta heavy-duty fleet retrofits for thermal camera night-vision compliance where incumbent coverage remains thin. White-space exists in edge-computing camera modules that reduce central ECU dependency for legacy fleet CAN bus architectures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across surround-view neural accelerator integration as algorithm-hardware co-development demands expand. Long-term viability favors suppliers with captive Ontario electronics manufacturing and California machine-vision R&D pipelines. Acquisition targets should combine sensor fusion expertise with FMVSS 111 validation track records. Watch NHTSA automatic emergency braking rulemaking finalization as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Accelerator Integration | Embedded AI processors at sensor nodes reduce central ECU dependency for Michigan OEM platforms. |
| CMOS-LiDAR Fusion Development | Joint calibration protocols in Ontario validation facilities enable redundant object detection stacks. |
| FMVSS 111 Compliance Expansion | Certification investments unlock rearview baseline demand across Mexico-U.S. border assembly corridors. |
| Aftermarket Fleet Retrofit Channels | Texas and Alberta oilfield corridors present underpenetrated thermal camera night-vision volume. |
| Cross-Border Manufacturing Footprint | Ontario-Michigan supply chain control compresses logistics costs for price-sensitive compliance modules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA rulemaking dockets, vehicle production databases, and SEC Tier-1 supplier filings. Interviews with OEM platform engineers, Tier-1 procurement leads, aftermarket distributors, and dealership operations heads inform demand-side calibration. Validation draws from IHS Markit registration data, Transport Canada safety compliance records, and customs trade flows. Bottom-up module shipment estimates triangulate against top-down ADAS content-per-vehicle assumptions.
Segmentation dimensions modeled span vehicle class, camera architecture type, sensor technology, and regional production cluster across the projection horizon. CAGRs derive from regression analysis of historical ADAS penetration curves and OEM platform lifecycle data. Forward-facing stereo-camera adoption rates and neural accelerator integration timelines serve as primary forecast sensitivity inputs.
Decision-makers should treat outputs as directional under stable NHTSA rulemaking trajectory and intact East Asian foundry supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
In-Car Gaming System Market