
 Automotive 360 Degree Technology Market | 2026-2036
Automotive 360 Degree Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 360 Degree Technology Market Outlook
Multi-source procurement of camera modules and ultrasonic sensors is shifting toward vertically integrated supply chains among tier-1 automotive suppliers. Continental AG leverages captive semiconductor sourcing to secure image-processing chipsets for surround-view controllers. Robert Bosch GmbH anchors its competitive stance through in-house manufacturing of MEMS sensors and lens assemblies. ZF Friedrichshafen AG differentiates via integrated software stacks that fuse camera feeds with radar returns.
Automotive 360 degree technology encompasses multi-camera arrays, ultrasonic sensors, and processing units that synthesize real-time vehicle-perimeter imagery into a unified bird's-eye view, typically operating at 30 frames per second with sub-100-millisecond latency for parking and low-speed maneuvering. The primary commercial purpose centers on eliminating blind spots during tight-space navigation and enabling automated parking trajectories. ADAS applications command the dominant revenue share due to regulatory pressure for pedestrian detection and cross-traffic alert functionality. Machine Learning processing segments exhibit the steepest trajectory as neural networks replace rule-based object classification in surround-view systems. LIDAR integration remains nascent in 360-degree configurations but attracts premium pricing for autonomous valet parking implementations.
NHTSA mandates rear-view camera visibility under FMVSS 111, while Euro NCAP's safety-assessment protocols reward surround-view and cross-traffic monitoring with scoring incentives that OEMs actively pursue. China's MIIT issues GB standards for intelligent connected vehicles that specify camera resolution and data-transmission protocols for 360-degree systems. Stakeholders must monitor how UN R79 amendments on automated steering interact with parking-assistance homologation timelines across multiple jurisdictions.
Market Dynamics
Regulatory mandates for pedestrian safety and automated parking are compressing homologation timelines while forcing tier-1 suppliers to consolidate sensor fusion capabilities under unified software architectures.
Growth Catalysts
- Euro NCAP scoring incentives:The safety assessment protocol awards points for surround-view and cross-traffic monitoring, compelling OEMs to standardize 360-degree systems across vehicle classes.
- Neural network deployment:Machine learning processing segments are accelerating as convolutional networks replace heuristic object detection in parking assistance controllers.
- German engineering clusters:Stuttgart and Munich anchor development ecosystems where Bosch, Continental, and ZF co-locate R&D for camera-radar fusion algorithms.
Market Restraints
- Semiconductor supply concentration:Image signal processors and MIPI bridge chips depend on Taiwanese and South Korean foundry capacity, exposing tier-1s to allocation volatility.
- Calibration complexity:Multi-camera alignment requires sub-millimeter precision during assembly, inflating warranty costs and service bay time.
- LIDAR cost floor:Solid-state LIDAR modules for autonomous valet parking remain priced at multiples of camera-only configurations, limiting mass-market penetration.
Strategic Opportunities
- China MIIT GB standards:Intelligent connected vehicle regulations specify camera resolution and data protocols, creating compliance-driven replacement cycles for legacy systems.
- Edge AI acceleration:On-device neural processing units are converging with 5G vehicle-to-infrastructure links, enabling real-time parking space detection without cloud dependency.
- Aftermarket channel expansion:Retrofit surround-view kits for commercial fleets address aging vehicle populations in Eastern European and Southeast Asian markets.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for surround-view controllers demands specialized systems engineering talent that OEMs and tier-1s compete to secure.
- Legacy vehicle integration:CAN bus bandwidth limitations in pre-2020 vehicle architectures constrain data throughput for high-resolution camera feeds.
- Cross-jurisdictional homologation:UN R79 automated steering amendments interact differently with NHTSA FMVSS 111 and MIIT GB standards, fragmenting validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 360 Degree Technology Market |
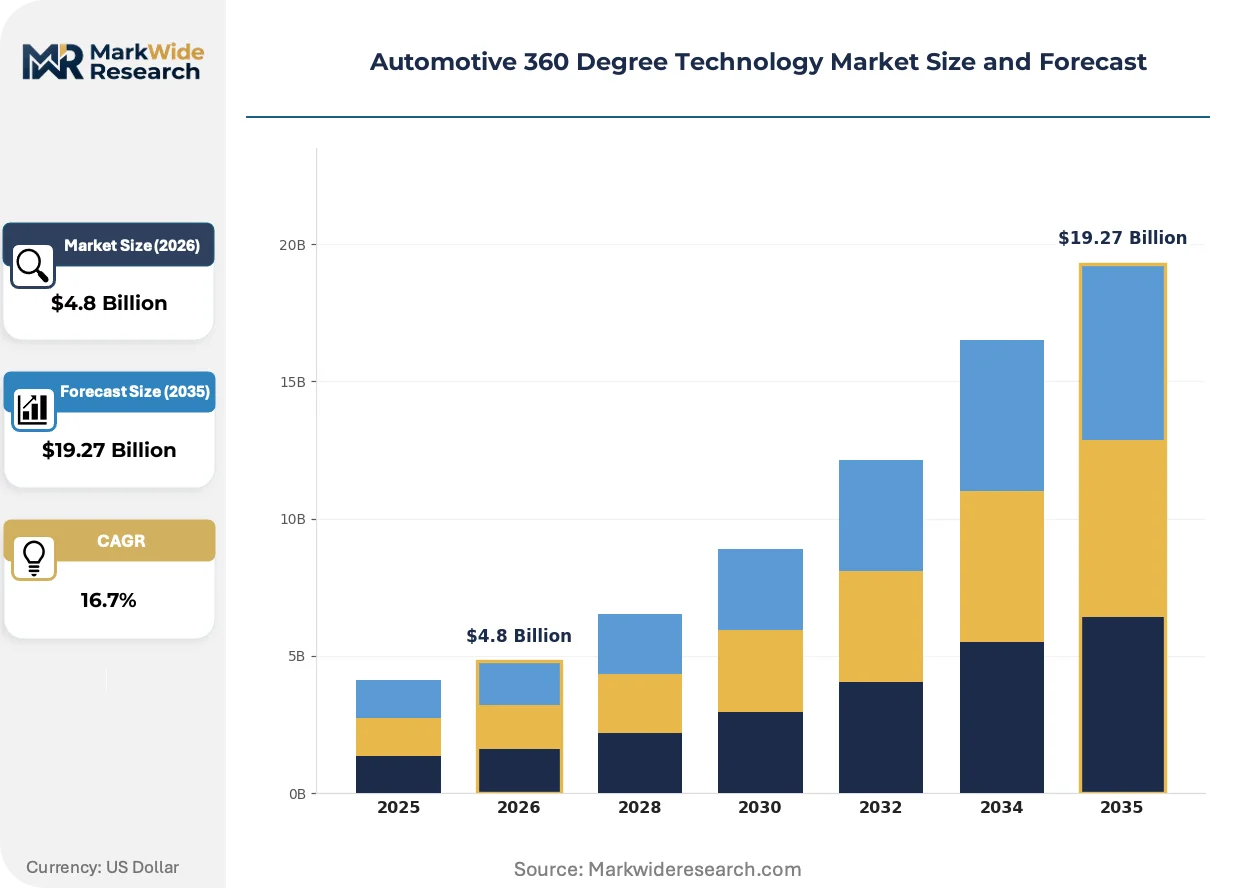
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ADAS, Telematics, Infotainment, Electric Powertrain Technology: V2X Communication, LIDAR, Radar, Machine Learning End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Autonomous Driving, Fleet Management, Remote Diagnostics, Vehicle-to-Vehicle Communication |
| Companies Covered | Continental AG, Denso Corporation, Aptiv PLC, Valeo SA, Magna International Inc., Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis, Mobileye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 360 Degree Technology Market Strategic Shifts
Sensor fusion architectures are migrating from centralized domain controllers to distributed edge computing nodes, compressing latency budgets while multiplying software complexity across the vehicle network.
Camera-based perception is decentralizing from single high-performance SoCs to multiple smart imagers with embedded ISP and object detection. Tier-1 suppliers are adopting these distributed modules for surround-view arrays to reduce wiring harness weight and simplify thermal management. This topology is compressing the addressable market for standalone image processing chipsets while expanding firmware revenue per vehicle.
UN R79 amendments on automated steering and parking are forcing OEMs to recalibrate validation protocols for hands-free maneuvering systems. The regulation mandates specific failure-mode responses that exceed current software safety standards. European and Japanese manufacturers are accelerating over-the-air update capabilities to maintain compliance across vehicle lifecycles.
Fleet procurement patterns are fragmenting as logistics operators unbundle parking assistance from full ADAS packages. Commercial buyers in Germany and the US are specifying camera-only configurations for urban delivery vehicles while omitting radar fusion to reduce per-unit cost. This specification divergence is pressuring tier-1s to maintain parallel product lines with incompatible software stacks.
Automotive 360 Degree Technology Market Segmentation
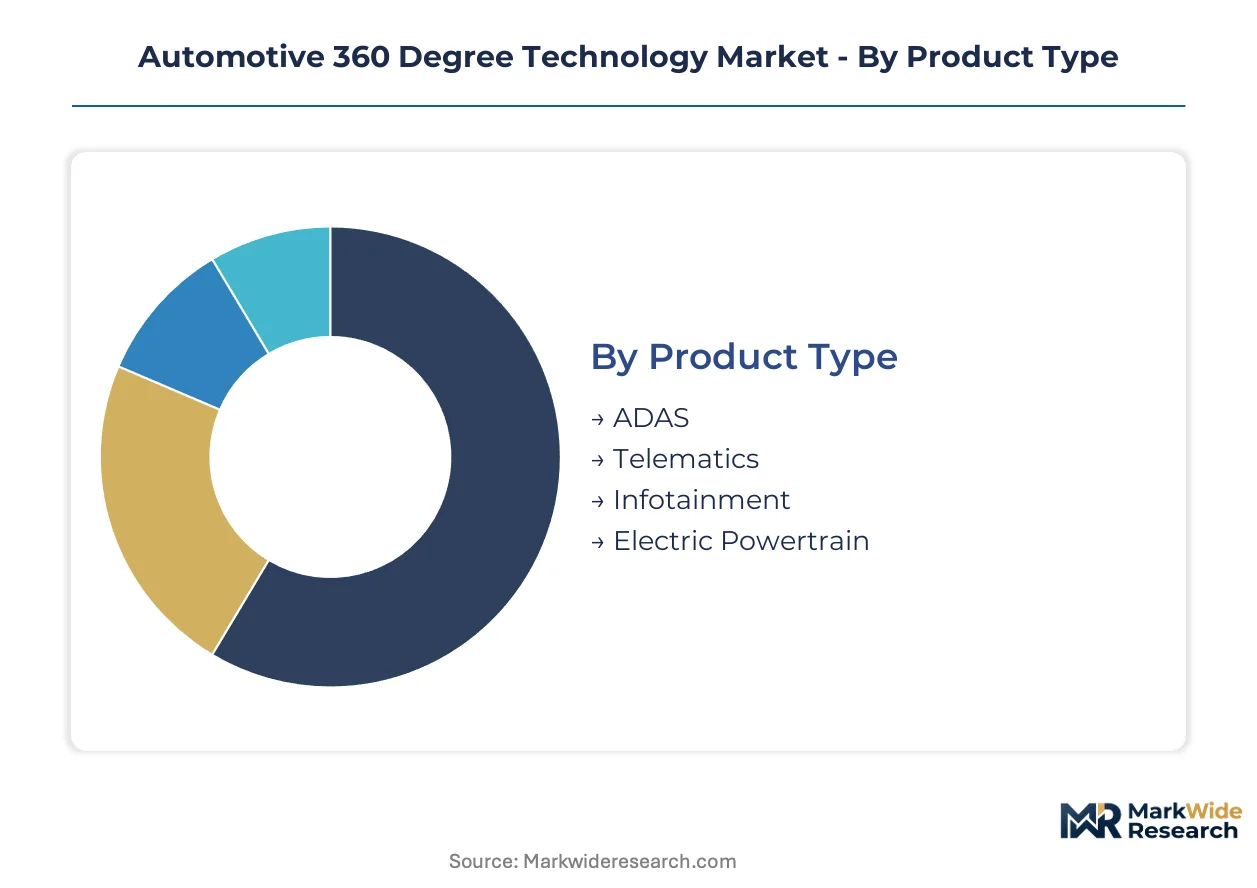
Segmentation in automotive 360-degree technology reveals how procurement decisions split between regulatory compliance mandates and autonomous feature roadmaps. Buyers prioritize sensor fusion architectures that satisfy Euro NCAP scoring while preserving upgrade paths to higher automation levels.
Product Type:
OEM procurement budgets allocate differentially across safety-critical and convenience systems, with regulatory pressure dictating baseline specifications.
- ADAS:Surround-view controllers integrate multi-camera arrays with ultrasonic sensors for parking assistance and cross-traffic alerts. German and Japanese OEMs standardize these configurations across passenger vehicle classes to secure five-star safety ratings.
- Telematics:Data transmission modules relay 360-degree imagery to fleet management platforms for remote monitoring of commercial vehicle operations. Logistics operators in the United States specify these systems for last-mile delivery vans to reduce insurance liability.
- Infotainment:Bird's-eye view displays merge with cabin entertainment interfaces for passenger engagement during automated parking sequences.
- Electric Powertrain:Battery electric vehicle platforms leverage 360-degree perception for optimized thermal management and charging port alignment.
Volume sits with ADAS; growth tilts toward Telematics.
Technology:
Technology selection follows a cost-performance hierarchy where camera-based solutions dominate mass deployment and premium sensor modalities capture autonomous valet applications.
- V2X Communication:Dedicated short-range communication modules transmit vehicle position and intent to infrastructure and surrounding traffic. Chinese OEMs integrate these systems to comply with MIIT GB standards for intelligent connected vehicles.
- LIDAR:Solid-state scanning modules provide centimeter-level ranging for automated parking in structured environments. German luxury manufacturers specify these for flagship sedan programs where valet parking commands price premiums.
- Radar:77GHz and 79GHz units supplement camera feeds with all-weather object detection capability.
- Machine Learning:Neural processing units execute real-time object classification on edge devices without cloud dependency.
Deployment concentrates on V2X Communication; steepest expansion trajectory belongs to Machine Learning.
End User:
Supply chain position determines specification authority, with vehicle manufacturers dictating sensor fusion architectures and tier-1s competing on integration speed.
- OEMs:Volkswagen, Toyota, and Hyundai directly procure camera modules and software licenses to maintain feature differentiation across model lineups. These buyers prioritize over-the-air update capabilities to extend system functionality across vehicle lifecycles.
- Tier-1 Suppliers:Continental, Bosch, and ZF aggregate sensor inputs into domain controllers for multiple OEM customers. Their procurement concentrates on Taiwanese image signal processors and South Korean MIPI bridge components.
- Aftermarket Providers:Retrofit specialists target aging commercial fleets in Eastern Europe with camera-only surround-view kits.
- Vehicle Assemblers:Contract manufacturers integrate pre-validated 360-degree systems under white-label arrangements for emerging EV brands.
Revenue accrues to Tier-1 Suppliers; aftermarket channels expand most quickly.
Application:
Use case maturity spans from production-ready parking assistance to experimental autonomous deployment, with validation requirements scaling accordingly.
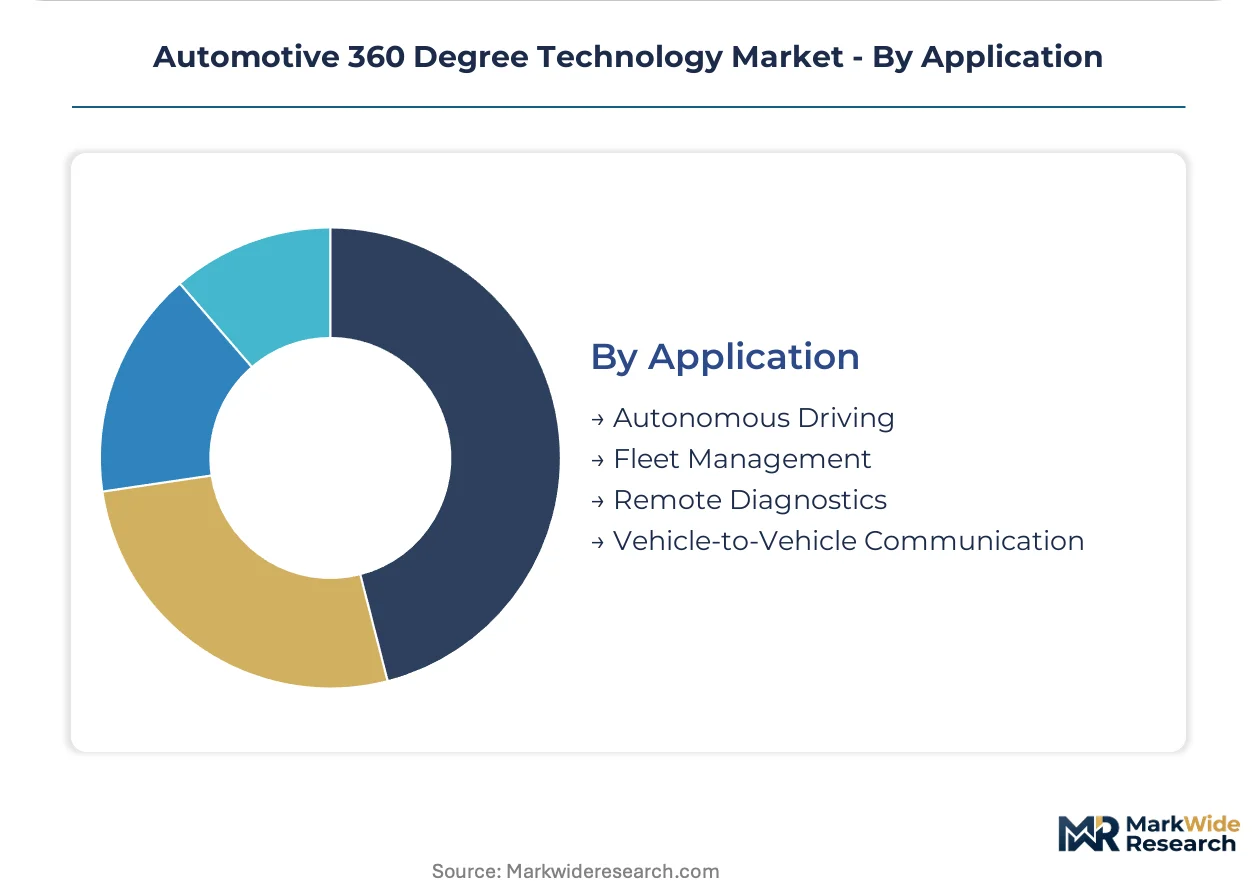
- Autonomous Driving:Level 4 parking systems require redundant perception layers satisfying UN R79 automated steering amendments. Japanese OEMs lead validation programs for hands-free maneuvering in geofenced urban zones.
- Fleet Management:Commercial operators monitor driver behavior and vehicle surroundings through centralized 360-degree feeds. German logistics firms deploy these systems to reduce collision frequency in dense urban delivery routes.
- Remote Diagnostics:Service technicians access surround-view imagery to assess vehicle condition without physical inspection.
- Vehicle-to-Vehicle Communication:Cooperative perception exchanges camera-derived object lists between proximate vehicles.
Investment flows to Fleet Management; capability advancement centers on Autonomous Driving.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement of surround-view systems concentrates demand in Stuttgart and Munich engineering clusters, while Chinese MIIT GB standards and US NHTSA mandates create parallel compliance-driven replacement cycles across three continents.
Germany
Volkswagen and BMW procurement of camera-radar fusion systems drives tier-1 supplier consolidation around Stuttgart and Munich. KBA homologation requirements for automated parking systems compress validation timelines for Bosch and Continental. Baden-Württemberg anchors development of MEMS sensor manufacturing and lens assembly operations.
China
BYD and NIO integrate 360-degree perception for automated valet parking in premium electric vehicle lineups. MIIT GB standards for intelligent connected vehicles mandate specific camera resolutions and data-transmission protocols. Yangtze River Delta manufacturing bases in Shanghai and Suzhou concentrate image signal processor assembly capacity.
United States
Ford and General Motors standardize surround-view systems to satisfy NHTSA FMVSS 111 rear-view visibility mandates across light truck and SUV segments. NHTSA safety ratings influence fleet procurement for commercial delivery vehicles. Michigan engineering corridors in Detroit and Ann Arbor host validation facilities for parking assistance algorithms.
Japan
Toyota and Honda deploy 360-degree systems for cross-traffic alert functionality in compact urban vehicles. METI guidelines for automated driving promote sensor fusion standardization across domestic supply chains. Nagoya industrial zones concentrate ultrasonic sensor manufacturing for parking assistance modules.
South Korea
Hyundai and Kia integrate surround-view technology with 5G vehicle-to-infrastructure links for real-time parking space detection. MFDS automotive safety guidelines align with international homologation standards for ADAS components. Seoul Capital Area hosts R&D centers for neural processing unit integration in edge devices.
Automotive 360 Degree Technology Market Competitive Environment
Strategic partnerships dominate the current landscape as tier-1 suppliers consolidate sensor fusion capabilities under unified software architectures. The vendor base separates into three distinct tiers: diversified automotive conglomerates with captive semiconductor sourcing, specialized camera module fabricators, and emerging software-centric challengers. Two competitive moves define positioning: backward integration into image processing chipsets and geographic expansion into Chinese EV supply chains.
Within the diversified conglomerate tier, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG occupy positions that exemplify contrasting integration strategies. Continental leverages upstream control over semiconductor supply chains. Bosch anchors its stance through in-house manufacturing capabilities. ZF differentiates via integrated software stacks that fuse multiple sensor modalities.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Aptiv PLC |
| Valeo SA |
| Magna International Inc. |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Mobileye |
| Others |
Value Chain & Pricing Dynamics
Image signal processor foundry capacity in Taiwan and South Korea feeds downstream through three distinct pricing tiers, with automotive-grade MIPI bridge chips commanding premiums over consumer electronics variants while camera module assembly in China and Mexico absorbs labor arbitrage benefits.
Pricing Analysis
Volume-mass-market camera-only configurations trade margin for OEM platform wins, while LIDAR-augmented premium tiers capture value through autonomous valet parking differentiation. Price differentiation separates ASIL-D certified controllers from basic parking assistance modules, with certification grade and volume scale as primary tiering mechanisms. Cost compression in standard-tier surround-view systems is intensifying because tier-1s compete for Volkswagen and Toyota platform awards. Fleet procurement teams exhibit highest price sensitivity, whereas German luxury OEMs prioritize feature completeness over per-unit cost.
Supply Chain Analysis
Specialized systems engineering talent shortages in Stuttgart and Munich constrain controller validation throughput for Bosch and Continental. Geographic supply concentration centers on Taiwan for image signal processors, South Korea for MIPI bridge components, and Germany for MEMS sensor fabrication. Raw material dependencies include silicon wafers, automotive-grade lens glass, and rare-earth elements for ultrasonic transducers. Single-source vulnerability in Taiwanese foundry capacity exposes tier-1s to allocation volatility during demand spikes. Distribution runs through direct OEM contracts with Continental, Bosch, and ZF anchoring procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for automotive-grade image processors prop pricing power for suppliers with captive sourcing or long-term allocation agreements.
For Market Incumbents: Cement market position through backward integration into image processing chipsets and lens assembly operations to offset Taiwanese foundry concentration risk. Secure ISO 26262 ASIL-D certification pipelines ahead of UN R79 amendment deadlines to defend against emerging software-centric challengers. Prioritize capacity addition in German engineering clusters where KBA homologation proximity accelerates validation cycles. For New Entrants and Emerging Players: Aftermarket distributors in Eastern Europe represent the most penetrable channel partner type for retrofit surround-view kits targeting aging commercial fleets. White-space targets include camera-only configurations for urban delivery vehicles and edge AI modules for parking space detection. Pursue white-label arrangements with emerging EV brands in China where MIIT GB standards create compliance-driven replacement demand. For Investors and Strategic Acquirers: Tier-1 consolidation announcements involving sensor fusion software assets are the leading indicator that valuation multiples for autonomous parking capabilities are resetting upward. Long-term viability favors targets with validated camera-radar fusion algorithms and established OEM platform relationships. Watch for MIIT GB standard enforcement timelines as inflection signal for Chinese aftermarket replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Software Acquisition | Consolidates camera-radar-LIDAR processing under unified architectures for UN R79 compliance. |
| Captive Semiconductor Sourcing | Secures image signal processor allocation from Taiwanese foundries amid capacity constraints. |
| Edge AI Module Development | Enables on-device neural processing for real-time parking space detection without cloud dependency. |
| Aftermarket Channel Expansion | Targets Eastern European commercial fleets with retrofit camera-only surround-view configurations. |
| ASIL-D Certification Investment | Accelerates functional safety validation for hands-free maneuvering systems under amended UN R79. |
Study Parameters
Vehicle production databases, IHS Markit registration data, and SEC filings from tier-1 suppliers formed the secondary backbone, supplemented by customs records tracking camera module trade flows. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads validated demand assumptions. Bottom-up unit economics triangulated against top-down market sizing across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions.
Historical trendline analysis of surround-view system penetration rates by vehicle segment anchored the projection framework across the analysis window. Segmentation modeling incorporated technology modality, end-user supply chain position, and application maturity to derive CAGRs. Industry-specific forecast inputs included Euro NCAP scoring protocol evolution and NHTSA FMVSS 111 enforcement intensity.
Caveats apply where semiconductor allocation volatility, UN R79 amendment implementation delays, or MIIT GB standard enforcement gaps could materially shift the outlook. Forecasts reflect assumptions about OEM platform standardization timelines and tier-1 consolidation trajectories. A small set of named triggers—foundry capacity expansion, automated parking homologation acceleration, and Chinese EV export growth—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market