
 Global Automotive Intelligence Park Assist System Market | 2026-2036
Global Automotive Intelligence Park Assist System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Intelligence Park Assist System Market Intelligence
A shortage of embedded software engineers with automotive functional safety expertise is redrawing competitive boundaries in park assist development. Continental AG leverages its ultrasonic sensor manufacturing scale to anchor supply contracts with European OEMs. Robert Bosch GmbH competes through in-house production of radar modules and camera systems. Valeo SA specializes in sensor fusion algorithms that integrate lidar with legacy parking architectures.
Automotive intelligence park assist systems combine ultrasonic, camera, radar, and lidar sensors with real-time processing units to detect obstacles, measure parking bay dimensions, and execute steering maneuvers with minimal driver intervention, typically operating within detection ranges of 0.3 to 5.0 meters depending on sensor modality. The primary commercial purpose is to reduce parking collisions, compress parking durations in dense urban environments, and enable remote parking in confined spaces. Camera-based systems dominate value contribution due to higher per-unit pricing and integration complexity with surround-view displays. Autonomous parking technology represents the fastest-expanding segment as automakers pursue SAE Level 4 capabilities in structured parking facilities. Electric vehicle applications concentrate margin pools because EV architectures accommodate higher-voltage compute platforms and over-the-air update cycles.
The EU's Vehicle General Safety Regulation and the U.S. NHTSA's New Car Assessment Program are tightening requirements for rearward and surround visibility, directly mandating sensor-based parking assistance in new vehicle certifications. Japan's METI has issued guidelines for autonomous parking validation in commercial parking structures, creating a regulatory pathway for remote parking deployment. China's MIIT enforces GB standards for advanced driver assistance system performance that encompass automatic parking functions. Stakeholders must monitor divergence between regional test protocols for autonomous parking to avoid redundant homologation investments.
Market Dynamics
The automotive intelligence park assist system market is being fundamentally restructured by the EU's Vehicle General Safety Regulation mandating advanced driver assistance features, which compresses homologation timelines and forces OEMs to accelerate multi-sensor fusion platform deployment across vehicle lineups.
Growth Catalysts
- EU Vehicle General Safety Regulation:Mandates for advanced driver assistance features in new vehicle certifications create immediate demand pull across European vehicle assemblers.
- China's tier-one cities:Parking space scarcity combined with electric vehicle penetration concentrates adoption in Beijing, Shanghai, and Shenzhen.
- Multi-sensor fusion platforms:Integration of ultrasonic, radar, camera, and lidar sensors enables SAE Level 4 autonomous parking capabilities in structured facilities.
Market Restraints
- Embedded software engineer shortage:Functional safety expertise scarcity under ISO 26262 limits development velocity for park assist algorithm teams.
- Sensor cost structure:Lidar module pricing remains prohibitive for mass-market vehicle segments despite manufacturing scale improvements.
- Regional test protocol divergence:Differences between EU, US NHTSA, and China MIIT validation requirements force redundant homologation investments.
Strategic Opportunities
- Japan's METI autonomous parking guidelines:Validation frameworks for commercial parking structures open deployment pathways for remote parking systems.
- Electric vehicle architectures:Higher-voltage compute platforms and over-the-air update cycles in EVs accommodate more sophisticated park assist software stacks.
- Surround-view camera convergence:Integration of park assist with 360-degree display systems creates bundled value propositions for premium vehicle segments.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D compliance for autonomous parking algorithms extends development cycles by 12-18 months.
- Legacy parking architecture integration:Retrofitting sensor fusion platforms into existing ultrasonic-only vehicle platforms creates engineering complexity and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Intelligence Park Assist System Market |
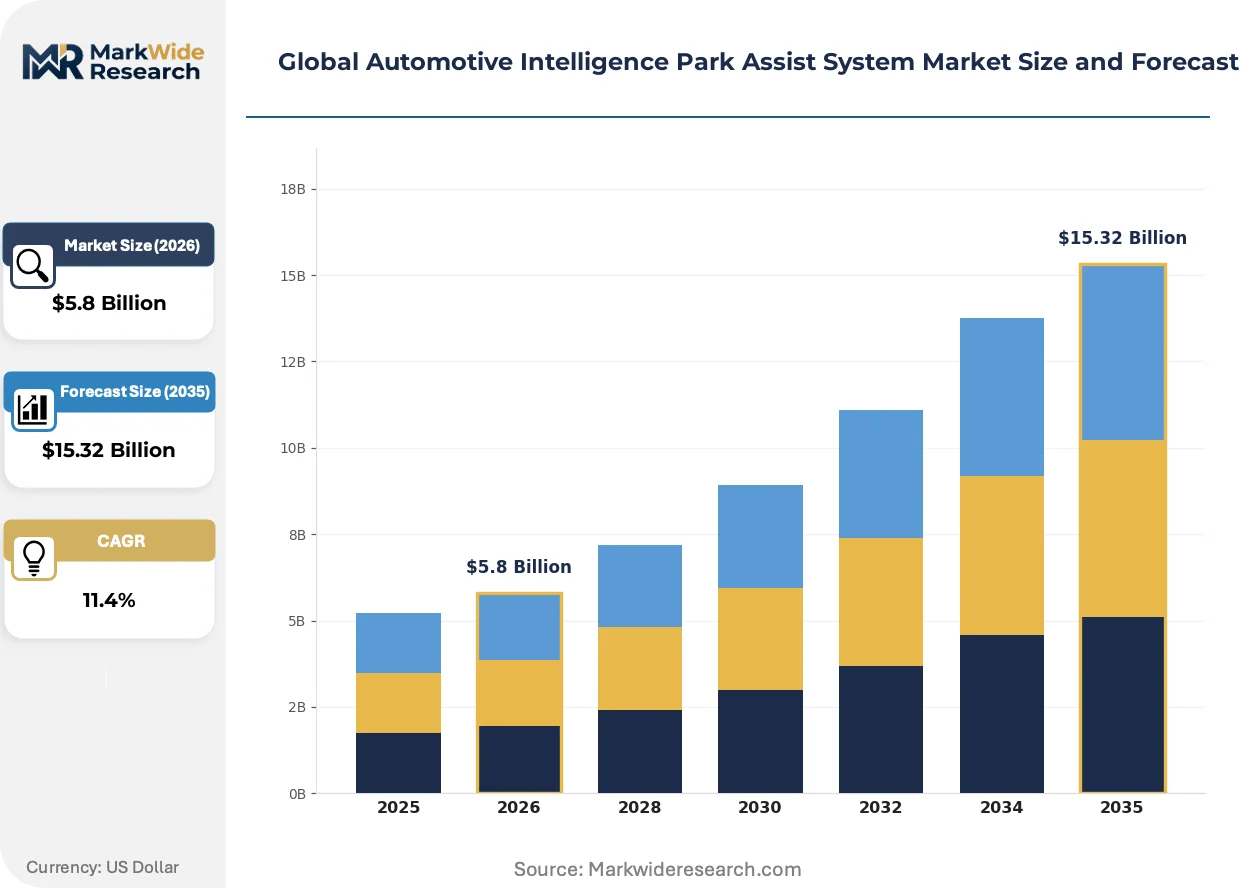
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Camera-Based Systems, Radar Sensors, Lidar Solutions Technology: Active Parking Assist, Semi-Autonomous Parking, Autonomous Parking, Remote Parking Assist Application: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Trucks, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Valeo SA, NXP Semiconductors, Magna International, Aisin Seiki Co., Ltd., Denso Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Intelligence Park Assist System Market Strategic Shifts & Innovations
Sensor modality convergence and regulatory mandate acceleration are compressing development cycles while reshaping competitive boundaries around software-defined parking capabilities.
Camera-based park assist systems with surround-view integration are supplanting ultrasonic-only architectures in premium vehicle segments. German and Japanese OEMs are scaling orders for multi-camera platforms that merge visual odometry with legacy parking sensors. This supplanting of single-modality systems is compressing margins for pure-play ultrasonic suppliers while elevating software integration capabilities as the primary competitive differentiator.
The EU's Vehicle General Safety Regulation mandates advanced driver assistance features including sensor-based parking assistance for all new vehicle type approvals. European vehicle assemblers are accelerating homologation timelines to meet these requirements ahead of enforcement deadlines. Premium passenger car OEMs in Germany are prioritizing multi-sensor fusion platforms to satisfy both regulatory compliance and consumer positioning objectives.
Procurement patterns for park assist systems are consolidating around tier-one suppliers capable of delivering integrated sensor fusion software stacks. Chinese EV manufacturers are bypassing traditional component distributors to contract directly with algorithm developers and sensor module producers. This channel disintermediation is most visible in China's tier-one cities where parking space scarcity and EV penetration create concentrated demand for advanced park assist capabilities.
Global Automotive Intelligence Park Assist System Market Segmentation
Park assist system architectures fragment sharply across sensor modalities and automation levels, with margin concentration shifting toward software-defined fusion platforms. Technology choices directly determine homologation pathways under divergent regional safety regulations.
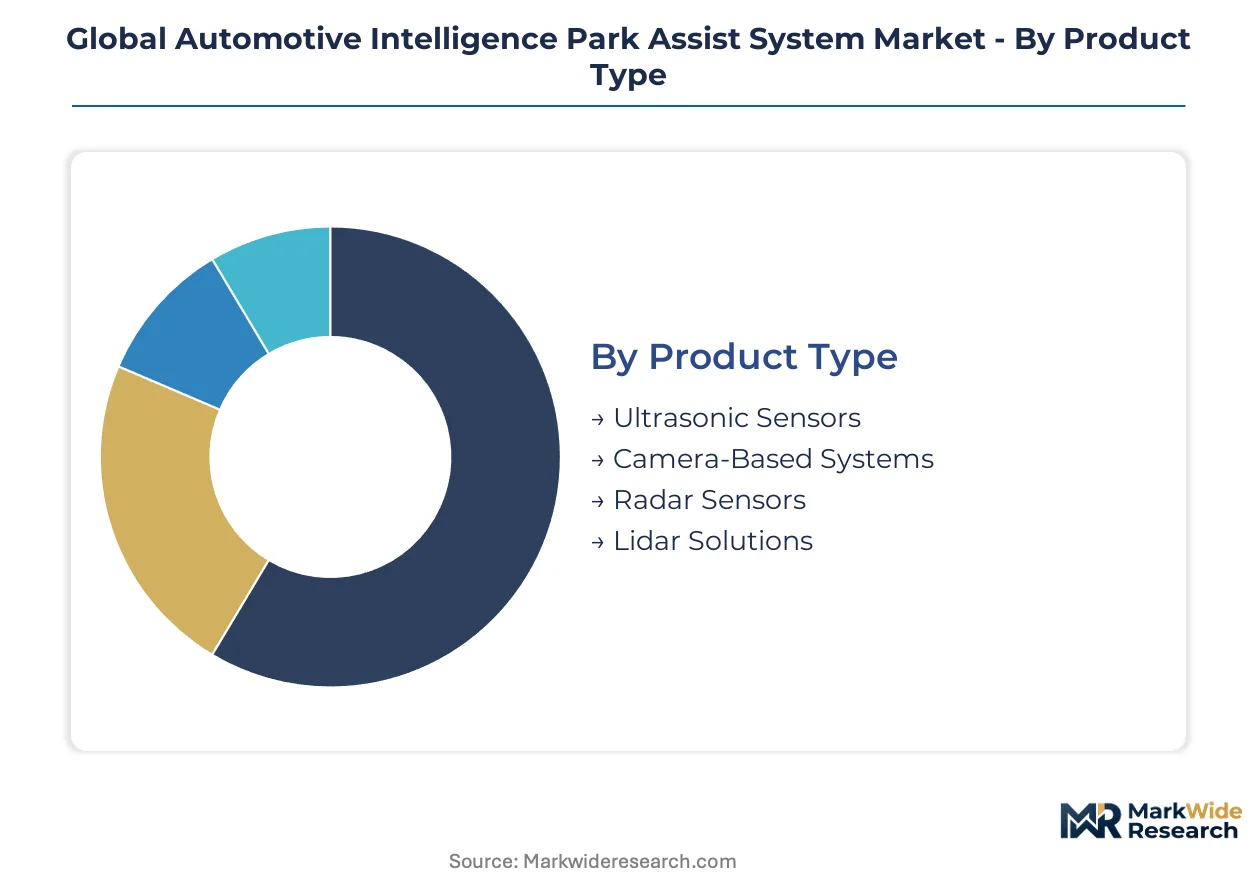
Product Type:
Camera-based systems command the highest per-unit margins due to integration complexity with surround-view displays and higher processing requirements. Ultrasonic sensors anchor volume production through mature manufacturing economics and established supply chains.
- Ultrasonic Sensors:Piezoelectric transducers operating at 40-50 kHz detect obstacles within 0.3-2.5 meter ranges through time-of-flight measurement. German and Japanese OEMs specify these for entry-level vehicle lineups where cost containment dominates procurement criteria.
- Camera-Based Systems:Multi-camera arrays with 190-degree fisheye lenses generate stitched surround-view imagery processed through neural network-based depth estimation. Premium passenger car manufacturers in Germany scale orders for these platforms to satisfy EU Vehicle General Safety Regulation visibility mandates.
- Radar Sensors:77 GHz millimeter-wave modules penetrate weather conditions that degrade optical sensors.
- Lidar Solutions:Solid-state and mechanical scanning units deliver centimeter-precision ranging for structured parking facilities.
The dominant share belongs to Camera-Based Systems, while Lidar Solutions is closing the gap fastest.
Technology:
Autonomous parking capabilities concentrate development investment as automakers pursue SAE Level 4 validation for structured facilities. Active parking assist retains the largest installed base through regulatory minimum compliance requirements.
- Active Parking Assist:Systems automate steering while requiring driver throttle and brake control, typically using ultrasonic sensors with basic trajectory planning. Mass-market vehicle segments in China specify these for cost-optimized compliance with MIIT GB standards.
- Semi-Autonomous Parking:Combined longitudinal and lateral control with driver supervision through integrated sensor fusion. European vehicle assemblers deploy these platforms to satisfy compressed homologation timelines under EU mandates.
- Autonomous Parking:SAE Level 4 operation without driver presence in facility, enabled by vehicle-to-infrastructure communication and high-definition mapping.
- Remote Parking Assist:Smartphone-app-controlled maneuvering from outside vehicle at low speeds.
Active Parking Assist holds the largest current deployment, though Autonomous Parking exhibits the steepest expansion trajectory.
Application:
Electric vehicle architectures accommodate higher-voltage compute platforms that enable more sophisticated park assist software stacks. Passenger cars dominate absolute unit volume across all automation tiers.
- Passenger Cars:Multi-sensor fusion platforms scale across compact through luxury segments with feature differentiation by price tier. China's tier-one cities concentrate demand where parking space scarcity intersects with high EV penetration rates.
- Electric Vehicles:Dedicated high-voltage electrical architectures support centralized compute domains and over-the-air update cycles for continuous algorithm refinement. Battery-electric platforms in Germany and Japan prioritize these systems for technology positioning.
- Light Commercial Vehicles:Fleet operators specify parking assistance for urban delivery optimization.
- Heavy-Duty Trucks:Maneuvering assistance for confined loading docks and rest areas.
Passenger Cars maintains the dominant application share, with Electric Vehicles gaining ground most rapidly.
End User:
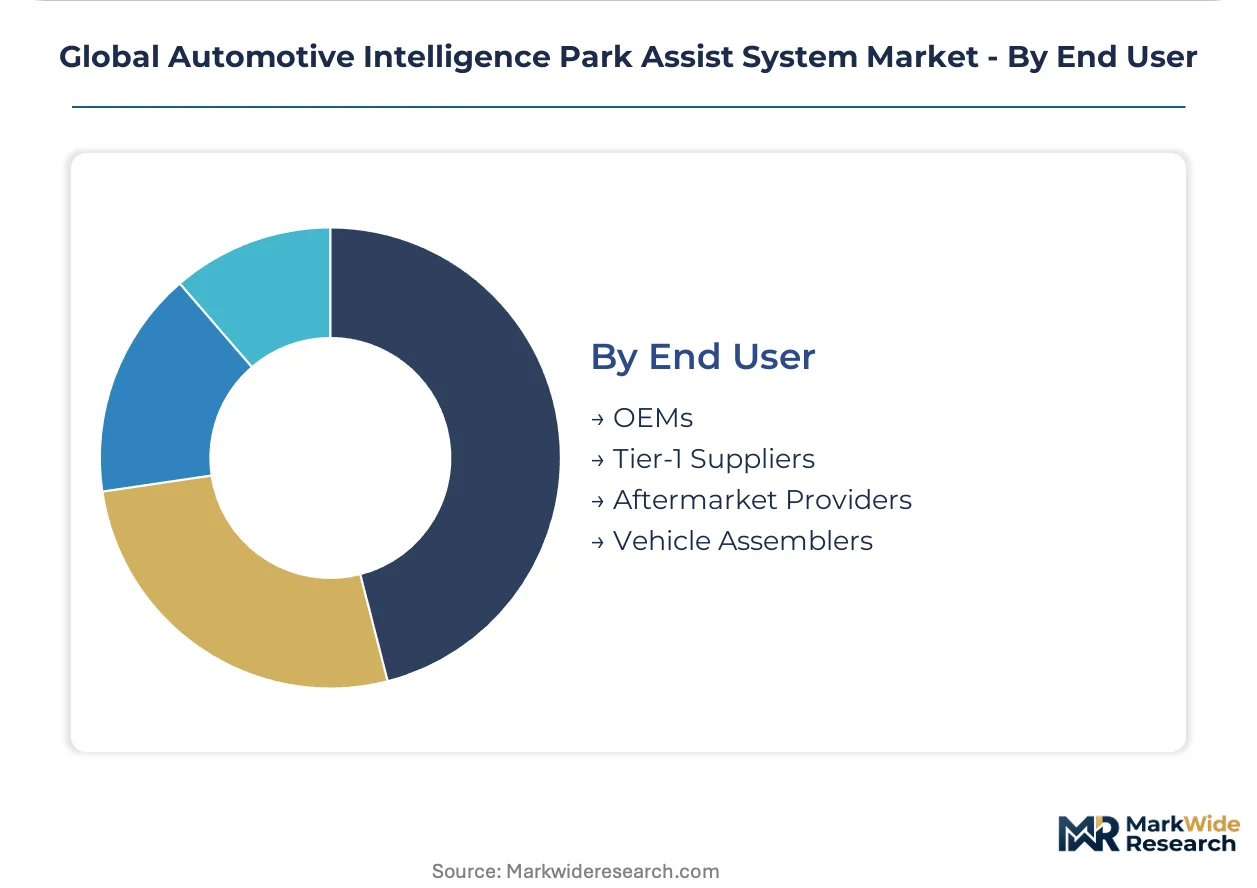
Tier-1 suppliers capture margin through integrated software stack delivery while OEMs increasingly contract directly with algorithm developers. Aftermarket channels serve vehicle retrofit demand where factory installation was omitted.
- OEMs:Vehicle manufacturers specify complete park assist systems for factory installation with multi-year platform commitments. German premium OEMs anchor European demand through multi-sensor fusion procurement.
- Tier-1 Suppliers:Integrated module producers deliver sensor fusion software with hardware bundles to multiple OEM customers. These suppliers compete on ISO 26262 functional safety certification velocity.
- Aftermarket Providers:Retrofit kit distributors serve vehicle owners seeking parking assistance upgrades.
- Vehicle Assemblers:Contract manufacturers integrate specified subsystems into final vehicle production.
OEMs command the largest procurement volume, while Tier-1 Suppliers are expanding their influence fastest through software integration capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards enforcement is concentrating development investment in China's tier-one cities. Germany's KBA accelerates homologation timelines under EU Vehicle General Safety Regulation mandates. Japan's METI guidelines create regulatory pathways for autonomous parking validation in commercial structures.
China
Parking space scarcity in Beijing, Shanghai, and Shenzhen intersects with electric vehicle penetration to concentrate demand. MIIT enforces GB standards for advanced driver assistance system performance encompassing automatic parking functions. Shenzhen-based EV manufacturers contract directly with algorithm developers, bypassing traditional component distributors.
Germany
Premium passenger car OEMs scale orders for multi-sensor fusion platforms to satisfy regulatory and consumer positioning objectives. KBA compresses homologation timelines under EU Vehicle General Safety Regulation enforcement. Stuttgart and Munich anchor European procurement for integrated sensor fusion software stacks.
Japan
Domestic OEMs pursue SAE Level 4 capabilities in structured parking facilities. METI issued guidelines for autonomous parking validation in commercial parking structures, creating deployment pathways for remote parking systems. Nagoya and Tokyo metropolitan areas concentrate technology validation partnerships.
United States
NHTSA's New Car Assessment Program tightens requirements for rearward and surround visibility, mandating sensor-based parking assistance. Fleet operators in urban delivery segments specify parking assistance for optimization. Detroit and California tech corridors drive procurement for camera-based surround-view integration.
South Korea
Domestic battery-electric platforms prioritize park assist systems for technology positioning. MFDS alignment with international functional safety standards supports ISO 26262 certification velocity. Seoul Capital Area concentrates R&D investment for neural network-based depth estimation processing.
Global Automotive Intelligence Park Assist System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around tier-one suppliers capable of delivering integrated sensor fusion software stacks alongside specialized component manufacturers. Three archetypes dominate: diversified automotive suppliers with captive sensor production, semiconductor specialists with functional safety certification, and algorithm-focused software developers. Competitive moves center on strategic partnerships for sensor fusion integration and geographic expansion into China's tier-one cities.
Within the diversified automotive supplier tier, Robert Bosch GmbH, Continental AG, and Valeo SA exemplify different strategic positions. Bosch represents the vertically integrated archetype with in-house radar and camera module production. Continental anchors supply relationships through ultrasonic sensor manufacturing scale. Valeo occupies a specialization position in sensor fusion algorithms. These three entities collectively illustrate how procurement patterns consolidate around suppliers capable of delivering complete hardware-software bundles.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Valeo SA |
| NXP Semiconductors |
| Magna International |
| Aisin Seiki Co., Ltd. |
| Denso Corporation |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Ultrasonic sensor manufacturing scale in Germany and China anchors cost floors across park assist tiers, concentrating margin leverage with tier-one suppliers while compressing pricing power for pure-play component vendors serving mass-market vehicle segments.
Pricing Analysis
Geographic price spreads between European and Chinese procurement contracts exceed factor-of-two differentials, driven by divergent certification requirements under EU Vehicle General Safety Regulation versus MIIT GB standards. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor modality complexity and ISO 26262 ASIL certification grade. Cost compression in ultrasonic-only tiers intensifies as Chinese EV manufacturers bypass traditional distributors to contract directly with algorithm developers. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while German premium OEMs prioritize functional safety certification velocity over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for lidar module imports, compressing margins for European system integrators dependent on Chinese solid-state sensor production. Manufacturing concentration rests on Germany, China, and Japan for ultrasonic transducers, camera modules, and radar substrates respectively. Raw material dependencies span silicon wafers for image sensors, rare earth elements for piezoelectric ceramics, and gallium arsenide for millimeter-wave chips. Single-source vulnerability in solid-state lidar emitter arrays creates supply chain risk. Distribution runs through tier-one supplier direct contracts with OEM platform engineering teams, disintermediating traditional component distributors in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
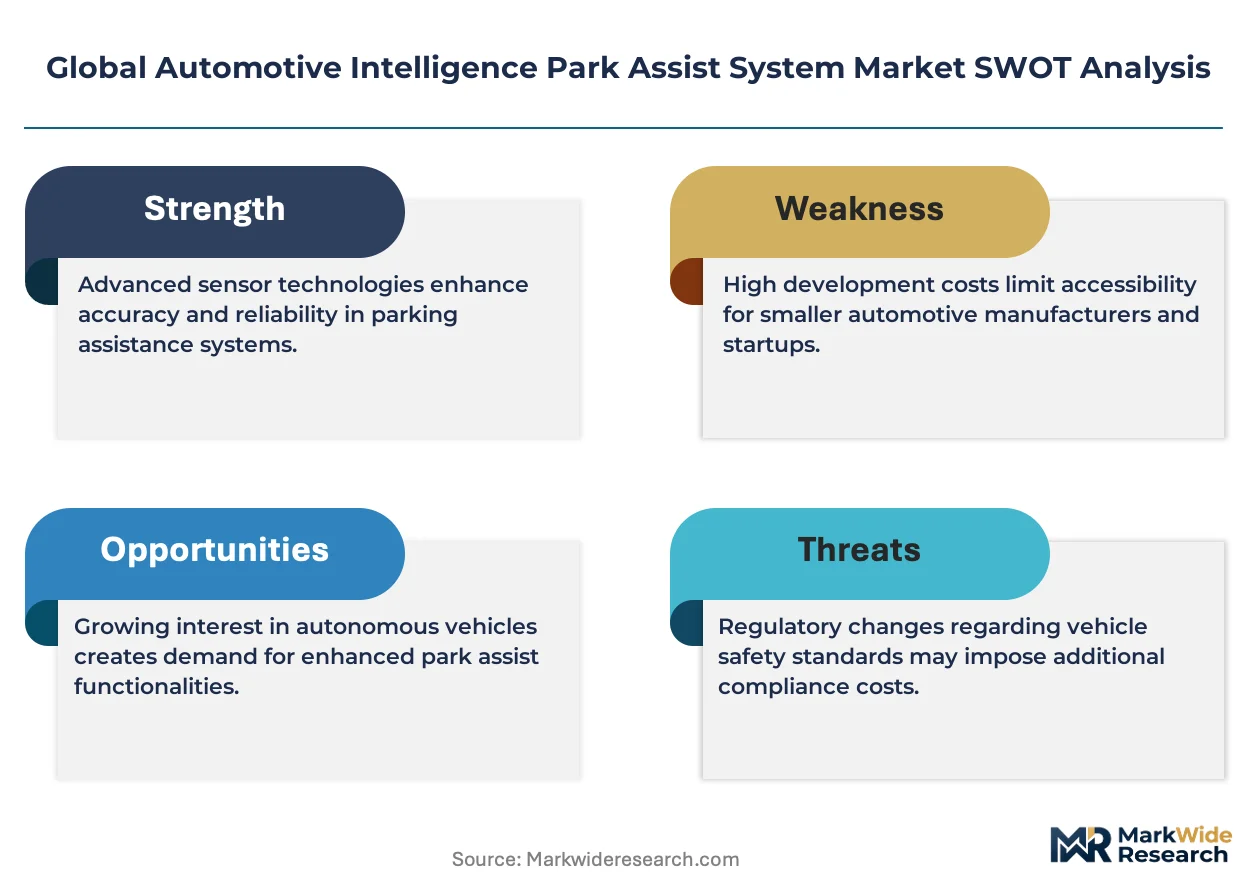
Incumbents face substitution pressure from smartphone-based remote parking apps that leverage vehicle-to-infrastructure connectivity, threatening to commoditize basic park assist functionality in mass-market segments.
For Market Incumbents: Shield software-defined parking capabilities through backward integration into sensor fusion algorithm development, countering disintermediation by direct OEM-contracting patterns in Shenzhen and Shanghai. Prioritize ISO 26262 ASIL-D certification velocity to compress homologation timelines under EU Vehicle General Safety Regulation enforcement, defending margin position against tier-one suppliers with captive functional safety expertise. For New Entrants and Emerging Players: Anchor in aftermarket retrofit channels for legacy vehicle fleets where factory-installed park assist was omitted, particularly in China's tier-one cities with acute parking space scarcity. Target surround-view camera integration partnerships with premium vehicle service centers as the most penetrable entry vector, leveraging smartphone-app-controlled maneuvering interfaces to bypass traditional tier-one supply relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among algorithm-focused software developers with over-the-air update capabilities serving electric vehicle architectures. Long-term viability centers on functional safety certification assets and direct OEM relationships rather than component manufacturing scale. Monitor Japan METI autonomous parking guideline enforcement as the inflection signal for SAE Level 4 validation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Standardization | Reduces homologation redundancy across EU, US NHTSA, and China MIIT test protocols for tier-one suppliers. |
| Software-Defined Vehicle Investment | Enables over-the-air algorithm refinement for electric vehicle park assist systems in Germany and Japan. |
| Sensor Module Supply Agreement | Secures gallium arsenide and silicon wafer allocations for radar and camera production scaling. |
| Functional Safety Certification Partnership | Accelerates ISO 26262 ASIL-D compliance velocity for autonomous parking algorithm deployment. |
| Geographic Manufacturing Footprint Expansion | Localizes production in China's tier-one cities to serve BYD, NIO, and XPeng direct contracting patterns. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution channel managers, and automotive functional safety auditors, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from diversified automotive suppliers, and MIIT GB standard enforcement records. Bottom-up unit economics from sensor module bill-of-materials were triangulated with top-down market sizing derived from OEM platform commitment disclosures.
Variance decomposition across sensor modality, automation level, vehicle propulsion architecture, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates and content-per-vehicle expansion trajectories, incorporating electric vehicle penetration curves and parking assistance mandate enforcement timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued EU Vehicle General Safety Regulation enforcement and MIIT GB standard adherence; material deviation in autonomous parking validation timelines or lidar cost reduction curves would warrant model refresh. Forecasts reflect base-case assumptions regarding functional safety engineer availability and tier-one supplier consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market