
 Automotive Surround View Systems Market | 2026-2036
Automotive Surround View Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Surround View Systems Market Intelligence
Camera module sourcing from single-tier suppliers to multi-vendor ecosystems is shifting as automakers seek cost flexibility and supply resilience. Continental AG leverages in-house lens and sensor integration to control quality across European assembly lines. Valeo anchors its position through specialized fish-eye optics and real-time stitching algorithms for premium OEM programs. Magna International Inc. competes by extending manufacturing scale across North American and Asian plants.
Automotive surround view systems combine multiple ultra-wide-angle cameras with image-processing hardware to generate a composite top-down or three-dimensional vehicle perspective, typically employing four to six cameras with 180-degree fields of view and high dynamic range sensors for low-light performance. These systems reduce parking collisions and pedestrian accidents by eliminating blind spots around vehicle perimeters. Processor modules lead hardware value capture due to the computational intensity of real-time image fusion and distortion correction. Electric vehicles represent the fastest-growing vehicle-type segment as EV architectures prioritize sensor-rich platforms and software-defined cabin experiences.
Euro NCAP protocols and NHTSA Federal Motor Vehicle Safety Standard 111 mandate expanded rear and side visibility, directly expanding camera count per vehicle platform. ECE R46 regulations in Europe and Japan's Ministry of Land, Infrastructure, Transport and Tourism guidelines further standardize camera-based indirect vision systems for commercial and passenger applications. Stakeholders must monitor how evolving UN R158 and UN R159 homologation requirements reshape camera resolution minimums and software validation burdens across export markets.
Market Dynamics
Camera-to-processor integration density is restructuring competitive advantage as automakers consolidate electronic control units and demand real-time software updates over-the-air.
Growth Catalysts
- Euro NCAP 2026 protocols:Expanded vulnerable road user detection requirements are mandating camera coverage of vehicle corners and rear zones, directly expanding per-vehicle camera counts.
- EV platform architectures:Battery-electric vehicle skateboard designs prioritize flat underbody packaging that accommodates multi-camera routing without drivetrain interference.
- High dynamic range sensors:HDR image sensors with 120 dB dynamic range are eliminating the need for separate low-light and daytime camera variants, reducing bill-of-material complexity.
Market Restraints
- Image sensor wafer allocation:Automotive-grade CMOS sensors compete with smartphone and industrial imaging for foundry capacity at TSMC and Samsung, creating input cost volatility.
- Software validation burdens:UN R158 and UN R159 homologation requirements impose extensive test mileage documentation that extends development cycles.
- Optical component concentration:Precision glass lens grinding capacity clusters in German and Japanese supplier networks, creating geographic supply concentration risk.
Strategic Opportunities
- Commercial vehicle retrofit:ECE R46 regulations for trucks and buses are opening aftermarket surround view installation demand across European fleet operators.
- Camera-lidar fusion:Convergence of surround view cameras with solid-state lidar modules is enabling unified perception stacks for automated parking.
- India PLI scheme:Production-linked incentives for automotive electronics manufacturing are attracting component assembly investments for domestic OEM programs.
Industry Challenges
- Embedded vision engineering:Shortage of engineers with expertise in real-time image stitching and geometric calibration is constraining R&D velocity at tier-one suppliers.
- Legacy vehicle integration:Controller area network bandwidth limitations in older vehicle platforms complicate retrofit of high-resolution multi-camera systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Surround View Systems Market |
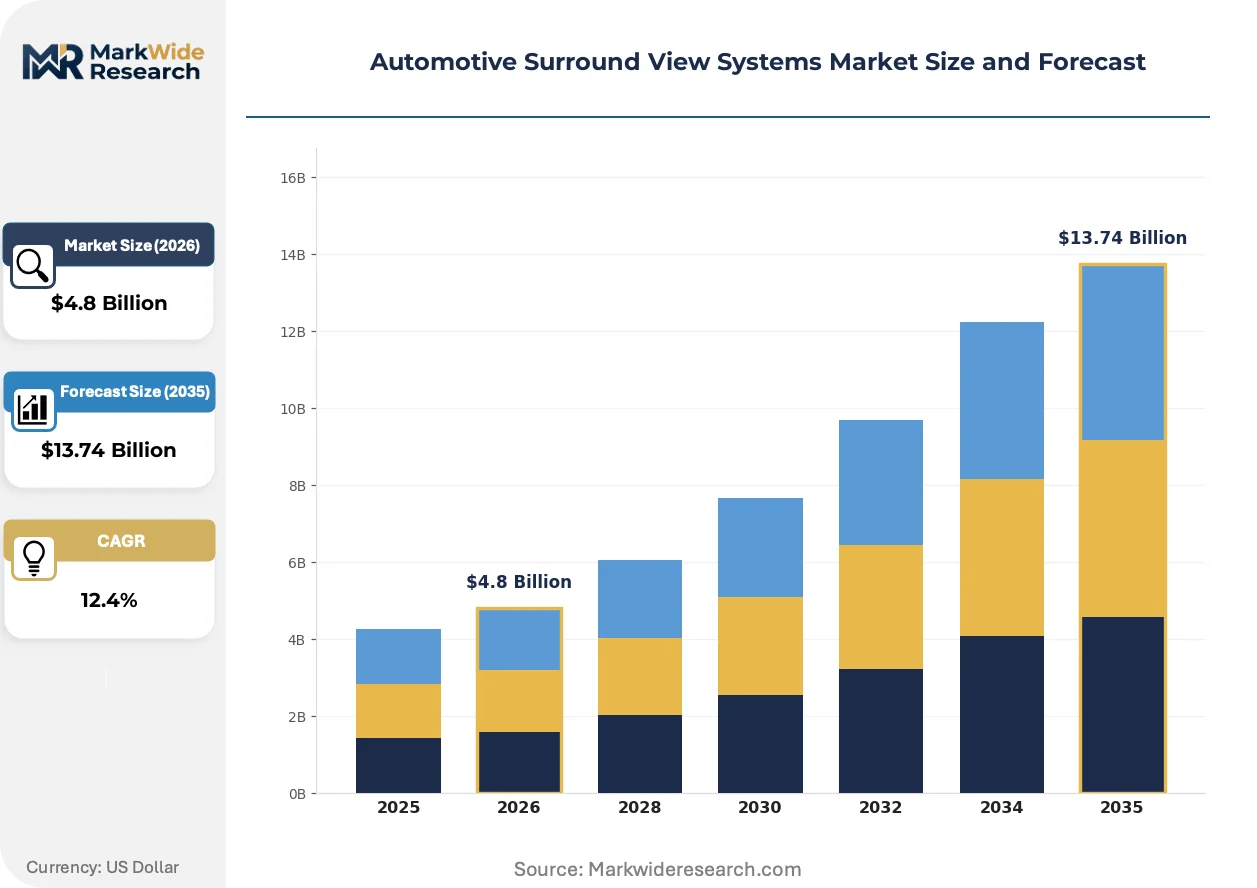
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.74 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Imaging, High-Definition Cameras, Processor Modules, Display Systems Technology: Infrared Sensors, Optical Sensors, Digital Signal Processing, Wireless Technologies End User: OEMs, Aftermarket Segment, Fleet Operators, Logistics Providers Vehicle Type: SUVs, Sedans, Commercial Vehicles, Electric Vehicles |
| Companies Covered | Continental AG, Renesas Electronics Corporation, Valeo, Denso Corporation, OmniVision Technologies, Inc., Magna International Inc., NXP Semiconductors N.V., Hyundai Mobis, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Surround View Systems Market Strategic Shifts & Innovations
Deep learning inference at the camera edge is compressing latency budgets and enabling new safety functions without central processor dependency.
Neural network-based image enhancement is automating real-time denoising and dynamic range expansion that previously required dedicated hardware pipelines. Tier-one suppliers are deploying tensor processing units directly into camera modules for premium EV programs. This distributed intelligence architecture is automating the shift from centralized domain controllers toward zonal computing topologies.
NHTSA Federal Motor Vehicle Safety Standard 111 revisions are expanding rear-visibility field-of-view requirements for light trucks and SUVs. The rulemaking is forcing redesigns of camera mounting positions and lens specifications. Heavy-duty pickup manufacturers are responding with integrated tailgate camera modules that combine rear-view and surround view feeds.
Fleet procurement departments are consolidating surround view specifications across vehicle classes to reduce service training and spare parts complexity. Large commercial operators are mandating standardized camera interfaces and diagnostic protocols across mixed-brand fleets. This specification consolidation is most visible in North American last-mile delivery vehicle procurement.
Automotive Surround View Systems Market Segmentation
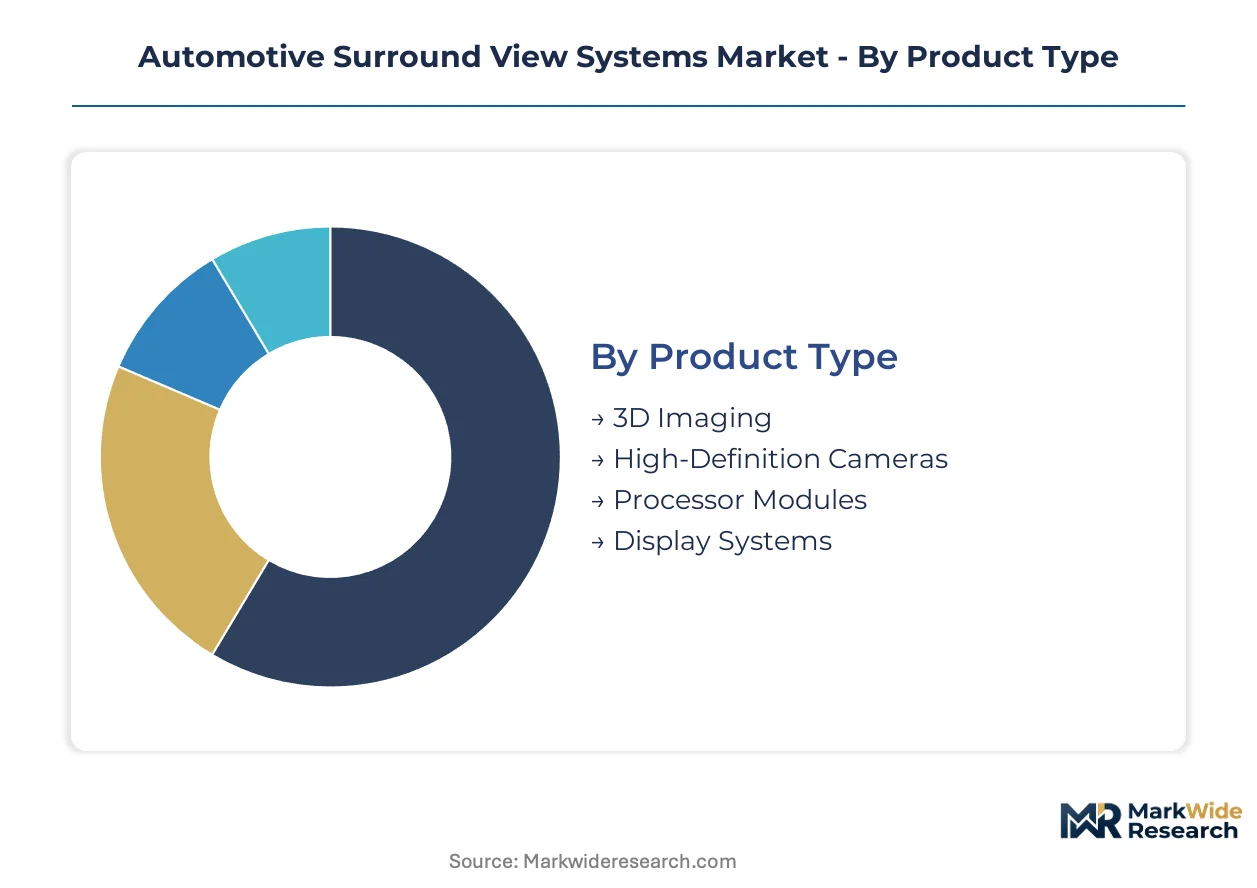
Segmentation in automotive surround view systems reveals how hardware specifications, software architectures, and buyer procurement patterns diverge across vehicle platforms. Camera resolution tiers and processing capabilities create distinct value bands that align with OEM program budgets and regulatory compliance thresholds.
Product Type:
Buyers prioritize processing power and image fidelity when selecting hardware configurations, with cost-performance tradeoffs driving tier placement across vehicle lines.
- 3D Imaging:Advanced depth-perception algorithms synthesize multi-camera feeds into volumetric vehicle representations with real-time obstacle detection. Premium German and Japanese OEMs specify these systems for automated parking programs, with NHTSA rear-visibility mandates accelerating fitment in North American luxury SUVs.
- High-Definition Cameras:Ultra-wide-angle lens assemblies with 180-degree fields of view capture high-dynamic-range imagery for low-light performance. Mass-market electric vehicle platforms in the United States and Japan standardize these modules to meet Euro NCAP vulnerable road user protocols without processor redundancy.
- Processor Modules:Edge-computing silicon handles real-time image stitching and geometric distortion correction.
- Display Systems:Center-stack and digital instrument cluster screens render composite top-down views.
Processor modules lead on scale; 3D imaging leads on momentum.
Technology:
Sensor modality choices determine environmental robustness and supply chain sourcing flexibility for tier-one integrators.
- Infrared Sensors:Thermal detection layers extend operational range in fog and darkness beyond visible-spectrum limitations. German commercial vehicle manufacturers deploy these for ECE R46-compliant truck surround view, with fleet operators in the United States specifying hybrid visible-IR configurations for 24-hour logistics operations.
- Optical Sensors:CMOS image sensors with 120 dB dynamic range consolidate daytime and nighttime functionality into single hardware variants. Japanese and South Korean foundry supply constraints are pushing automakers toward multi-vendor qualification strategies for these components.
- Digital Signal Processing:FPGA and ASIC architectures execute real-time geometric calibration.
- Wireless Technologies:Low-latency transmission protocols enable camera module placement flexibility.
Optical sensors dominate current volumes; infrared configurations are climbing fastest.
End User:
Procurement scale and specification control separate volume buyers from fragmented installation channels.
- OEMs:Original equipment manufacturers dictate camera counts, resolution minimums, and software validation protocols through platform engineering specifications. German and Japanese automakers integrate surround view as standard equipment across electric vehicle architectures, with NHTSA Federal Motor Vehicle Safety Standard 111 compliance driving US pickup truck program adoption.
- Aftermarket Segment:Independent installers retrofit camera systems to legacy vehicles lacking factory-equipped indirect vision. United States and European specialty equipment distributors serve this demand, though CAN bus bandwidth limitations in older vehicle platforms constrain high-resolution multi-camera deployments.
- Fleet Operators:Commercial vehicle owners mandate standardized camera interfaces across mixed-brand fleets.
- Logistics Providers:Last-mile delivery companies specify uniform surround view diagnostics for service efficiency.
OEMs anchor absolute volumes; fleet operators are gaining share fastest.
Vehicle Type:
Platform packaging constraints and electrification roadmaps reshape camera routing and sensor density requirements.
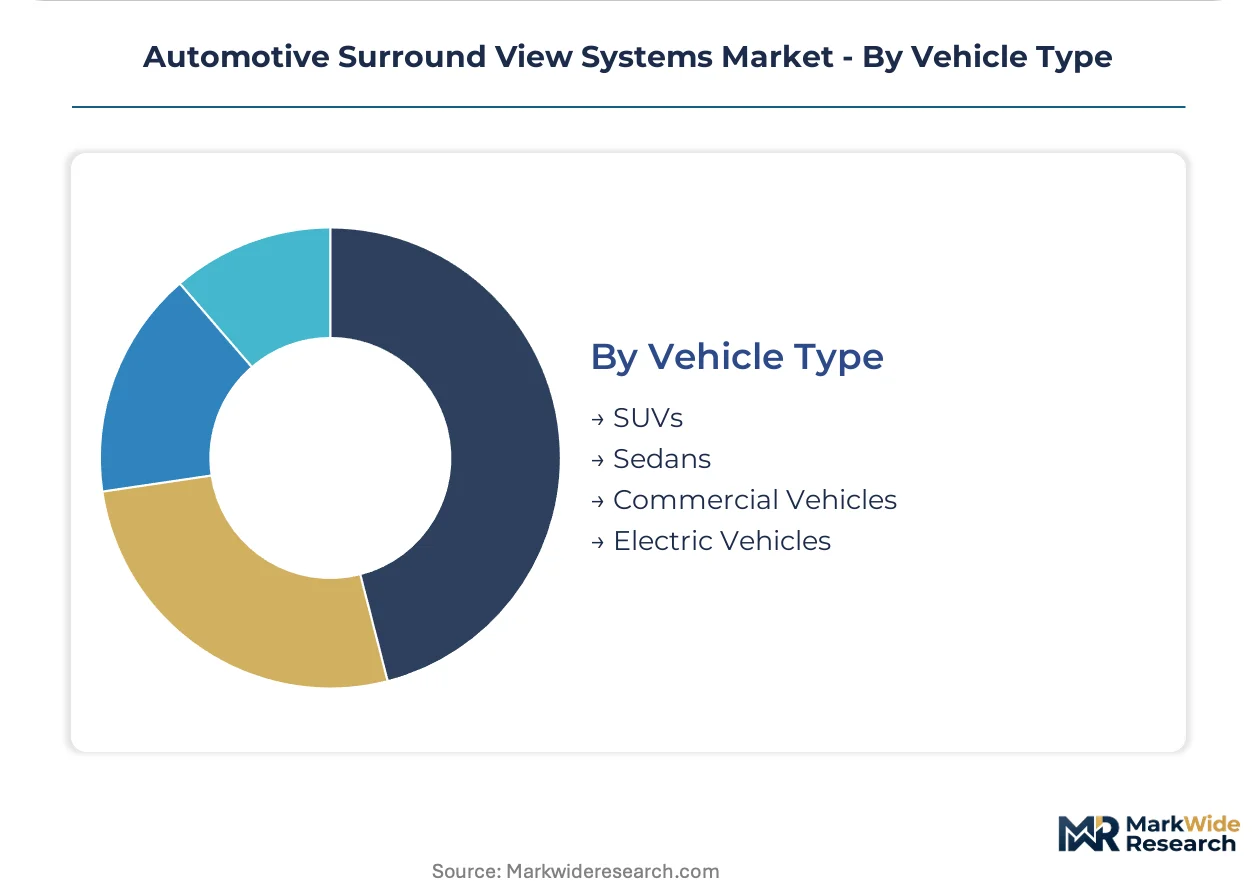
- Electric Vehicles:Skateboard battery architectures enable flat underbody cable routing without drivetrain interference, accommodating six-camera configurations. German and United States automakers prioritize these sensor-rich platforms for software-defined cabin experiences, with Euro NCAP 2026 protocols mandating expanded corner coverage.
- SUVs:Elevated ride heights and larger footprints demand comprehensive blind-spot elimination for parking maneuverability. Japanese and United States manufacturers specify surround view as standard equipment in mid-size and full-size segments, with integrated tailgate camera modules responding to NHTSA field-of-view expansions for light trucks.
- Sedans:Compact packaging limits camera placement options to bumper and mirror integrations.
- Commercial Vehicles:ECE R46 regulations mandate camera-based indirect vision for trucks and buses.
SUVs maintain volume leadership; electric vehicles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are reshaping where automotive surround view system suppliers locate assembly and calibration operations. NHTSA rear-visibility mandates in the United States impose stricter test documentation than equivalent Asian frameworks, pushing some component sourcing toward lower-burden export zones.
United States
Light truck and SUV manufacturers dominate procurement volumes as NHTSA Federal Motor Vehicle Safety Standard 111 revisions expand rear-visibility field-of-view requirements. The Detroit Three automakers specify integrated tailgate camera modules combining rear-view and surround view feeds. Michigan-based engineering centers coordinate validation protocols for cross-border Canadian assembly plants.
Germany
Premium OEMs mandate surround view as standard equipment across electric vehicle architectures, with KBA homologation procedures setting software validation benchmarks for EU export compliance. Stuttgart and Munich engineering clusters specialize in real-time image stitching algorithms. Bavarian lens grinding suppliers anchor optical component concentration for fish-eye camera assemblies.
Japan
Ministry of Land, Infrastructure, Transport and Tourism guidelines standardize camera-based indirect vision systems for both passenger and commercial applications. Tokyo and Nagoya automakers integrate six-camera configurations into skateboard EV platforms. Kyushu semiconductor foundries face allocation pressure from competing smartphone sensor demand.
China
Domestic EV manufacturers prioritize sensor-rich platforms for software-defined cabin experiences, with MIIT standards accelerating local camera module qualification. Yangtze River Delta electronics assemblers scale multi-vendor sourcing strategies to circumvent foundry bottlenecks. Shenzhen processing hardware specialists compete on edge-computing silicon integration.
South Korea
Hyundai and Kia electric vehicle programs drive surround view adoption across mid-market segments, with MFDS-aligned validation protocols enabling EU market access. Seoul Capital Area tier-one suppliers consolidate electronic control unit architectures for over-the-air update capability. Busan-Ulsan manufacturing corridors specialize in high-dynamic-range sensor packaging.
Automotive Surround View Systems Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-defined zonal computing architectures. The supplier base concentrates around three strategic archetypes: integrated lens-sensor manufacturers, specialized image processing silicon vendors, and full-system integrators. Dominant competitive moves include backward integration into optical component production and strategic partnerships for over-the-air software update infrastructure.
Among European full-system integrators, Continental AG and Valeo exemplify the vertically integrated archetype controlling quality across assembly lines. Magna International Inc. represents the North American scale-driven position with manufacturing footprints spanning multiple continents. These three anchors illustrate how geographic production distribution and in-house component control separate premium-tier positioning from commodity module supply.
| Leading Market Players |
|---|
| Continental AG |
| Renesas Electronics Corporation |
| Valeo |
| Denso Corporation |
| OmniVision Technologies, Inc. |
| Magna International Inc. |
| NXP Semiconductors N.V. |
| Hyundai Mobis |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Fleet procurement consolidation across North American last-mile delivery operators is forcing standardization of camera interfaces and diagnostic protocols, compelling suppliers to absorb qualification costs while competing on volume scale rather than customization premiums.
Pricing Analysis
Input-cost pass-through from automotive-grade CMOS sensor foundry allocation pressures is compressing margins at the module assembly tier. Three-tier pricing structure across premium, standard, and economy levels separates 3D imaging systems with edge AI processors from basic four-camera configurations. Cost compression in the economy tier is intensifying because smartphone and industrial imaging demand competes for TSMC and Samsung wafer capacity. Fleet operators exhibit the highest price sensitivity due to multi-thousand-unit procurement scales, while premium German OEMs prioritize validation documentation over unit cost.
Supply Chain Analysis
Precision glass lens grinding capacity rests on German and Japanese specialty optics networks, creating geographic concentration risk for fish-eye camera assemblies. Automotive-grade CMOS sensors draw from South Korean and Taiwanese foundry supply, while processor modules source from Shenzhen and Seoul Capital Area packaging corridors. Single-source vulnerability in Bavarian lens grinding operations exposes the supply chain to regional disruption events. Distribution runs through tier-one system integrators with captive assembly lines adjacent to OEM vehicle plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Euro NCAP 2026 protocols mandate expanded corner camera coverage that only validated tier-one suppliers can deliver within shortened development windows.
For Market Incumbents: Lock in multi-year platform engineering specifications with German and Japanese OEMs before 2026 protocol deadlines close qualification windows. Deepen backward integration into optical component production to offset lens grinding concentration risk in Bavarian supplier networks. Prioritize over-the-air software update infrastructure as a retention lever against emerging silicon vendors offering zonal computing alternatives. For New Entrants and Emerging Players: Capture commercial vehicle retrofit demand across European fleet operators responding to ECE R46 compliance deadlines. Target India PLI scheme incentives for automotive electronics assembly to establish cost-competitive manufacturing without legacy European cost structures. Lead with standardized camera interfaces that reduce service training complexity for mixed-brand fleet procurement departments. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized image processing silicon vendors possessing tensor processing unit IP for edge camera deployment. Long-term viability favors suppliers with validated software stacks across multiple OEM programs rather than single-platform dependencies. Watch for consolidation signals when tier-one integrators exhaust internal R&D capacity for real-time stitching algorithm development.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Fleet procurement departments at United States last-mile operators mandate uniform camera interfaces across mixed-brand vehicle pools. |
| Software-Defined Vehicle Investment | German OEMs prioritize sensor-rich EV architectures with over-the-air update capability for surround view feature expansion. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract component assembly investments to serve domestic OEM programs with localized sourcing. |
| Backward Integration into Optics | Continental AG and Valeo control quality through in-house lens grinding to reduce dependency on Bavarian supplier concentration. |
| Camera-Lidar Fusion Development | Convergence with solid-state lidar enables unified perception stacks for automated parking at premium German and Japanese OEMs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 111 regulatory filings, and Euro NCAP protocol documentation. Bottom-up camera unit forecasts triangulated against top-down OEM platform content assumptions.
Segment-weighting across vehicle class, propulsion architecture, content per vehicle, and regional production clusters shaped the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical fitment rates applied to announced OEM platform timelines. Industry-specific inputs included announced EV skateboard architecture rollouts and regulatory compliance deadline schedules.
Foundry capacity reallocation, Euro NCAP protocol revision timing, and UN R158 homologation documentation requirements are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about OEM platform engineering specifications. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
China Automotive Camera Market