

Off-Road Machine High-Durability Wiring Harness Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Road Machine High-Durability Wiring Harness Systems Market Insights
Project finance for autonomous mining fleets is narrowing the competitive field to suppliers with balance-sheet depth and long-term service contracts. Yazaki Corporation leverages its integrated connector-to-harness manufacturing footprint to lock in multi-year supply agreements with heavy equipment OEMs. Sumitomo Electric Industries anchors its position through fluoropolymer insulation R&D that extends harness life in abrasive environments. Leoni competes by specializing in modular harness architectures that reduce field-replacement downtime for tier-1 component manufacturers.
Off-road machine high-durability wiring harness systems are engineered cable assemblies rated for vibration resistance, chemical exposure, and temperature extremes from minus 40 to 125 degrees Celsius, typically employing cross-linked polyethylene or fluoropolymer insulation with braided shielding to protect signal integrity in electromagnetic-noise environments. Their primary purpose is to distribute power and data reliably across engine, transmission, and implement control systems in vehicles that operate beyond paved infrastructure. Custom harness configurations command margin premiums because they integrate proprietary sensor arrays and CAN bus architectures specific to OEM platforms. Shielded harness demand is accelerating fastest in mining and military applications where electromagnetic compatibility failures carry catastrophic cost. Thermoplastic insulation remains the volume leader for construction equipment due to its cost-positioning in price-sensitive emerging markets.
EPA Tier 4 Final and EU Stage V emissions regulations are forcing OEMs to embed additional exhaust-temperature and aftertreatment sensors, directly expanding conductor counts and connector complexity in every harness. ISO 6722 and SAE J1128 standards govern conductor sizing and insulation performance, creating compliance barriers for suppliers lacking certified testing infrastructure. Brazil's national mining regulator and Australia's state-based workplace safety authorities impose equipment-availability mandates that shorten harness replacement intervals. Stakeholders must monitor how autonomous vehicle retrofits reshape harness specification requirements across OEM and aftermarket channels.
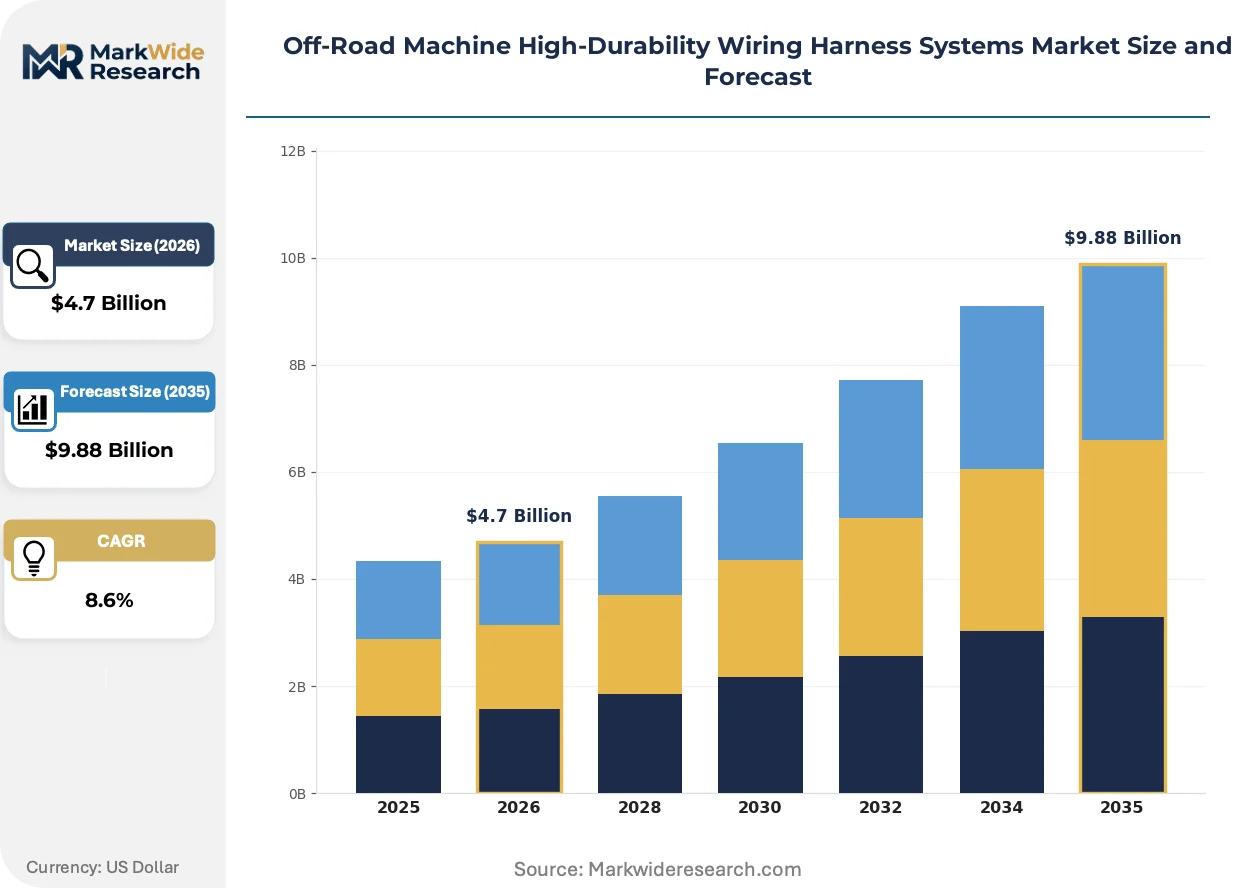
Market Dynamics
Mining fleet electrification is compressing harness replacement cycles while EPA Tier 4 Final and EU Stage V mandates multiply sensor integration requirements, forcing suppliers to recertify architectures every 18-24 months.
Growth Catalysts
- Autonomous haulage deployment:Australia's Pilbara region and Brazil's iron ore belt are retrofitting legacy fleets with redundant harness loops for fail-safe sensor networks.
- EPA Tier 4 Final mandates:Exhaust aftertreatment systems require additional temperature and NOx sensor circuits, expanding conductor counts per harness assembly.
- Fluoropolymer insulation advances:Extended service life in abrasive mining environments reduces total cost of ownership for high-availability operations.
Market Restraints
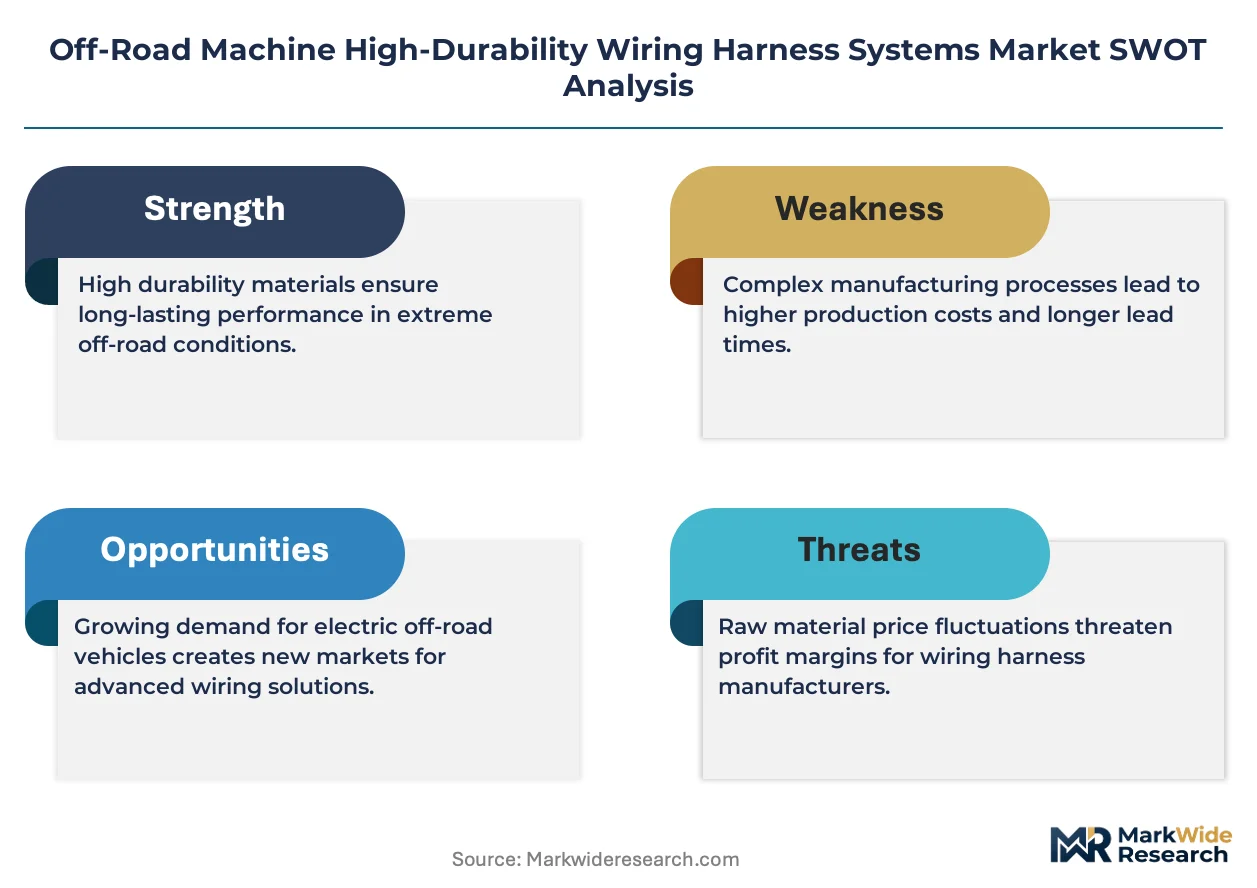
- Copper price volatility:Conductor materials constitute 35-45% of harness raw material costs, exposing margins to commodity swings.
- Certified testing infrastructure scarcity:ISO 6722 and SAE J1128 compliance requires capital-intensive validation labs concentrated in Germany, Japan, and the US.
- Thermoplastic substitution ceiling:Cross-linked polyethylene cannot match fluoropolymer temperature ratings above 125°C, limiting addressable applications in engine compartments.
Strategic Opportunities
- Modular field-replacement architectures:Plug-and-play segment designs reduce downtime for tier-1 component manufacturers operating remote sites.
- India's mining capacity expansion:The country's national mineral policy is accelerating open-cast project approvals, creating demand for construction-grade harness systems.
- Shielded harness penetration:Military and autonomous mining applications where electromagnetic compatibility failures carry catastrophic cost represent underserved premium segments.
Industry Challenges
- CAN bus integration complexity:Legacy analog sensor networks require complete harness redesigns to accommodate digital protocol migrations.
- Specialized termination technician shortages:Crimping and sealing operations for IP69K-rated connectors demand certified skill sets concentrated in mature manufacturing regions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Road Machine High-Durability Wiring Harness Systems Market Trends and Innovations
Harness engineering is pivoting from passive cable assemblies to active system components, with insulation chemistry and connector modularity becoming primary competitive differentiators rather than commodity specifications.
Fluorinated ethylene propylene insulation is migrating from niche aerospace applications to standard mining equipment specifications. Major iron ore operators in Western Australia now specify FEP-insulated harnesses for autonomous haul trucks operating 24/7 duty cycles. The technology is migrating from premium custom builds to catalog-standard product lines, compressing price premiums and forcing incumbent suppliers to absorb R&D amortization over shorter production runs.
EU Stage V emissions enforcement is mandating real-time particulate matter and selective catalytic reduction monitoring, embedding four to six additional sensors per engine harness. OEMs serving European construction equipment markets must redesign connector layouts to accommodate denser pin configurations without enlarging physical envelopes. The regulation is accelerating demand for miniaturized sealed connectors that maintain IP ratings under high-pressure washdown conditions.
Aftermarket procurement is fragmenting from bundled OEM service contracts toward independent component sourcing. Mining maintenance departments in Chile and South Africa are purchasing harness segments through specialized industrial distributors rather than captive OEM channels. This pattern is most visible in mature extraction regions where technical staff can specify replacement parts without platform engineering support.
Off-Road Machine High-Durability Wiring Harness Systems Market Segmentation
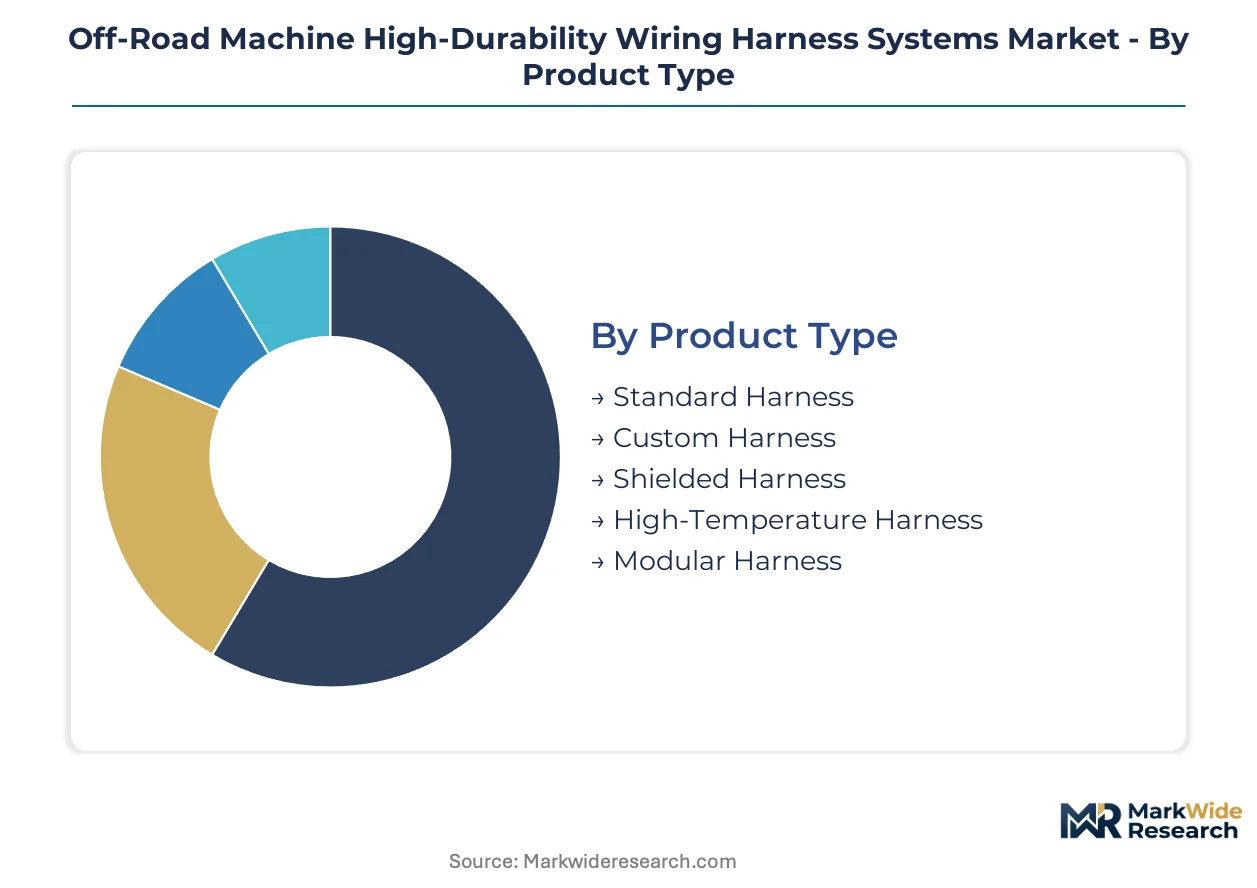
Off-road machine wiring harness systems fragment across insulation chemistry, thermal performance, and integration complexity. Each dimension carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
Cost tier differentiation separates commodity replacement parts from engineered systems commanding multi-year service contracts.
- Standard Harness:Catalog-specified assemblies with thermoplastic insulation dominate emerging market construction fleets. Brazil's iron ore belt operators specify these for non-critical auxiliary circuits where replacement frequency tolerates shorter service intervals.
- Custom Harness:Proprietary sensor-integrated architectures embed OEM-specific CAN bus configurations. Australia's Pilbara autonomous haulage operators mandate these for redundant fail-safe networks where electromagnetic compatibility failures carry catastrophic downtime costs.
- Shielded Harness:Braided copper shielding protects signal integrity in military and mining applications with dense electromagnetic noise environments.
- High-Temperature Harness:Cross-linked polyethylene or fluoropolymer insulation rated above 125°C serves engine compartment and exhaust aftertreatment zones.
- Modular Harness:Plug-and-play segment designs reduce field-replacement downtime for tier-1 component manufacturers operating remote extraction sites.
Standard Harness commands the established base. The steepest expansion runs through Custom Harness.
Technology:
Application temperature requirements and abrasive exposure levels dictate insulation material selection across mining, construction, and military end-uses.
- Thermoplastic Insulation:Volume leader for construction equipment in price-sensitive markets. India's accelerating open-cast mining approvals are driving procurement of these cost-positioned systems for new fleet builds.
- Cross-linked Polyethylene:Dominates mid-duty agricultural and forestry equipment where temperature ceilings remain below 125°C and chemical exposure is moderate.
- Fluoropolymer Coating:FEP-insulated systems are migrating from aerospace to standard mining specifications. Western Australia's 24/7 autonomous haul trucks now specify these for extended service life in abrasive dust environments.
- PVC Insulation:Restricted to low-temperature auxiliary applications where cost minimization outweighs durability requirements.
- Silicone Overmolding:Seals connector junctions against high-pressure washdown conditions required by EU Stage V emissions monitoring equipment.
Thermoplastic Insulation anchors current volume. Fluoropolymer Coating is climbing the fastest as mining electrification compresses replacement cycles.
Application:
End-use duty cycles and regulatory exposure create divergent harness specification requirements across equipment categories.
- Construction Equipment:Thermoplastic-insulated standard harnesses serve excavators and loaders in emerging markets. EPA Tier 4 Final mandates are expanding conductor counts for exhaust aftertreatment sensors.
- Mining Vehicles:Autonomous haul trucks in Australia's Pilbara and Brazil's Carajás require redundant harness loops with fluoropolymer insulation for 24/7 availability mandates.
- Agricultural Machinery:Harvesters and tractors deploy cross-linked polyethylene systems where seasonal operation patterns reduce thermal stress accumulation.
- Forestry Equipment:Mechanical damage resistance and moisture sealing priorities shape specification requirements for harvesters and forwarders.
- Military Vehicles:Shielded harness penetration is deepest here where electromagnetic compatibility failures carry mission-critical consequences.
Construction Equipment holds the broadest installed base. Mining Vehicles are gaining share fastest through fleet electrification and autonomous retrofit programs.
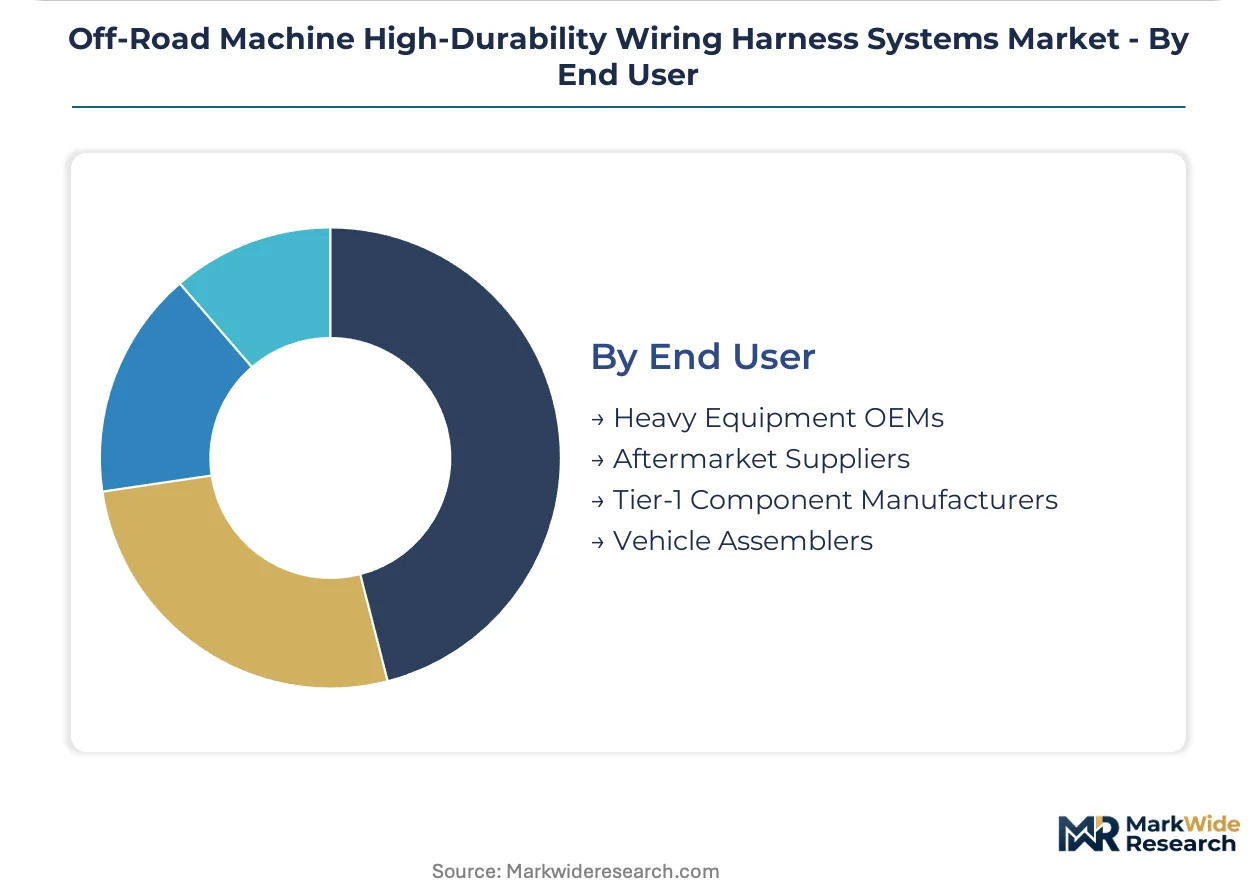
End User:
Procurement authority concentration varies from captive OEM channels to fragmented aftermarket sourcing patterns.
- Heavy Equipment OEMs:Integrated design authority over proprietary CAN bus architectures locks in multi-year supply agreements. These customers specify custom harness configurations with embedded sensor arrays.
- Aftermarket Suppliers:Chilean and South African mining maintenance departments are shifting procurement toward independent industrial distributors rather than captive OEM channels.
- Tier-1 Component Manufacturers:Modular harness architectures reduce their field-replacement downtime at remote extraction sites.
- Vehicle Assemblers:Final integration points for harness systems into complete machine platforms.
Heavy Equipment OEMs control the premium specification channel. Aftermarket Suppliers are expanding most quickly as technical capabilities mature in established mining regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final and EU Stage V emissions standards are reshaping procurement patterns across mining and construction corridors, with autonomous fleet retrofits concentrating demand in specific mineral belts and industrial zones.
United States
Surface mining operations in Wyoming's Powder River Basin and Arizona's copper districts are retrofitting haul fleets with sensor-dense harness architectures. EPA enforcement of Tier 4 Final standards for non-road diesel engines mandates additional aftertreatment monitoring circuits. Pittsburgh-area engineering clusters are supplying modular harness segments for autonomous conversion programs.
Australia
The Pilbara iron ore region commands premium fluoropolymer-insulated harness specifications for 24/7 autonomous haul truck operations. State workplace safety authorities in Western Australia impose equipment-availability mandates that compress replacement intervals. Perth-based maintenance contractors are sourcing shielded harness loops directly from industrial distributors rather than OEM channels.
Brazil
Carajás iron ore belt operators are specifying standard thermoplastic harnesses for auxiliary circuits while reserving custom architectures for critical control systems. The national mining regulator's availability requirements are shortening field-replacement cycles. São Paulo-state manufacturers are expanding connector assembly capacity to serve regional construction equipment demand.
Germany
EU Stage V emissions enforcement is mandating real-time particulate matter monitoring across construction and agricultural machinery fleets. Engineering consultancies in Baden-Württemberg are certifying harness architectures to ISO 6722 and SAE J1128 standards for export markets. Munich-area automotive suppliers are repurposing connector expertise for off-road electrification programs.
China
Open-cast coal operations in Inner Mongolia and Shanxi Province are importing fluoropolymer insulation technologies for high-availability mining fleets. GB standards for non-road mobile machinery emissions are aligning with EU Stage V equivalent requirements. Yangtze River Delta manufacturing clusters are scaling cross-linked polyethylene capacity for domestic construction equipment OEMs.
Off-Road Machine High-Durability Wiring Harness Systems Market Competitive Landscape
On the supply side, the industry is consolidating around suppliers with integrated manufacturing footprints and certified testing infrastructure. Tier-1 automotive harness specialists dominate premium mining and military segments, while regional fabricators compete on construction equipment replacement cycles. Two strategic archetypes prevail: integrated connector-to-harness manufacturers with backward control over insulation chemistry, and modular architecture specialists optimizing field-replacement logistics. Competitive moves center on fluoropolymer R&D partnerships and multi-year service contracts locking in autonomous fleet operators.
Within the integrated manufacturing tier, Yazaki Corporation and Sumitomo Electric Industries exemplify suppliers with captive connector production and materials science capabilities. Leoni occupies a position among modular architecture specialists, representing the segment-focused approach to reducing field-replacement downtime. These three companies anchor the competitive structure, with tier-2 regional fabricators competing on price-sensitive construction equipment procurement in emerging markets.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Aptiv |
| Leoni |
| Lear Corporation |
| Furukawa Electric |
| PKC Group |
| Dräxlmaier Group |
| Kostal Group |
| Others |
Pricing and Supply Chain Analysis
Copper price volatility acts as the dominant risk vector, compressing margins across all tiers while simultaneously forcing suppliers toward backward integration into conductor sourcing and long-term offtake contracts with Chilean and Peruvian mining operations.
Pricing Analysis
Certification level creates the primary spread between premium fluoropolymer-insulated systems and commodity thermoplastic alternatives. Pricing stratifies across ISO 6722-certified custom architectures, SAE J1128-compliant standard harnesses, and uncertified replacement segments for emerging market construction fleets. Cost compression in the standard tier is intensifying because India's open-cast mining expansion is pulling volume toward price-sensitive procurement. Aftermarket buyers in Chile and South Africa exhibit the highest price sensitivity, while Australia's Pilbara autonomous operators prioritize availability guarantees over unit cost.
Supply Chain Analysis
Export-control restrictions on fluoropolymer precursor chemicals limit insulation material flows from US and Japanese specialty chemical producers to Chinese harness fabricators. Manufacturing gravity centers on Germany, Japan, and the US for certified testing infrastructure, with Mexico and Thailand expanding connector assembly capacity for regional construction equipment demand. The supply chain draws from copper concentrate sourced through Chilean state mining operations, fluoropolymer resins from Daikin and Chemours production networks, and precision connectors from automotive-tier suppliers repurposing capacity. Single-source vulnerability concentrates in certified validation laboratories, where ISO 6722 compliance testing capacity remains restricted to three national clusters. Distribution runs through captive OEM channels for custom architectures and industrial distributors for aftermarket replacement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical upswing driven by mining fleet electrification retrofit programs, which compress replacement intervals and expand addressable spend per vehicle across the installed base.
For Market Incumbents: Harden certification infrastructure against emerging regional competitors by expanding ISO 6722 validation capacity in Brazil and Australia. Lock in multi-year service contracts with autonomous fleet operators before aftermarket technical capabilities mature in Chile and South Africa. Prioritize fluoropolymer insulation R&D partnerships to extend service life differentiation as FEP technology commoditizes.
For New Entrants and Emerging Players: Build out modular harness architecture capabilities targeting tier-1 component manufacturers operating remote extraction sites in India's accelerating open-cast mining corridor. The aftermarket channel in mature mining regions offers the most penetrable entry point, where technical staff can specify replacement segments without OEM engineering support. Lead with field-replacement downtime reduction as the primary go-to-market angle.
For Investors and Strategic Acquirers: Regional fabricators with certified testing partnerships and established relationships with Brazil's iron ore belt operators represent the most attractive acquisition targets. Long-term viability hinges on exposure to electrification-driven replacement cycle compression rather than new equipment production volumes. Watch for EPA Tier 4 Final enforcement acceleration as the signal for harness specification upgrade inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Insulation R&D Partnership | Extends harness life differentiation as FEP technology migrates to catalog-standard specifications. |
| Modular Field-Replacement Architecture Development | Reduces downtime for tier-1 component manufacturers operating Australia's Pilbara autonomous sites. |
| Certified Testing Infrastructure Expansion | Builds compliance barriers against uncertified competitors in Brazil's iron ore belt procurement. |
| Multi-Year Service Contract Lock-In | Captures autonomous fleet operator spend before aftermarket technical capabilities mature in Chile. |
| Backward Integration into Conductor Sourcing | Insulates margins from copper price volatility through long-term offtake with Chilean mining operations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with heavy equipment OEM procurement directors, mining fleet maintenance managers, tier-1 component manufacturer engineering leads, and aftermarket industrial distributor category buyers. Secondary validation drew from EPA enforcement documentation, EU Stage V regulatory filings, ISO certification registries, and customs trade data for copper conductor and fluoropolymer resin flows. Bottom-up segment sizing triangulated against top-down mining and construction equipment production forecasts.
Calibration against historical replacement cycle data and autonomous fleet deployment schedules anchored projections across the analysis window. Segmentation dimensions modeled include insulation chemistry tier, harness architecture type, end-use equipment category, and regional regulatory cluster. CAGRs were derived from installed base growth, electrification retrofit penetration curves, and specification upgrade elasticities tied to emissions enforcement timelines. Mining equipment availability mandates and autonomous haulage sensor density requirements served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese harness fabricators with GB standard certification would shift outcomes. Material shifts in copper price volatility regimes, EPA enforcement acceleration, or fluoropolymer export-control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.