
 Automotive Logging Device Market | 2026-2036
Automotive Logging Device Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Logging Device Market Intelligence
Modular hardware-software bundling is decoupling across the Automotive Logging Device landscape, giving fleet buyers granular control over feature tiers. Omnitracs, LLC leverages decades of route optimization heritage to anchor enterprise contracts with large carriers. Geotab Inc. differentiates through open-platform telematics that integrates third-party fleet applications. Samsara competes aggressively on cloud-native architecture, capturing mid-market fleets seeking rapid deployment without legacy infrastructure.
An automotive logging device captures, stores, and transmits vehicle operational data through embedded sensors and communication modules, typically processing engine diagnostics, GPS positioning, driver behavior metrics, and hours-of-service compliance at sampling rates between 1 Hz and 10 Hz depending on parameter criticality. Hardwired devices dominate installed base volumes due to tamper-resistant connections meeting FMCSA certification requirements, while wireless loggers represent the fastest-expanding configuration as retrofit demand surges among smaller operators avoiding professional installation downtime. CAN Bus technology leads integration depth for OEM-aligned systems, though cellular connectivity commands the highest margin pools through recurring data subscription structures.
The Federal Motor Carrier Safety Administration enforces ELD certification standards that dictate hardware encryption, data transfer protocols, and driver edit permissions, directly constraining which devices qualify for interstate commerce. State-level departments of transportation in California, Texas, and Florida layer additional weight-distance tax reporting requirements that expand logging functionality beyond federal baselines. Stakeholders must monitor emerging privacy litigation around driver biometric data collection, as courts weigh fourth-amendment protections against commercial fleet oversight imperatives.
Market Dynamics
The FMCSA's Electronic Logging Device mandate has triggered a wholesale replacement cycle across commercial trucking, decoupling hardware procurement from legacy fleet management contracts and forcing operators to requalify vendors against encrypted data-transfer standards.
Growth Catalysts
- Hours-of-service enforcement:Federal compliance deadlines in the United States continue to pull forward replacement demand among long-haul carriers operating across state lines.
- Cellular module cost compression:Falling LTE-M and NB-IoT component pricing is enabling subscription-based recurring revenue models that improve vendor lifetime value.
- Route optimization integration:Fleet operators now demand logging systems that feed real-time positioning data directly into dispatch algorithms, eliminating siloed data architectures.
Market Restraints
- Semiconductor allocation volatility:Persistent tightness in automotive-grade microcontroller supply from East Asian foundries is elongating hardware lead times.
- Installation labor scarcity:Certified technician availability constrains retrofit velocity for hardwired ELD configurations requiring FMCSA-compliant tamper-proof mounting.
- Driver privacy litigation:Fourth-amendment challenges to biometric data collection in Illinois and California are creating compliance friction for advanced driver monitoring features.
Strategic Opportunities
- Wireless retrofit penetration:Self-install OBD-II loggers offer a wedge into the long-tail of owner-operators and small fleets below fifty vehicles.
- State-level tax reporting expansion:California's weight-distance filing requirements and Texas fuel tax reconciliation rules create upsell paths beyond federal ELD baselines.
- Video telematics convergence:Integrating dashcam footage with logging data streams opens new insurance partnerships and risk-scoring revenue pools.
Industry Challenges
- FMCSA certification latency:Device approval timelines stretching twelve to eighteen months compress vendor product roadmaps and freeze feature iterations mid-cycle.
- Legacy TMS integration complexity:Fleet operators running on-premise transportation management systems face API mismatch friction when adopting cloud-native logging platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Logging Device Market |
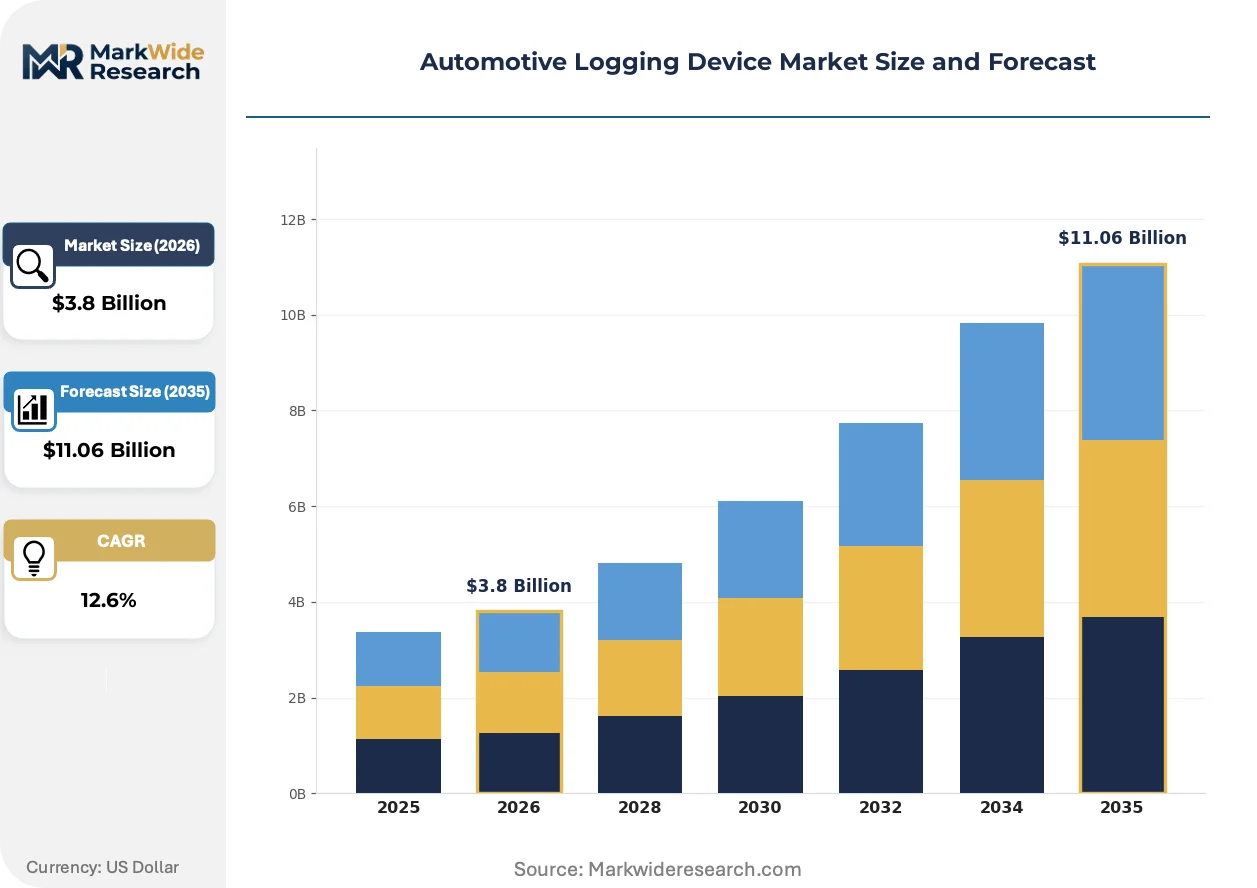
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwired Devices, Portable Loggers, Wireless Loggers, GPS Trackers Technology: Bluetooth, Wi-Fi, Cellular, CAN Bus End User: Fleet Operators, Individual Vehicle Owners, Insurance Companies, Logistics Installation: DIY Installation, Professional Installation, Integrated Solutions, Remote Installation |
| Companies Covered | Omnitracs, LLC, Geotab Inc., Teletrac Navman, Trimble Inc., Samsara, Motive, Robert Bosch GmbH, Continental AG, National Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Logging Device Market Strategic Shifts & Innovations
Automotive logging devices are shedding their standalone compliance-tool identity, becoming data hubs that feed adjacent fleet optimization systems. This functional expansion is reshaping vendor R&D priorities and buyer evaluation criteria.
Edge computing architectures are converging with logging hardware to enable real-time driver coaching without cloud round-trip latency. Mid-market fleets with thin IT infrastructure are adopting these systems fastest, compressing the historical gap between enterprise telematics capabilities and smaller operator budgets. The technology is converging with predictive maintenance algorithms that flag engine anomalies before diagnostic trouble codes trigger.
The FMCSA's pending updates to ELD technical specifications will mandate enhanced cybersecurity protocols for data transfer mechanisms. This regulatory tightening will disqualify older device generations from interstate commerce eligibility and accelerate replacement cycles among early mandate adopters. Long-haul carriers operating across multiple jurisdictions face the steepest requalification burden.
Subscription pricing for data connectivity is displacing perpetual hardware licensing as the dominant commercial model. Fleet procurement departments now evaluate total cost of ownership over five-year horizons rather than upfront capital expenditure, favoring vendors with transparent cellular data pooling structures. This shift is most visible among refrigerated transport operators in the Midwest and Southeast United States who prioritize uptime visibility over asset ownership.
Automotive Logging Device Market Segmentation
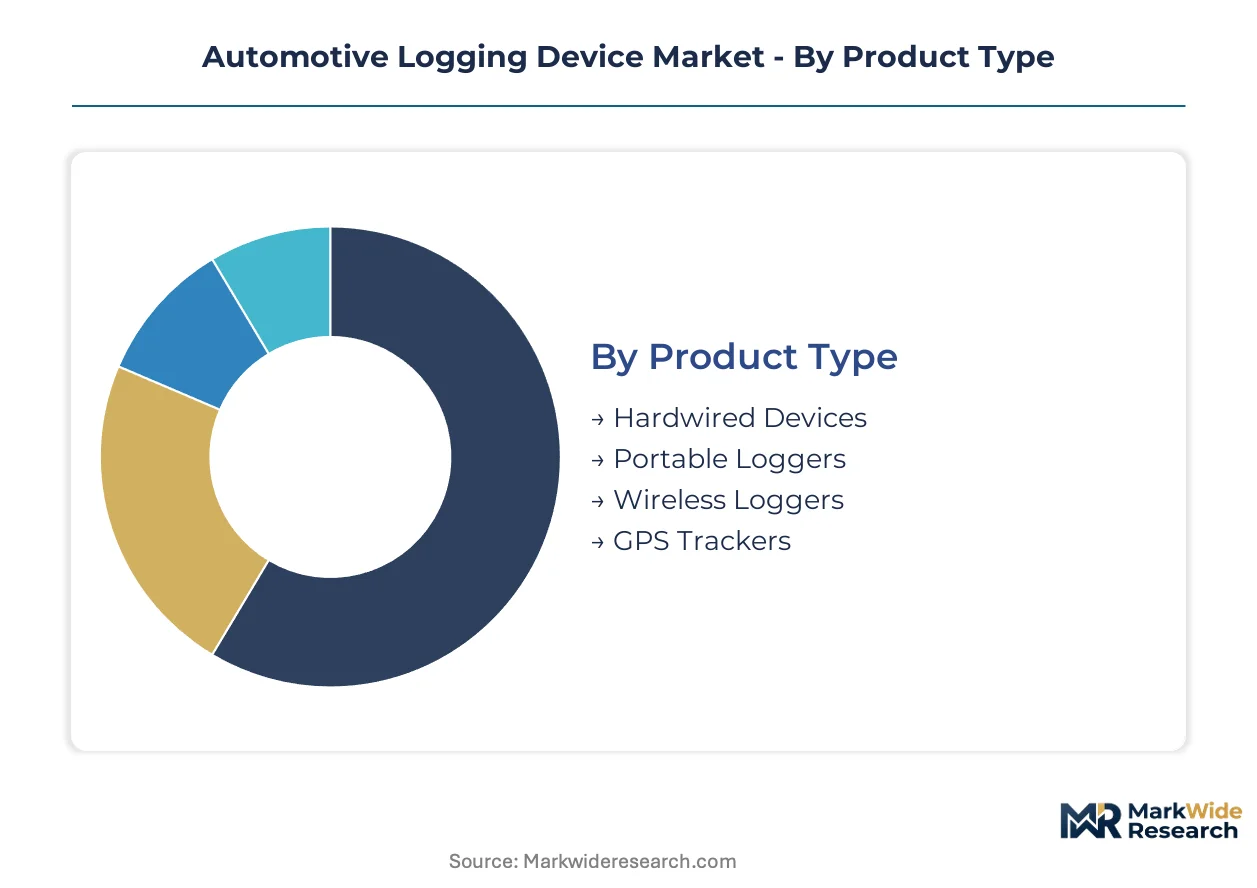
Fleet procurement decisions in the Automotive Logging Device Market hinge on how deeply logging hardware integrates with existing telematics stacks. Segmentation reveals where buyers prioritize standalone compliance versus embedded system architectures.
Product Type:
Integration depth separates permanently mounted systems from detachable alternatives, with hardwired configurations anchoring enterprise fleet contracts while portable formats serve intermittent monitoring needs.
- Hardwired Devices:These units feature tamper-resistant electrical connections and direct vehicle power integration, sampling engine and location data at 1-10 Hz frequencies. Long-haul carriers operating across multiple state jurisdictions favor these for FMCSA certification durability. Certified technician shortages constrain retrofit velocity in the United States.
- Wireless Loggers:Self-install OBD-II configurations eliminate professional mounting requirements through plug-and-play cellular or Bluetooth transmission. Owner-operators and fleets below fifty vehicles in Texas and Florida adopt these to avoid installation downtime. Falling LTE-M module costs compress hardware price points.
- Portable Loggers:Detachable units serve temporary compliance verification and rental fleet applications.
- GPS Trackers:Location-centric devices dominate asset recovery and basic fleet visibility use cases.
Volume placements concentrate in hardwired configurations; the faster expansion belongs to wireless loggers.
Technology:
Data transmission protocols determine subscription economics and real-time responsiveness, with cellular structures commanding recurring revenue premiums against short-range alternatives.
- Cellular:LTE-M and NB-IoT modules enable continuous cloud synchronization without driver intervention or proximity dependencies. Refrigerated transport operators in the Midwest prioritize these for temperature-alert continuity. Data pooling structures now dominate five-year total cost of ownership calculations.
- CAN Bus:Direct vehicle network integration delivers the deepest diagnostic access, capturing engine trouble codes and fuel consumption metrics at OEM-grade precision. Heavy-duty truck manufacturers embed these for factory-installed logging compliance. Semiconductor allocation volatility from East Asian foundries elongates lead times.
- Bluetooth:Short-range pairing suits driver smartphone tethering for last-mile delivery verification.
- Wi-Fi:Depot-synchronized logging fits return-to-base fleet models with scheduled data batch uploads.
Revenue margins peak with cellular subscriptions; CAN Bus systems claim the steepest technical barrier to competitive entry.
End User:
Procurement scale and compliance urgency diverge sharply between commercial fleet operators and individual asset protectors, reshaping vendor sales motion and pricing architecture.
- Fleet Operators:Enterprise buyers demand API-accessible logging data feeding dispatch optimization and hours-of-service dashboards. Large carriers anchor multi-year contracts with route heritage vendors. FMCSA certification latency compresses vendor product roadmaps.
- Insurance Companies:Underwriters deploy logging hardware for usage-based premium calculations and claims verification, particularly in commercial auto liability lines. Risk-scoring algorithms now ingest driver behavior telemetry alongside traditional actuarial data. Privacy litigation in Illinois and California creates compliance friction.
- Individual Vehicle Owners:Consumer-grade adoption centers on theft recovery and teen driver monitoring.
- Logistics:Third-party freight brokers utilize logging verification for carrier qualification and shipment tracking.
Contract value concentrates with fleet operators; insurance channel partnerships are climbing the fastest.
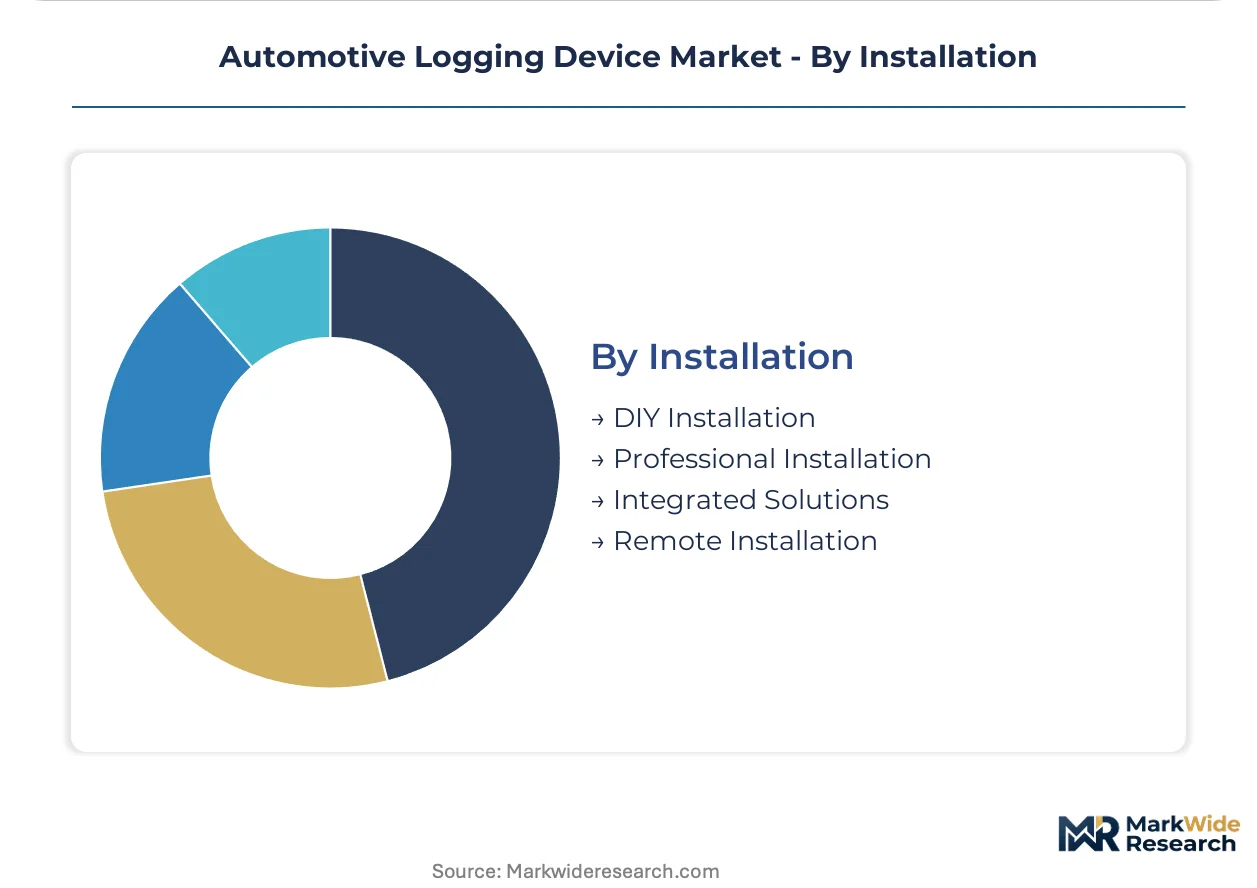
Installation:
Labor requirements and technical qualification standards create tiered market access, with self-service formats opening owner-operator segments previously sealed by technician scarcity.
- Professional Installation:FMCSA-mandated tamper-proof mounting for interstate commerce demands certified technician execution, particularly for hardwired ELD configurations. Installation labor scarcity in the United States constrains retrofit velocity for smaller fleets seeking compliance upgrades.
- DIY Installation:OBD-II port plug-in and magnetic-mount GPS units eliminate labor costs entirely, serving the long-tail of independent operators. Self-install wireless loggers from Geotab and Samsara capture mid-market fleets avoiding legacy infrastructure.
- Integrated Solutions:Factory-embedded logging at vehicle manufacture bypasses aftermarket installation entirely.
- Remote Installation:Over-the-air provisioning and guided self-setup reduce field technician deployment for software-centric configurations.
Deployment volume flows through professional channels; DIY formats are gaining share fastest among sub-fifty-vehicle operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in East Asian electronics corridors while consumption tilts heavily toward North American fleet operators governed by federal compliance mandates. The United States absorbs the dominant share of hardware shipments, though Germany and China anchor production of CAN Bus modules and cellular chipsets.
United States
FMCSA hours-of-service enforcement drives replacement cycles among interstate carriers operating across state lines. The federal agency's ELD certification standards constrain which devices qualify for commercial use. Dallas-Fort Worth and Atlanta logistics clusters deploy the highest density of hardwired logging systems for temperature-controlled freight monitoring.
Germany
Heavy-duty truck OEMs embed factory-installed logging hardware to meet EU tachograph regulations and factory calibration standards. KBA type-approval requirements layer additional technical barriers above baseline CE marking. Stuttgart and Munich automotive corridors supply CAN Bus integration modules to global Tier 1 suppliers.
China
Domestic fleet digitization and export manufacturing of LTE-M cellular modules propel dual demand streams. MIIT equipment certification governs radio transmission standards for devices entering commercial service. Shenzhen electronics clusters produce the majority of NB-IoT chipsets deployed in North American aftermarket configurations.
Japan
Precision manufacturing standards and METI industrial IoT promotion programs accelerate edge-computing logger adoption. JIS certification requirements ensure interoperability with domestic vehicle networks. Nagoya's automotive supplier corridor specializes in predictive maintenance algorithm integration for export markets.
Canada
Cross-border trucking harmonization with US FMCSA rules pulls Canadian carriers toward identical ELD hardware specifications. Transport Canada enforcement alignment with American federal standards eliminates product differentiation needs. Ontario's Windsor-Toronto freight corridor represents the densest provincial deployment of certified logging devices.
Automotive Logging Device Market Key Industry Players
The competitive structure tilts toward telematics heritage players with established fleet management relationships. Enterprise contract concentration favors vendors with route optimization software integration capabilities, while mid-market penetration rewards cloud-native architectures with rapid deployment timelines. Two strategic archetypes dominate: legacy fleet management platforms extending into compliance hardware, and pure-play logging specialists bundling cellular connectivity subscriptions. Competitive moves center on API ecosystem expansion and state-level tax reporting feature modularization.
Within the telematics-heritage tier, Omnitracs, LLC and Geotab Inc. occupy positions shaped by decades of fleet data platform development. Samsara represents the cloud-native archetype with architecture designed for mid-market operators seeking minimal infrastructure overhead. These three entities exemplify the market's bifurcation between enterprise-scale contract anchoring and agile deployment targeting sub-fifty-vehicle fleets.
| Leading Market Players |
|---|
| Omnitracs, LLC |
| Geotab Inc. |
| Teletrac Navman |
| Trimble Inc. |
| Samsara |
| Motive |
| Robert Bosch GmbH |
| Continental AG |
| National Instruments |
| Others |
Cost & Logistics Intelligence
Certified technician concentration in the Dallas-Fort Worth and Atlanta logistics corridors creates labor-cost differentials that widen pricing-tier spreads between professional-install hardwired systems and self-service wireless configurations. Fleet operators in Texas and Florida absorb premium installation charges for FMCSA-compliant tamper-proof mounting, while owner-operators in the Midwest and Southeast bypass labor entirely through OBD-II plug-in alternatives.
Pricing Analysis
Margin tightening in hardwired ELD tiers reflects certified installation labor scarcity and semiconductor allocation volatility from East Asian foundries. Three-tier pricing structure across enterprise, mid-market, and owner-operator levels separates multi-year contract bundles from month-to-month cellular subscriptions. Cost-down pressure on wireless logger hardware accelerates because falling LTE-M module pricing compresses bill-of-materials. Owner-operators exhibit highest price sensitivity; refrigerated transport fleets prioritize uptime visibility over upfront capital.
Supply Chain Analysis
Freight costs from Shenzhen electronics clusters to North American distribution hubs fluctuate with transpacific container rates, amplifying landed cost variability for NB-IoT chipset suppliers. Manufacturing concentrates in China, Taiwan, and South Korea for cellular modules and automotive-grade microcontrollers. Raw material dependencies span silicon wafers, rare earth elements for magnetics, and copper for vehicle harness integration. Single-source vulnerability in automotive-grade microcontroller supply from East Asian foundries threatens hardware lead times. Distribution runs through Tier 1 telematics vendors, OEM embedded programs, and aftermarket direct-to-fleet channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
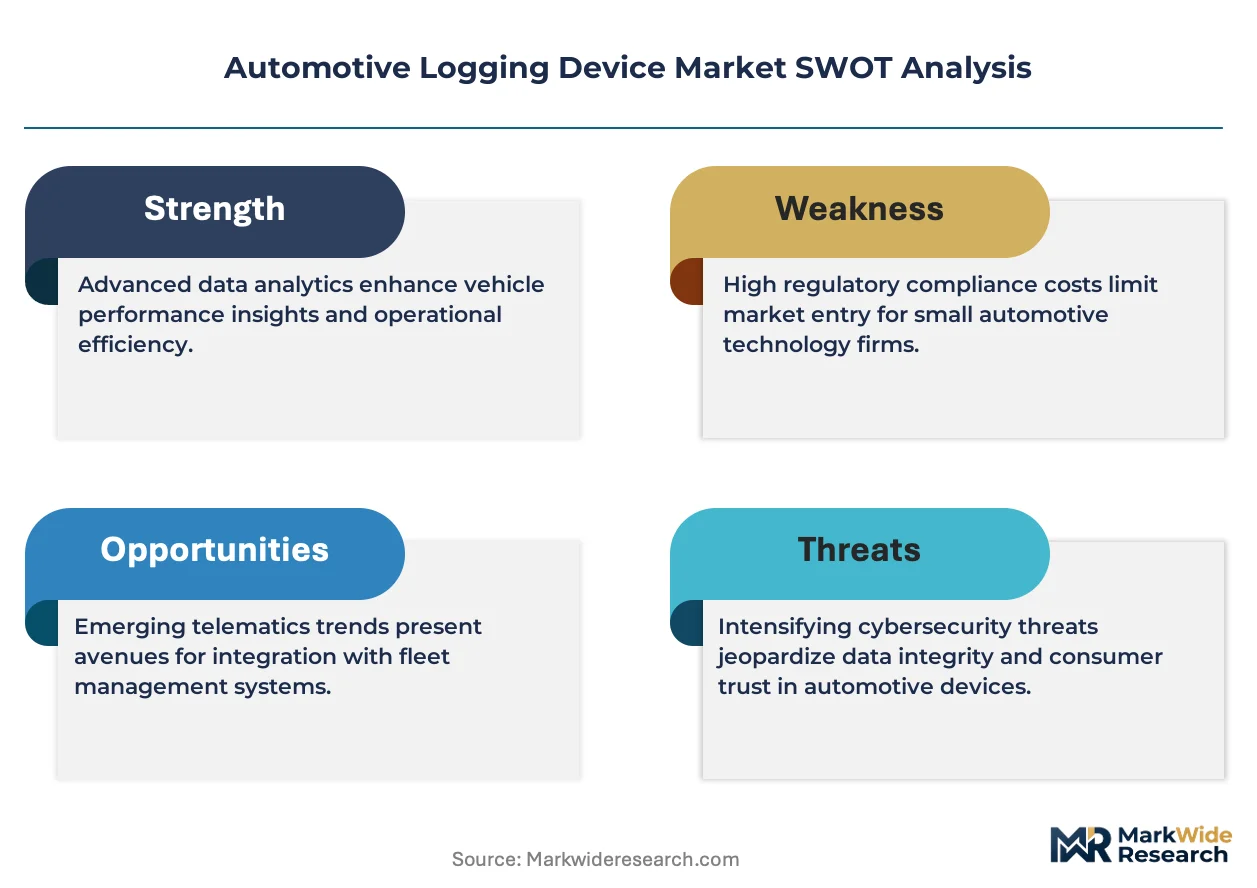
Consolidation pressure intensifies as FMCSA certification latency stretching twelve to eighteen months freezes product roadmaps and strands subscale vendors without capital reserves to navigate requalification cycles.
For Market Incumbents: To counter cloud-native entrants capturing mid-market fleets with rapid deployment, anchor enterprise contracts through API ecosystem expansion feeding dispatch optimization platforms. Deepen backward integration into cellular data pooling structures to capture recurring revenue premiums. Invest in state-level tax reporting modularization for California weight-distance and Texas fuel tax reconciliation upsells. For New Entrants and Emerging Players: Owner-operators and sub-fifty-vehicle fleets in the Midwest and Southeast represent the most penetrable buyer archetype, underserved by legacy fleet management platforms with heavy infrastructure requirements. Self-install wireless loggers with transparent subscription pricing bypass certified technician scarcity constraining retrofit velocity. Partner with insurance underwriters for usage-based premium verification to open risk-scoring revenue pools. For Investors and Strategic Acquirers: Re-rating potential sits with telematics-heritage vendors possessing established route optimization software and FMCSA certification durability, given pending cybersecurity protocol updates that will disqualify older device generations. Long-term viability hinges on cloud-native architecture and cellular subscription economics over hardware transactional models. Watch FMCSA technical specification update timing as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-accessible logging data feeding dispatch algorithms eliminates siloed fleet management architectures. |
| Geographic Expansion | State-level tax reporting modules for California and Texas create upsell paths beyond federal ELD baselines. |
| Acquisition of Specialist Firm | Video telematics specialists enable dashcam-logging convergence for insurance partnership revenue. |
| Product Launch | Edge-computing loggers with real-time driver coaching compress capability gaps for thin-IT mid-market fleets. |
| Strategic Partnership | Cellular carrier data pooling agreements improve five-year total cost of ownership transparency for procurement departments. |
Research Approach
Independent corroboration across fleet operations executives, ELD procurement officers, and certified installation technicians underwrites the qualitative findings in this study. Primary interviews with OEM platform engineers, aftermarket distributor principals, and insurance underwriting specialists combined with secondary validation from FMCSA certification databases, vehicle production registries, and cellular module trade data. Bottom-up shipment modeling and top-down fleet penetration analysis triangulate market sizing across hardware configurations and connectivity technologies.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include device integration depth, transmission protocol, fleet scale tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, cellular subscription attach rates, and state-level compliance expansion. Forecast inputs incorporate semiconductor lead time indices and certified technician labor availability by logistics corridor.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FMCSA specification update timing, driver privacy litigation resolutions in Illinois and California, and East Asian foundry allocation volatility. Forecasts reflect documented assumptions about mandate enforcement continuity and cellular cost compression trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
UK Automotive Camera Market