
 Automotive Monitor Touch Market | 2026-2036
Automotive Monitor Touch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Monitor Touch Market Analytics
EU Green Deal emissions benchmarks is broadening the cost-of-entry calculus for cockpit electronics suppliers. Continental AG leverages captive display manufacturing to anchor its position in integrated dashboard modules. Robert Bosch GmbH sustains R&D intensity across capacitive sensing architectures for premium vehicle lines. Synaptics Incorporated specializes in touch controller ICs that compete on response latency and electromagnetic interference tolerance.
Automotive monitor touch systems combine projected capacitive or resistive sensing layers with bonded cover glass and LCD or OLED display panels to enable driver and passenger interaction with navigation, climate, and media functions. Manufacturing employs photolithographic patterning of indium tin oxide or metal mesh electrodes on soda-lime or chemically strengthened glass substrates, followed by optical bonding to eliminate parallax and improve outdoor readability. Capacitive technology dominates volume shipments due to multi-touch capability and durability advantages over resistive alternatives. Multi-touch display configurations command premium positioning in luxury and electric vehicle segments where gesture control and haptic feedback integration justify higher unit economics. OEM channel supply captures the largest margin pool as vehicle assemblers specify proprietary interface designs and lock in multi-year platform contracts.
NHTSA guidelines on driver distraction limit touchscreen complexity during vehicle motion, while ECE R79 mandates specific steering control layouts that constrain display placement in European-type approved vehicles. REACH substance restrictions on hazardous materials in electronics affect electrode material selection and glass treatment chemistries across EU-bound production. Stakeholders must monitor evolving UN ECE regulations on automated driving system interfaces and cybersecurity certification requirements that will reshape hardware-software integration obligations.
Market Dynamics
Passenger EV platforms are compressing development cycles for cockpit electronics, forcing suppliers to synchronize touch controller releases with 18-month vehicle redesign schedules rather than traditional 5-year platform lifecycles.
Growth Catalysts
- EU Green Deal emissions benchmarks:These benchmarks mandate interior material sustainability credentials that favor capacitive touch systems with recyclable glass substrates over mechanical switch alternatives in EU-type approved vehicles.
- Multi-touch gesture libraries:Standardized pinch-to-zoom and swipe protocols developed for consumer electronics are migrating into automotive-grade controllers, reducing driver training friction and accelerating interface acceptance.
- China's NEV penetration:Domestic electric vehicle assemblers specify 15-inch-plus center stack displays as standard equipment, creating concentrated demand pull for bonded touch modules in Shanghai and Shenzhen manufacturing corridors.
Market Restraints
- Indium supply concentration:Over 80% of indium tin oxide sputtering targets originate from Chinese refiners, exposing electrode production to export licensing volatility and geopolitical friction.
- Optical bonding yield losses:Vacuum lamination of cover glass to display panels generates 8-12% scrap rates in high-humidity manufacturing environments, compressing gross margins for tier-two module integrators.
- NHTSA distraction guidelines:These guidelines impose task-completion time limits that constrain feature complexity, preventing premium-tier interface differentiation on US-bound vehicles.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive electronics attract touch controller assembly to Tamil Nadu and Gujarat, creating captive supply for domestic OEMs and export markets.
- Haptic feedback convergence:Integration of piezoelectric actuators with capacitive sensing layers enables eyes-off confirmation for climate and media controls, opening premium positioning in luxury EV segments.
- UN ECE cybersecurity certification:Pending mandatory hardware security module requirements for connected vehicle interfaces will favor suppliers with pre-integrated cryptographic touch controllers, consolidating vendor selection criteria.
Industry Challenges
- Automotive-grade firmware validation:ISO 26262 functional safety certification for touch controller software demands 24-36 month validation cycles, misaligning with consumer electronics talent accustomed to agile release schedules.
- Legacy 12V electrical architecture integration:Electrified vehicles with 48V or 800V systems require voltage level translation and isolation redesigns for touch controllers originally architected for conventional power networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Monitor Touch Market |
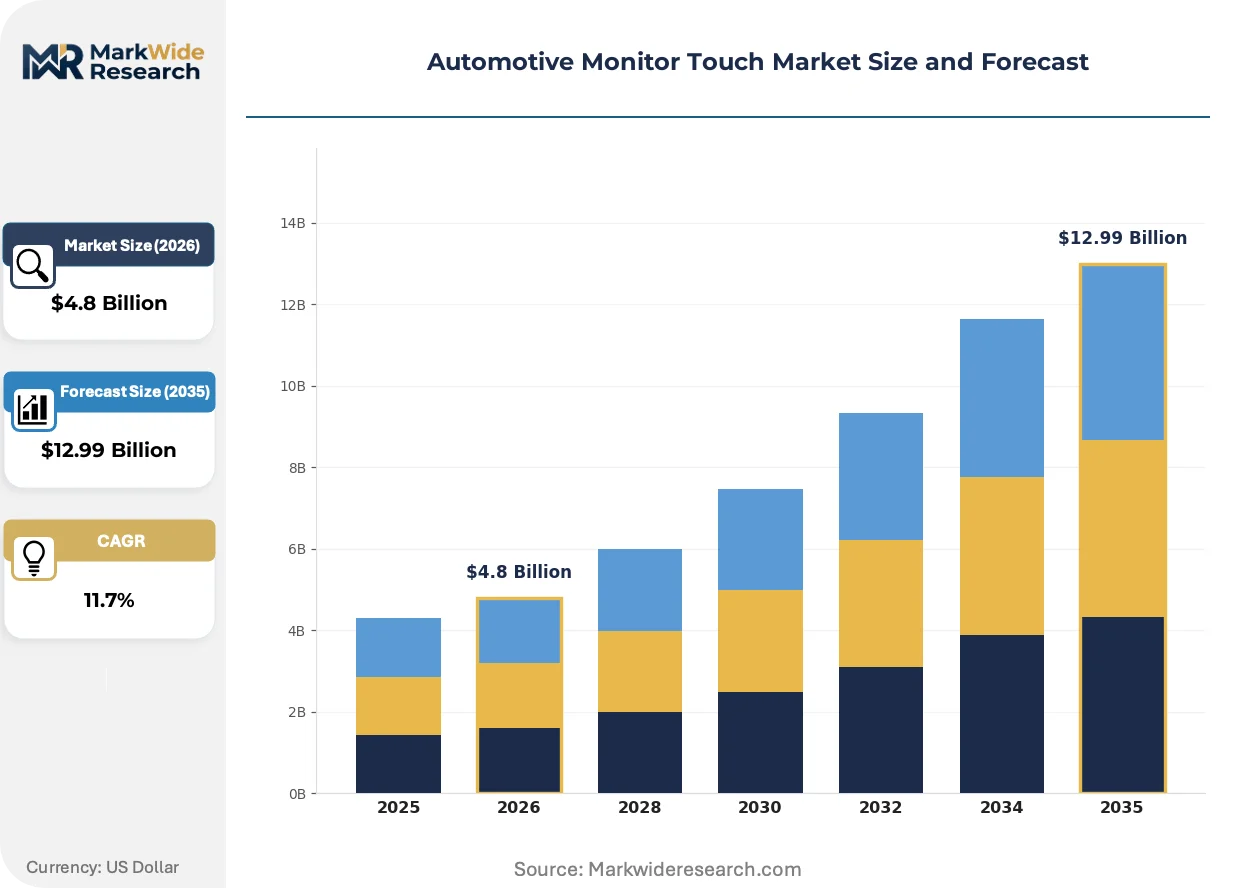
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touch Screen, LCD Monitor, OLED Panel, Multi-Touch Display Technology: Capacitive, Resistive, Infrared, Optical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation: Dashboard, Infotainment System, Rear-View Mirror, Center Console |
| Companies Covered | Continental AG, Synaptics Incorporated, Infineon Technologies AG, KYOCERA Corp., Robert Bosch GmbH, Texas Instruments Inc., STMicroelectronics NV, Aptiv, Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Monitor Touch Market Evolving Landscape
Metal mesh electrode patterning is displacing indium tin oxide in large-format automotive displays, driven by conductivity requirements for 15-inch-plus diagonal dimensions and supply security concerns.
Projected capacitive sensing with silver nanowire traces is absorbing the performance demands of curved and free-form dashboard surfaces that conventional ITO cannot accommodate. Tier-one suppliers in Germany and Japan are qualifying these films for 2026 platform launches. The technology is absorbing design freedom previously constrained by planar glass limitations, enabling wraparound center console configurations.
REACH substance restrictions on hazardous materials are tightening electrode etching chemistries and glass treatment processes for EU-bound production. ECHA enforcement is driving substitution of hydrofluoric acid-based strengthening protocols toward alternative ion-exchange methods. Module suppliers serving Stuttgart and Munich clusters are requalifying supply chains to maintain CE marking compliance.
Fleet procurement of standardized touch interface specifications is compressing SKU diversity for rental and commercial vehicle channels. Corporate buyers now mandate 7-year component availability guarantees, displacing the annual refresh cycles common in retail passenger vehicles. This pattern concentrates most visibly in US commercial fleet operators specifying uniform cockpit electronics across multi-thousand vehicle orders.
Automotive Monitor Touch Market Segmentation
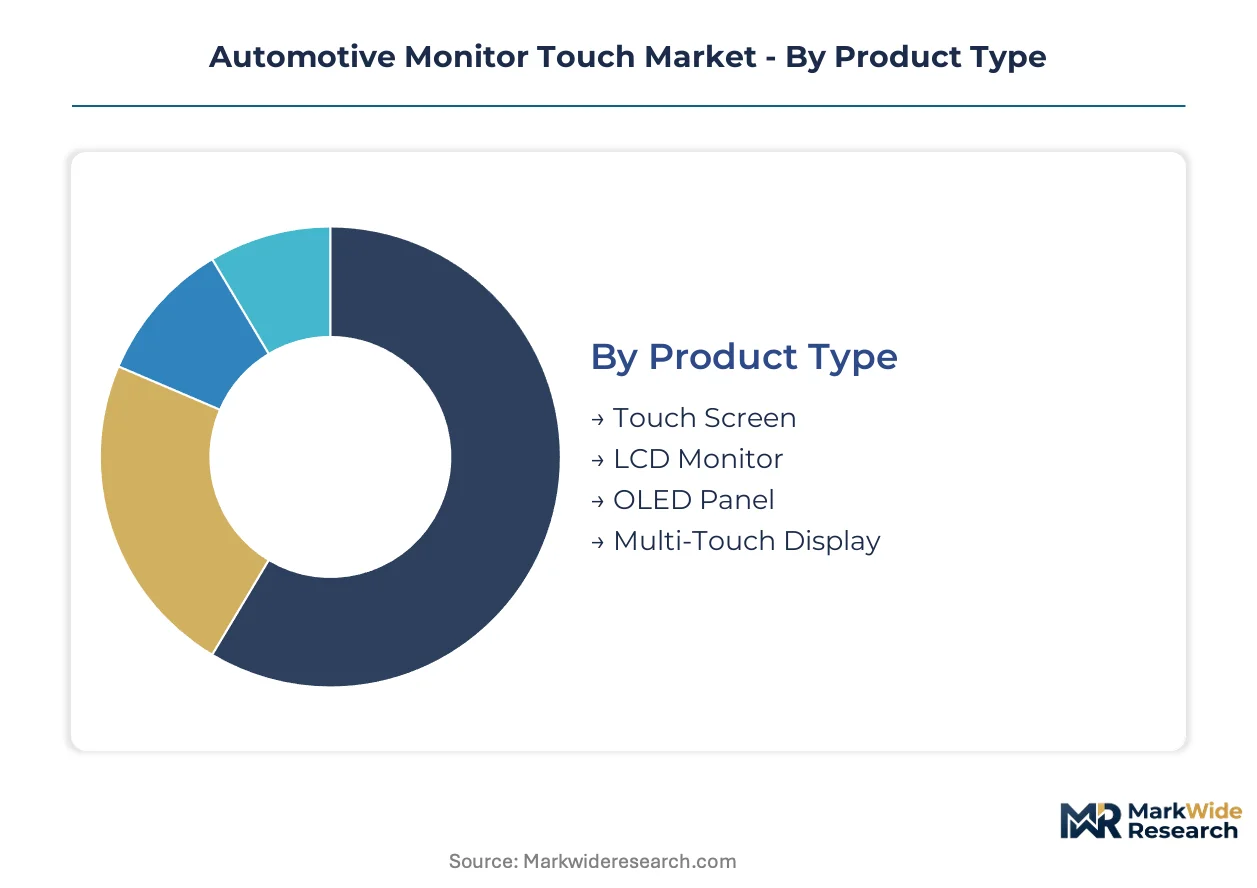
Automotive monitor touch systems fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and certification requirements. Understanding these divides reveals where upgrade cycles compress development timelines and where replacement demand stabilizes revenue streams.
Product Type:
Replacement cycles for cockpit displays are shortening as EV platforms accelerate refresh schedules, compressing supplier validation windows.
- Touch Screen:Bonded cover glass with projected capacitive sensing layers enables multi-touch gesture recognition. Passenger EV platforms in China specify 15-inch-plus configurations as standard equipment, pulling bonded module demand toward Shenzhen manufacturing corridors.
- LCD Monitor:Backlit liquid crystal panels with indium tin oxide electrode patterning dominate current volume shipments due to cost optimization and supply chain maturity. Tier-one suppliers in Germany leverage captive glass manufacturing to secure margin positions in integrated dashboard modules.
- OLED Panel:Self-emitting organic diode arrays deliver contrast ratios exceeding conventional backlit alternatives.
- Multi-Touch Display:Gesture-capable interfaces with haptic feedback integration command premium positioning in luxury vehicle segments.
Volume placements concentrate in LCD Monitor configurations; the faster expansion belongs to Multi-Touch Display systems.
Technology:
Cost tier differentiation separates high-volume commodity sensing from precision architectures serving premium positioning.
- Capacitive:Projected electric field sensing enables multi-touch recognition and durability advantages over mechanical alternatives. ECE R79 steering control standards in Europe constrain display placement, favoring capacitive architectures that tolerate constrained form factors.
- Resistive:Pressure-activated membrane stacks persist in commercial fleet applications where glove compatibility and environmental sealing outweigh gesture sophistication. NHTSA distraction guidelines in the United States limit task-completion complexity, preserving resistive viability in cost-sensitive vehicle lines.
- Infrared:Optical beam interruption sensing accommodates very large format displays without conductivity limitations.
- Optical:Camera-based touch detection enables flexible surface geometries beyond planar glass constraints.
Capacitive architectures capture the dominant share of new platform specifications; Infrared sensing is climbing the fastest among emerging alternatives.
End User:
Customer type determines contract structure, with long-term platform agreements contrasting against spot aftermarket procurement.
- OEMs:Vehicle brand owners specify proprietary interface designs and lock in multi-year platform contracts with exclusive supplier arrangements. Germany's automotive electronics clusters around Stuttgart and Munich concentrate OEM engineering resources and qualification facilities.
- Tier-1 Suppliers:Module integrators combine display panels, touch controllers, and bonding processes for direct OEM delivery. China's NEV assemblers compress development cycles to 18-month redesign schedules, forcing Tier-1 synchronization with accelerated release timelines.
- Aftermarket Providers:Independent distributors serve vehicle retrofit and repair channels with standardized specifications.
- Vehicle Assemblers:Contract manufacturers rely on specified component sourcing with limited design authority.
Procurement volume pools with OEMs; Tier-1 Suppliers are gaining share fastest through vertical integration into controller IC design.
Installation:
Application placement dictates optical bonding requirements and regulatory exposure across different vehicle interior zones.
- Dashboard:Integrated instrument cluster displays combine speedometer, navigation, and vehicle status readouts behind single bonded glass surfaces. REACH substance restrictions in the European Union drive substitution of hydrofluoric acid strengthening protocols toward ion-exchange alternatives for EU-bound production.
- Center Console:Primary human-machine interface for climate, media, and navigation functions commands the largest display real estate. United States commercial fleet operators mandate 7-year component availability guarantees, standardizing console specifications across multi-thousand vehicle orders.
- Infotainment System:Passenger-facing entertainment screens require distinct optical bonding for wide-angle viewing.
- Rear-View Mirror:Compact touch overlays enable camera feed switching and brightness control in limited surface area.
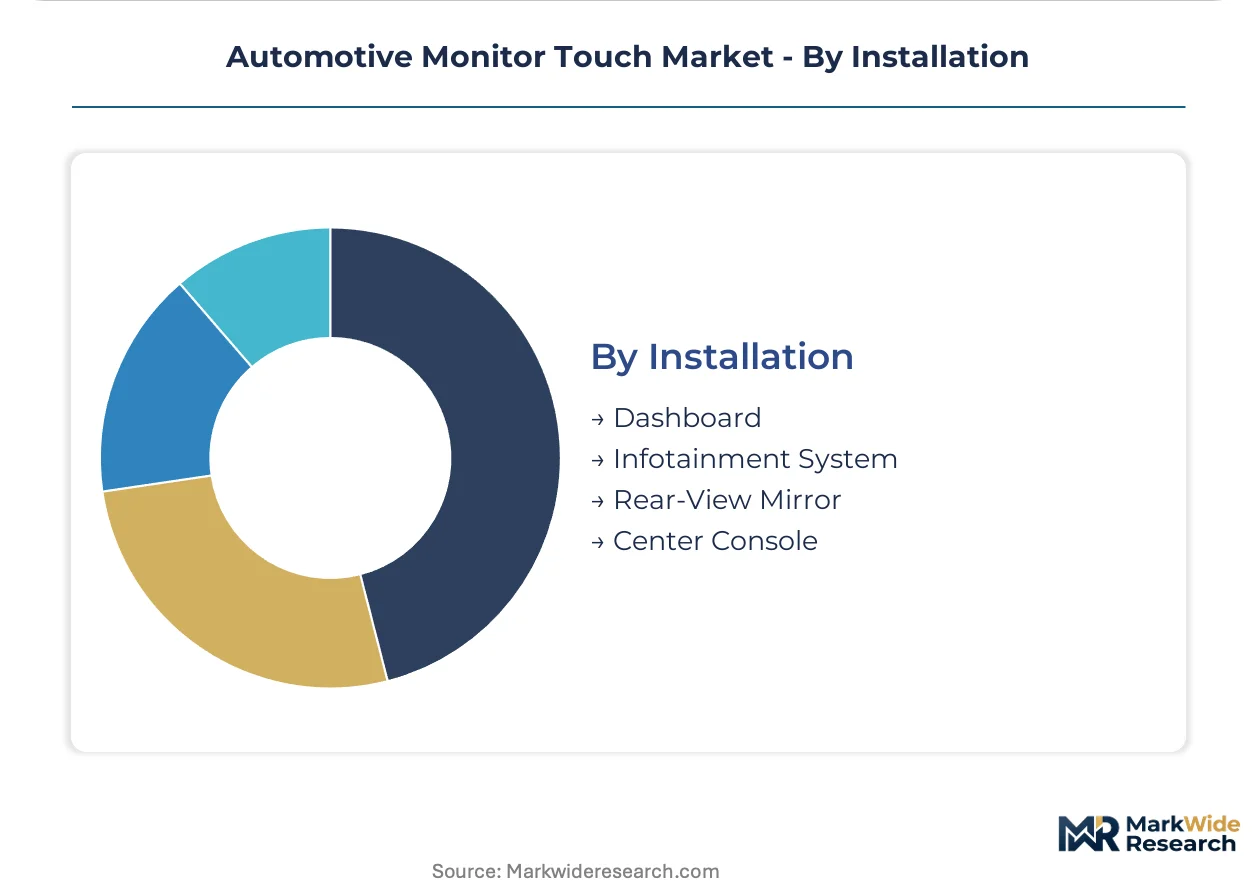
Dashboard integration carries the heaviest certification burden; Center Console applications are expanding most quickly as display diagonal requirements grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive monitor touch systems concentrates in Germany, China, and the United States, where automotive electronics clusters and regulatory stringency converge to shape procurement patterns and technology roadmaps.
United States
NHTSA distracted-driving guidelines limit touchscreen complexity during vehicle motion, constraining feature differentiation for US-bound vehicles. Commercial fleet operators mandate 7-year component availability guarantees, standardizing cockpit electronics specifications across multi-thousand vehicle orders. Engineering resources concentrate in Michigan and California, where OEM qualification facilities anchor North American platform development.
Germany
ECE R79 steering control standards constrain display placement in European-type approved vehicles, favoring capacitive architectures that tolerate constrained form factors. REACH substance restrictions drive substitution of hydrofluoric acid strengthening protocols toward ion-exchange alternatives for EU-bound production. Stuttgart and Munich clusters host captive display manufacturing and integrated dashboard module assembly operations.
China
Domestic electric vehicle assemblers specify 15-inch-plus center stack displays as standard equipment, creating concentrated demand pull for bonded touch modules. MIIT dual carbon goals accelerate interior material sustainability credentials in NEV platforms. Shenzhen and Shanghai manufacturing corridors synchronize touch controller releases with compressed 18-month vehicle redesign schedules.
Japan
METI industrial policy supports advanced automotive electronics R&D, particularly for curved and free-form dashboard surface applications. JIS standards govern electromagnetic compatibility testing for touch controller ICs deployed in premium vehicle lines. Nagoya and Tokyo metropolitan areas concentrate Tier-1 supplier engineering resources and optical bonding qualification facilities.
South Korea
Domestic OEMs integrate haptic feedback convergence into luxury EV segments, opening premium positioning for piezoelectric actuator suppliers. MFDS cybersecurity frameworks anticipate UN ECE hardware security module requirements for connected vehicle interfaces. Seoul Capital Area hosts display panel manufacturing and touch controller semiconductor fabrication operations.
Automotive Monitor Touch Market Competitive Landscape
German producers anchor one tier in integrated dashboard modules; Japanese and South Korean specialists hold advanced sensing and display panel positions. The vendor base organizes around three strategic archetypes: diversified automotive electronics conglomerates with captive glass manufacturing, semiconductor specialists competing on controller IC response latency, and Tier-1 module integrators managing optical bonding and supply chain synchronization. Competitive moves concentrate on backward integration into controller IC design and strategic partnerships to secure indium tin oxide alternative materials.
Among Germany-based diversified suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated module archetype with in-house production capabilities spanning sensing layers through final assembly. Synaptics Incorporated represents the controller IC specialist tier, competing on electromagnetic interference tolerance and haptic integration. These three anchors illustrate how geographic concentration in Stuttgart, Munich, and San Jose shapes competitive positioning across the value chain.
| Leading Market Players |
|---|
| Continental AG |
| Synaptics Incorporated |
| Infineon Technologies AG |
| KYOCERA Corp. |
| Robert Bosch GmbH |
| Texas Instruments Inc. |
| STMicroelectronics NV |
| Aptiv |
| Visteon Corporation |
| Others |
Value Network & Pricing Analysis
OEM platform engineering teams concentrate procurement authority in multi-year vehicle contracts, anchoring pricing around long-term offtake agreements with volume-tiered discounts rather than spot-market transactions. This buyer concentration shifts pricing power toward vehicle assemblers capable of locking in 18-month redesign schedules, while tier-two module integrators absorb margin compression from optical bonding yield losses.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery windows as China's NEV assemblers compress development cycles. Three-tier pricing structure across premium, standard, and economy levels separates multi-touch gesture systems with haptic integration from basic capacitive alternatives. Pricing pressure stems from indium supply concentration and vacuum lamination scrap rates eroding tier-two margins. Fleet procurement channels exhibit highest price sensitivity due to standardized 7-year availability mandates, while luxury EV lines tolerate premium positioning for curved display configurations.
Supply Chain Analysis
Dual-sourcing requirements from Stuttgart and Munich OEM clusters mandate qualified secondary suppliers for indium tin oxide alternatives and silver nanowire electrode films. Manufacturing gravity centers on Germany, China, and Japan, with module assembly drawing from soda-lime glass substrates, photolithographic patterning equipment, and touch controller ICs. Single-source vulnerability concentrates in Chinese indium refining and optical bonding adhesive chemistries. Distribution runs through captive OEM channels with multi-year platform lock-ins dominating over spot aftermarket procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
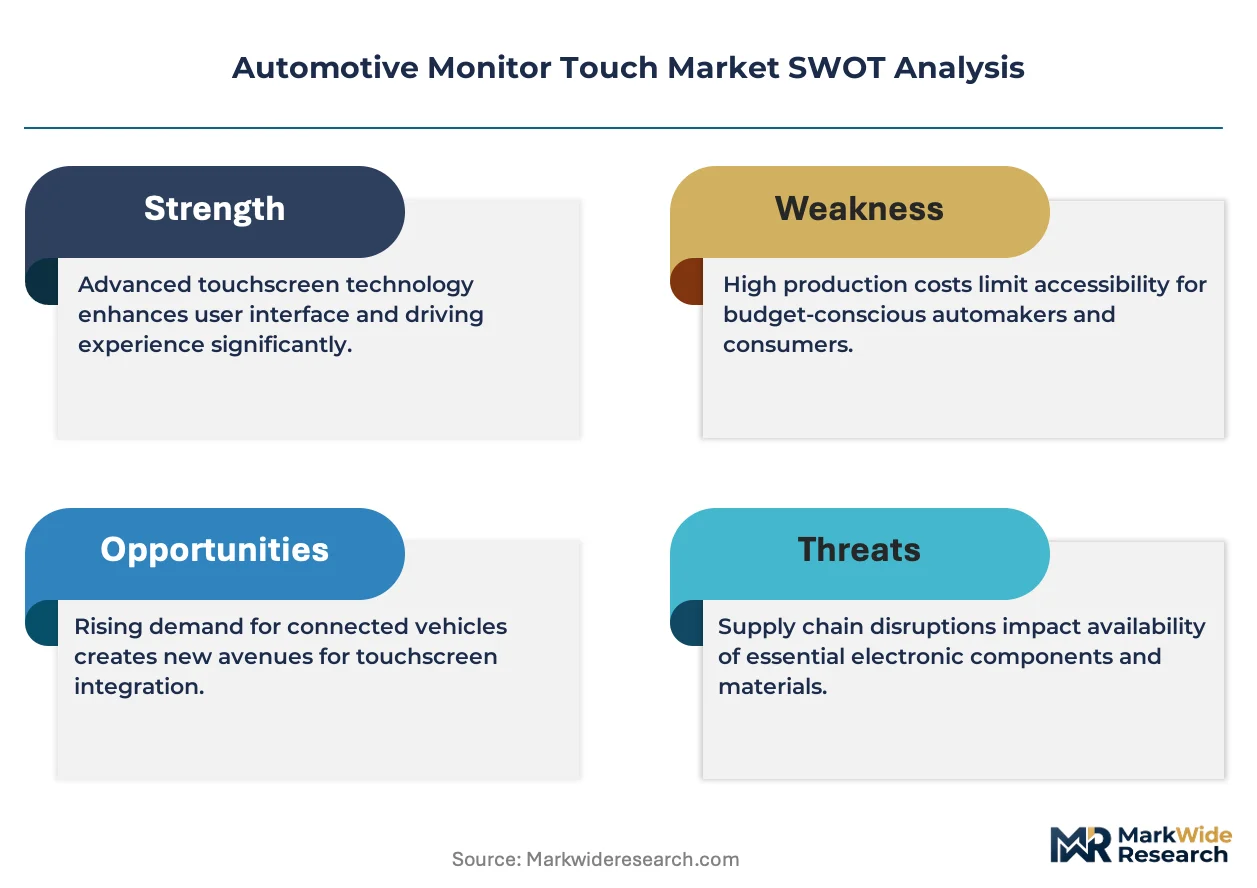
Automotive monitor touch systems function as a cost-of-compliance market where REACH substance restrictions and UN ECE cybersecurity certification erect barrier-to-entry moats favoring incumbents with pre-validated supply chains and ISO 26262 functional safety credentials.
For Market Incumbents: Lock in captive controller IC design capabilities and ion-exchange glass strengthening protocols before ECHA enforcement tightens further. Consolidate position through backward integration into silver nanowire electrode patterning to offset indium supply volatility. Threat substitution from metal mesh alternatives demands R&D synchronization with 2026 platform launches in Germany and Japan. For New Entrants and Emerging Players: Aftermarket retrofit channels for commercial fleet operators represent the most penetrable white-space target, given standardized 7-year availability requirements and limited incumbent focus. India's PLI scheme for auto components offers geographic entry with production-linked incentives backing Tamil Nadu assembly operations. Go-to-market positioning should emphasize REACH-compliant material substitution as a compliance-first value proposition. For Investors and Strategic Acquirers: The window for entry favors controller IC specialists with pre-integrated cryptographic touch controllers ahead of mandatory UN ECE hardware security module requirements. Long-term viability hinges on automotive-grade firmware validation capabilities and OEM platform engineering relationships. Watch for MIIT dual carbon goal acceleration in China as the inflection signal for interior material sustainability credential demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Materials | Silver nanowire and metal mesh sourcing reduces indium concentration risk from Chinese refiners. |
| ISO 26262 Functional Safety Certification | Automotive-grade firmware validation creates 24-36 month moats against consumer electronics talent pools. |
| Curved Display Surface Qualification | Projected capacitive sensing on free-form dashboards enables wraparound center console configurations for 2026 platforms. |
| Haptic Feedback Convergence | Piezoelectric actuator integration with capacitive layers opens premium positioning in luxury EV segments. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat assembly creates captive supply for domestic OEMs and export corridor access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive electronics analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and touch controller IC design leads combined with vehicle production databases, IHS Markit registration data, SEC 10-K electronics disclosures, and ECHA substance restriction updates. Bottom-up module shipment tallies triangulated against top-down vehicle production forecasts across passenger EV and internal combustion platform splits.
Data-stream reconciliation merged capacitive sensing layer shipments, display panel procurement records, and optical bonding capacity utilization into segmented projections. Vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions structured the analytical framework. CAGRs derived from fitted growth curves applied to validated base-year estimates, with NEV penetration rates and regulatory compliance timelines as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when indium export licensing volatility, ECHA enforcement acceleration, or NHTSA distraction guideline tightening materialize beyond modeled assumptions. Deviation in UN ECE cybersecurity certification timelines or MIIT dual carbon goal implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market