
 Rear-Seat Entertainment Display Platforms for SUVs Market | 2026-2036
Rear-Seat Entertainment Display Platforms for SUVs Market Size, Share, and Industry Trends Forecast 2026-2036
Rear-Seat Entertainment Display Platforms for SUVs Market Insights
Buyer concentration among OEM manufacturers is expanding as premium SUV brands consolidate rear-cabin digital sourcing around fewer Tier-1 partners. Panasonic Automotive Systems leverages vertical integration into display module production to secure long-term OEM contracts. HARMAN sustains technology leadership in audio-visual integration, while LG Display anchors supply security through captive OLED panel capacity.
Rear-seat entertainment display platforms for SUVs comprise fixed or detachable visual interfaces engineered for second- and third-row passenger engagement, typically integrating screens from 8 to 15.6 inches with resolutions up to 4K, HDMI or wireless casting protocols, and automotive-grade thermal tolerance. These systems serve commercial purposes spanning passenger distraction reduction, brand differentiation in premium segments, and incremental revenue capture through content services. Headrest screens and overhead displays currently occupy the largest installed base, while OLED panels represent the fastest-growing technology category as unit costs decline and color performance advantages harden. Family transport and executive travel applications concentrate margin pools, whereas ride-sharing services and rental fleets drive volume through standardized fleet specifications.
NHTSA guidelines govern screen placement and driver-visibility restrictions in the United States, while EU REACH and RoHS frameworks constrain hazardous substance profiles in display manufacturing. ECE R48 regulations across European markets mandate specific mounting geometries that directly shape product form factors. OEM procurement teams and Tier-1 engineering groups must monitor evolving cybersecurity standards for connected entertainment systems alongside pending harmonization between regional crash-safety and electromagnetic compatibility requirements.
Market Dynamics
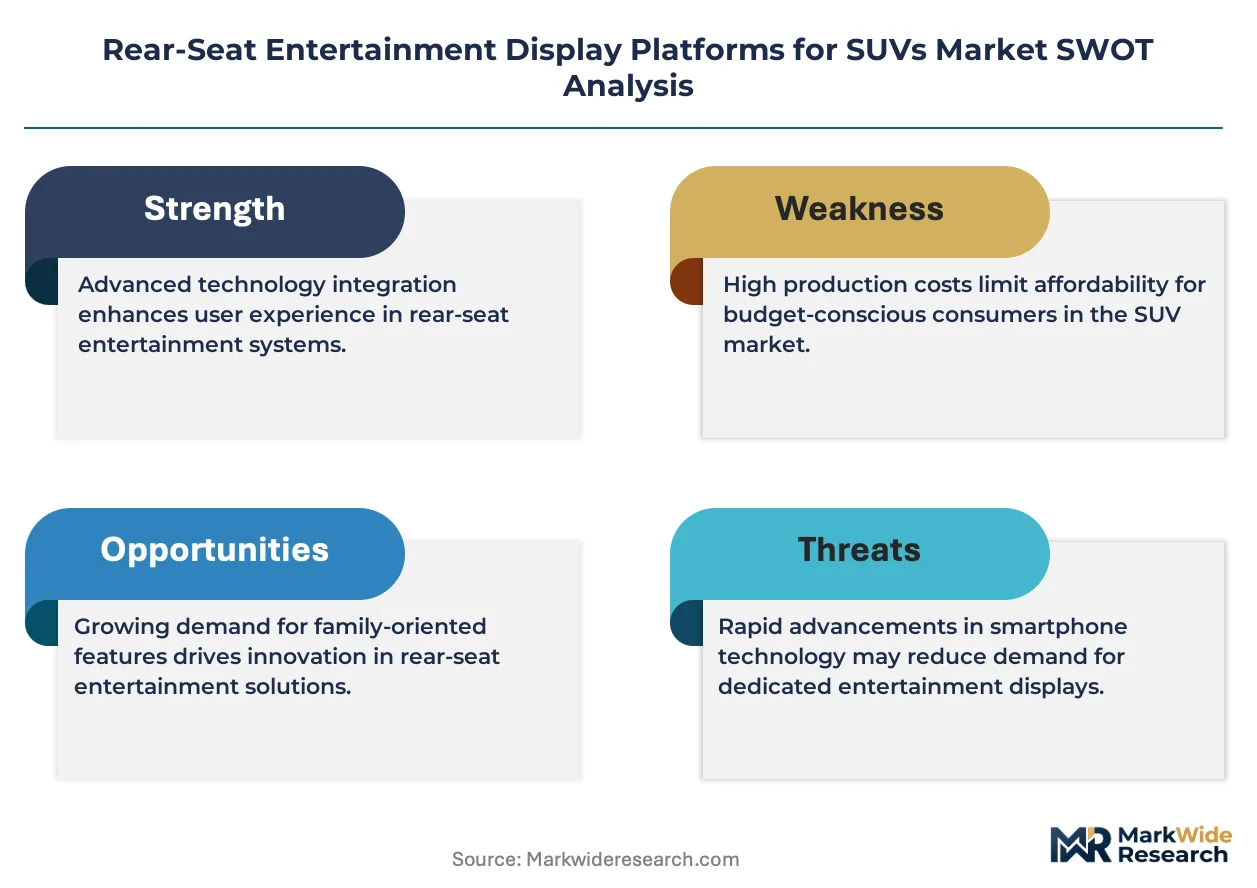
OLED panel cost curves and NHTSA mounting-geometry mandates are compressing supplier margins while forcing simultaneous investments in thermal management and optical bonding capabilities.
Growth Catalysts
- EU REACH substance restrictions:RoHS-compliant QLED chemistries are unlocking fleet procurement contracts previously blocked by hazardous material limits.
- Family transport segment concentration:Premium SUV buyers in the United States now specify 4K resolution and wireless casting as standard equipment, pulling assembly-line integration forward.
- HDMI 2.1 protocol adoption:Latency specifications below 20 milliseconds enable gaming-console compatibility, expanding addressable use cases beyond passive video.
Market Restraints
- Indium tin oxide supply concentration:Korean and Taiwanese substrate suppliers control transparent electrode deposition capacity, exposing Tier-1 integrators to input volatility.
- ECE R48 mounting-geometry mandates:European visibility-angle restrictions limit screen sizes in compact SUV architectures, constraining average selling price expansion.
- Tablet substitution threat:Consumer-owned iPad and Android devices with vehicle-mount accessories capture price-sensitive fleet segments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Display module assembly incentives are attracting module-level investment for export-oriented SUV platforms.
- Overhead OLED convergence with ambient lighting:Ceiling-mounted displays integrating tunable white LED arrays create differentiated cabin experiences in executive transport.
- Subscription content services:OEM-branded streaming partnerships generate recurring revenue streams beyond hardware margins.
Industry Challenges
- Automotive cybersecurity certification:UN R155 and ISO/SAE 21434 compliance timelines extend product development cycles by 8-14 months.
- Optical bonding capex intensity:Cleanroom-grade lamination equipment for 15.6-inch panels requires capital commitments exceeding Tier-2 balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rear-Seat Entertainment Display Platforms for SUVs Market |
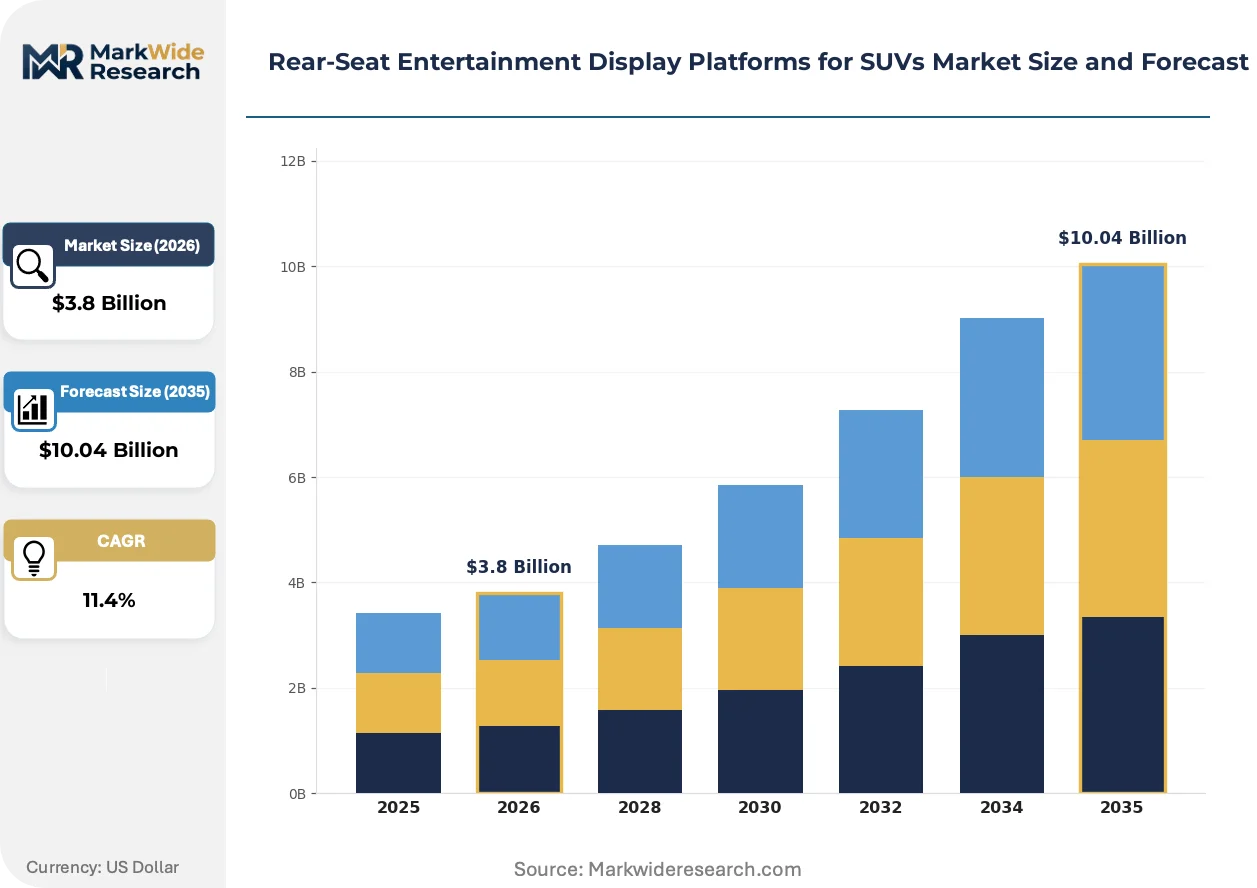
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Dash Monitors, Headrest Screens, Portable Tablets, Overhead Displays, OLED Panels Technology: LCD, OLED, QLED, LED, Touchscreen, Capacitive Application: Family Transport, Executive Travel, Ride-Sharing Services, Chauffeur Vehicles, Rental Fleets Customer Type: OEM Manufacturers, Aftermarket Installers, Tier-1 Suppliers, Car Dealerships, Fleet Operators |
| Companies Covered | Panasonic Automotive Systems, HARMAN, LG Display, Samsung Display, Continental Automotive, Alps Alpine, Robert Bosch, Valeo, Visteon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rear-Seat Entertainment Display Platforms for SUVs Market Trends and Innovations
Display technology migration and regulatory fragmentation are rewriting competitive requirements faster than product replacement cycles, compressing R&D amortization windows.
Flexible OLED substrates with polyimide backplanes are consolidating the premium tier as BMW and Mercedes-Benz specify curved 12.3-inch rear-cabin panels. These architectures reduce depth requirements by 40% versus glass-backed alternatives, enabling slimmer seatback integration. The shift is consolidating procurement around suppliers with captive thin-film transistor capacity.
NHTSA driver-distraction guidelines are tightening screen-visibility restrictions in the United States, mandating automatic dimming when forward-facing cameras detect driver eye movement. Tier-1 engineers must redesign ambient-light sensors and software arbitration layers. Luxury SUV segments absorb compliance costs through bundled packages, while mass-market platforms defer feature introduction.
Fleet procurement through rental and ride-sharing operators is consolidating volume around standardized 10.1-inch specifications with removable headrest mounting. Hertz and Enterprise Holdings now specify HDMI and USB-C as mandatory interfaces, displacing proprietary automotive connectors. This specification convergence is most visible in the United States, where fleet turnover cycles compress technology refresh windows to 24-36 months.
Rear-Seat Entertainment Display Platforms for SUVs Market Segmentation
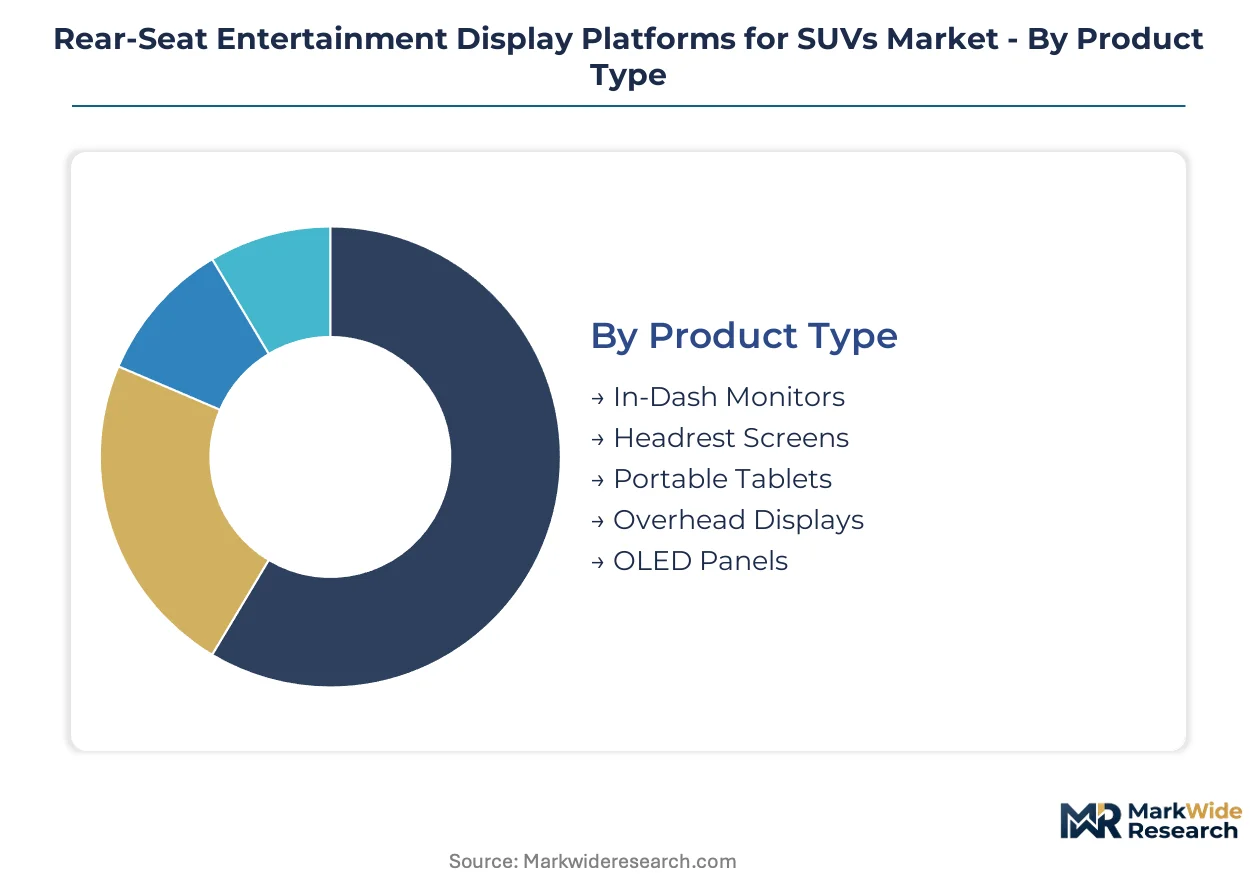
Rear-seat entertainment display platforms fragment across integration depth, display chemistry, and procurement channel. Each dimension shapes margin structure, certification burden, and replacement-cycle timing differently.
Product Type:
Standalone mounting solutions dominate fleet procurement, while embedded architectures anchor premium OEM assembly lines.
- Headrest Screens:Seatback-integrated displays from 8 to 12 inches with automotive-grade hinge mechanisms and quick-release latches for theft deterrence. Family transport specifications in the United States concentrate procurement here, with 4K resolution and wireless casting now standard in premium SUV trims.
- OLED Panels:Organic emissive displays on polyimide substrates enabling curved form factors and 40% depth reduction versus glass-backed alternatives. Executive travel segments in Germany specify these for Mercedes-Benz and BMW rear-cabin packages, pulled by color performance advantages as unit costs decline.
- In-Dash Monitors:Center-console-integrated displays serving second-row visibility through articulating armatures.
- Portable Tablets:Detachable Android or proprietary OS devices with vehicle-dock charging and thermal management.
- Overhead Displays:Ceiling-mounted flip-down screens, typically 15.6 inches, favored in rental fleet specifications.
Volume placements concentrate in Headrest Screens; the faster expansion belongs to OLED Panels.
Technology:
Cost tier and thermal tolerance separate display chemistries, with premium specifications absorbing compliance investments that mass-market configurations defer.
- QLED:Quantum-dot-enhanced LCD architectures with RoHS-compliant chemistries unlocking EU fleet procurement previously blocked by hazardous material limits. Rental operators in Germany and France specify these for 10.1-inch standardized configurations.
- OLED:Self-emissive organic diodes eliminating backlight modules and enabling flexible substrates. Luxury OEM assembly in China pulls supply through LG Display and Samsung SDI captive capacity, with curved 12.3-inch panels now specified for BMW rear-cabin integration.
- LCD:Mature thin-film transistor backplane technology dominating entry-level and mid-market SUV platforms.
- LED:Direct-lit and edge-lit configurations for overhead and ambient-integrated display applications.
- Touchscreen:Projected capacitive layers enabling gesture and multi-point input for interactive content.
- Capacitive:Advanced touch-sensing architectures with glove-compatible and moisture-rejection algorithms.
Procurement weight sits with LCD for fleet standardization; QLED and OLED are climbing the fastest on premium assembly lines.
Application:
Customer use case dictates screen size, connectivity protocol, and mounting geometry requirements across divergent duty cycles.
- Family Transport:Second- and third-row entertainment for private SUV owners, typically specifying dual 10.1-inch or single 12.3-inch headrest configurations. United States premium buyers now mandate HDMI 2.1 latency below 20 milliseconds for gaming-console compatibility, expanding use cases beyond passive video.
- Ride-Sharing Services:High-utilization commercial duty with standardized 10.1-inch removable specifications. Hertz and Enterprise Holdings in the United States specify HDMI and USB-C as mandatory interfaces, displacing proprietary automotive connectors and compressing technology refresh windows to 24-36 months.
- Executive Travel:Chauffeur-driven and owner-operated luxury transport emphasizing cabin differentiation.
- Chauffeur Vehicles:Professional driver services requiring durable mounting and passenger privacy features.
- Rental Fleets:Turnover-optimized specifications prioritizing interchangeability and theft resistance.
Installation volume favors Ride-Sharing Services; margin expansion is strongest in Family Transport.
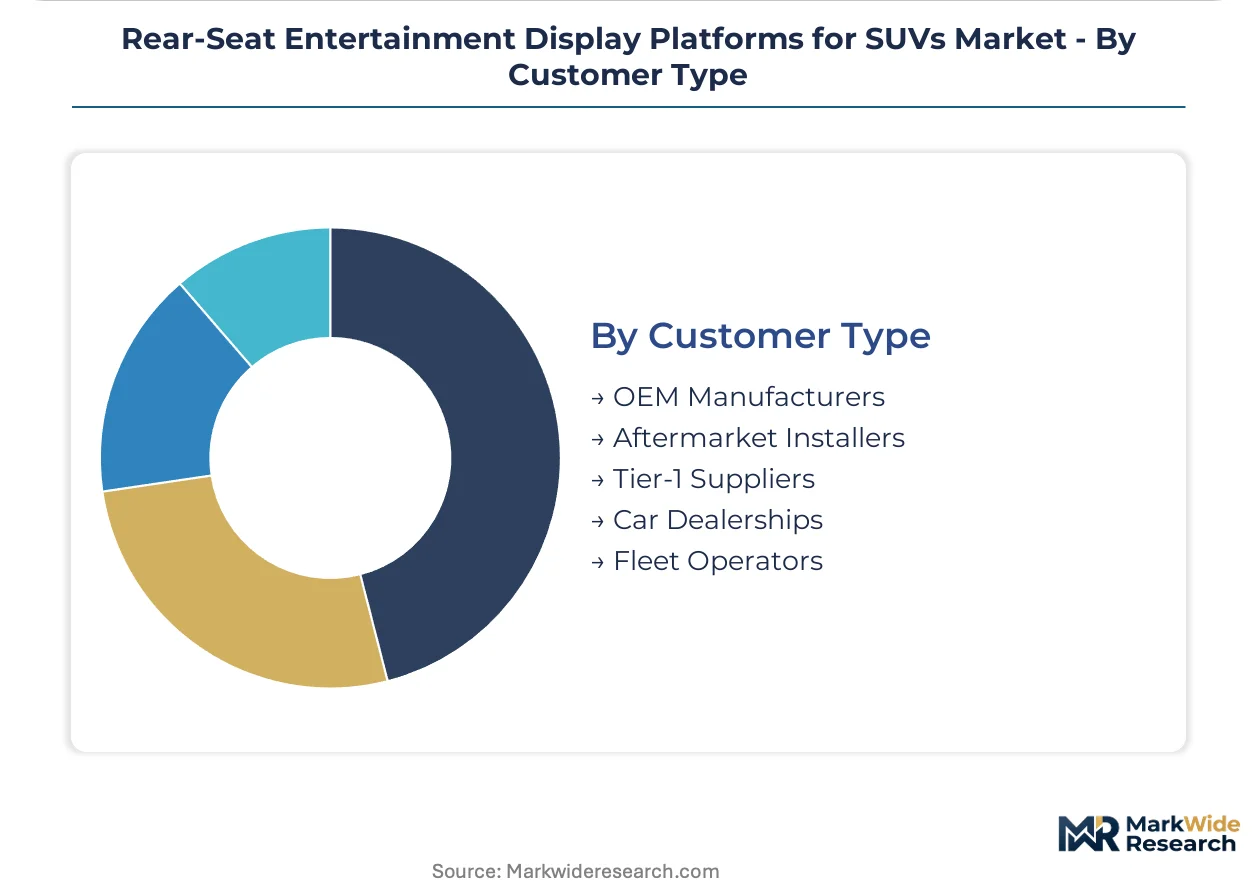
Customer Type:
Channel structure determines specification authority, with OEMs controlling embedded designs and aftermarket channels serving replacement and upgrade demand.
- OEM Manufacturers:Vehicle assemblers specifying display platforms at the design-in phase, typically sourcing through Tier-1 integrators. NHTSA driver-distraction guidelines and ECE R48 mounting-geometry mandates force simultaneous investment in thermal management and optical bonding capabilities, compressing supplier margins.
- Tier-1 Suppliers:Panasonic Automotive Systems and HARMAN consolidating procurement around fewer partners through backward integration into display module production and audio-visual integration leadership respectively.
- Aftermarket Installers:Independent service providers retrofitting headrest and overhead solutions to existing vehicles.
- Car Dealerships:Franchise and independent retailers bundling accessories at point of sale.
- Fleet Operators:Rental and ride-sharing companies standardizing specifications across vehicle pools.
Specification authority concentrates in OEM Manufacturers; aftermarket velocity runs through Aftermarket Installers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium tin oxide substrate production concentrates in Korean and Taiwanese supplier clusters, anchoring display module assembly decisions across major SUV manufacturing regions.
United States
Premium SUV assembly volumes in Detroit and Southern states pull procurement of 4K headrest screens with HDMI 2.1 protocols. NHTSA driver-distraction guidelines mandate automatic dimming systems when forward-facing cameras detect operator eye movement. Tier-1 integrators in Michigan concentrate optical bonding and thermal management investments to meet these visibility restrictions.
Germany
Executive travel specifications from Stuttgart and Munich OEMs drive demand for curved 12.3-inch OLED panels in rear-cabin configurations. ECE R48 mounting-geometry regulations constrain screen sizes in compact SUV architectures, limiting average selling price expansion. Bavarian engineering clusters specialize in polyimide substrate integration for flexible display form factors.
China
Domestic premium SUV brands in Shanghai and Guangzhou specify large-format OLED panels for family transport segments. MIIT cybersecurity standards for connected vehicle systems extend product development timelines. Yangtze River Delta display fabs anchor captive supply chains for automotive-grade panel production.
South Korea
Seoul-based panel suppliers control transparent electrode deposition capacity for OLED backplanes. KBA certification requirements for electromagnetic compatibility shape export-oriented module specifications. Busan-Ulsan industrial corridors concentrate thin-film transistor manufacturing for curved automotive displays.
India
Export-oriented SUV platform assembly in Maharashtra and Tamil Nadu attracts display module investment under the PLI scheme for electronics manufacturing. BIS automotive safety standards govern screen mounting and visibility angles. Chennai and Pune clusters specialize in 10.1-inch standardized specifications for fleet procurement contracts.
Rear-Seat Entertainment Display Platforms for SUVs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in content services and subscription platforms. The supplier base concentrates around three to four dominant integrators with captive display module production or audio-visual integration capabilities. Strategic archetypes include backward-integrated electronics conglomerates, specialist automotive Tier-1 suppliers, and captive panel manufacturers with automotive divisions. Competitive positioning hardens through long-term OEM contracts and simultaneous investments in optical bonding cleanroom capacity.
Among the backward-integrated tier, Panasonic Automotive Systems and HARMAN occupy positions exemplifying vertical control over module production and audio-visual system integration respectively. LG Display represents the captive panel manufacturer archetype with dedicated automotive OLED capacity. These three anchors illustrate how supply security and technology leadership consolidate procurement decisions among premium SUV assemblers.
| Leading Market Players |
|---|
| Panasonic Automotive Systems |
| HARMAN |
| LG Display |
| Samsung Display |
| Continental Automotive |
| Alps Alpine |
| Robert Bosch |
| Valeo |
| Visteon |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between UN R155 cybersecurity-compliant systems and uncertified alternatives manifests in both pricing stratification and supply chain configuration. Premium OEM assembly lines absorb compliance investments through bundled hardware-service packages, while mass-market platforms defer feature introduction entirely.
Pricing Analysis
Warranty and service-bundling arrangements separate premium from commodity tiers, with extended thermal-performance guarantees and optical-bonding defect coverage now standard in executive transport specifications. Price differentiation hinges on certification tier and after-sales service depth, with UN R155-compliant modules commanding substantial premiums over uncertified alternatives. Cost compression in mid-market LCD configurations is intensifying because Korean and Taiwanese substrate suppliers control transparent electrode deposition capacity. Fleet operators exhibit the highest price sensitivity, while luxury OEM procurement teams prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and refurbishment cycles concentrate in South Korea, Taiwan, and China, where display module assembly clusters support rapid turnaround for defective units. Indium tin oxide substrates, polyimide backplanes, and automotive-grade driver ICs constitute critical input dependencies. Single-source vulnerability in Korean transparent electrode deposition capacity exposes Tier-1 integrators to input volatility. Distribution runs through captive OEM supply agreements and fleet procurement contracts, with aftermarket channels serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, where UN R155 automotive cybersecurity certification creates a barrier-to-entry moat for compliant players and extends product development cycles substantially.
For Market Incumbents: Lock in long-term OLED panel offtake agreements with Korean suppliers before capacity constraints tighten further. Deepen backward integration into optical bonding cleanroom capacity to defend margin position against Tier-2 competitors unable to match capital commitments. The tablet substitution threat demands proactive content-service bundling to maintain hardware attach rates. For New Entrants and Emerging Players: Flexible substrate manufacturing expertise offers the most penetrable wedge for challenging established display module integrators. Target India's PLI-subsidized assembly corridors for export-oriented SUV platform supply, where standardized 10.1-inch fleet specifications reduce certification burden. A technology-licensing go-to-market angle bypasses direct OEM relationship requirements. For Investors and Strategic Acquirers: Re-rating potential sits with Tier-1 suppliers possessing captive cybersecurity certification capabilities given pending harmonization between regional crash-safety and electromagnetic compatibility requirements. Long-term viability over the next decade hinges on subscription content service attach rates rather than hardware margins alone. Watch for inflection signals in OEM streaming partnership announcements as recurring revenue validation.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Bonding Capacity Expansion | Cleanroom-grade lamination equipment for 15.6-inch panels secures Tier-1 positioning with BMW and Mercedes-Benz rear-cabin programs. |
| OLED Panel Supply Agreement | Long-term offtake contracts with LG Display or Samsung SDI anchor procurement decisions for curved 12.3-inch premium specifications. |
| Cybersecurity Certification Investment | UN R155 and ISO/SAE 21434 compliance capabilities extend product development timelines but lock out uncertified competitors. |
| Content Service Platform Launch | OEM-branded streaming partnerships generate recurring revenue streams beyond hardware margins in family transport segments. |
| India Manufacturing Footprint | PLI scheme incentives for display module assembly attract investment for export-oriented SUV platforms serving European and North American fleets. |
Research Methodology
Independent corroboration across Tier-1 supplier procurement leads, OEM platform engineering directors, and fleet operator specification managers underwrites the qualitative findings. Primary interviews with optical bonding equipment vendors, thermal management specialists, and automotive cybersecurity consultants combined with secondary validation from NHTSA guidance documents, ECE R48 regulatory filings, and MIIT connected vehicle standards. Vehicle production databases, IHS Markit registration data, and customs records on display module trade flows enabled bottom-up and top-down triangulation across the analysis window.
Comparable-period anchoring to historical premium SUV assembly volumes and technology refresh cycles shaped the projection horizon. The analytical framework modeled segmentation across display chemistry, integration depth, procurement channel, vehicle class, and regional regulatory cluster. CAGRs were derived from unit economics analysis and content-per-vehicle trajectories, with OLED cost curves and NHTSA mounting-geometry mandates as primary forecast inputs.
Several conditions sit outside the modeled scope, including potential harmonization of cybersecurity standards between NHTSA and EU frameworks, and abrupt indium supply disruptions from geopolitical events. Forecasts reflect documented assumptions about panel cost decline rates and fleet turnover cycles. Practitioners should monitor OEM streaming partnership announcements and PLI scheme capacity commitments for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Data Logger Market