
 Asia-Pacific Automotive Smart Key Market | 2026-2036
Asia-Pacific Automotive Smart Key Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Smart Key Market Outlook
GB/T automotive cybersecurity certification is collapsing the supplier base for connected entry systems in China. Continental AG leverages its integrated hardware-software stack to sustain qualification across multiple OEM programs. Denso Corporation anchors Japanese domestic supply through captive relationships with Toyota and Lexus. HELLA GmbH and Co. KGaA competes on European-derived encryption architectures adapted for Asia-Pacific vehicle platforms.
An automotive smart key is a wireless electronic access device that authenticates vehicle entry through encrypted radio-frequency communication, typically operating at 315 MHz or 433 MHz bands with rolling-code protocols for anti-relay protection. The device eliminates mechanical key insertion while enabling passive entry, remote start, and personalized driver profile loading through secure handshake sequences with onboard immobilizer modules. Smart Key Fob and Keyless Start/Go configurations lead volume shipments across the region, though Biometric Key integration is gaining traction as OEMs differentiate premium electric vehicle lineups. RFID and Bluetooth technologies dominate current production, while NFC adoption accelerates in smartphone-as-key deployments where handset OEMs partner directly with Tier-1 suppliers.
China's MIIT enforces GB/T standards for connected vehicle data security, compelling smart key suppliers to embed hardware security modules and encrypted key storage. Japan's METI and PMDA coordinate JIS authentication requirements with automotive cybersecurity frameworks, creating dual compliance obligations for cross-border component suppliers. India's BIS and TRAI are developing localization mandates for telematics and connected vehicle subsystems, reshaping procurement patterns for multinational Tier-1s. Stakeholders must monitor divergence between national encryption standards and smartphone ecosystem key-sharing protocols, as interoperability decisions by Apple and Google will determine which technology pathways achieve scale.
Market Dynamics
China's MIIT cybersecurity certification for connected vehicles is compressing the supplier base for automotive entry systems, forcing Tier-1s to embed hardware security modules and encrypted key storage while Japanese OEMs accelerate standard fitment across mid-range vehicle trims.
Growth Catalysts
- Passive Entry System Standardization:Premium passenger car OEMs in Japan and South Korea are expanding smart key adoption as standard fitment across mid-range trims, normalizing proximity-based authentication for mass-market vehicles.
- GB/T Cybersecurity Mandates:China's MIIT enforcement of connected vehicle data security standards compels hardware security module integration, creating qualification barriers that favor technically capable suppliers.
- Yangtze River Delta Cluster Demand:Domestic EV manufacturers in China's automotive manufacturing corridor source proximity-based entry systems at scale, concentrating procurement volume in a single geographic production hub.
Market Restraints
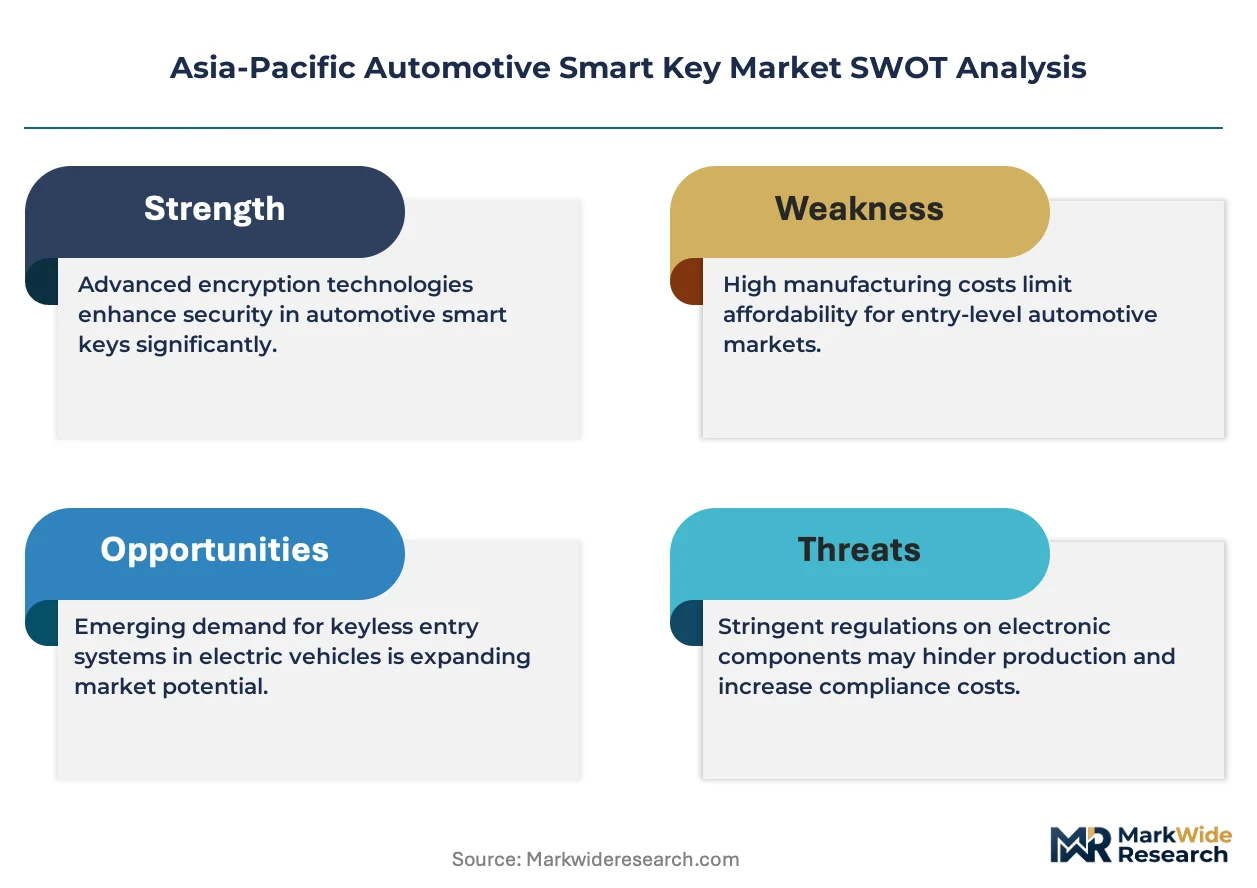
- Semiconductor Supply Concentration:RF transceiver and secure element fabrication concentrates among specialized foundries, exposing smart key module production to input bottlenecks.
- Dual Compliance Burden:Cross-border component suppliers face overlapping obligations from China's GB/T standards and Japan's JIS authentication protocols, extending qualification timelines.
- Smartphone-as-Key Substitution:NFC and Bluetooth Low Energy handset integration threatens dedicated fob volumes as Apple and Google expand digital key ecosystems.
Strategic Opportunities
- Biometric Key Integration:Fingerprint and facial recognition modules represent whitespace for premium electric vehicle lineups seeking cabin personalization differentiation.
- India Localization Mandates:BIS and TRAI development of domestic content requirements for telematics subsystems creates first-mover advantage for localized manufacturing investments.
- UWB-BLE Convergence:Ultra-wideband precision ranging combined with Bluetooth Low Energy enables centimeter-accurate passive entry while supporting smartphone key interoperability.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Hardware security module design and rolling-code protocol implementation require specialized firmware expertise that outpaces regional education pipeline output.
- Legacy Immobilizer Integration:Backward compatibility with 315 MHz and 433 MHz RF architectures complicates next-generation platform development for multi-generational vehicle programs.
- Smartphone Ecosystem Dependency:Interoperability decisions by Apple and Google determine which technology pathways achieve scale, constraining OEM and Tier-1 strategic autonomy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Smart Key Market |
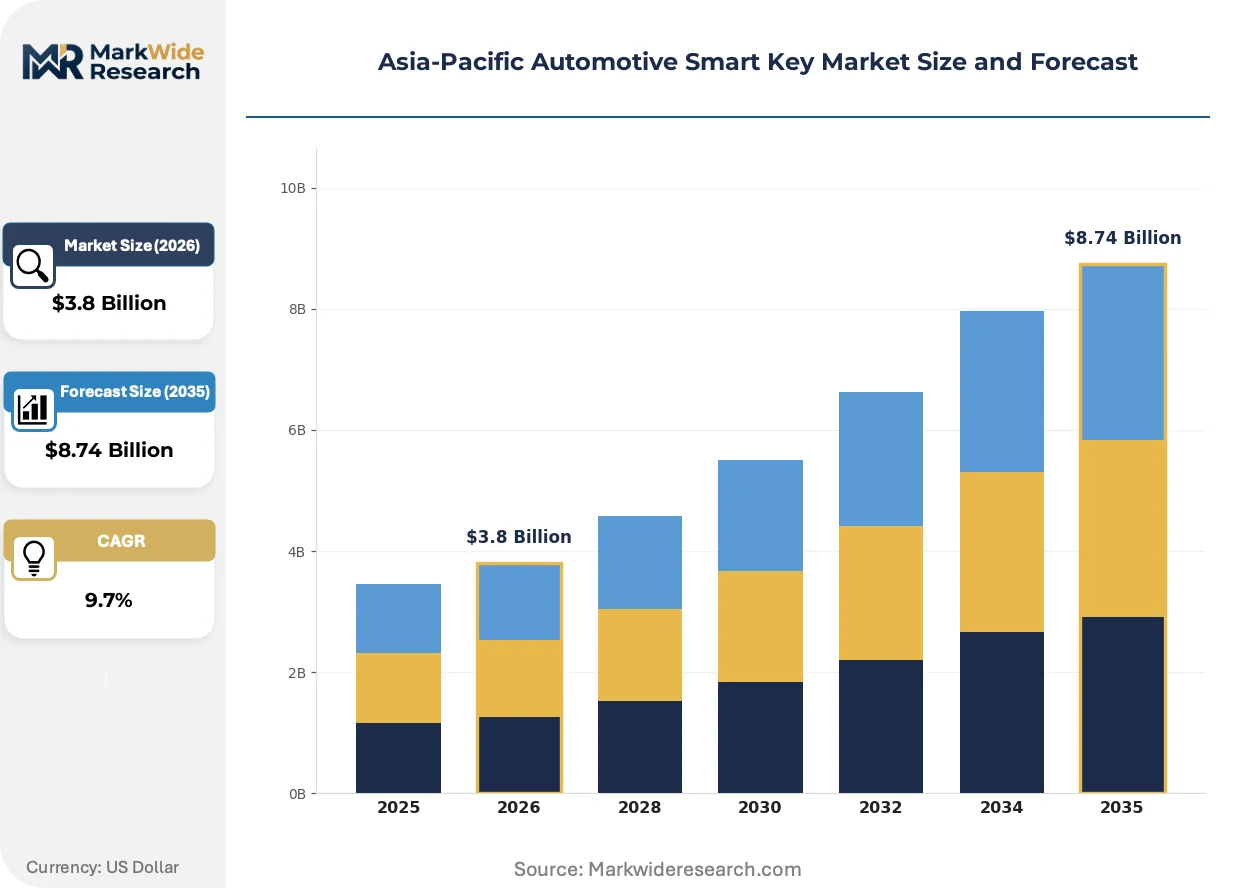
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Keyless Entry, Smart Key Fob, Keyless Start/Go, Biometric Key End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: RFID, Bluetooth, NFC, Infrared Application: Luxury Vehicles, Commercial Vehicles, Passenger Cars, Electric Vehicles |
| Companies Covered | Continental AG, Denso Corporation, HELLA GmbH and Co. KGaA, Honda Lock Mfg. Co., Ltd., Hyundai Mobis, Tokai Rika Co., Ltd., ZF Friedrichshafen AG, Valeo SA, Huf Hulsbeck & Furst GmbH & Co. KG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Smart Key Market Strategic Shifts
Automotive smart key architectures are converging around smartphone-centric authentication models while hardware form factors compress and regulatory cybersecurity requirements harden across Asia-Pacific production corridors.
Ultra-wideband positioning technology is replacing legacy RFID for passive entry applications, enabling centimeter-accurate spatial detection that eliminates relay attack vulnerabilities. Chinese EV manufacturers in the Yangtze River Delta cluster are adopting UWB-BLE hybrid modules for 2025 model year vehicles. The technology stack is miniaturizing from discrete component assemblies to single-package system-in-package solutions that reduce fob and vehicle-side module footprints.
Japan's METI coordination with PMDA on JIS authentication requirements is tightening product qualification frameworks for automotive cybersecurity components. Suppliers must demonstrate compliance with both automotive-specific standards and cross-sector encryption protocols before commercial deployment. Japanese domestic OEMs and their captive Tier-1 relationships are absorbing compliance costs faster than multinational competitors attempting market entry.
Fleet procurement of smart key systems is fragmenting across direct OEM supply, aftermarket channel expansion, and smartphone ecosystem partnerships. Traditional Tier-1 distribution through vehicle assembly integration faces displacement by handset OEM direct partnerships for digital key deployment. South Korean automotive groups are most exposed to this channel restructuring due to Samsung and LG Electronics' integrated device and component strategies.
Asia-Pacific Automotive Smart Key Market Segmentation
Smart key procurement patterns in the Asia-Pacific region diverge sharply across product tiers and customer channels. Regulatory frameworks in China, Japan, and South Korea create asymmetric qualification requirements that reshape how segments compete for volume.
Product Type:
China's GB/T cybersecurity mandates and Japan's JIS authentication protocols impose divergent hardware security requirements on each product category.
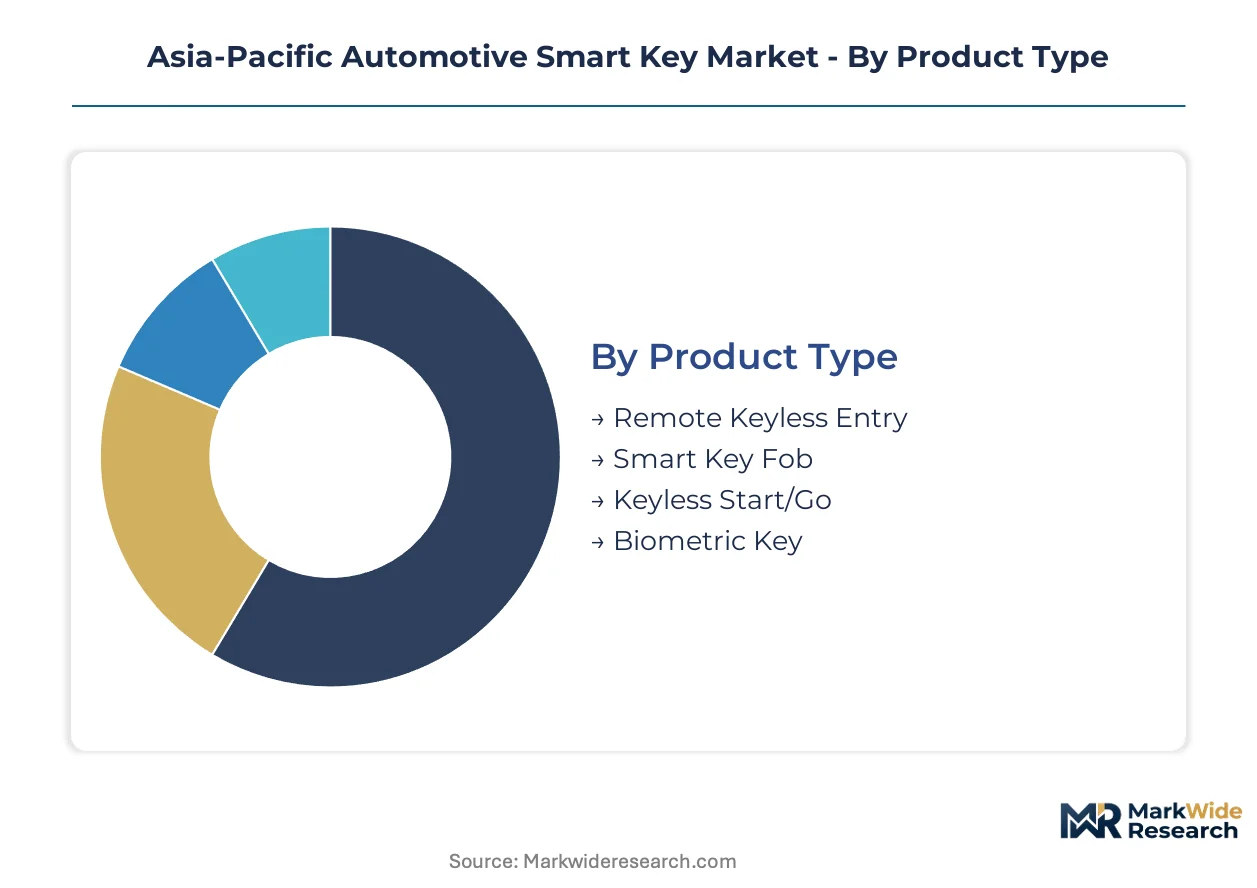
- Smart Key Fob:Encrypted radio-frequency devices operating at 315 MHz or 433 MHz bands with rolling-code protocols for anti-relay protection. Yangtze River Delta EV manufacturers source these proximity-based systems at scale for mid-range and premium vehicle trims, though semiconductor supply concentration in specialized foundries creates input bottlenecks.
- Keyless Start/Go:Passive entry systems eliminating mechanical key insertion through secure handshake sequences with onboard immobilizer modules. Japanese and South Korean OEMs are standardizing this configuration across mass-market vehicle lines, normalizing proximity authentication beyond luxury segments.
- Remote Keyless Entry:Basic RF-based door unlocking without passive detection capabilities.
- Biometric Key:Fingerprint and facial recognition modules for cabin personalization in premium electric vehicle lineups.
Smart Key Fob handles the majority of throughput; Biometric Key is expanding most quickly on share.
End User:
Channel structures are fragmenting as smartphone ecosystem partnerships displace traditional Tier-1 distribution pathways.
- OEMs:Direct vehicle assembly integration of smart key modules through captive supply relationships. Toyota and Lexus anchor Japanese domestic procurement through Denso Corporation, while Chinese EV manufacturers concentrate demand in the Yangtze River Delta cluster.
- Tier-1 Suppliers:Technical qualification barriers from GB/T and JIS compliance favor integrated hardware-software stack providers capable of sustaining multi-OEM programs across cybersecurity frameworks.
- Aftermarket Providers:Secondary channel for replacement fobs and retrofit systems.
- Dealerships:Localized distribution point for spare key programming and customer-facing services.
OEMs dominate procurement volume; Tier-1 Suppliers are climbing the fastest as qualification barriers reshape vendor selection.
Technology:
Frequency bands and encryption architectures determine regional qualification feasibility and interoperability with smartphone ecosystems.
- RFID:Legacy 315 MHz and 433 MHz radio-frequency identification dominating current production volumes. Backward compatibility requirements with existing immobilizer architectures complicate next-generation platform development for multi-generational vehicle programs.
- Bluetooth:Low Energy protocols enabling smartphone-as-key deployments where handset OEMs partner directly with automotive suppliers. South Korean automotive groups face particular channel restructuring exposure due to Samsung and LG Electronics' integrated strategies.
- NFC:Near-field communication accelerating in smartphone-centric authentication models.
- Infrared:Legacy directional transmission technology with limited current adoption.
RFID maintains installed base dominance; Bluetooth is gaining share fastest through handset ecosystem convergence.
Application:
Vehicle electrification and trim standardization are redistributing smart key demand across passenger and commercial segments.
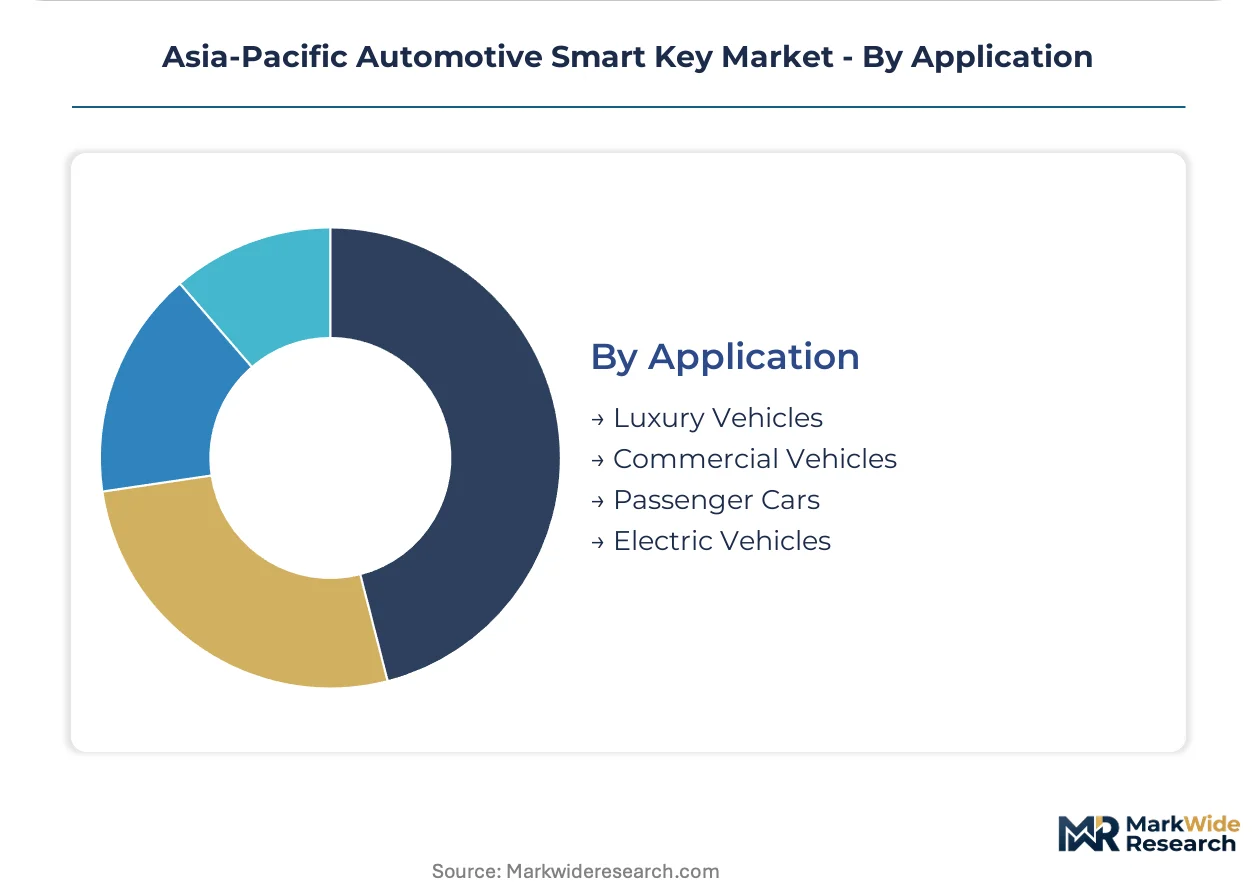
- Passenger Cars:Volume anchor for proximity-based entry systems across mid-range and premium trims. Japanese and South Korean OEMs are accelerating standard fitment normalization, compressing the timeline for mass-market adoption.
- Electric Vehicles:Technology differentiation vector where UWB-BLE hybrid modules enable centimeter-accurate passive entry. Chinese EV manufacturers in the Yangtze River Delta cluster are adopting these architectures for upcoming model year vehicles.
- Luxury Vehicles:Premium segment driving biometric integration and personalized driver profile loading.
- Commercial Vehicles:Fleet procurement segment with distinct durability and multi-user authentication requirements.
Passenger Cars handle the majority of throughput; Electric Vehicles show the steepest expansion trajectory as domestic Chinese manufacturers scale production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT cybersecurity mandates and JIS authentication protocols are reshaping procurement corridors across Asia-Pacific, compressing supplier bases while concentrating demand in established manufacturing clusters.
China
Yangtze River Delta EV manufacturers source proximity-based entry systems at scale for domestic and export programs. MIIT enforcement of GB/T connected vehicle data security standards compels hardware security module integration, creating qualification barriers that favor technically capable suppliers with integrated hardware-software stacks. Shanghai and Suzhou anchor production for smart key modules serving BYD, NIO, and XPeng assembly lines.
Japan
Toyota and Lexus normalize smart key standard fitment across mid-range vehicle trims, expanding addressable volume beyond luxury segments. METI coordination with PMDA on JIS authentication requirements tightens product qualification frameworks, creating dual compliance obligations for cross-border component suppliers. Aichi Prefecture's automotive corridor concentrates captive supply relationships through Denso Corporation and Tokai Rika Co., Ltd.
South Korea
Hyundai Mobis and Kia Motors accelerate passive entry system deployment across mass-market vehicle lines. Samsung and LG Electronics' integrated device strategies expose domestic automotive groups to smartphone-as-key channel restructuring. Gyeonggi-do's Seoul Capital Area manufacturing belt hosts concentrated R&D activity for UWB-BLE hybrid authentication modules.
India
BIS and TRAI development of localization mandates for telematics subsystems reshapes procurement patterns for multinational Tier-1s. Maruti Suzuki and Tata Motors drive initial smart key adoption in premium passenger car segments. Tamil Nadu and Gujarat automotive clusters attract first-mover manufacturing investments seeking compliance with emerging domestic content requirements.
Australia
Fleet procurement of proximity-based entry systems concentrates in mining and resource sector commercial vehicles with multi-user authentication requirements. Toyota Australia and Ford Motor Company import smart key modules through established Asia-Pacific supply chains. Victoria's automotive component manufacturing base serves limited domestic assembly and aftermarket retrofit channels.
Asia-Pacific Automotive Smart Key Market Competitive Environment
Player mix skews toward diversified automotive electronics conglomerates with captive OEM relationships and integrated hardware-software capabilities. Market structure concentrates around Japanese keiretsu-affiliated suppliers and German system integrators with multi-regional qualification portfolios. Three archetypes dominate: captive Tier-1s serving single OEM families, independent module specialists competing on encryption architecture differentiation, and diversified conglomerates leveraging cross-divisional technology transfer. Competitive moves center on cybersecurity certification pre-emption and smartphone ecosystem partnership formation.
Among diversified German system integrators, Continental AG exemplifies the multi-OEM qualification archetype through sustained compliance across divergent national cybersecurity frameworks. Denso Corporation anchors the captive Tier-1 model through exclusive supply relationships with Toyota and Lexus production networks. HELLA GmbH and Co. KGaA occupies a position representing European-derived encryption architectures adapted for Asia-Pacific regulatory environments.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| HELLA GmbH and Co. KGaA |
| Honda Lock Mfg. Co., Ltd. |
| Hyundai Mobis |
| Tokai Rika Co., Ltd. |
| ZF Friedrichshafen AG |
| Valeo SA |
| Huf Hulsbeck & Furst GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
UWB-BLE hybrid module substitution for legacy RFID architectures is redistributing procurement toward Yangtze River Delta contract manufacturers while compressing margins on 315 MHz and 433 MHz component tiers. GB/T cybersecurity certification costs are embedding into supplier quotations, creating divergence between qualified and unqualified vendor pricing.
Pricing Analysis
Certification tier creates the primary spread across supplier quotations, with GB/T and JIS-compliant modules commanding premium positioning against uncertified alternatives. Three-tier pricing structure separates hardware security module-embedded units from basic rolling-code fobs and economy-grade remote entry systems. Pricing pressure stems from smartphone-as-key substitution threatening dedicated fob volumes. Fleet procurement managers exhibit highest price sensitivity, while luxury OEMs prioritize cybersecurity qualification over unit cost.
Supply Chain Analysis
China and Taiwan anchor secure element and RF transceiver fabrication, while South Korea concentrates UWB-BLE hybrid module assembly. Silicon wafers, cryptographic processors, and antenna substrates constitute critical input dependencies. Single-source vulnerability in specialized foundry capacity exposes production schedules to allocation constraints. Distribution runs through captive Tier-1 channels toward OEM assembly plants, with aftermarket retrofit representing secondary flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national cybersecurity frameworks creates specialized qualification niches for technically capable suppliers. Smartphone ecosystem partnerships are splitting traditional Tier-1 distribution channels, opening entry points for non-traditional competitors.
For Market Incumbents: Fortify GB/T and JIS certification portfolios to sustain multi-OEM program eligibility against emerging regional specialists. Deepen captive relationships with Toyota and Hyundai-Kia production networks to offset smartphone-as-key channel displacement. Prioritize UWB-BLE hybrid module R&D to maintain technology leadership as Chinese EV manufacturers scale adoption.
For New Entrants and Emerging Players: Anchor in India's Tamil Nadu and Gujarat automotive clusters ahead of BIS localization mandate enforcement. Target biometric key integration for premium electric vehicle lineups where cabin personalization differentiation commands margin. Pursue direct handset OEM partnerships for NFC smartphone-as-key deployments, bypassing traditional Tier-1 distribution chokepoints.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated hardware-software stack providers with sustained qualification across divergent national cybersecurity frameworks. Long-term viability hinges on cryptographic engineering talent depth and smartphone ecosystem partnership access. Monitor Apple and Google interoperability protocol announcements as inflection indicators for technology pathway scale potential.
| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Certification Pre-emption | Early qualification secures access to Yangtze River Delta EV procurement pipelines. |
| Handset OEM Partnership Formation | Direct collaboration with Samsung and LG Electronics displaces traditional Tier-1 distribution. |
| UWB-BLE Hybrid Module Development | Centimeter-accurate ranging eliminates relay attack vulnerabilities for Chinese EV manufacturers. |
| India Manufacturing Localization | Tamil Nadu and Gujarat investments anticipate BIS domestic content requirement enforcement. |
| Biometric Key Integration | Fingerprint and facial recognition modules differentiate premium electric vehicle cabin personalization. |
Study Parameters
A standing panel of Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers provided ongoing calibration across primary fieldwork. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT GB/T certification filings, and METI JIS standard documentation. Bottom-up module shipment analysis and top-down OEM program penetration estimates underwent iterative reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs were derived from fitted growth curves applied to qualification-constrained supply expansion. Smartphone ecosystem partnership announcements and cybersecurity framework enforcement timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained GB/T and JIS enforcement, stable semiconductor foundry allocation, and gradual smartphone-as-key adoption; material deviation would warrant model refresh. Specific risk factors include divergence between national encryption standards and handset ecosystem protocols, plus cryptographic engineering talent pipeline constraints. Recalibration cycles align with material shifts in regulatory enforcement schedules and smartphone interoperability announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market