
 Global Automotive Audio Speakers Market | 2026-2036
Global Automotive Audio Speakers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Audio Speakers Market Intelligence
The shift from basic audio in economy cars to premium, multi-speaker systems in mainstream vehicles is broadening the addressable market. Harman International dominates the OEM-integrated premium audio space through deep partnerships with global automakers. Bose leverages its unique expertise in acoustics and active noise-cancellation for specialized cabin sound management solutions. Pioneer Corporation competes aggressively in the global aftermarket, offering a wide array of speaker types for custom installations.
Automotive audio speakers are transducers converting electrical signals into sound within a vehicle's cabin. They are engineered with materials like polypropylene cones to withstand the temperature variations and vibrations inside door panels. While coaxial speakers represent a high-volume product, the component speaker segment, which includes separate tweeters and subwoofers, delivers superior acoustic performance and generates higher margins. The OEM end-user channel drives market volume, with aftermarket providers serving a specialized enthusiast base.
The European Union's RoHS directive restricts hazardous substances in electronic components, impacting material selection for speaker magnets and wiring. Concurrently, wireless audio systems must comply with FCC Part 15 regulations in the United States and specific GB standards for radio frequency devices in China. The primary strategic decision for suppliers is how to allocate resources between high-volume OEM contracts and the higher-margin, brand-driven aftermarket channel.
Market Dynamics
The central structural force shaping the automotive audio speaker market is the architectural pivot of vehicles towards software-defined platforms. This transition elevates cabin electronics, making advanced, multi-speaker, and acoustically managed sound systems a key competitive differentiator for automakers.
Growth Catalysts
- Electric Vehicle Adoption:The quiet cabins of electric vehicles amplify the need for active noise cancellation and premium sound, creating a dedicated, high-value demand stream for sophisticated speaker systems.
- Premiumization in Mainstream Segments:Consumer demand for luxury-grade features in non-premium vehicles is compelling automakers to offer branded, multi-speaker audio packages as optional upgrades, expanding the addressable market.
- Neodymium Magnet Technology:The use of lightweight, powerful neodymium magnets enables the design of smaller, more efficient speakers that deliver superior performance without adding significant weight, a critical factor for vehicle efficiency.
Market Restraints
- Input Cost Volatility:The market is exposed to price fluctuations and supply chain instability for rare earth elements, particularly neodymium and dysprosium, which are essential for high-performance speaker magnets.
- Design Cycle Complexity:Long vehicle development cycles mean speaker suppliers must commit to designs years in advance, creating a risk of technological obsolescence and difficulty adapting to rapid shifts in consumer electronics trends.
- Acoustic Tuning Costs:The significant engineering investment required to custom-tune audio systems for the unique acoustic properties of each vehicle model's interior presents a high barrier to entry and a major cost for suppliers.
Strategic Opportunities
- Immersive Audio Software:Licensing advanced digital signal processing (DSP) algorithms for 3D sound, sound zoning, and personalized audio represents a high-margin opportunity beyond the hardware itself.
- Aftermarket in Developing Economies:A growing middle class and an expanding fleet of used cars in countries like India and Brazil create a substantial opportunity for branded aftermarket speaker upgrades.
- Integration with Driver Alerts:Speakers can be integrated into Advanced Driver-Assistance Systems (ADAS) to provide directional audio alerts, enhancing safety and creating a new functional application for cabin audio.
Industry Challenges
- Software Integration Complexity:Ensuring seamless interoperability between the speaker system's software, the vehicle's infotainment head unit, and various operating systems poses a significant integration challenge for suppliers.
- Compliance with RF Standards:Wireless and connected speaker systems must navigate a complex web of radio frequency regulations, including FCC Part 15 in the US and specific GB standards in China, adding to development time and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Audio Speakers Market |
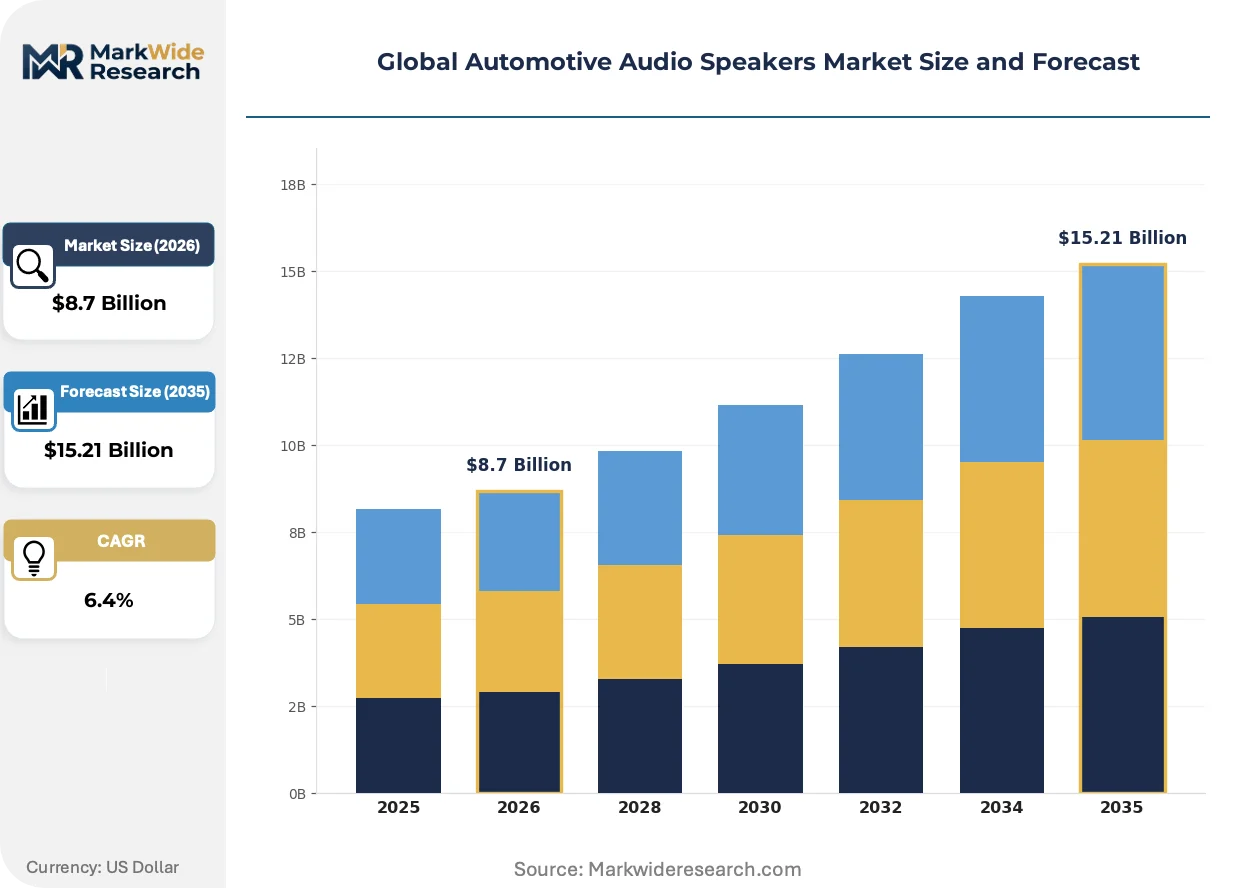
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Speaker Type: Coaxial, Component, Subwoofer, Tweeter, Midrange Technology: Wired, Wireless, Bluetooth, Active, Passive Installation Type: Dashboard, Door Panel, Rear Deck, Roof Mounted, Custom Setup End User: OEMs, Vehicle Assemblers, Aftermarket Providers, Car Audio Shops |
| Companies Covered | Pioneer Corporation, Yanfeng Visteon, Harman International, JL Audio, Sony, Bose, JVCKENWOOD Corporation, Blaupunkt, Alpine Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Audio Speakers Market Strategic Shifts & Innovations
Automotive audio is transforming from a passive component into an active, intelligent system within the vehicle's electronic architecture. Innovations in material science and digital signal processing are creating more immersive and personalized in-cabin soundscapes, directly influencing vehicle purchasing decisions.
Component speaker systems separate tweeters, mid-range drivers, and subwoofers to allow for acoustically optimized placement within the vehicle cabin. Automakers in the premium and electric vehicle segments are increasingly adopting this approach to deliver superior sound staging and clarity. This trend is modularizing the in-cabin audio architecture, enabling greater OEM customization and simplifying aftermarket upgrades.
The European Union's RoHS directive restricts hazardous materials in electronic components, directly impacting speaker manufacturing. This regulation forces a redesign of components to eliminate substances like lead in solder and certain chemicals in cones and surrounds. Global suppliers are most affected, as they must harmonize their entire product portfolio to meet these stringent standards for market access into Europe.
A discernible shift in purchasing patterns is the rise of "OEM-plus" upgrades, where consumers replace standard factory speakers with higher-performance, model-specific kits from aftermarket brands. This behavior blends the OEM and aftermarket channels, as speaker manufacturers develop products designed for easy installation in specific vehicles. This trend is particularly prominent in the sport compact and truck segments in North America.
Global Automotive Audio Speakers Market Segmentation
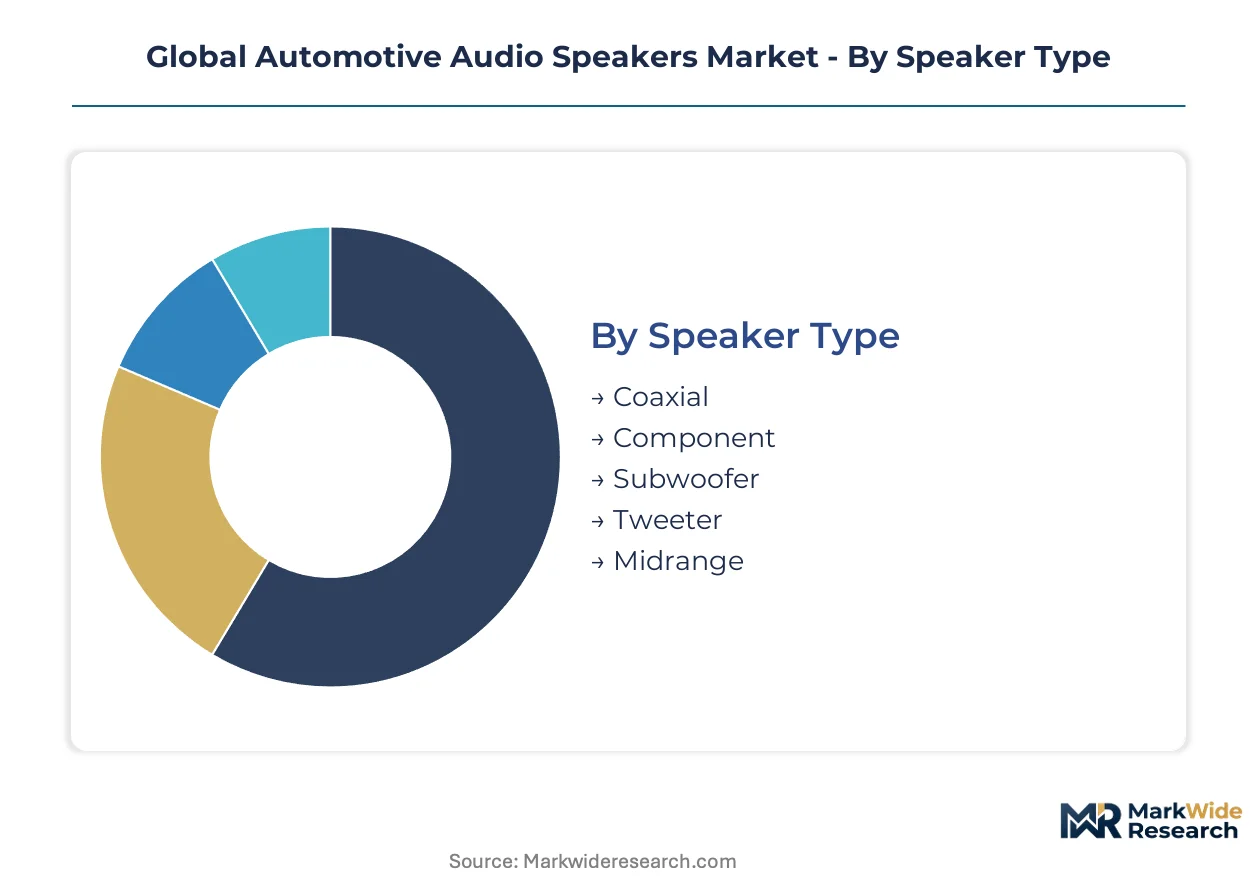
The automotive audio speakers market segmentation reflects the diverse requirements of vehicle manufacturers and consumer preferences for in-cabin sound. Understanding these distinct segments allows suppliers to tailor product development and market strategies for specific niches within the industry.
Speaker Type:
Buyer differentiation in speaker types hinges on desired acoustic performance and integration complexity within the vehicle.
- Component:These systems separate tweeters, mid-range drivers, and subwoofers, enabling acoustically optimized placement within the vehicle cabin. Automakers in premium and electric vehicle segments adopt this approach for superior sound staging and clarity.
- Coaxial:A single speaker unit integrates multiple sound-producing elements, simplifying installation and reducing space requirements. This represents a high-volume product, often standard in mainstream vehicles due to its cost-effectiveness and balanced sound output.
- Subwoofer:A specialized speaker designed to reproduce very low audio frequencies, enhancing bass response and overall sound richness.
- Tweeter:A small, dedicated speaker that handles high audio frequencies, delivering crisp and detailed treble sounds.
- Midrange:This speaker type reproduces the middle range of audio frequencies, crucial for vocal clarity and instrument definition.
Coaxial speakers lead volumes today; component systems are gaining share fastest.
Technology:
The functional integration and power delivery mechanisms define the technology segment for automotive audio speakers.
- Wireless:These systems transmit audio signals without physical cables, offering significant installation flexibility and reducing wiring harness complexity. They must comply with complex radio frequency standards, including FCC Part 15 in the US and GB standards in China.
- Active:Speakers incorporating built-in amplification and often digital signal processing (DSP) to optimize sound output. This technology delivers precisely tuned audio and enables advanced acoustic management within the vehicle cabin.
- Wired:Traditional speaker systems connect via physical cables, providing reliable signal transmission and power delivery. This remains the foundational technology for most standard installations.
- Bluetooth:A short-range wireless standard specifically used for streaming audio from personal devices to the vehicle's sound system.
- Passive:These speakers require external amplification and rely on external crossovers to direct appropriate frequencies to each driver.
While wired systems remain foundational, wireless technologies exhibit the steepest expansion trajectory.
Installation Type:
Acoustic placement and vehicle integration considerations largely determine the choice of installation type for automotive audio speakers.
- Door Panel:This is a primary location for mid-range drivers and woofers, designed to withstand the temperature variations and vibrations inside the door. This location drives significant market volume for standard speaker designs.
- Custom Setup:Tailored speaker placement and enclosure design optimize sound staging and personalization for specific vehicle interiors. This approach is popular among aftermarket enthusiasts seeking superior acoustic performance.
- Dashboard:Speakers mounted on the dashboard, often tweeters, contribute to the front sound stage and improve sound imaging for occupants.
- Rear Deck:This location is commonly used for subwoofers or full-range speakers, contributing to overall cabin sound and bass reinforcement.
- Roof Mounted:Less common, these speakers are utilized for immersive audio experiences or to create specific sound zones within the vehicle cabin.
Door panel installations dominate OEM volumes, with custom setups capturing specialized enthusiast demand.
End User:
Procurement channels and market access strategies differentiate the end-user segments for automotive audio speakers.
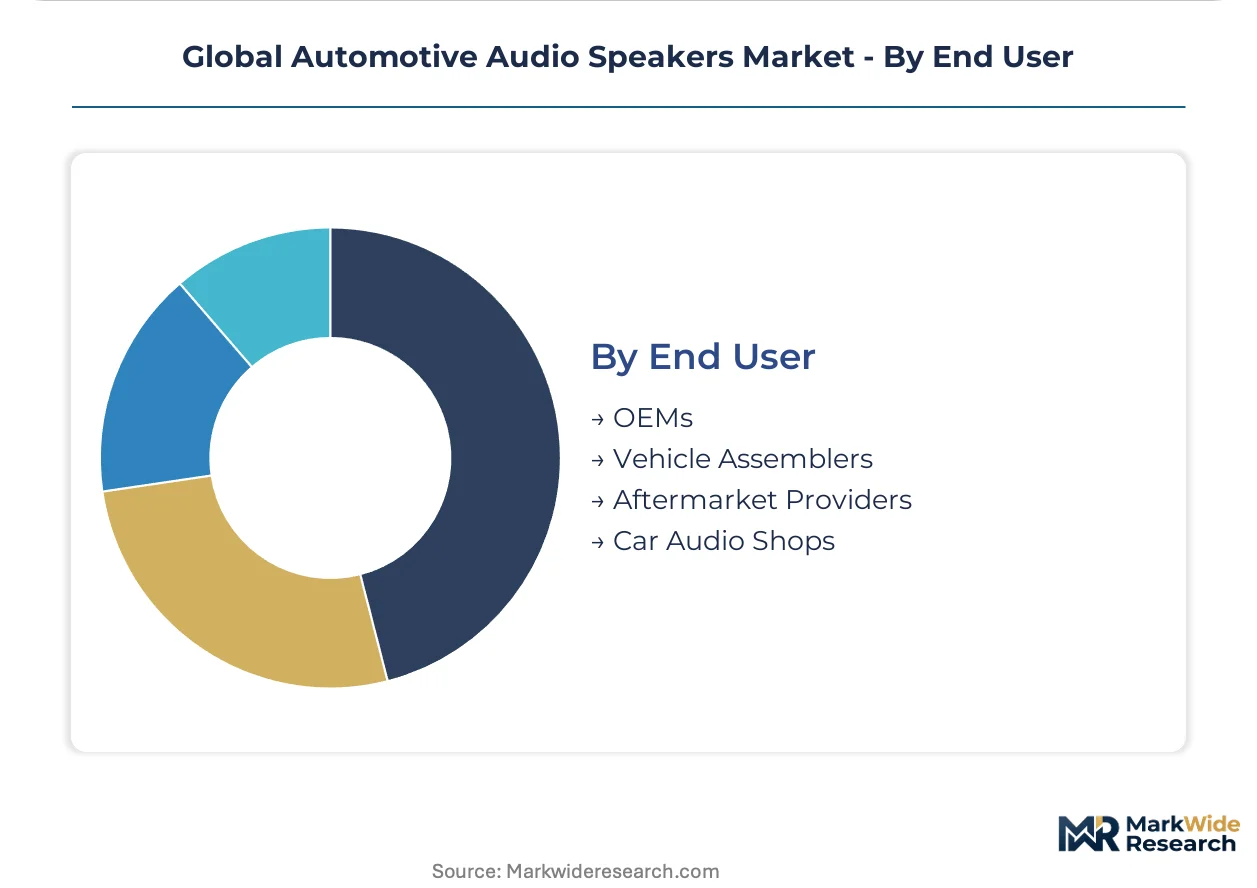
- OEMs:Original Equipment Manufacturers integrate speaker systems directly into new vehicles during the production process. This channel drives significant market volume and requires long design commitments from suppliers.
- Aftermarket Providers:These entities supply speakers for post-purchase upgrades and custom installations, catering to a specialized enthusiast base. Aftermarket providers often achieve higher margins on branded products.
- Vehicle Assemblers:These companies integrate components from various suppliers, including speaker systems, into final vehicle products.
- Car Audio Shops:These specialized retailers and installers focus on selling and fitting automotive sound systems directly to consumers.
OEMs command the largest share of procurement, while aftermarket channels offer higher margin opportunities for suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of automotive audio speakers is increasingly influenced by regulatory environments, with some manufacturing shifting to regions offering more favorable compliance costs. This dynamic creates a cost-of-compliance gap, impacting supplier investment decisions and global supply chain configurations. Companies evaluate regional directives like material restrictions and radio frequency standards when establishing production hubs.
China
China's robust electric vehicle adoption and expanding domestic automotive production drive significant demand for advanced audio systems. Wireless audio systems must adhere to specific GB standards for radio frequency devices, influencing product design. The Yangtze River Delta, a major automotive manufacturing hub, sees intense activity in speaker component sourcing and assembly for both local and international brands.
Germany
Germany's strong luxury automotive segment and its focus on high-performance vehicles fuel demand for sophisticated, multi-speaker audio systems. Manufacturers operating here must strictly comply with the European Union's RoHS directive, impacting material selection for speaker components. Bavaria, home to several premium automakers, serves as a critical center for acoustic engineering and OEM integration for advanced cabin sound solutions.
United States
Consumer preferences for premium audio upgrades and the integration of ADAS features are shaping demand in the United States. Wireless audio systems must navigate FCC Part 15 regulations for radio frequency devices, ensuring compliance for market entry. Detroit, a historic automotive center, remains a focal point for OEM partnerships and the development of next-generation in-car infotainment and audio platforms.
India
India's expanding middle class and a large fleet of used cars create substantial aftermarket opportunities for speaker upgrades. Electronic components, including audio speakers, must meet BIS standards for quality and safety to access the market. Chennai, an emerging automotive manufacturing hub, attracts investment in localized production for both OEM and aftermarket audio solutions.
Global Automotive Audio Speakers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing market structure. The automotive audio speaker market exhibits a tiered competitive landscape, with established players dominating OEM contracts and niche providers serving the aftermarket. Strategic archetypes include integrated premium audio providers, specialized acoustic engineering firms, and high-volume component suppliers. Companies primarily engage in strategic partnerships with automakers and continuous technology innovation to maintain their market positions.
Within the premium OEM segment, Harman International exemplifies deep integration with global automakers, providing comprehensive high-end audio solutions. Bose Corporation represents specialized expertise in acoustic management and active noise cancellation technologies, differentiating its unique cabin sound offerings. Pioneer Corporation, a Japan-based electronics company, anchors the global aftermarket channel, providing a diverse array of speaker types for custom installations and upgrades. These entities collectively highlight the distinct strategies employed across the automotive audio speaker market's varied channels.
| Leading Market Players |
|---|
| Pioneer Corporation |
| Yanfeng Visteon |
| Harman International |
| JL Audio |
| Sony |
| Bose |
| JVCKENWOOD Corporation |
| Blaupunkt |
| Alpine Electronics |
| Others |
Cost & Logistics Intelligence
Captive supply relationships with original equipment manufacturers anchor both the supply position and the pricing power for automotive audio speaker providers. These long-term contracts ensure volume stability but introduce design cycle complexities and cost pressures.
Pricing Analysis
Direct-to-OEM discount structures dominate the high-volume procurement channel, reflecting the significant scale of vehicle production. Price differentiation stems from the quality grade of components, such as neodymium magnets, and the brand premium associated with specialized acoustic engineering firms. Pricing softness stems from intense competition among Tier 1 suppliers for OEM contracts, especially in mainstream vehicle segments. Aftermarket enthusiasts, prioritizing superior performance and customization, exhibit lower price sensitivity compared to volume-driven OEMs.
Supply Chain Analysis
Domestic-content mandates in regions like China and the United States are reshaping sourcing strategies for automotive audio speakers. Supply concentration centers on China for manufacturing and assembly, with Germany providing acoustic engineering expertise and the United States facilitating OEM partnerships. The supply chain relies heavily on rare earth elements like neodymium and dysprosium, as well as polypropylene for speaker cones. Commodity price volatility for rare earths represents a significant structural risk. Distribution runs through direct channels to OEMs and specialized aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the European Union's RoHS directive consistently driving demand for compliant material innovations across the industry.
For Market Incumbents: To counter technological obsolescence from rapid consumer electronics trends, incumbent firms must deepen investment in advanced digital signal processing (DSP) algorithms for immersive audio experiences. Securing long-term OEM contracts with electric vehicle manufacturers also stabilizes revenue streams. Prioritize R&D into lightweight materials and active noise cancellation to maintain a competitive edge in premium segments.
For New Entrants and Emerging Players: Begin with targeting the "OEM-plus" upgrade segment in North America, offering model-specific kits for easy installation. Focus on developing specialized audio solutions for Advanced Driver-Assistance Systems (ADAS) to create new functional applications for cabin audio. Leverage digital platforms and e-commerce channels for direct-to-consumer sales in developing economies like India.
For Investors and Strategic Acquirers: Roll-up economics work for specialized acoustic technology firms because structural fragmentation exists in high-margin software and component niches. The long-term viability of the market is anchored by the premiumization trend across all vehicle segments. Acquire firms with proprietary DSP software or unique active noise cancellation expertise. A small set of named triggers warrants ongoing watch, particularly increased OEM investment in software-defined vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Immersive Audio Software | This enhances user experience and creates high-margin licensing opportunities beyond hardware for Harman International. |
| Expand Aftermarket Presence in India | This captures growth from a rising middle class and expanding used car fleet for Pioneer Corporation. |
| Develop ADAS-Integrated Audio Systems | This creates new safety-critical applications for in-cabin speakers, differentiating Bose Corporation. |
| Secure Long-Term Neodymium Supply Contracts | This mitigates input cost volatility for all high-performance speaker manufacturers. |
| Standardize Wireless Audio Compliance | This streamlines market access and reduces development costs across diverse regulatory environments. |
Research Approach
Coverage spans China, Germany, United States, and India, with primary inputs from each region informing market dynamics. The methodology combined in-depth primary interviews with OEM procurement managers, aftermarket distributors, acoustic engineers, and material suppliers. Secondary validation drew from vehicle production databases, IHS Markit registration data, and regulatory filings including FCC, RoHS, and GB standards. This approach ensured robust bottom-up and top-down triangulation.
The granularity of the analysis modeled speaker type, technology, installation type, and end-user segments, alongside vehicle class and content per vehicle, across the analysis window. Compound annual growth rates (CAGRs) were derived from historical data analysis and future trend projections. Key industry-specific forecast inputs included electric vehicle adoption rates and consumer premiumization trends for in-cabin audio.
Caveats apply where rare earth element supply disruptions or rapid shifts in consumer electronics integration could materially shift the outlook. Forecasts reflect assumptions documented through extensive research and validation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market