
 North America Automotive Steering Sensor Market | 2026-2036
North America Automotive Steering Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Steering Sensor Market Analytics
ASIL-D functional safety compliance is unwinding across the North America Automotive Steering Sensor Market as automakers raise reliability thresholds for steer-by-wire architectures. Robert Bosch GmbH leverages its integrated semiconductor-to-module pipeline to capture premium calibration contracts with Detroit-based OEMs. Continental AG anchors its position through captive MEMS foundry partnerships that reduce lead times for torque sensor substrates. Sensata Technologies differentiates via Hall-effect arrays optimized for electromagnetic interference rejection in electric power steering racks.
Automotive steering sensors are electromechanical transducers that convert mechanical steering column rotation, torsion, or angular position into electrical signals with resolution thresholds typically below 0.1 degrees for closed-loop chassis control. These devices enable real-time feedback to electronic control units governing lane-keeping torque overlay, variable assist mapping, and automated parking trajectory execution. Torque sensors command the dominant share of value given their load-cell complexity and safety-critical fault-tolerance requirements, while Hall-effect variants represent the fastest-expanding product category as contactless architectures displace potentiometric designs in high-cycle steering applications. End-user concentration tilts toward Tier-1 suppliers who bundle sensor modules with rack-and-pinion assemblies, though OEM direct sourcing is gaining traction as vehicle assemblers internalize steering system integration.
NHTSA Federal Motor Vehicle Safety Standards and EPA fuel economy compliance pathways jointly shape sensor specification baselines by mandating precision thresholds for automated steering intervention and weight reduction through electromechanical replacement of hydraulic assist. ISO 26262 functional safety ratings and SAE J3016 automation taxonomy further stratify supplier qualification barriers, particularly for Level-2-plus and Level-3 highway pilot systems. Stakeholders must monitor NHTSA rulemaking on steering system fail-operational requirements, as pending definitions of minimum sensor redundancy will determine which electromechanical architectures qualify for production volume beyond current ADAS penetration curves.
Market Dynamics
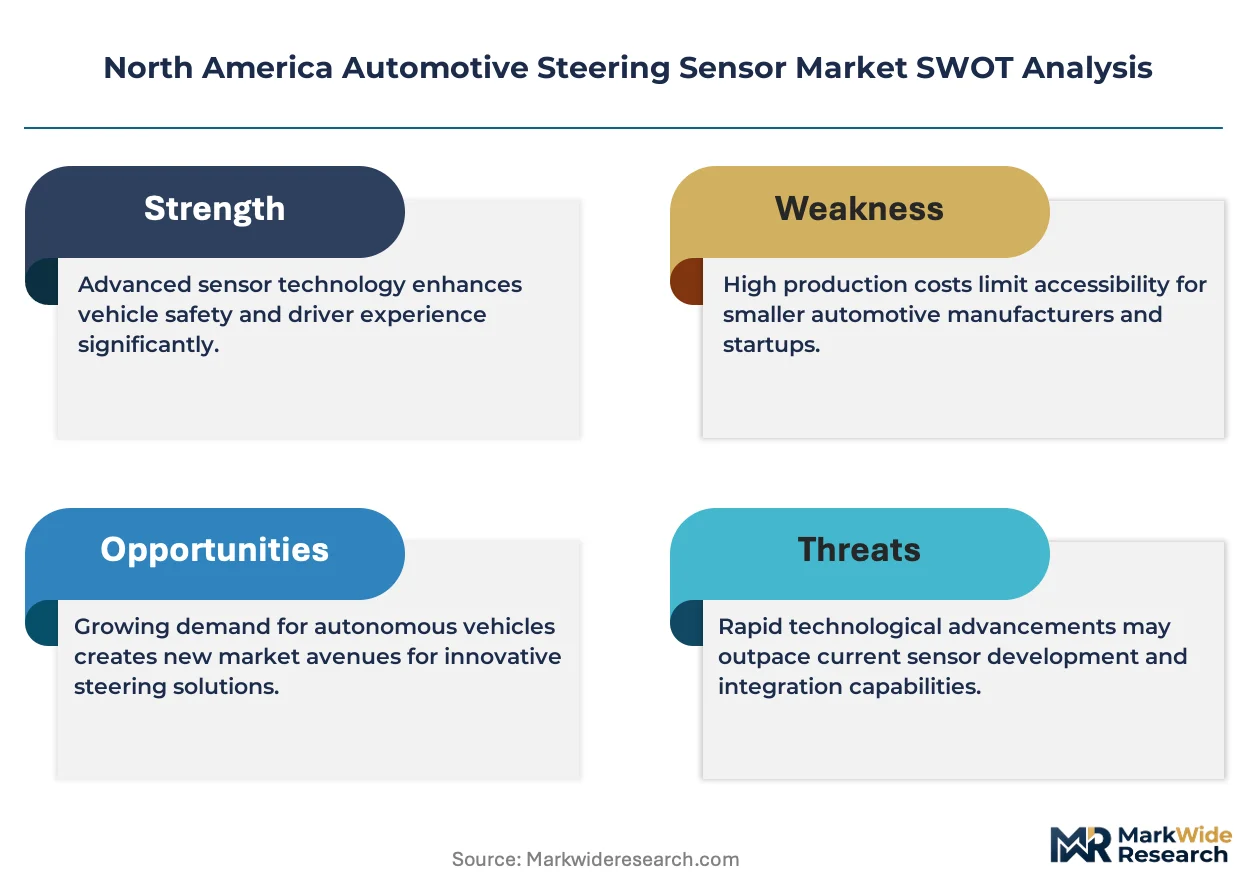
Steer-by-wire migration is compressing supplier margins as automakers internalize steering system integration and demand module-level calibration guarantees from fewer qualified vendors.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandates:Federal performance standards for pedestrian detection and collision avoidance require sub-degree steering angle resolution, expanding sensor deployment across light-duty vehicle platforms.
- Electric Power Steering Rack Electrification:Torque sensor demand concentrates in Michigan and Ontario assembly corridors where Tier-1 suppliers bundle Hall-effect arrays with rack-and-pinion modules.
- Lane-Keeping Performance Thresholds:Calibration requirements for highway pilot systems are tightening specification bands for electromagnetic interference rejection in steering columns.
Market Restraints
- MEMS Substrate Supply Concentration:Captive foundry partnerships in Texas and Arizona create single-source vulnerability for torque sensor die production during capacity constraints.
- ASIL-D Certification Timeline Compression:ISO 26262 functional safety validation cycles extend 18-24 months, freezing architecture decisions for Level-2-plus programs.
- Potentiometer Replacement Cost Parity:Legacy contact-based designs retain cost advantage in economy vehicle segments, delaying contactless Hall-effect penetration in price-sensitive trims.
Strategic Opportunities
- Texas Corridor Expansion:Emerging vehicle assembly capacity near Austin and San Antonio is attracting sensor module engineering centers outside traditional Michigan-Ontario clusters.
- Sensor Fusion Convergence:Integration of steering angle data with lidar and camera inputs for automated parking trajectory execution opens new specification tiers.
- IRA Clean Vehicle Tax Credits:Domestic content requirements for battery electric vehicle incentives are steering procurement toward North American-qualified sensor substrates.
Industry Challenges
- Functional Safety Engineer Scarcity:ASIL-D certified firmware developers command premium compensation in Detroit and Toronto, constraining Tier-1 R&D scaling.
- Legacy Hydraulic Assist Integration:Full-size truck platforms retain electrohydraulic architectures, forcing dual-source sensor qualification across incompatible electromechanical interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Steering Sensor Market |
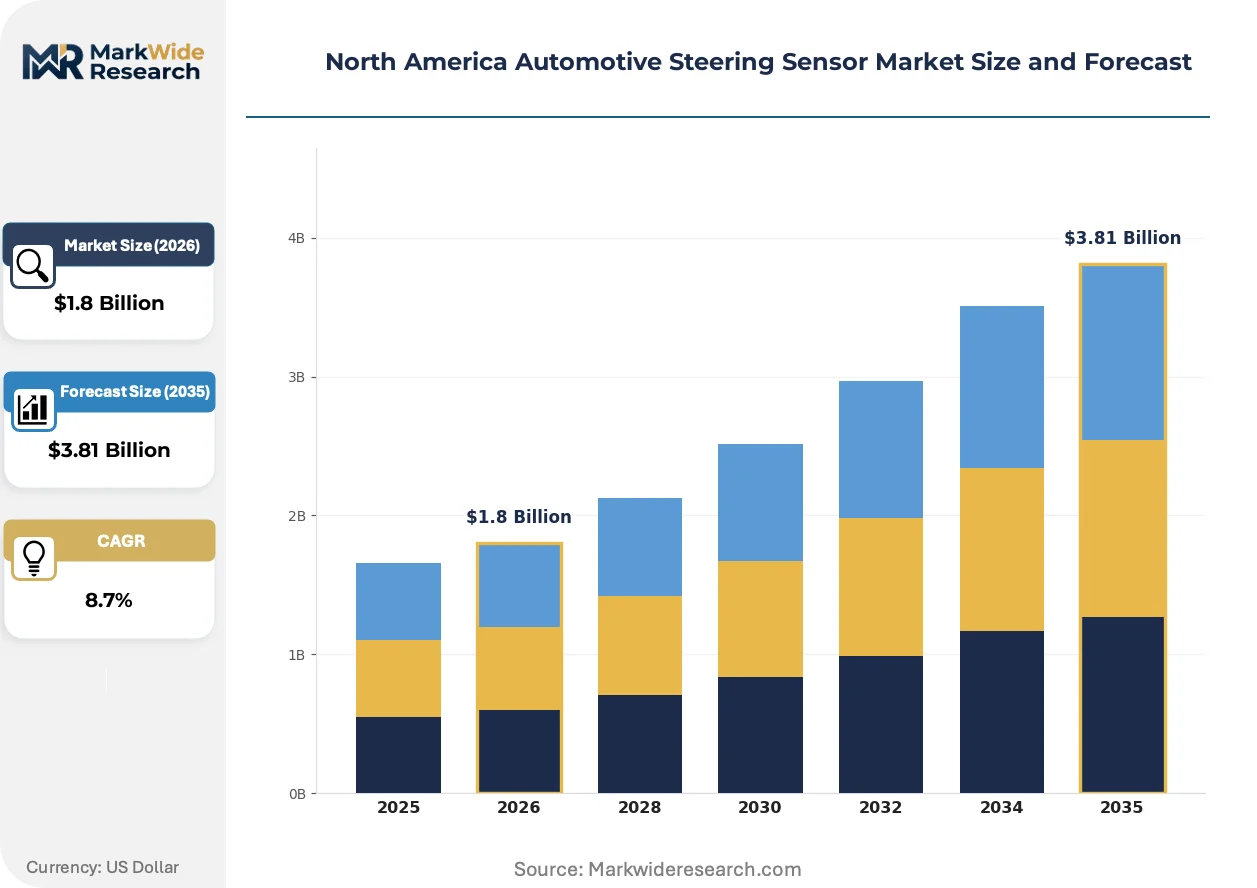
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angle Sensors, Torque Sensors, Position Sensors, Hall Effect Sensors Application: Active Steering, Lane Keeping Assist, Collision Avoidance, Adaptive Cruise Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: OEM Technology, Electromechanical Systems, MEMS Technology, Analog Systems |
| Companies Covered | Valeo SA, Delphi Automotive, Robert Bosch GmbH, CTS Corporation, Infineon Technologies AG, Continental AG, HELLA GmbH & Co. KgaA, Sensata Technologies, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Steering Sensor Market Evolving Landscape
Steering sensor architectures are fragmenting as automakers diverge on redundancy philosophies for fail-operational steer-by-wire systems, splitting the supplier base between integrated module vendors and component specialists.
Hall-effect magnetic position sensing is decomposing traditional potentiometric architectures in high-cycle steering applications. Tier-1 rack suppliers in Ontario are adopting contactless arrays for torque and angle measurement in electromechanical power steering systems. This shift is compressing maintenance intervals and enabling sealed housing designs that resist contamination in severe-service environments.
NHTSA rulemaking on steering system fail-operational requirements is tightening redundancy definitions for Level-3 highway pilot systems. Pending Federal Motor Vehicle Safety Standards will mandate dual-sensor architectures with dissimilar measurement principles, forcing redesigns of single-chip torque modules. Premium electric vehicle programs in California and Michigan are pre-emptively qualifying triple-redundant steering angle sensors to secure homologation headroom.
Direct OEM procurement of steering sensors is fragmenting traditional Tier-1 bundling relationships. Vehicle assemblers in Detroit and Austin are establishing captive calibration laboratories to internalize steering system integration and reduce rack supplier markups. This pattern is most visible in battery electric vehicle platforms where steer-by-wire architectures decouple mechanical steering columns from rack actuators.
North America Automotive Steering Sensor Market Segmentation
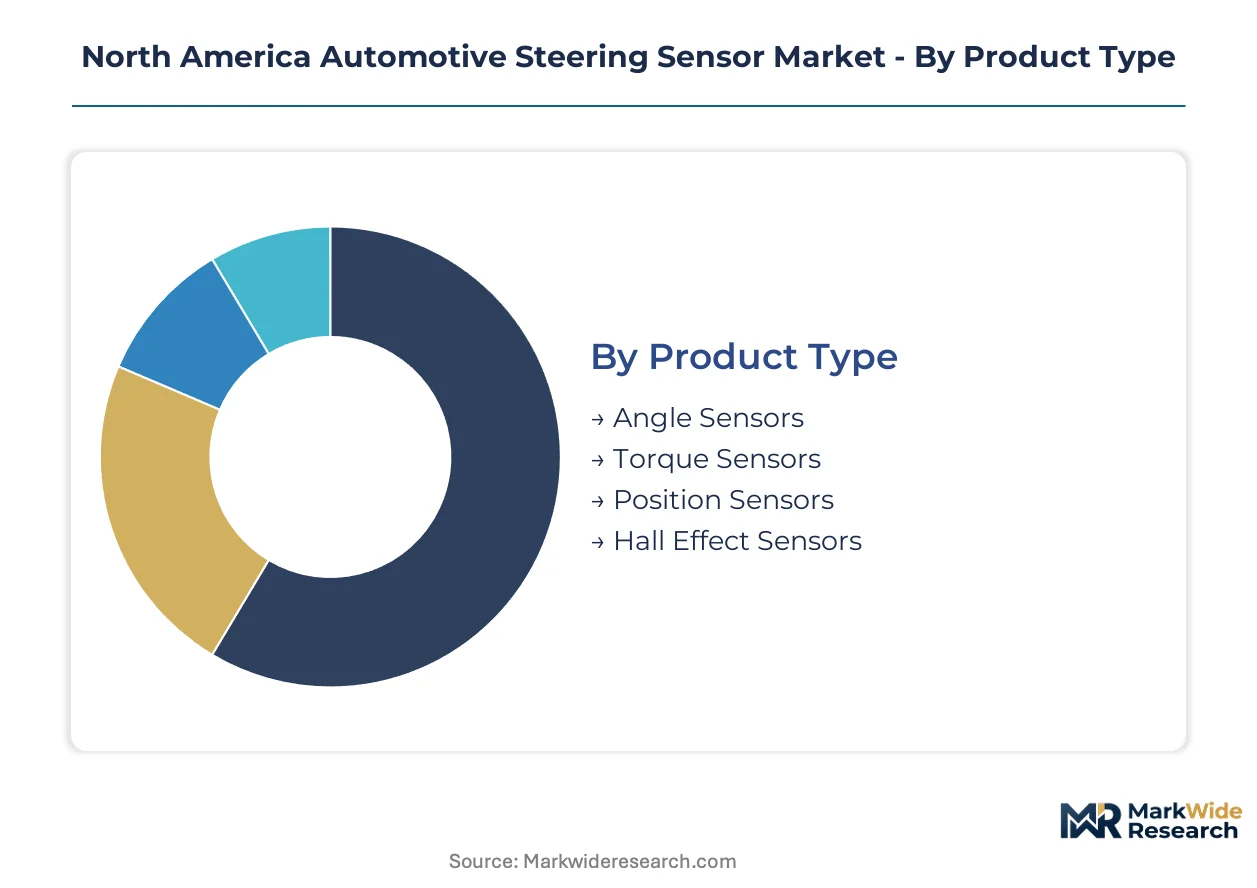
Segmentation in the North America Automotive Steering Sensor Market reveals how NHTSA compliance pathways and Tier-1 supplier bundling practices concentrate procurement across distinct technical tiers. Each dimension exposes divergent margin structures and qualification barriers that reshape competitive positioning across Michigan, Ontario, and Texas corridors.
Product Type:
Torque and angle sensors flow predominantly to domestic OEM assembly plants in Michigan and Ontario, while Hall-effect variants serve export-oriented Tier-1 module production from Texas engineering centers.
- Angle Sensors:Electromechanical transducers measuring steering column rotation with sub-0.1-degree resolution for closed-loop chassis control. Demand clusters in Detroit-based OEM captive calibration laboratories as steer-by-wire architectures decouple mechanical columns from rack actuators.
- Torque Sensors:Load-cell devices converting torsional strain into electrical signals with ASIL-D fault-tolerance requirements. Michigan and Ontario assembly corridors dominate procurement where Tier-1 suppliers bundle these with rack-and-pinion modules for electric power steering.
- Position Sensors:Contactless magnetic arrays tracking absolute angular displacement in steering columns.
- Hall Effect Sensors:Solid-state magnetic sensing elements displacing potentiometric designs in high-cycle applications.
Torque sensors command the established base. The steepest expansion runs through Hall-effect variants.
Application:
Cost tier stratification separates premium highway pilot systems from economy-grade collision avoidance, with specification bands widening as NHTSA mandates tighten.
- Active Steering:Real-time torque overlay systems enabling variable steering ratios and automated trajectory correction. California and Michigan premium electric vehicle programs pre-emptively qualify triple-redundant architectures to secure homologation headroom beyond pending Federal Motor Vehicle Safety Standards.
- Lane Keeping Assist:Closed-loop lateral control requiring electromagnetic interference rejection in steering columns. Ontario Tier-1 engineering centers concentrate development as NHTSA performance thresholds tighten calibration requirements.
- Collision Avoidance:Automatic emergency braking integration demanding sub-degree steering angle resolution for pedestrian detection compliance.
- Adaptive Cruise Control:Longitudinal speed management with steering coordination for highway pilot systems.
Lane keeping assist anchors current volume. Active steering climbs the fastest as steer-by-wire penetration deepens.
End User:
Customer type fragmentation accelerates as OEMs internalize integration and Tier-1 suppliers defend module-level bundling relationships.
- OEMs:Vehicle assemblers establishing captive calibration laboratories to reduce rack supplier markups. Detroit and Austin battery electric vehicle platforms lead direct sensor procurement as steer-by-wire decouples mechanical steering columns from actuators.
- Tier-1 Suppliers:Rack-and-pinion integrators bundling sensor modules with electromechanical power steering systems. Michigan and Ontario corridors retain concentration despite OEM sourcing fragmentation.
- Aftermarket Providers:Replacement sensor distributors serving legacy hydraulic assist retrofits and collision repair channels.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders sourcing calibrated sensor subsystems.
Tier-1 suppliers retain the established base. OEM direct procurement gains share fastest.
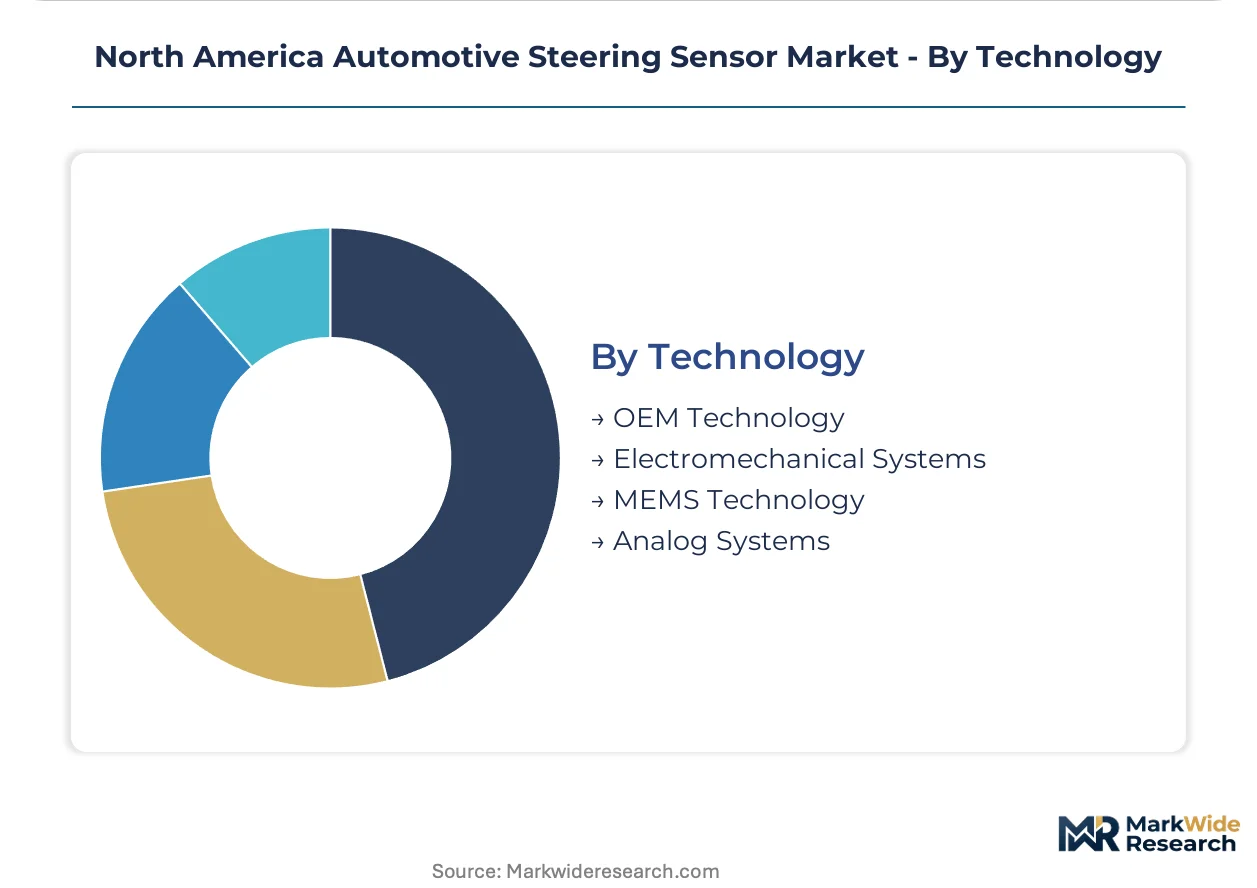
Technology:
Maturity gradients separate qualified ASIL-D architectures from legacy analog systems, with MEMS substrate availability constraining expansion timelines.
- OEM Technology:Proprietary sensor fusion algorithms and calibration protocols internalized by vehicle assemblers. Detroit-based engineering centers develop steer-by-wire redundancy philosophies that fragment supplier qualification requirements.
- Electromechanical Systems:Integrated torque and angle measurement modules replacing hydraulic assist architectures. Texas and Arizona foundry partnerships supply Hall-effect substrates with reduced lead times for contactless designs.
- MEMS Technology:Microelectromechanical strain gauges and accelerometers for high-precision torque measurement.
- Analog Systems:Legacy potentiometric and resistive sensing elements retaining cost advantage in economy trims.
Electromechanical systems anchor production volume. OEM technology expands most quickly as assemblers capture integration margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive steering sensors favor North American production, with Michigan-Ontario corridor assembly plants supplying Tier-1 rack integrators while Texas engineering centers feed Hall-effect substrate demand. Regional trade flows concentrate sensor module shipments across the US-Mexico-Canada Agreement framework, reducing tariff exposure for electromechanical power steering components.
United States
Detroit-based OEMs operate captive calibration laboratories for steer-by-wire architectures, internalizing steering system integration previously outsourced to rack suppliers. NHTSA Federal Motor Vehicle Safety Standards mandate sub-degree angle resolution for automatic emergency braking compliance, tightening specification bands for Michigan assembly corridors. Texas foundry partnerships in Austin and San Antonio reduce lead times for torque sensor die production serving electric power steering rack electrification.
Canada
Ontario Tier-1 engineering centers bundle Hall-effect sensor arrays with rack-and-pinion modules for export to US vehicle assembly plants. The country's national automotive regulator aligns with NHTSA performance thresholds for lane-keeping assist systems, synchronizing cross-border homologation requirements. Windsor-Toronto corridor concentrations of electromechanical power steering integrators are expanding capacity to capture IRA Clean Vehicle Tax Credit procurement shifts.
Mexico
Vehicle assembly capacity in Nuevo León and the Bajío Region attracts sensor module sourcing for export-oriented production serving US market demand. The country's automotive manufacturing incentive programs accelerate Tier-1 supplier co-location with OEM final assembly plants. Querétaro and Aguascalientes industrial clusters are developing torque sensor substrate packaging capabilities to reduce cross-border component transit times.
North America Automotive Steering Sensor Market Competitive Landscape
Listed leaders compete with private specialists across functional safety certification tiers, creating a bifurcated supplier base where ASIL-D qualified vendors capture premium calibration contracts while legacy analog specialists retain economy trim positions. Market structure tilts toward consolidated module integration at the top, with fragmentation persisting in component substrate supply. Two strategic archetypes dominate: integrated semiconductor-to-module pipeline operators and captive MEMS foundry partners. Competitive moves center on backward integration into sensor die production and geographic expansion toward Texas corridor vehicle assembly capacity.
Within the integrated pipeline tier, Robert Bosch GmbH and Continental AG exemplify archetypes of captive manufacturing control. Sensata Technologies occupies a position among Hall-effect specialists optimized for electromagnetic interference rejection. These three anchors represent divergent redundancy philosophies for fail-operational steer-by-wire systems, with each sitting within distinct qualification tiers for Level-2-plus and Level-3 highway pilot programs.
| Leading Market Players |
|---|
| Valeo SA |
| Delphi Automotive |
| Robert Bosch GmbH |
| CTS Corporation |
| Infineon Technologies AG |
| Continental AG |
| HELLA GmbH & Co. KgaA |
| Sensata Technologies |
| DENSO Corporation |
| Others |
Value Network & Pricing Analysis
Hall-effect magnetic arrays displacing potentiometric designs in high-cycle steering applications simultaneously concentrates procurement leverage in Texas-Ontario corridors and compresses module-level margins as contactless architectures standardize. Tier-1 suppliers face pricing pressure from OEM captive calibration laboratories while MEMS substrate scarcity in Arizona and Texas foundries constrains volume flexibility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across ASIL-D certification tiers, volume scale commitments, and after-sales calibration service bundling. Price differentiation separates fault-tolerant torque modules for highway pilot systems from economy-grade angle sensors in collision avoidance trims. Cost compression in Hall-effect arrays is intensifying because captive foundry partnerships reduce substrate sourcing flexibility. Economy vehicle assemblers exhibit highest price sensitivity, while premium electric vehicle programs prioritize certification grade over unit cost.
Supply Chain Analysis
Inbound logistics costs through Laredo and Detroit-Windsor corridors constrain just-in-time delivery windows for torque sensor die shipments from Texas and Arizona foundries. The supply chain draws from Taiwan for semiconductor lithography equipment, Germany for precision strain gauge alloys, and Mexico for electromechanical assembly labor. Single-source vulnerability in MEMS substrate production creates qualification bottlenecks during capacity constraints. Distribution runs through Tier-1 rack integrator hubs in Michigan and Ontario before final vehicle assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steer-by-wire platform economics are fragmenting traditional bundling relationships as OEMs internalize sensor fusion algorithms and calibration protocols, creating interoperability requirements that favor modular component suppliers over integrated rack vendors.
For Market Incumbents: Compound backward integration into Hall-effect substrate production to defend margin position against OEM direct procurement trends. Secure captive foundry partnerships in Texas corridors to reduce lead time exposure during MEMS capacity constraints. Prioritize ASIL-D certification investment for triple-redundant architectures ahead of pending NHTSA fail-operational rulemaking. For New Entrants and Emerging Players: ISO 26262 functional safety fast-track programs offer entry pathways into aftermarket collision repair channels where legacy potentiometer replacement demand persists. Target economy vehicle trims in Mexico's Bajío Region assembly clusters where cost parity favors contact-based designs. Pursue white-label sensor module partnerships with emerging steer-by-wire platform developers in Austin engineering centers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Tier-1 suppliers holding stranded hydraulic assist integration capabilities as electric power steering penetration deepens. Five-to-ten year viability hinges on steer-by-wire homologation headroom and NHTSA redundancy mandate timing. Monitor NHTSA Federal Motor Vehicle Safety Standards rulemaking publication as inflection signal for dual-sensor architecture qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Fast-Track | Accelerates qualification for Level-3 highway pilot programs ahead of NHTSA rulemaking. |
| Texas Corridor Manufacturing Footprint | Captures IRA Clean Vehicle Tax Credit procurement shifts toward domestic sensor substrates. |
| Hall-Effect Substrate Backward Integration | Reduces single-source vulnerability in MEMS foundry partnerships during capacity constraints. |
| Sensor Fusion Algorithm Development | Enables direct OEM procurement relationships as steer-by-wire decouples mechanical columns. |
| Triple-Redundant Architecture Pre-Qualification | Secures homologation headroom for premium electric vehicle programs in California and Michigan. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and MEMS foundry operations managers; and secondary validation against NHTSA Federal Motor Vehicle Safety Standards dockets, vehicle production databases, IHS Markit registration data, and SEC filings from listed sensor component suppliers. Bottom-up volume modeling triangulated with top-down market sizing across the value chain.
Across the analysis window, forecasts employed segmented modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from production volume trajectories, ADAS penetration curves, and NHTSA mandate compliance timelines. Industry-specific inputs included steer-by-wire platform deployment schedules and ASIL-D certification pipeline visibility.
Underlying assumptions cover NHTSA rulemaking finalization timelines, MEMS foundry capacity expansion plans, and IRA domestic content interpretation stability, with deviation risk concentrated in pending fail-operational redundancy definitions and functional safety engineer labor market tightness. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Smart Key Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market