
 Park Assist System Market | 2026-2036
Park Assist System Market Size, Share, and Industry Trends Forecast 2026-2036
Park Assist System Market Outlook
Software-defined parking feature subscriptions is hardening into a recurring revenue layer alongside hardware sales. Robert Bosch GmbH leverages its sensor fusion portfolio to anchor integrated park assist bundles across European OEM platforms. Continental AG sustains R&D intensity in ultrasonic and camera fusion algorithms for automated parking execution. Valeo SA specializes in scalable proximity detection modules that occupy the mid-tier vehicle segment.
Park assist systems combine ultrasonic sensors, cameras, radar modules, and LiDAR units with embedded processing to detect obstacles, measure parking space dimensions, and execute steering maneuvers with minimal driver intervention; ultrasonic sensors dominate unit volume due to cost efficiency, while camera and radar fusion commands premium positioning in automated parking configurations. Vision-based systems and smart parking technologies represent the fastest-expanding technology categories as OEMs integrate valet parking and infrastructure-linked navigation. Passenger cars and commercial vehicles constitute the primary end user segments, with fleet management emerging as a distinct demand pool for multi-vehicle parking optimization.
NHTSA in the United States, ECE regulations under UN R79 in Europe, and Japan's Ministry of Land, Infrastructure, Transport and Tourism shape mandatory performance benchmarks for automatic steering and parking assistance systems. These frameworks elevate baseline sensor accuracy requirements and validate functional safety protocols under ISO 26262. Stakeholders must monitor regulatory divergence between camera-centric and sensor-fusion compliance pathways as software update architectures redefine certification obligations.
Market Dynamics
Software-defined vehicle architectures are compressing hardware margins while elevating recurring revenue from parking feature subscriptions, forcing suppliers to restructure commercial models around over-the-air activation.
Growth Catalysts
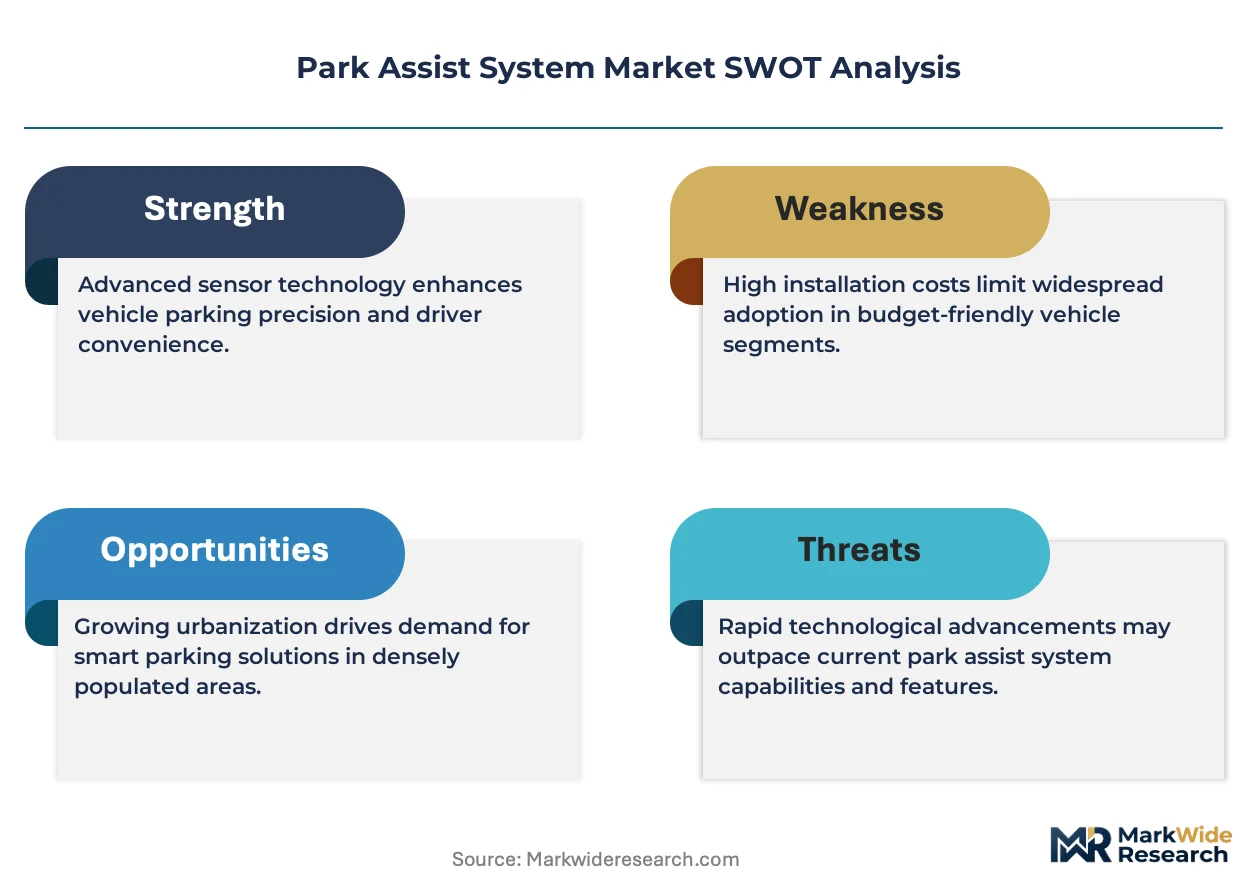
- Euro NCAP safety protocols:The European assessment body's mandatory parking assistance benchmarks compel OEMs to standardize automated parking across vehicle lines, expanding addressable hardware volumes.
- LiDAR fusion modules:Multi-sensor configurations combining ultrasonic, camera, and LiDAR inputs enable valet parking execution in complex urban environments, opening premium pricing tiers.
- Fleet management operators:Multi-vehicle logistics providers in Germany and Japan deploy centralized parking optimization platforms, creating dedicated demand pools beyond retail consumers.
Market Restraints
- Semiconductor supply concentration:Embedded processing chips for sensor fusion concentrate among Taiwan and South Korea foundries, exposing Tier-1 suppliers to allocation volatility.
- UN R79 compliance costs:Europe's steering automation regulations mandate extensive validation protocols that extend development cycles and inflate certification expenditures for automated parking systems.
- Ultrasonic sensor commoditization:Mature proximity detection hardware faces price erosion from Chinese component manufacturers, compressing margins in economy vehicle segments.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Production-linked incentives for advanced driver-assistance system manufacturing attract module assembly investments serving domestic and export demand.
- Smart city infrastructure integration:Vehicle-to-infrastructure communication protocols enable automated parking guidance systems linked to municipal sensor networks in Japanese urban centers.
- Camera-radar convergence:Fused perception stacks reduce sensor count while maintaining redundancy, creating cost-optimized pathways for mid-tier passenger car penetration.
Industry Challenges
- ISO 26262 functional safety certification:ASIL-D validation for automated steering execution demands specialized systems engineering talent that concentrates among German and Japanese suppliers.
- Legacy platform integration:Retrofitting software-defined parking architectures onto existing vehicle electrical architectures requires extensive gateway and domain controller reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Park Assist System Market |
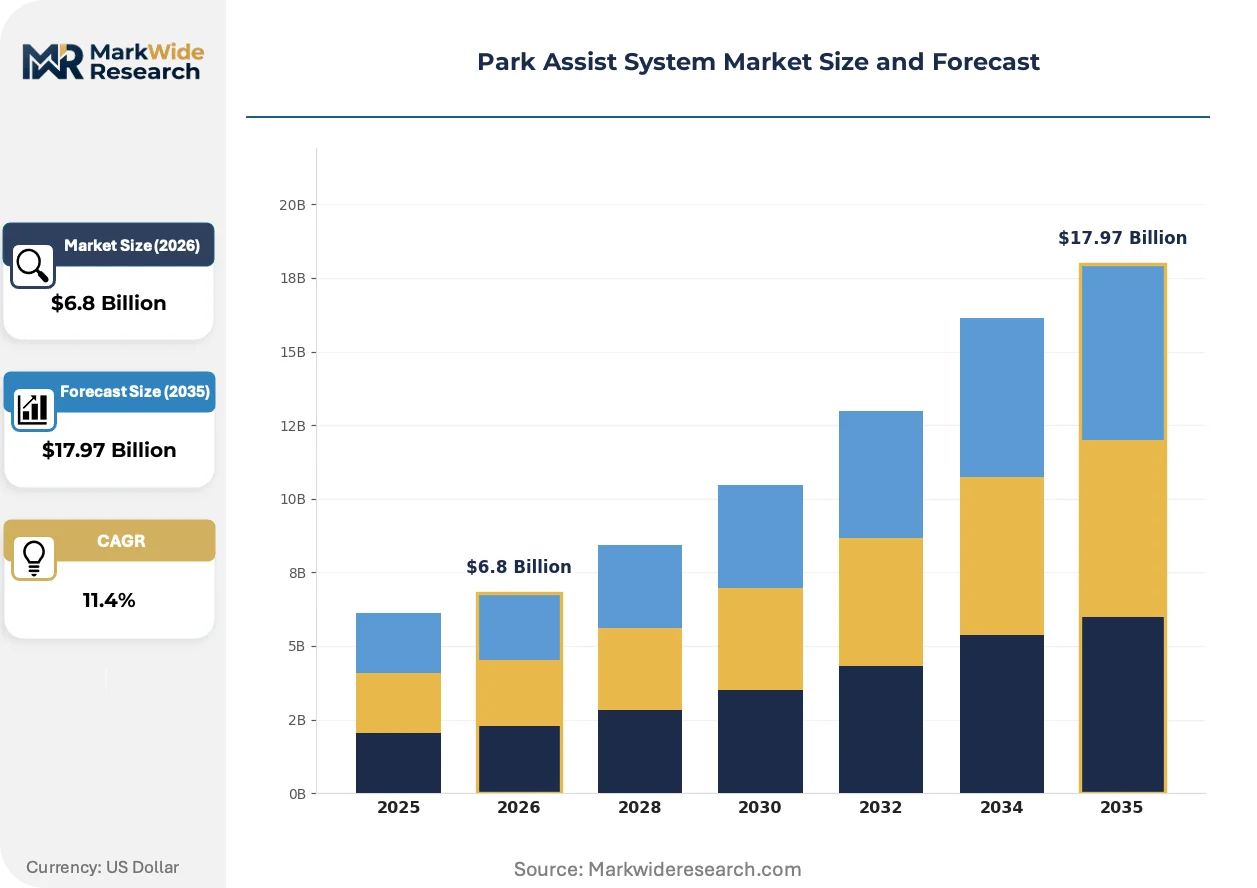
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Cameras, Radar Systems, LiDAR Technology: Automated Parking, Smart Parking, Proximity Detection, Vision-Based Systems End User: Commercial Vehicles, Passenger Cars, Fleet Management, Municipalities Installation: OEM, Aftermarket, Retrofit, Integrated Systems |
| Companies Covered | Robert Bosch GmbH, Continental AG, Valeo SA, ZF Friedrichshafen AG, Aisin Seiki Co., Ltd., Denso Corporation, Magna International, Aptiv, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Park Assist System Market Strategic Shifts
Sensor fusion architectures and over-the-air software distribution are redefining how parking assistance capabilities reach vehicles, shifting value capture from hardware shipment to feature activation.
4D imaging radar is electrifying automated parking perception by delivering dense point clouds that resolve static obstacles and moving pedestrians in shared urban spaces. Premium German OEMs are integrating these modules into their flagship electric vehicle platforms for unsupervised valet parking execution. The technology is electrifying competitive positioning around safety redundancy as LiDAR alternatives face cost and packaging constraints.
NHTSA's pending updates to Federal Motor Vehicle Safety Standards for automatic steering systems are tightening validation requirements for parking maneuver execution in the United States. The regulatory friction is accelerating supplier investment in simulation-based testing protocols to compress homologation timelines. Commercial vehicle segments face the steepest compliance burden as regulators scrutinize automated parking in freight and logistics applications.
Fleet operators are consolidating procurement decisions for parking assistance systems under centralized mobility service contracts rather than individual vehicle specifications. This channel shift compresses supplier margins through volume aggregation while demanding outcome-based performance guarantees for parking efficiency metrics. The transformation is most advanced in Germany where corporate fleet electrification programs bundle automated parking into total cost of ownership calculations.
Park Assist System Market Segmentation
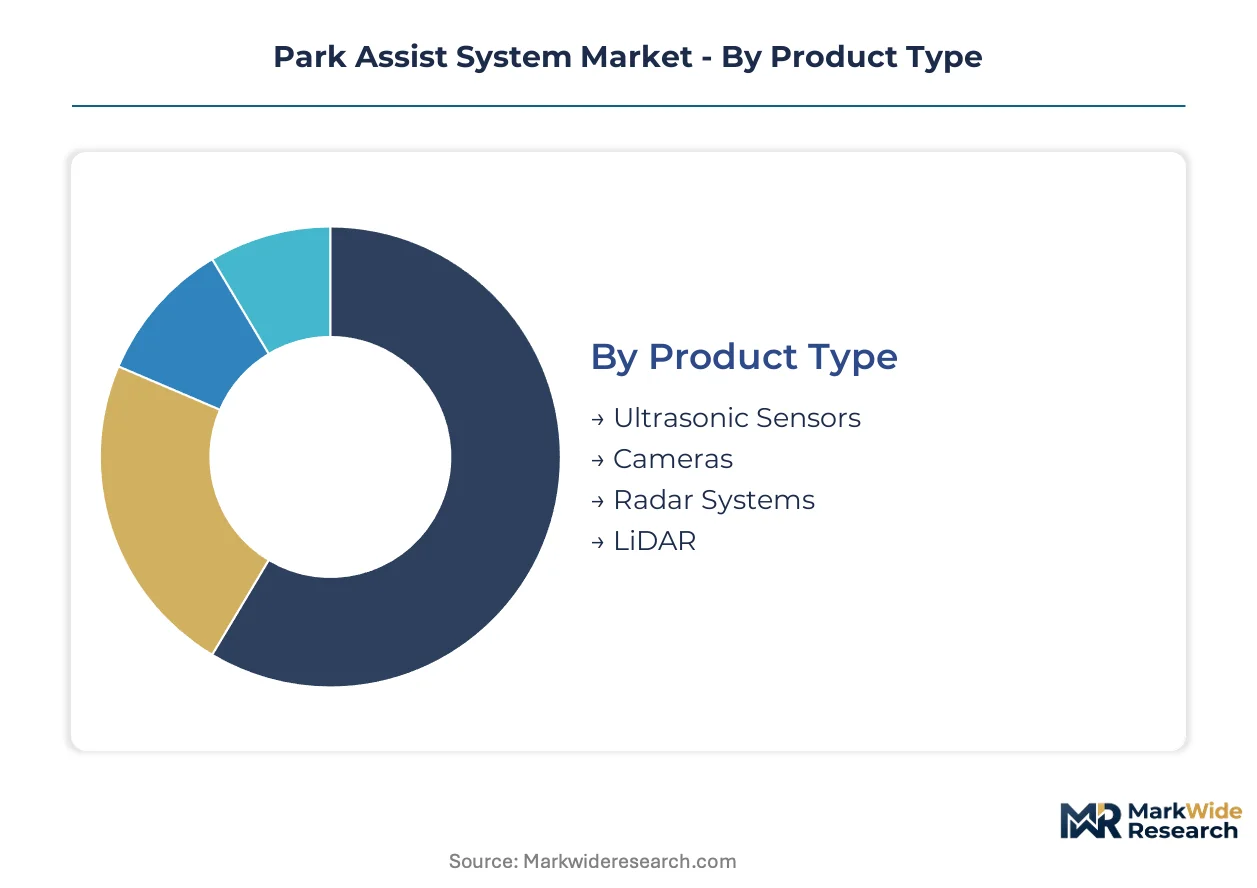
Park assist system segmentation reveals how sensor modality, integration depth, and buyer sophistication fragment revenue pools. Understanding these divides exposes where hardware margins hold versus where software subscriptions capture recurring value.
Product Type:
Cost tier separates buyers in this category, with economy vehicle programs prioritizing unit economics while premium platforms absorb multi-sensor fusion expenses.
- Ultrasonic Sensors:These proximity detection modules emit high-frequency sound waves to measure distance from obstacles, offering mature technology with minimal processing overhead. Demand concentrates in economy and mid-tier passenger cars across Germany and Japan where OEMs face acute price pressure from Chinese component suppliers.
- Cameras:Vision-based modules capture environmental imagery for space recognition and trajectory planning, requiring substantial embedded processing. Adoption is accelerating in United States premium electric vehicle platforms where NHTSA validation protocols favor camera redundancy for automated steering compliance.
- Radar Systems:Millimeter-wave sensors penetrate weather conditions that degrade optical performance, serving commercial vehicle operators in freight applications.
- LiDAR:Time-of-flight laser scanning delivers dense point clouds for valet parking execution in dense urban environments.
Ultrasonic sensors lead volumes today; camera systems are gaining share fastest.
Technology:
Application maturity divides this category, with established proximity functions facing displacement from infrastructure-linked and fully automated alternatives.
- Automated Parking:These systems execute steering, braking, and gear selection without driver intervention, integrating multiple sensor modalities through centralized domain controllers. Deployment concentrates in German premium OEM platforms where Euro NCAP safety ratings mandate standardized capability across vehicle lines.
- Vision-Based Systems:Camera-centric architectures leverage machine learning for space detection and obstacle classification, reducing hardware count. Japanese urban centers are driving fastest expansion as smart city infrastructure enables vehicle-to-environment communication for garage-linked navigation.
- Smart Parking:Infrastructure-integrated platforms connect vehicles to municipal sensor networks for real-time space availability.
- Proximity Detection:Basic distance alerting remains the entry-level configuration for economy vehicle segments.
Proximity detection leads volumes today; vision-based systems are climbing the fastest.
End User:
Customer procurement sophistication fragments this category, with fleet operators aggregating volume decisions differently than individual consumers or municipal agencies.
- Passenger Cars:Retail buyers demand intuitive interfaces and insurance premium reductions, driving standardization of park assist across vehicle trims. Germany, Japan, and the United States concentrate demand where advanced driver-assistance system penetration reaches deepest into mass-market segments.
- Fleet Management:Multi-vehicle operators in Germany bundle automated parking into total cost of ownership calculations for electrification programs, demanding outcome-based efficiency guarantees.
- Commercial Vehicles:Freight and logistics applications face heightened NHTSA scrutiny for automated parking validation.
- Municipalities:Urban authorities in Japanese centers deploy centralized parking optimization for public transit integration.
Passenger cars lead volumes today; fleet management is expanding most quickly.
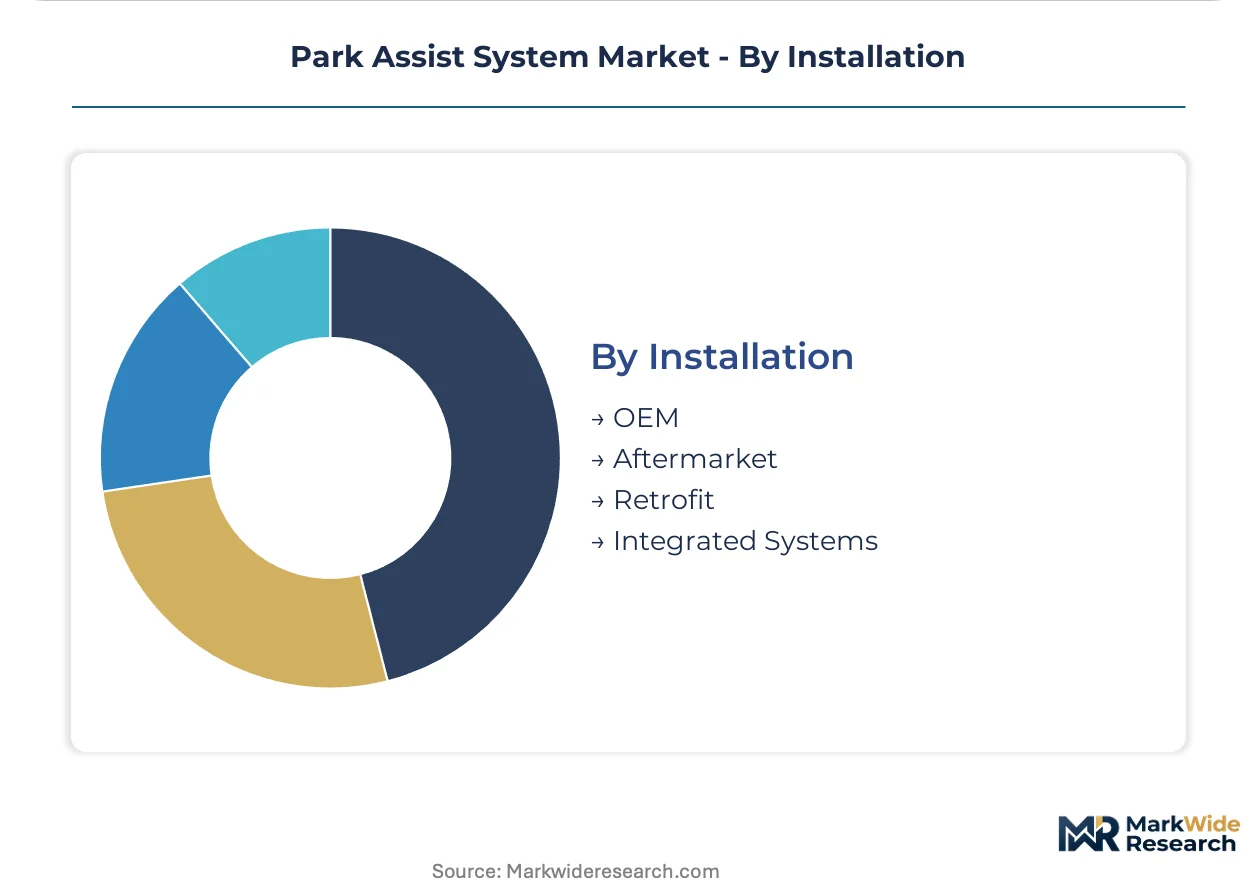
Installation:
Supply chain configuration separates this category, with factory integration offering margin protection against price-transparent aftermarket channels.
- OEM:Factory-installed systems benefit from embedded electrical architecture optimization and warranty integration. Robert Bosch GmbH and Continental AG anchor supply relationships with European OEM platforms, capturing bundled sensor fusion contracts.
- Integrated Systems:Domain controller-based architectures enable over-the-air feature activation, shifting revenue toward software subscriptions. This pathway is advancing fastest in United States electric vehicle programs where software-defined vehicle platforms compress hardware margins.
- Aftermarket:Dealer and third-party installation serves vehicle owners seeking feature upgrades outside factory configurations.
- Retrofit:Legacy platform adaptation demands extensive gateway reconfiguration for older vehicle electrical architectures.
OEM installation leads volumes today; integrated systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are steering module assembly toward jurisdictions with production-linked incentives, as Euro NCAP and NHTSA validation costs compress margins in mature markets. Suppliers are diversifying manufacturing footprints to capture cost-of-compliance advantages while maintaining proximity to premium OEM demand centers.
Germany
Premium passenger car OEMs in Stuttgart and Munich drive sensor fusion demand for automated valet parking execution. KBA homologation protocols under UN R79 mandate extensive steering automation validation that extends development cycles. The Baden-Württemberg industrial corridor anchors Continental AG and Robert Bosch GmbH engineering centers for domain controller integration.
United States
NHTSA's pending Federal Motor Vehicle Safety Standards updates are accelerating simulation-based testing investments for automated steering compliance. Electric vehicle platforms in California and Michigan compress hardware margins while elevating software subscription revenue from over-the-air feature activation. The Detroit-Toledo technology corridor concentrates Tier-1 supplier engineering resources for camera-radar fusion development.
Japan
METI smart city initiatives in Tokyo and Osaka are driving vehicle-to-infrastructure communication protocols for garage-linked navigation systems. Ministry of Land, Infrastructure, Transport and Tourism regulations shape parking assistance performance benchmarks for domestic OEM platforms. The Nagoya industrial cluster hosts Denso Corporation and Aisin Seiki engineering operations for ultrasonic and camera module production.
China
Domestic EV manufacturers in Shanghai and Shenzhen are integrating vision-based parking systems at price points that challenge established sensor fusion architectures. MIIT standards for advanced driver-assistance systems are tightening baseline accuracy requirements for automated parking execution. The Yangtze River Delta manufacturing basin concentrates module assembly capacity serving both domestic consumption and export markets.
India
PLI scheme incentives for automotive electronics manufacturing are attracting module assembly investments from multinational Tier-1 suppliers. BIS certification requirements for advanced driver-assistance system components are establishing domestic quality benchmarks. The Tamil Nadu automotive belt near Chennai is emerging as a production hub for proximity detection modules serving Southeast Asian export demand.
Park Assist System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system suppliers capturing premium pricing through domain controller expertise while component specialists face margin compression in mature sensor categories. The vendor base organizes around three strategic archetypes: diversified automotive conglomerates with full-stack sensor fusion portfolios, semiconductor-focused technology providers supplying embedded processing chips, and regional component specialists serving cost-optimized vehicle segments. Consolidation pressure is intensifying through strategic partnerships for software-defined vehicle architectures and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify full-stack positioning through bundled sensor fusion contracts across European OEM platforms. Valeo SA occupies a position among scalable module specialists serving mid-tier vehicle segments with proximity detection hardware. These three anchors represent contrasting strategic postures: integrated system depth versus component cost leadership versus regional manufacturing scale.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Valeo SA |
| ZF Friedrichshafen AG |
| Aisin Seiki Co., Ltd. |
| Denso Corporation |
| Magna International |
| Aptiv |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot prices cascade through sensor module manufacturing into three-tier pricing structure across premium, standard, and economy levels for park assist systems. Automotive OEM procurement teams in Germany and Japan exploit this concentration to negotiate volume discounts on ultrasonic sensor bundles while absorbing premium markups for LiDAR fusion configurations.
Pricing Analysis
Distributor margins on aftermarket park assist modules compress pricing by 15-25 points below direct OEM contract rates. Three-tier pricing structure across premium, standard, and economy levels separates sensor fusion platforms from camera-only systems from basic ultrasonic configurations. Cost compression in economy vehicle segments is intensifying because Chinese component manufacturers flood proximity detection markets with commoditized hardware. Fleet operators exhibit lowest price sensitivity due to outcome-based efficiency guarantees, while individual aftermarket buyers drive hardest bargain on installation labor.
Supply Chain Analysis
Refurbishment flows for domain controllers and sensor modules remain underdeveloped, creating stranded asset risk as software-defined architectures obsolete hardware generations. Embedded processing chips draw from Taiwan and South Korea foundries, while ultrasonic transducer assemblies source from Chinese and Mexican plants. Single-source vulnerability concentrates in 12-inch wafer fabrication for AI accelerators. Distribution runs through Tier-1 supplier direct channels to OEM assembly plants, bypassing traditional automotive wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Park assist systems constitute a late-cycle quality story as Euro NCAP safety ratings force standardization of automated parking across vehicle lines, elevating specification floors industry-wide.
For Market Incumbents: Anticipate margin compression from software-defined vehicle architectures by anchoring sensor fusion contracts with domain controller integration. Secure backward integration into LiDAR module production to defend against semiconductor supply concentration. Prioritize ISO 26262 ASIL-D certification investment as validation talent concentrates among German and Japanese engineering centers. For New Entrants and Emerging Players: Launch via fleet management service contracts rather than retail aftermarket channels to bypass entrenched OEM supply relationships. Target India's PLI-subsidized manufacturing belt for proximity detection module assembly serving Southeast Asian export demand. Exploit camera-radar convergence as cost-optimized pathway for mid-tier passenger car penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-focused technology providers supplying embedded processing chips for sensor fusion architectures. Long-term viability favors suppliers with software update architectures that redefine certification obligations. Monitor NHTSA Federal Motor Vehicle Safety Standards updates for automated steering validation as inflection indicator for simulation-based testing protocol demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Reduces sensor count while maintaining redundancy for Euro NCAP compliance. |
| LiDAR Supply Agreement | Secures time-of-flight modules for valet parking execution in dense urban environments. |
| Software-Defined Vehicle Investment | Enables over-the-air feature activation shifting revenue from hardware to subscriptions. |
| Geographic Manufacturing Footprint | Captures PLI scheme incentives in India while maintaining proximity to German OEM demand. |
| Smart City Infrastructure Partnership | Links vehicle-to-infrastructure protocols with municipal sensor networks in Japanese urban centers. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads grounded qualitative demand assessment. Secondary validation drew from vehicle production databases, IHS Markit registration data, UN R79 regulatory filings, and Euro NCAP safety protocol documentation. Bottom-up sensor unit shipment estimates triangulated against top-down OEM platform content analysis.
Bottom-up modeling segmented by sensor modality, vehicle class, propulsion architecture, and regional production cluster across the analysis window. CAGRs derived from slope-intercept fitting of historical penetration curves against regulatory mandate timelines. Forecast inputs incorporated OEM electrification program announcements and fleet operator centralization of parking assistance procurement.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor allocation volatility and UN R79 compliance cost inflation. Practitioners should monitor NHTSA automated steering validation updates and MIIT ADAS accuracy standards for early signals of regulatory divergence affecting certification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market