
 Automotive Oxygen Sensor Market | 2026-2036
Automotive Oxygen Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oxygen Sensor Market Analysis
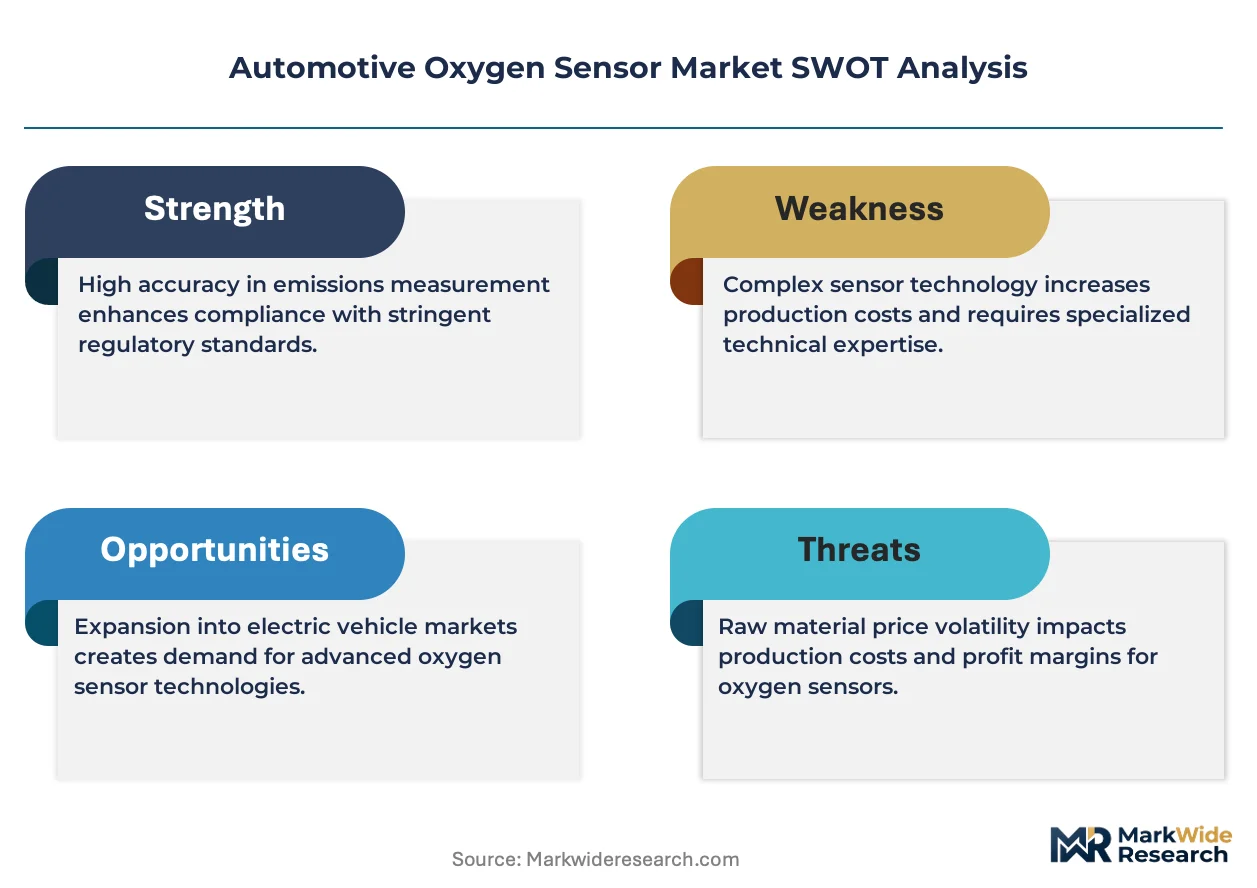
Fleet operators is bifurcating from individual repair shops as the dominant aftermarket buyer archetype for oxygen sensor replacement programs. Robert Bosch GmbH leverages captive semiconductor fabrication to secure zirconia element supply chains. Denso Corporation anchors its position through thermal shock-resistant sensor architectures designed for hybrid powertrains.
An automotive oxygen sensor measures residual oxygen concentration in exhaust gases, typically employing a zirconia ceramic thimble coated with porous platinum electrodes that generate a voltage signal proportional to the air-fuel ratio deviation from stoichiometry. Electrochemical wideband variants dominate OEM fitment for their linear output across lambda 0.7 to 2.0, while narrowband technologies retain aftermarket share due to lower unit cost and diagnostic compatibility with legacy engine control modules. Solid-state optical sensors represent the fastest-growing technology segment as manufacturers seek immunity to exhaust contaminant poisoning. Passenger car applications command the largest value pool, though heavy-duty truck fitment generates premium pricing through extended warranty requirements and severe-duty calibration protocols.
The EPA enforces onboard diagnostic thresholds that mandate oxygen sensor fault detection within two driving cycles, while the EU Green Deal's 55% CO2 reduction target for 2030 compels wider lambda control bandwidth. Euro 7 proposals from EMA would tighten cold-start emission windows, forcing sensor response time improvements below 200 milliseconds. Stakeholders must monitor regulatory divergence between California Air Resources Board waivers and federal harmonization talks, as divergent certification paths threaten platform standardization economics.
Market Dynamics
The automotive oxygen sensor market is undergoing structural recalibration as wideband electrochemical architectures displace narrowband technologies across OEM fitment programs, driven by regulatory mandates for real-time lambda control during cold-start and transient operating conditions.
Growth Catalysts
- Euro 7 Cold-Start Windows:The proposed EMA framework mandates sub-200 millisecond sensor response times, forcing OEMs to upgrade from switching-type to linear-output sensor designs.
- Hybrid Powertrain Thermal Cycling:Stop-start architectures generate repeated thermal shock that accelerates conventional sensor degradation, expanding replacement frequency in the installed base.
- Platinum Group Metal Recovery Economics:Recycler investments in urban mining infrastructure for zirconia thimble reclamation are lowering net material costs for remanufactured sensor programs.
Market Restraints
- Rhodium Price Volatility:Electrode coating costs fluctuate with South African mining output disruptions, compressing margin stability for non-integrated sensor assemblers.
- Legacy ECM Diagnostic Protocols:Narrowband voltage-switching signal formats remain hardcoded into 1996-2010 engine control modules, creating retrofit friction for wideband upgrades.
- Silicon Carbide Controller Concentration:Wideband sensor heater control ASIC fabrication concentrates among three foundry operators, creating single-source vulnerability for thermal management circuits.
Strategic Opportunities
- India BS-VI Stage II Implementation:The country's emission regulator is phasing in real-driving emissions monitoring, creating first-fit demand for wideband sensors in domestic passenger vehicle platforms.
- Solid-State Optical Sensing:Titanium dioxide thin-film platforms eliminate platinum electrode poisoning, enabling deployment in high-sulfur fuel markets where electrochemical sensors degrade prematurely.
- Fleet Telematics Integration:Connected vehicle architectures enable predictive sensor failure algorithms, converting aftermarket replacement from reactive to scheduled maintenance revenue models.
Industry Challenges
- Calibration Engineer Scarcity:Lambda control algorithm development requires rare cross-domain expertise spanning exhaust chemistry, control theory, and embedded systems.
- Homologation Timeline Compression:Divergent EPA and CARB certification paths for OBD-II monitor thresholds force parallel validation programs, duplicating test cell investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oxygen Sensor Market |
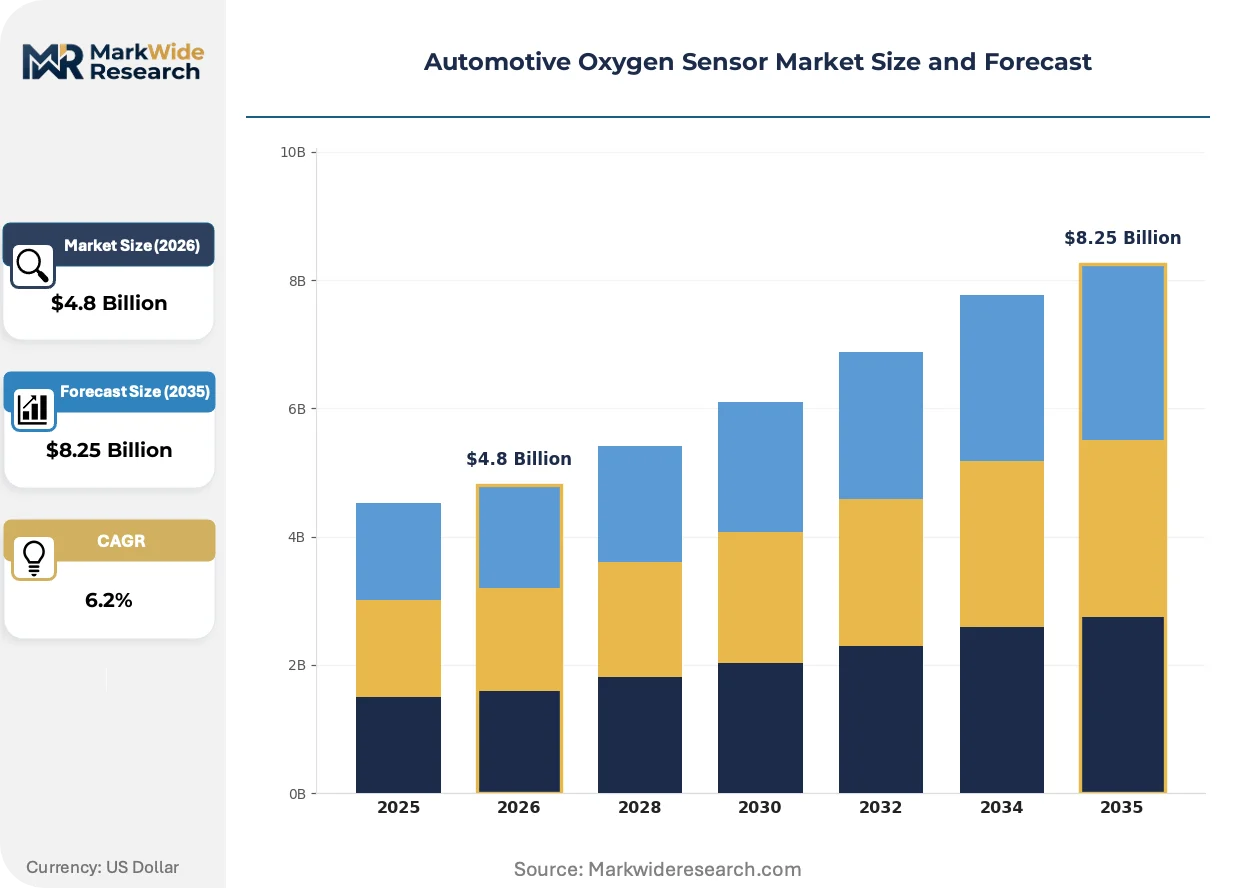
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wideband, Narrowband, Zircconia, Titania Application: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Technology: Electrochemical, Optical, Solid-State, Mass Spectrometry |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, NGK Spark Plug Co., Ltd., HELLA GmbH & Co. KGaA, BorgWarner Inc., Delphi Technologies, Hitachi Astemo, Ltd., Walker Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oxygen Sensor Market Emerging Trajectories
Sensor architecture evolution is compressing form factors while expanding functional bandwidth, as manufacturers reconcile packaging constraints against widening lambda measurement ranges demanded by powertrain electrification.
Planar zirconia element construction is miniaturizing sensor bodies from 18mm to 12mm hexagonal formats without sacrificing heater power density. OEMs are adopting these reduced-profile designs for turbocharger proximity mounting where space constraints previously excluded wideband instrumentation. The dimensional reduction is enabling dual-sensor placement within single exhaust runners, improving cylinder-specific air-fuel ratio resolution for diagnostic granularity.
EPA Tier 3 certification requirements now mandate onboard diagnostic detection of oxygen sensor degradation before emissions exceed 1.5 times the applicable standard. This regulatory compression is forcing suppliers to embed predictive heater resistance monitoring algorithms within sensor control modules. Heavy-duty engine manufacturers in the United States are responding with dual-element redundancy architectures that maintain compliance during single-sensor fault conditions.
Fleet maintenance departments are consolidating sensor procurement through integrated vehicle health management platforms rather than fragmented parts counter transactions. This channel migration is displacing traditional jobber distribution in North American commercial vehicle segments. Telematics-enabled bulk purchasing contracts now govern replacement scheduling for Class 8 truck operators running dedicated routes between California and Texas corridors.
Automotive Oxygen Sensor Market Segmentation
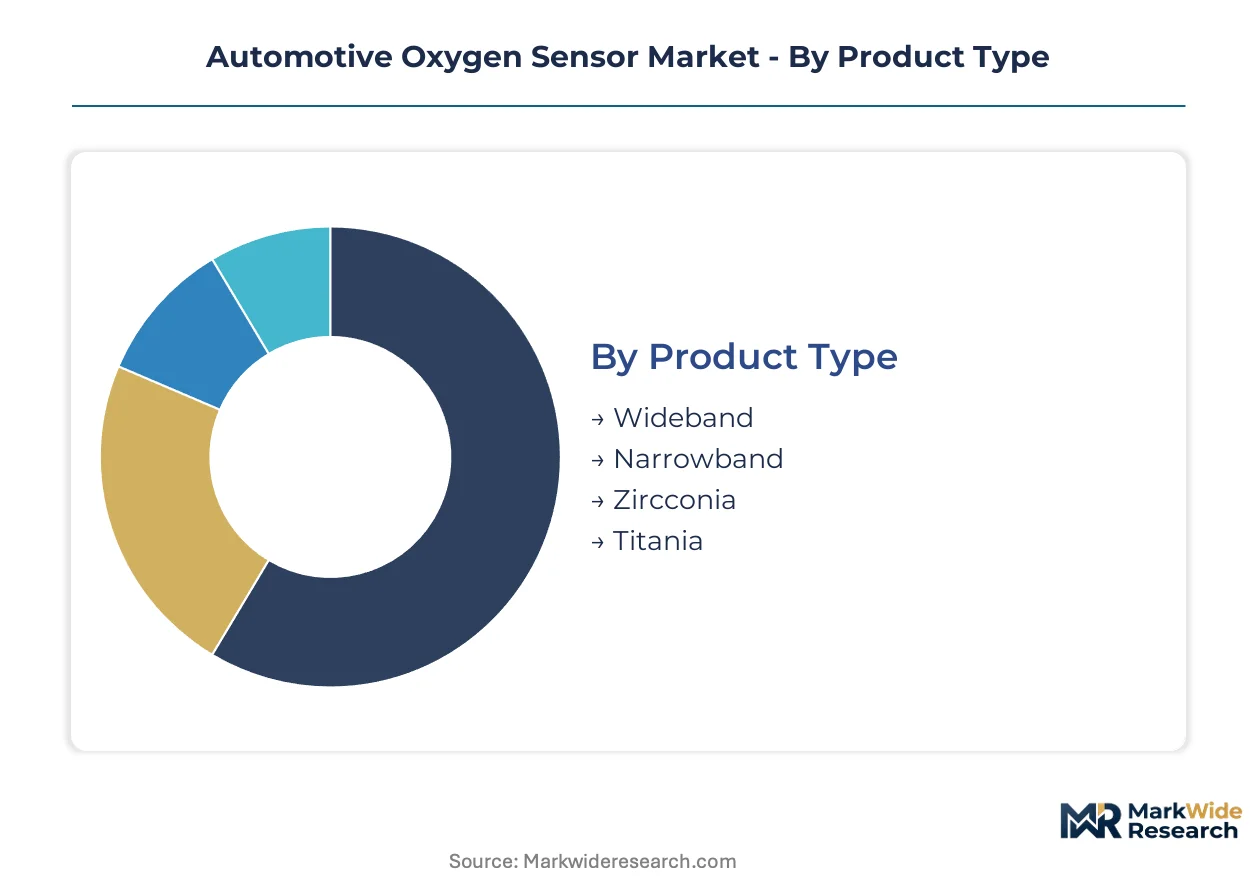
Oxygen sensor procurement patterns diverge sharply across product architectures and customer channels, with OEM fitment programs demanding precision linear-output devices while aftermarket replacement cycles favor cost-optimized switching-type units. Understanding these segment boundaries clarifies where technology investments concentrate versus where price competition dominates.
Product Type:
Wideband sensors command premium positioning in domestic OEM supply chains across Germany, Japan, and the United States, while narrowband variants sustain export-led aftermarket volume into Latin American and Southeast Asian repair markets.
- Wideband:Linear-output electrochemical cells measure lambda 0.7 to 2.0 with voltage proportional to air-fuel ratio deviation, enabling real-time closed-loop control during cold-start transients. Demand concentrates in Euro 7 pre-compliance programs at BMW, Volkswagen, and Stellantis powertrain facilities in Stuttgart, Wolfsburg, and Turin, where sub-200 millisecond response mandates force sensor upgrades.
- Narrowband:Switching-type zirconia thimbles generate rich-lean voltage transitions around stoichiometry, sacrificing measurement range for unit cost below wideband equivalents by 40-60%. Export-led replacement demand flows through Dubai and Singapore distribution hubs into African and South Asian markets running high-sulfur fuels where electrochemical poisoning accelerates refresh cycles.
- Zirconia:Yttria-stabilized ceramic electrolyte forms the functional core of both wideband and narrowband architectures, with planar element construction now displacing thimble formats in turbocharger-proximate mounting positions.
- Titania:Resistive-type titanium dioxide sensors offer faster thermal response than zirconia equivalents but require temperature-compensated signal conditioning, limiting fitment to niche performance applications.
Wideband holds the largest share; momentum sits with zirconia as planar miniaturization enables dual-sensor exhaust runner placement.
Application:
Passenger car platforms generate the highest sensor count per vehicle with four-to-six unit fitment on gasoline direct-injection architectures, while heavy-duty applications sustain margin through severe-duty calibration and extended warranty pricing tiers.
- Passenger Cars:Gasoline and diesel powertrains deploy pre-catalyst and post-catalyst sensor pairs for OBD-II catalyst efficiency monitoring, with turbocharged downsized engines requiring additional turbine-outlet instrumentation. European OEMs in Ingolstadt, Munich, and Rüsselsheim anchor volume through 48V mild-hybrid integration demanding wider lambda control bandwidth.
- Heavy-Duty Trucks:Class 8 commercial vehicles in the United States carry redundant dual-element architectures to maintain EPA compliance during single-sensor fault conditions, with calibration protocols spanning 1.2 million mile design lives. Freightliner and PACCAR specification engineers in Portland and Bellevue mandate thermal shock resistance above passenger car grades.
- Commercial Vehicles:Light-duty vans and delivery trucks in urban European centers face Euro 7 real-driving emissions surveillance, expanding wideband penetration in Ford and Renault commercial divisions.
- Motorcycles:Small-displacement two-wheelers in India and Vietnam retain narrowband fitment due to cost constraints, though BS-VI Stage II implementation is forcing sensor upgrades in 125cc-plus segments.
Passenger cars dominate unit volume; heavy-duty trucks deliver the steepest expansion trajectory as EPA Phase 2 greenhouse gas rules tighten.
End User:
OEM procurement concentrates sensor specification power among ten global powertrain engineering centers, while fleet operators are consolidating aftermarket demand through telematics-enabled predictive maintenance contracts.
- OEMs:Volkswagen Group, Toyota, and General Motors captive purchasing organizations negotiate multi-year supply agreements locking zirconia element allocation, with sensor control module integration bundled into engine ECU sourcing packages.
- Fleet Operators:Schneider National and J.B. Hunt in the United States now schedule oxygen sensor replacement through vehicle health management platforms rather than reactive failure response, converting aftermarket demand into contracted recurring revenue.
- Aftermarket Providers:O'Reilly Auto Parts and AutoZone distribution networks in North America stock narrowband universal-fit sensors for 1996-2010 vehicle parc compatibility, facing margin compression from direct fleet procurement bypass.
- Repair Shops:Independent garages in Germany's Kfz-Innung network and United States IATN members rely on diagnostic trouble code interpretation for sensor replacement authorization, with wideband retrofit friction limiting upgrade penetration.
OEMs command specification authority; fleet operators are gaining share fastest as channel intermediation collapses.
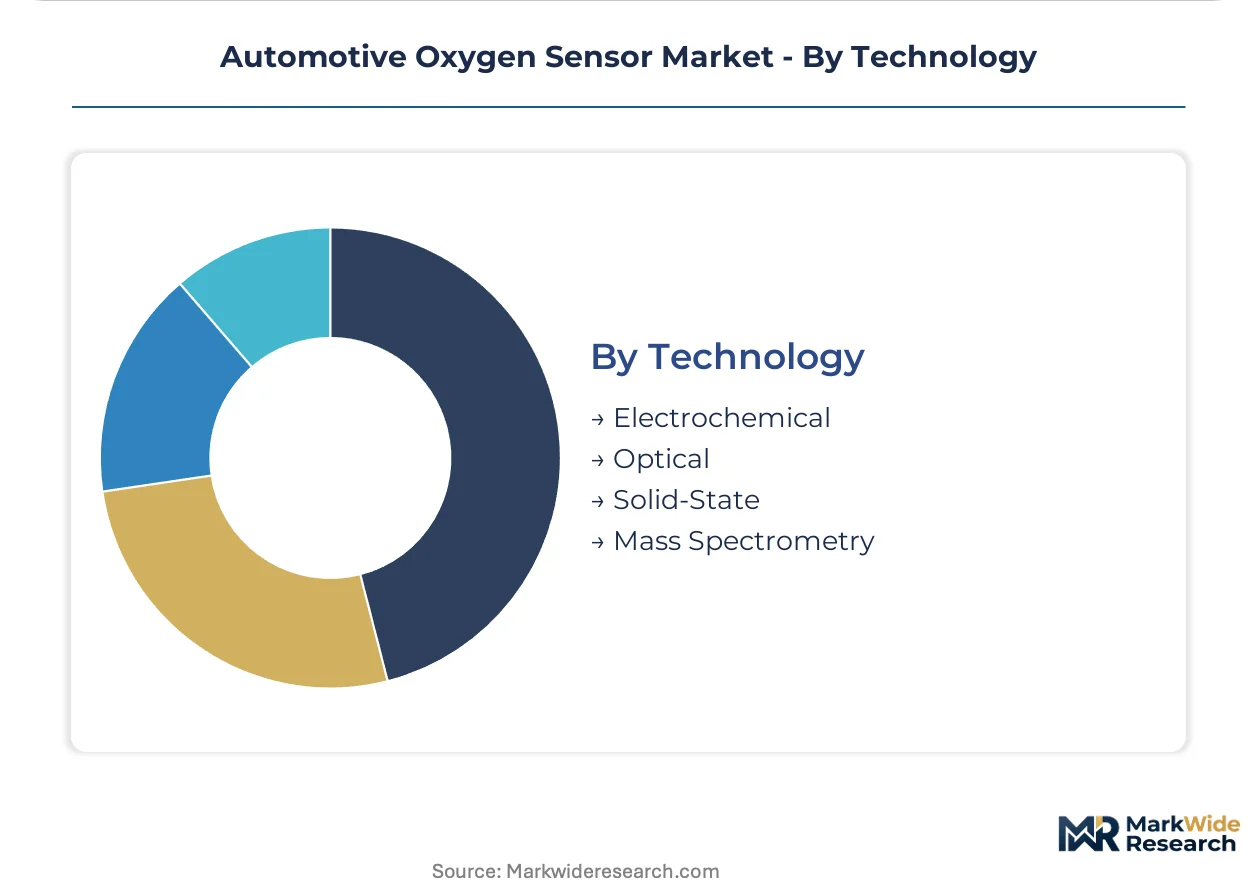
Technology:
Electrochemical architectures retain manufacturing scale advantages through established zirconia supply chains, while solid-state optical platforms eliminate platinum group metal exposure for high-sulfur fuel deployment.
- Electrochemical:Zirconia-based potentiometric and amperometric cells dominate OEM fitment with decades of calibration database accumulation, though heater control ASIC fabrication concentration among three foundry operators creates supply vulnerability.
- Solid-State:Titanium dioxide and gallium oxide thin-film platforms measure oxygen partial pressure through resistive or capacitive transduction, enabling deployment in Brazilian and Middle Eastern markets where sulfur poisoning degrades electrochemical sensors within 30,000 kilometers.
- Optical:Tunable diode laser absorption spectroscopy offers immunity to exhaust contaminant interference but requires protective window maintenance, limiting current fitment to laboratory validation and reference instrument applications.
- Mass Spectrometry:Quadrupole and time-of-flight analyzers deliver multi-species exhaust composition data for R&D calibration but remain excluded from onboard vehicle deployment due to vacuum system complexity.
Electrochemical retains installed base dominance; solid-state platforms are climbing the fastest as material science advances reduce thin-film production costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deepwater port underwrites China's role as the primary import hub for zirconia ceramic precursors, while the Rhine-Main-Danube canal network enables just-in-time sensor delivery to Stuttgart and Ingolstadt assembly plants.
China
Domestic OEMs in Beijing and Shanghai are accelerating wideband sensor procurement ahead of MEE enforcement of China 7 emission standards. MIIT's dual carbon goals mandate real-time lambda monitoring across hybrid powertrain platforms. Yangtze River Delta manufacturing clusters in Suzhou and Wuxi now host planar zirconia element fabrication lines serving Volkswagen and General Motors joint ventures.
Germany
KBA type-approval requirements for Euro 7 pre-compliance are forcing sensor response time upgrades at BMW Munich and Volkswagen Wolfsburg powertrain centers. The EU Green Deal's 55 percent CO2 reduction target compels wider bandwidth lambda control in 48V mild-hybrid architectures. Baden-Württemberg suppliers in Stuttgart anchor continental supply chains through captive zirconia element allocation contracts.
United States
EPA Tier 3 onboard diagnostic thresholds mandate oxygen sensor fault detection within two driving cycles, compressing validation timelines for Detroit Three powertrain engineers. The California Air Resources Board maintains waiver authority over federal harmonization, creating parallel certification paths for sensors deployed in California-Texas freight corridors. Michigan-based tier-one suppliers coordinate heater control ASIC sourcing through Arizona and Texas semiconductor foundry partnerships.
Japan
METI's carbon neutrality roadmap drives sensor specification for hybrid thermal cycling resilience at Toyota City and Honda Takanezawa powertrain development centers. JIS standards for exhaust gas sensors are converging with Euro 7 response time benchmarks. Kansai region manufacturing in Osaka and Kyoto prefectures concentrates zirconia thimble production for domestic OEM fitment and Southeast Asian export.
India
BS-VI Stage II real-driving emissions monitoring is creating first-fit demand for wideband sensors in 125cc-plus motorcycle segments and domestic passenger vehicle platforms. BIS certification requirements are tightening cold-start emission windows for Delhi-NCR and Mumbai metropolitan registration pools. Tamil Nadu automotive clusters in Chennai and Sriperumbudur are integrating sensor assembly into powertrain export programs for African and Middle Eastern markets.
Automotive Oxygen Sensor Market Vendor Landscape
Concentration sits with diversified automotive electronics conglomerates possessing captive ceramic fabrication capabilities. The vendor base organizes around three strategic archetypes: integrated powertrain suppliers controlling zirconia element supply chains, specialized sensor houses focused on thermal shock-resistant architectures, and semiconductor-forward players leveraging heater control ASIC design. Competitive dynamics center on backward integration into ceramic precursor sourcing and geographic expansion through joint venture structures in high-growth emission regulation markets.
Within the integrated tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes of captive supply chain control and hybrid-optimized thermal architecture specialization respectively. Continental AG occupies a position bridging electrochemical sensor heritage with solid-state optical development. NGK Spark Plug Co., Ltd. anchors the ceramic expertise vector through its legacy in spark plug insulator fabrication. Walker Products Inc. represents the aftermarket-focused archetype serving legacy vehicle parc replacement demand through narrowband distribution networks.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| NGK Spark Plug Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| BorgWarner Inc. |
| Delphi Technologies |
| Hitachi Astemo, Ltd. |
| Walker Products Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-day zirconia ceramic precursor inventory buffers at Yangshan port concentrate procurement leverage among three German and Japanese conglomerates, translating upstream material scarcity into downstream pricing power for wideband sensor architectures. This lead-time compression amplifies cost pass-through capacity during platinum group metal price spikes, while fragmenting margin capture across captive foundry operators and independent assemblers.
Pricing Analysis
Volume-discount tiering separates OEM captive contracts from aftermarket spot purchases by 40-60% unit cost deltas. Premium wideband sensors command certification-grade pricing tied to Euro 7 pre-compliance validation, while narrowband replacement units compete on compatibility with legacy ECM protocols. Pricing pressure stems from rhodium electrode coating volatility, squeezing non-integrated assemblers most acutely. Fleet operators exhibit lowest price sensitivity through telematics-enabled predictive contracts, whereas independent repair shops in Southeast Asian markets prioritize universal-fit economy tiers.
Supply Chain Analysis
Strait of Malacca transit underwrites zirconia precursor flows from Australian rare earth refineries to Yangtze River Delta planar element fabrication lines. Heater control ASIC production concentrates in Taiwan, South Korea, and Arizona foundries, creating single-source vulnerability for thermal management circuits. Supply chain risk rests on South African mining output disruptions affecting rhodium and palladium electrode coatings. Distribution runs through Stuttgart and Ingolstadt just-in-time pipelines for European OEM fitment, with Dubai and Singapore hubs serving African and South Asian aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lambda control algorithm development requires cross-domain expertise spanning exhaust chemistry, embedded systems, and powertrain calibration that remains concentrated among ten global engineering centers. This capability scarcity constrains competitive entry and amplifies acquisition premiums for teams possessing heater control ASIC design or zirconia thin-film fabrication experience.
For Market Incumbents: Fortify captive zirconia element allocation through backward integration into Australian and South African ceramic precursor sourcing, insulating margin structures from platinum group metal volatility. Expand planar miniaturization capacity in Suzhou and Wolfsburg to capture dual-sensor exhaust runner placements demanded by turbocharged downsized engine architectures. Prioritize thermal shock-resistant IP for hybrid powertrain thermal cycling resilience against Denso's established hybrid-optimized portfolios. For New Entrants and Emerging Players: Anchor in solid-state optical sensing for Brazilian and Middle Eastern high-sulfur fuel markets where electrochemical poisoning accelerates replacement cycles and incumbent calibration databases offer weaker protection. Target India's BS-VI Stage II implementation window for 125cc-plus motorcycle wideband upgrades, where domestic assembly partnerships with Tamil Nadu powertrain exporters reduce tariff exposure. Pursue fleet telematics integration as the primary go-to-market angle, converting reactive aftermarket transactions into contracted predictive maintenance revenue. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant automotive sensor divisions lacking hybrid powertrain thermal architecture specialization. Long-term viability hinges on exposure to emission regulation acceleration in China, India, and Europe rather than legacy narrowband aftermarket replacement decay. Monitor EPA-CARB harmonization negotiations as the critical inflection signal; divergent OBD-II threshold certification paths would duplicate validation investment and favor incumbent scale over mid-cap challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zirconia Precursor Sourcing | Captive supply of yttria-stabilized ceramic electrolytes secures margin stability against South African mining disruptions. |
| Planar Miniaturization Capacity Expansion | Twelve-millimeter hexagonal formats enable turbocharger-proximate mounting previously excluded from wideband instrumentation. |
| Solid-State Optical Platform Development | Titanium dioxide thin-film architectures eliminate platinum electrode poisoning in high-sulfur fuel deployment environments. |
| Fleet Telematics Integration Partnership | Predictive sensor failure algorithms convert reactive aftermarket replacement into scheduled maintenance recurring revenue. |
| Dual-Element Redundancy Architecture Certification | Heavy-duty EPA compliance maintenance during single-sensor fault conditions commands 1.2 million mile warranty pricing tiers. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributor operations managers, and fleet telematics platform developers, then refined through secondary validation across EPA enforcement guidance documents, KBA type-approval filings, MIIT dual carbon policy circulars, and vehicle production databases from IHS Markit. Bottom-up sensor unit economics triangulated against top-down emission regulation compliance spending estimates across the analysis window.
Variance-decomposition modeling isolated technology substitution effects, regulatory timeline uncertainty, and raw material price volatility as primary forecast error sources. Segmentation dimensions spanned product architecture, vehicle class, propulsion system thermal cycling intensity, OEM tier positioning, and regional emission enforcement stringency. CAGRs derived from installed base refresh frequency modeling and pre-compliance program acceleration curves, with specific inputs including hybrid powertrain penetration trajectories and wideband sensor content-per-vehicle expansion.
Decision-makers should treat outputs as directional under sustained EPA Tier 3 and Euro 7 enforcement timelines; material deviation in CARB waiver authority or China 7 implementation pace would warrant model refresh. Practitioners should keep alternative scenarios live as platinum group metal price corridors and semiconductor foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Automotive Smart Key Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Global Vehicle Camera Market