
 Electric Vehicle High Voltage Wire Harness Market | 2026-2036
Electric Vehicle High Voltage Wire Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle High Voltage Wire Harness Market Insights
Buyer concentration among top-tier EV original equipment manufacturers is expanding as vehicle electrification programs consolidate around fewer high-volume platforms. Yazaki Corporation leverages its integrated design-to-assembly footprint to secure long-term supply agreements with Japanese and European automakers. Sumitomo Electric Industries anchors its position through captive copper processing and proprietary aluminum-core conductor technology. TE Connectivity competes aggressively in the 800V and above segment with shielded connector systems engineered for silicon-carbide powertrains.
An electric vehicle high voltage wire harness is an engineered cable assembly rated typically between 400V and 1000V DC, comprising multi-strand copper or aluminum conductors, high-performance thermoplastic insulation, and electromagnetic shielding designed to distribute power between battery packs, inverters, and traction motors while containing thermal runaway risks. The connector sub-segment captures disproportionate margin pools due to the precision engineering required for waterproof, vibration-resistant mating interfaces in charging and battery management applications. Power distribution harnesses lead by installed value, though motor control harnesses represent the fastest-growing application dimension as multi-motor architectures proliferate in all-wheel-drive EVs.
The EU's F-Gas Regulation and CE marking requirements under the MDR framework constrain insulation material selection and mandate extended thermal cycling validation for harnesses deployed in European-type approved vehicles. China's GB standards, administered by SAMR, enforce localized testing protocols that foreign suppliers must navigate through joint ventures or dedicated in-country certification laboratories. Stakeholders must monitor how evolving ISO 6469 high-voltage safety standards and emerging solid-state battery thermal profiles reshape conductor gauge and shielding specifications before committing to next-generation platform designs.
Market Dynamics
Platform consolidation around 800V architectures is compressing supplier qualification timelines while amplifying volume concentration among wire harness specialists capable of integrated electromagnetic compatibility validation.
Growth Catalysts
- GB/T Standard Harmonization:China's SAMR-administered protocols are accelerating local certification throughput for foreign suppliers establishing Yangtze River Delta joint ventures, reducing time-to-production for high-voltage harness assemblies.
- Multi-Motor Architectures:All-wheel-drive EV platforms from premium passenger segments are multiplying motor control harness counts per vehicle, expanding addressable conductor length and connector density.
- F-Gas Thermal Requirements:The EU's insulation material constraints under tightened F-Gas Regulation are forcing specification upgrades that favor suppliers with captive polymer compounding capabilities.
Market Restraints
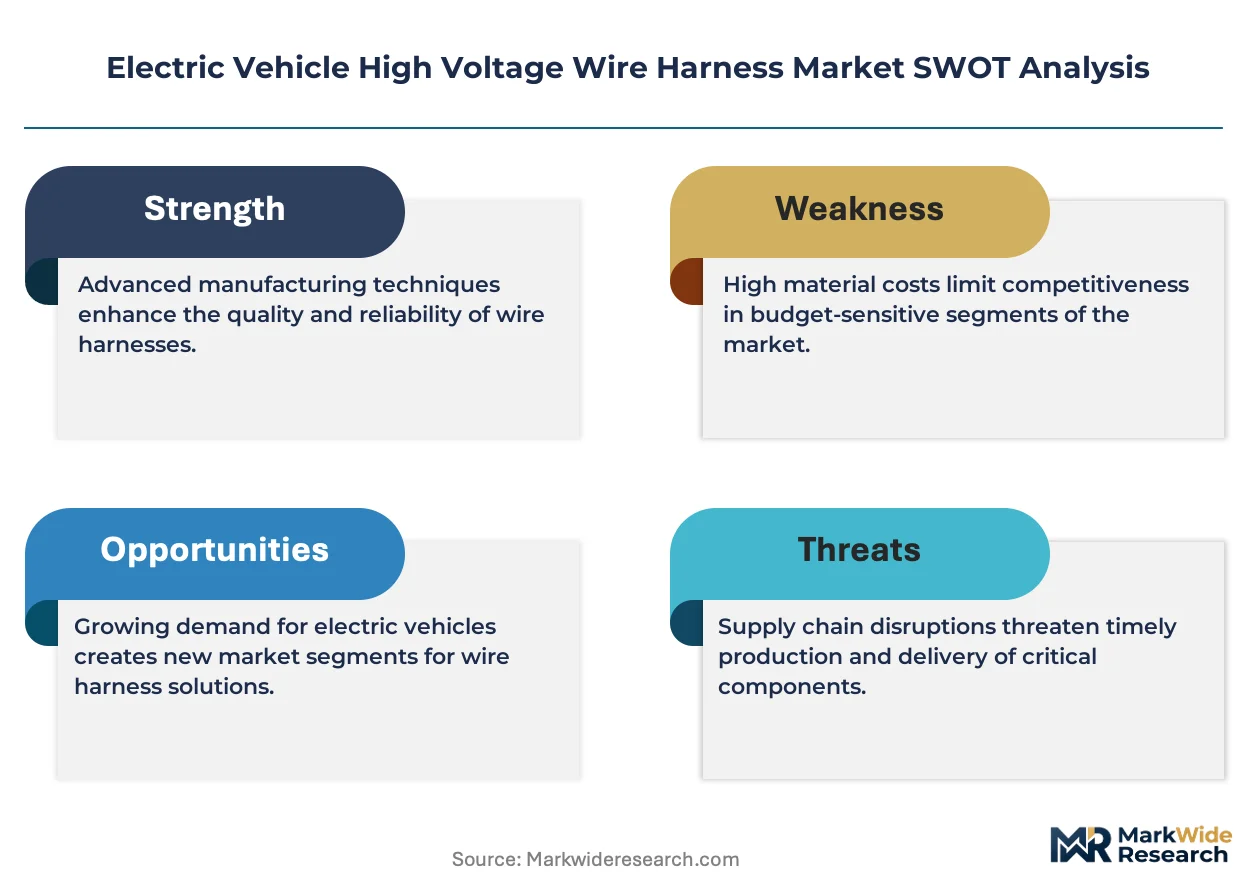
- Copper Price Volatility:LME copper futures swings directly compress margin pools for non-integrated harness assemblers lacking backward integration into conductor drawing or scrap reclamation.
- Yangtze River Delta Concentration:Over half of global EV wire harness output originates from a single Chinese industrial cluster, creating geographic supply risk exposure for European and North American automakers.
- Aluminum-Core Transition Friction:Lightweight conductor adoption stalls where connector crimp reliability and galvanic corrosion resistance remain unproven across full vehicle lifecycle thermal cycling.
Strategic Opportunities
- Solid-State Battery Thermal Profiles:Next-generation cell chemistries with distinct heat rejection signatures will reshape shielding specifications and conductor gauge requirements before platform lock-in.
- Silicon-Carbide Powertrain Integration:800V+ inverter architectures are electrifying demand for shielded connector systems with enhanced partial discharge resistance.
- India PLI Localization:India's production-linked incentive scheme for advanced automotive components is attracting harness investment toward Tamil Nadu and Gujarat manufacturing corridors.
Industry Challenges
- High-Voltage Safety Certification Velocity:ISO 6469 validation protocols and evolving CE marking requirements under the MDR framework are extending qualification timelines for new platform awards.
- Electromagnetic Compatibility Simulation Talent:Finite-element modeling expertise for shielding effectiveness prediction remains scarce relative to procurement demand from silicon-carbide powertrain programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle High Voltage Wire Harness Market |
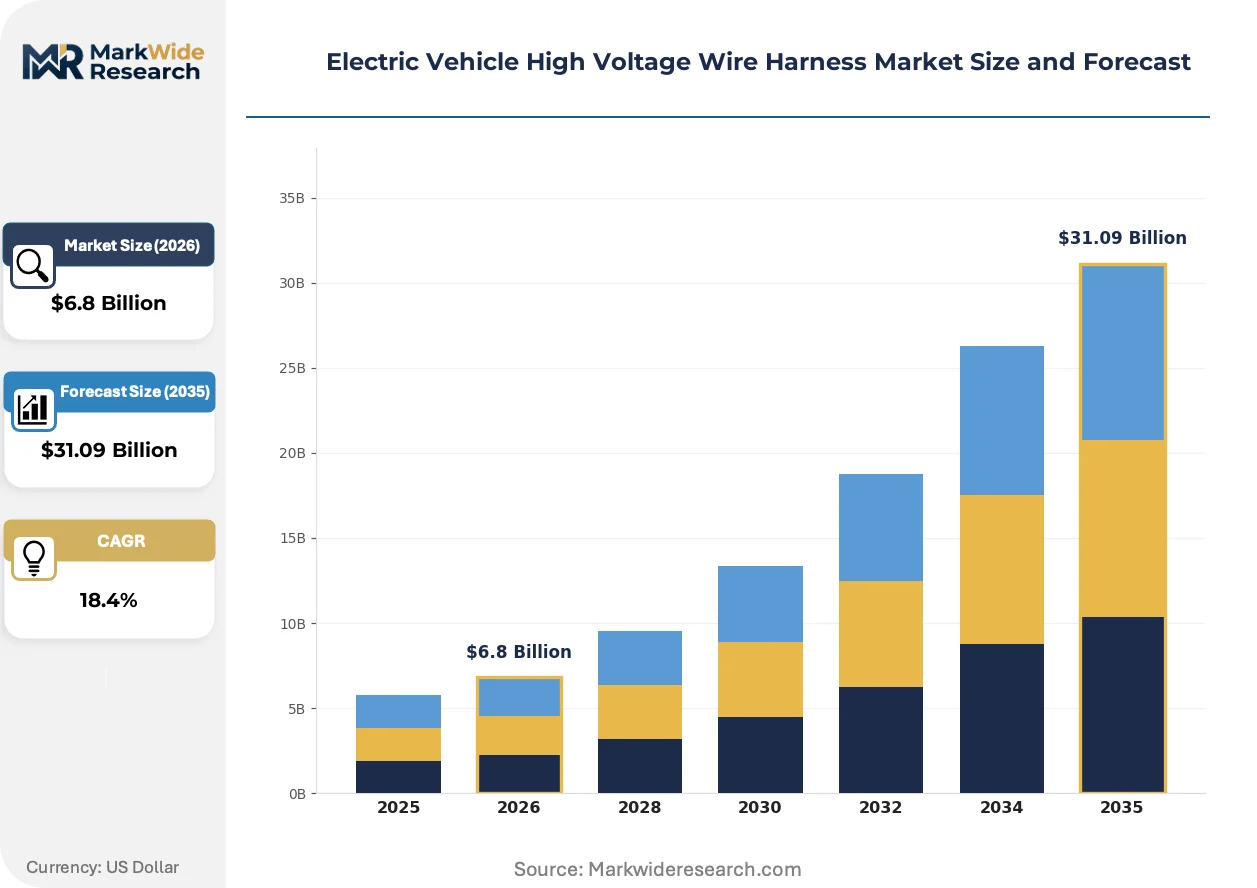
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Harness, Connector, Terminal, Insulation Application: Power Distribution, Battery Management, Motor Control, Charging Systems Installation Type: Integrated, Modular, Custom-built, Aftermarket Material: Copper, Aluminum, Thermoplastics, Composites |
| Companies Covered | Yazaki Corporation, Sumitomo Electric Industries, Aptiv PLC, TE Connectivity, Leoni AG, Lear Corporation, Furukawa Electric, Dräxlmaier Group, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle High Voltage Wire Harness Market Trends and Innovations
Three intersecting forces are restructuring competitive position: conductor material substitution, regulatory thermal performance mandates, and procurement consolidation around fewer high-volume EV platforms.
Aluminum-core conductors with copper-clad terminations are electrifying weight reduction strategies in battery electric vehicles. Premium passenger platforms from German and Korean automakers are adopting hybrid conductor architectures for non-critical power distribution runs. This material transition is electrifying margin pressure on pure-copper specialists while rewarding suppliers with in-house metallurgical processing capabilities.
The EU's F-Gas Regulation and associated CE marking requirements under the MDR framework are constraining fluoropolymer insulation selection. Harness suppliers must now validate extended thermal cycling performance under standardized aging protocols before European-type approval. Tier-1 suppliers with captive polymer laboratories in Germany and France are capturing disproportionate platform engineering roles.
Automaker procurement teams are consolidating supplier panels around vertically integrated wire harness specialists capable of design-to-assembly delivery. Long-term supply agreements now bundle connector development, electromagnetic shielding validation, and just-in-sequence logistics. This pattern concentrates most visibly in China's Yangtze River Delta, where BYD and Tesla procurement organizations have reduced qualified supplier counts by half over three platform generations.
Electric Vehicle High Voltage Wire Harness Market Segmentation
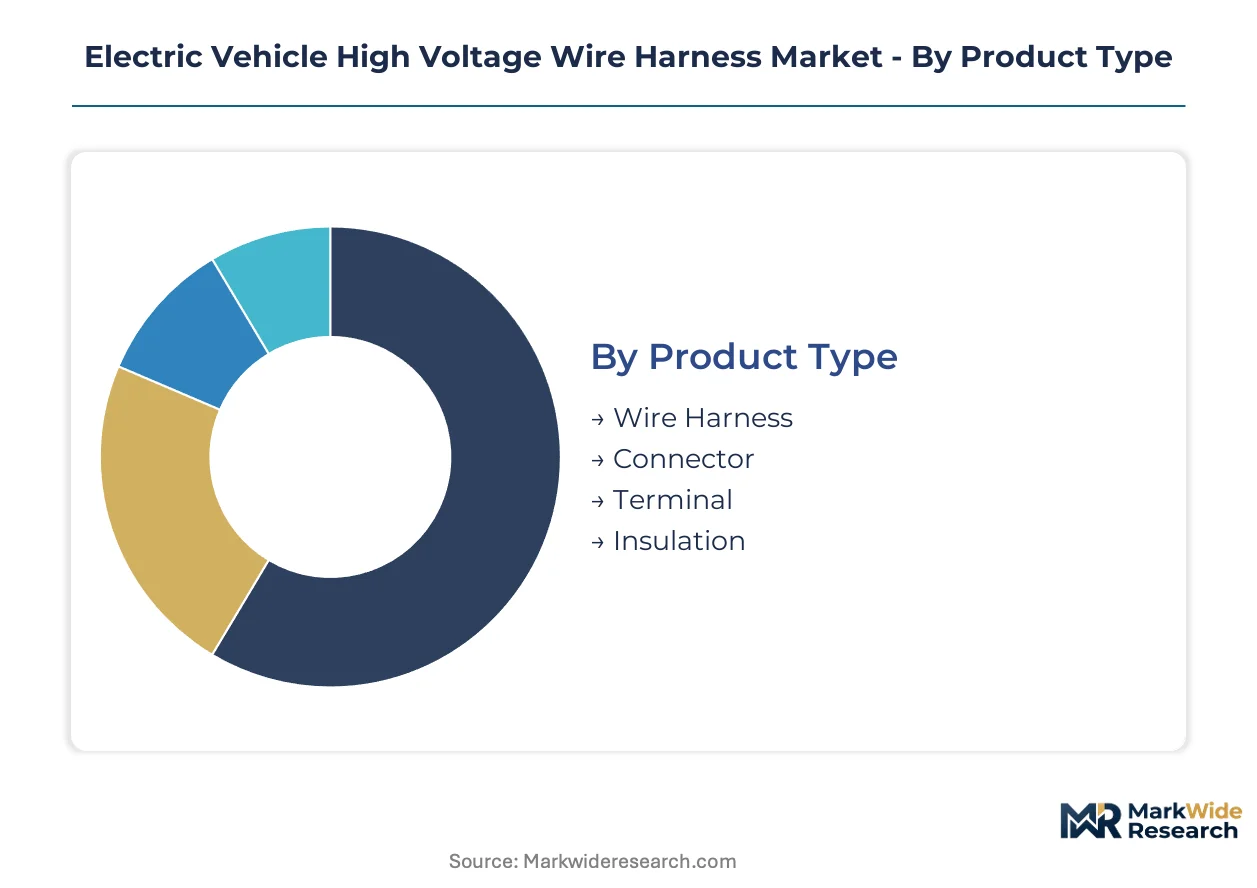
Segmentation in the Electric Vehicle High Voltage Wire Harness Market reveals how certification burdens, material science trade-offs, and platform architecture choices concentrate value capture. Suppliers must align portfolio depth with the specific validation protocols each segment demands.
Product Type:
GB standards administered by SAMR and EU F-Gas Regulation impose divergent insulation and thermal cycling requirements across product categories, fragmenting supplier qualification pathways.
- Wire Harness:Multi-strand conductor assemblies rated 400V-1000V DC with electromagnetic shielding distribute power between battery packs, inverters, and traction motors. Demand concentrates in China's Yangtze River Delta cluster, where over half of global output originates, driven by BYD and Tesla platform consolidation.
- Connector:Precision-engineered mating interfaces with waterproof and vibration-resistant specifications command disproportionate margin pools due to partial discharge resistance requirements at 800V+ architectures. Procurement from silicon-carbide powertrain programs is accelerating shielded connector development cycles.
- Terminal:Crimp and compression interfaces linking conductors to connectors require galvanic corrosion validation for aluminum-core transitions. CE marking under MDR frameworks extends qualification timelines for European-type approved vehicles.
- Insulation:High-performance thermoplastic layers containing thermal runaway risks face constrained fluoropolymer selection under tightened EU thermal mandates. Suppliers with captive polymer compounding capabilities capture expanded platform engineering roles.
Leading the category by volume: Wire Harness. Growing fastest: Connector.
Application:
End-use concentration tracks automaker electrification roadmaps, with motor control harness counts multiplying per vehicle as multi-motor architectures proliferate.
- Power Distribution:Main battery-to-inverter trunk lines carrying highest current loads dominate installed value per vehicle. German and Korean premium passenger platforms are specifying hybrid conductor architectures for weight-critical routing paths.
- Motor Control:Individual phase connections to traction motors are expanding most quickly as all-wheel-drive EVs adopt dual- and triple-motor configurations. Each additional motor increments harness count and connector density proportionally.
- Battery Management:Low-current signal harnesses monitoring cell voltage and temperature require precision shielding against electromagnetic interference from adjacent power conductors. ISO 6469 high-voltage safety standards govern routing separation mandates.
- Charging Systems:Onboard charger and inlet connections must withstand repeated thermal cycling during DC fast-charging events. India's PLI scheme for advanced automotive components is attracting harness investment toward Tamil Nadu manufacturing corridors.
Highest value concentration: Power Distribution. Steepest expansion trajectory: Motor Control.
Installation Type:
Procurement patterns reflect automaker vertical integration preferences and platform lifecycle positioning.
- Integrated:Design-to-assembly delivery bundled with electromagnetic compatibility validation dominates premium passenger EV programs. Long-term supply agreements now consolidate supplier panels around fewer vertically integrated specialists.
- Modular:Pre-validated sub-assemblies reduce qualification burden for mid-volume platforms with compressed development timelines. Standardized interfaces enable second-sourcing flexibility.
- Custom-built:Bespoke routing solutions for low-volume performance or commercial vehicle applications carry elevated engineering amortization. Validation costs per unit exceed modular alternatives substantially.
- Aftermarket:Replacement harness demand remains nascent as EV fleet age accumulates, concentrated in collision repair channels requiring OEM certification to preserve warranty coverage.
Dominant procurement mode: Integrated. Fastest-climbing alternative: Modular.
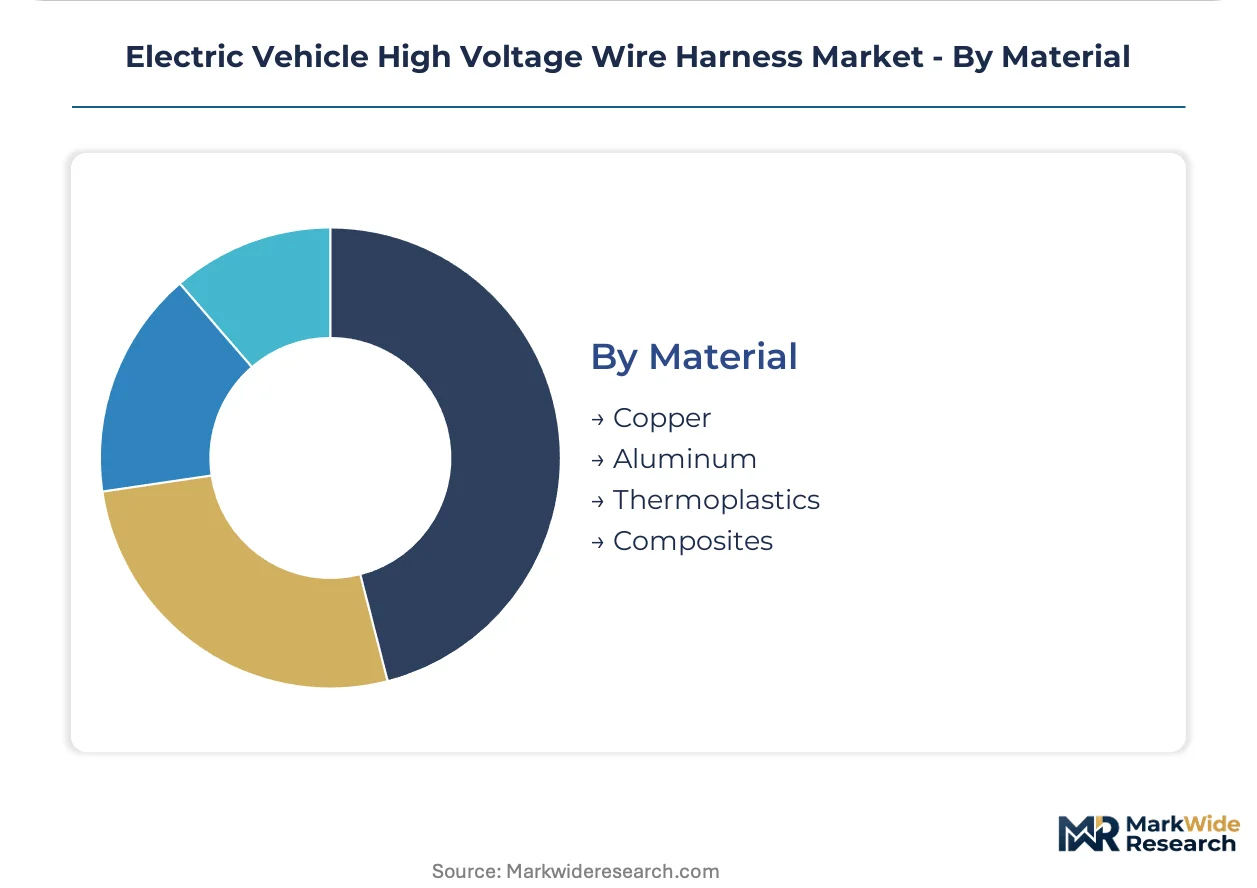
Material:
Conductor substitution dynamics and regulatory thermal constraints are restructuring supplier metallurgical capabilities.
- Copper:High-conductivity multi-strand conductors remain the baseline for critical power paths despite LME price volatility. Non-integrated assemblers lacking backward integration into conductor drawing face compressed margin exposure.
- Aluminum:Lightweight core conductors with copper-clad terminations are electrifying weight reduction strategies in battery electric vehicles. Transition friction persists where connector crimp reliability across full lifecycle thermal cycling remains unproven.
- Thermoplastics:Cross-linked polyethylene and polyamide insulation compounds must validate extended thermal cycling under standardized aging protocols for European-type approval. Captive polymer laboratories in Germany and France secure disproportionate engineering roles.
- Composites:Hybrid material structures combining conductive and insulating functions in single extrusions remain developmental, targeting solid-state battery thermal profiles with distinct heat rejection signatures.
Volume leader: Copper. Fastest material transition: Aluminum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automaker procurement teams concentrate high-voltage harness demand in manufacturing clusters where battery gigafactories and vehicle assembly plants co-locate. Platform consolidation around 800V architectures intensifies supplier qualification in these geographies.
China
BYD and Tesla procurement organizations drive demand concentration in the Yangtze River Delta cluster. SAMR-administered GB/T standards enforce localized testing protocols that foreign suppliers navigate through joint ventures. Over half of global EV wire harness output originates from this single industrial corridor.
Germany
BMW and Volkswagen electrification programs anchor European demand for 800V+ shielded connector systems. The EU's F-Gas Regulation and CE marking requirements under the MDR framework constrain insulation material selection. Captive polymer laboratories in Bavaria and Baden-Württemberg secure disproportionate platform engineering roles.
United States
Tesla's Gigafactory Nevada and Ford's BlueOval SK battery joint venture in Kentucky drive regional harness demand. NHTSA safety standards and evolving ISO 6469 protocols govern high-voltage routing separation mandates. Southeast manufacturing corridors attract supplier investment toward Tennessee and South Carolina vehicle assembly hubs.
Japan
Toyota and Nissan solid-state battery roadmaps reshape conductor gauge specifications for next-generation platforms. METI industrial policy supports domestic harness specialist consolidation. Kanto and Kansai industrial belts maintain concentrated supplier engineering capabilities for silicon-carbide powertrain integration.
India
Tata Motors and Mahindra electric vehicle programs expand motor control harness counts for domestic multi-motor architectures. The PLI scheme for advanced automotive components attracts harness investment toward Tamil Nadu and Gujarat manufacturing corridors. BIS certification requirements structure local qualification pathways for foreign tier-1 suppliers.
Electric Vehicle High Voltage Wire Harness Market Competitive Landscape
Japanese producers anchor one tier; German specialists hold premium-platform engineering relationships; Chinese fabricators capture volume scale. The vendor base structures around three tiers: integrated design-to-assembly specialists, component-focused connector manufacturers, and regional cable assemblers. Two strategic archetypes dominate: backward-integrated metallurgical processors and electromagnetic compatibility validation houses. Competitive moves concentrate on long-term supply agreement bundling and in-country certification laboratory establishment.
Among Japan-based fabricators, Yazaki Corporation and Sumitomo Electric Industries exemplify the integrated specialist archetype with captive conductor processing capabilities. TE Connectivity occupies a position among connector-focused competitors addressing silicon-carbide powertrain shielding requirements. These three companies represent distinct competitive vectors: metallurgical integration, electromagnetic validation, and precision connector engineering.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Aptiv PLC |
| TE Connectivity |
| Leoni AG |
| Lear Corporation |
| Furukawa Electric |
| Dräxlmaier Group |
| Nexans |
| Others |
Pricing and Supply Chain Analysis
The EU's F-Gas Regulation gates both qualified supply and premium-tier pricing access by mandating extended thermal cycling validation for insulation materials, forcing automakers to source exclusively from suppliers with captive polymer laboratories in Germany and France while paying certification premiums for European-type approved harness assemblies.
Pricing Analysis
Volume concentrates in standard-grade copper conductor assemblies serving mass-market EV platforms, while margins pool disproportionately in shielded connector systems for 800V+ silicon-carbide powertrains where partial discharge resistance commands engineering premiums. Price differentiation separates CE-marked harnesses validated under MDR frameworks from GB/T-certified alternatives for the Chinese domestic market. Pricing pressure stems from LME copper volatility compressing margin pools for non-integrated assemblers lacking backward integration into conductor drawing. Fleet procurement teams at BYD and Tesla demonstrate highest price sensitivity through consolidated platform sourcing, while BMW and Volkswagen premium programs prioritize electromagnetic compatibility performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tesla, BYD, and Volkswagen, bypassing traditional tier-2 distribution layers. Geographic supply concentrates in China, Germany, and Japan, with over half of global EV wire harness output originating from China's Yangtze River Delta cluster. Raw material dependencies rest on LME copper cathodes, high-performance thermoplastic compounds, and electromagnetic shielding alloys. Single-source vulnerability concentrates in Yangtze River Delta manufacturing corridors, where flooding or power rationing would disrupt European and North American automaker programs. Distribution runs through just-in-sequence logistics directly into battery gigafactory and vehicle assembly co-location sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle high voltage wire harness market sits in a technology-transition phase where 800V architectures are displacing legacy 400V systems, reshaping conductor gauge specifications and electromagnetic shielding requirements across platform generations.
For Market Incumbents: Cement long-term supply agreements with Japanese and European automakers by bundling connector development with electromagnetic compatibility validation services. Deepen backward integration into aluminum-core conductor processing to capture lightweighting premiums from German and Korean premium passenger platforms. Defend against Chinese joint venture competitors establishing SAMR-certified laboratories in the Yangtze River Delta by accelerating CE marking throughput for European-type approved vehicles. For New Entrants and Emerging Players: India's PLI scheme for advanced automotive components opens a window for harness investment toward Tamil Nadu and Gujarat manufacturing corridors, where Tata Motors and Mahindra procurement organizations seek localized motor control harness suppliers. Target modular pre-validated sub-assemblies for mid-volume platforms with compressed development timelines, avoiding direct competition with integrated design-to-assembly specialists. Establish BIS certification pathways early to secure qualification for foreign tier-1 supplier roles. For Investors and Strategic Acquirers: Solid-state battery thermal profile announcements from Toyota and Nissan are the leading indicator that conductor gauge and shielding specifications will reshape before next-generation platform lock-in. Position acquisition screening around electromagnetic compatibility validation houses with finite-element modeling expertise for silicon-carbide powertrain programs, as capability scarcity in this domain intensifies procurement competition. Monitor ISO 6469 protocol revisions for early signals of extended qualification timelines that would favor incumbent specialists with established certification relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | 800V architecture consolidation reduces supplier qualification timelines for Tesla and BYD procurement teams. |
| Battery Supply Agreement | Long-term offtake contracts with CATL and LG Energy Solution anchor conductor demand forecasting. |
| Software-Defined Vehicle Investment | Digital twin integration enables predictive harness routing optimization for multi-motor architectures. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat corridors capture India's PLI scheme incentives for advanced automotive components. |
| Charging Infrastructure Partnership | DC fast-cycling validation protocols with ABB and Siemens secure thermal performance credentials. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with OEM platform engineers, tier-1 supplier procurement leads, and electromagnetic compatibility validation specialists alongside secondary validation from SAMR GB/T standard databases, EU F-Gas Regulation implementation guidance, and vehicle production registries. Bottom-up and top-down triangulation cross-checked conductor demand estimates against battery gigafactory capacity announcements and platform electrification roadmaps.
Segmentation-level modeling tracked wire harness, connector, terminal, and insulation product types across power distribution, motor control, battery management, and charging system applications, with installation type and material composition dimensions layered throughout the projection horizon. CAGRs derived from vehicle electrification adoption curves, content-per-vehicle trajectories for multi-motor architectures, and regional regulatory enforcement timelines for high-voltage safety standards. Forecast inputs incorporated silicon-carbide powertrain penetration rates and solid-state battery thermal profile evolution.
Caveats apply where LME copper price volatility, Yangtze River Delta supply disruption, or accelerated ISO 6469 protocol revision could materially shift the outlook. Practitioners should monitor SAMR certification throughput rates and EU F-Gas Regulation enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
India ECU Market