
 Global Automotive Financing Market | 2026-2036
Global Automotive Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Financing Market Intelligence
China's EV manufacturing expansion is reconfiguring how automotive credit flows across emerging and developed economies. Toyota Financial Services leverages its captive finance model to sustain low-cost leasing programs across Asian markets. Volkswagen Financial Services anchors European EV subscription offerings through direct-to-consumer digital platforms. Ally Financial competes in North America by specializing in used-vehicle refinancing with rapid digital underwriting.
Automotive financing encompasses credit instruments, lease structures, and installment contracts that enable vehicle acquisition without full upfront payment, typically spanning 36 to 84 months with interest rates indexed to central bank benchmarks or residual value forecasts. Its primary commercial purpose is to accelerate vehicle sales velocity while generating recurring interest income for originators and distributing credit risk across institutional investors. Lease structures among passenger cars command dominant volume share in premium segments, while fixed-rate installment loans for electric vehicles represent the fastest-expanding margin pool as battery cost curves improve collateral valuation confidence. Balloon payment arrangements for commercial vehicles remain structurally mature in European markets, where residual value risk sits with fleet operators rather than finance providers.
US banking regulators including the Consumer Financial Protection Bureau and the Federal Reserve shape automotive credit through Truth in Lending Act enforcement and interest rate policy transmission, while the SEC governs asset-backed securitization markets that fund most originators. European oversight from EBA stress-testing frameworks and ECB monetary policy directly alters wholesale funding costs for captive lenders operating across the eurozone. Stakeholders must monitor how central bank rate trajectories and evolving battery residual value models reshape underwriting standards and securitization appetite.
Market Dynamics
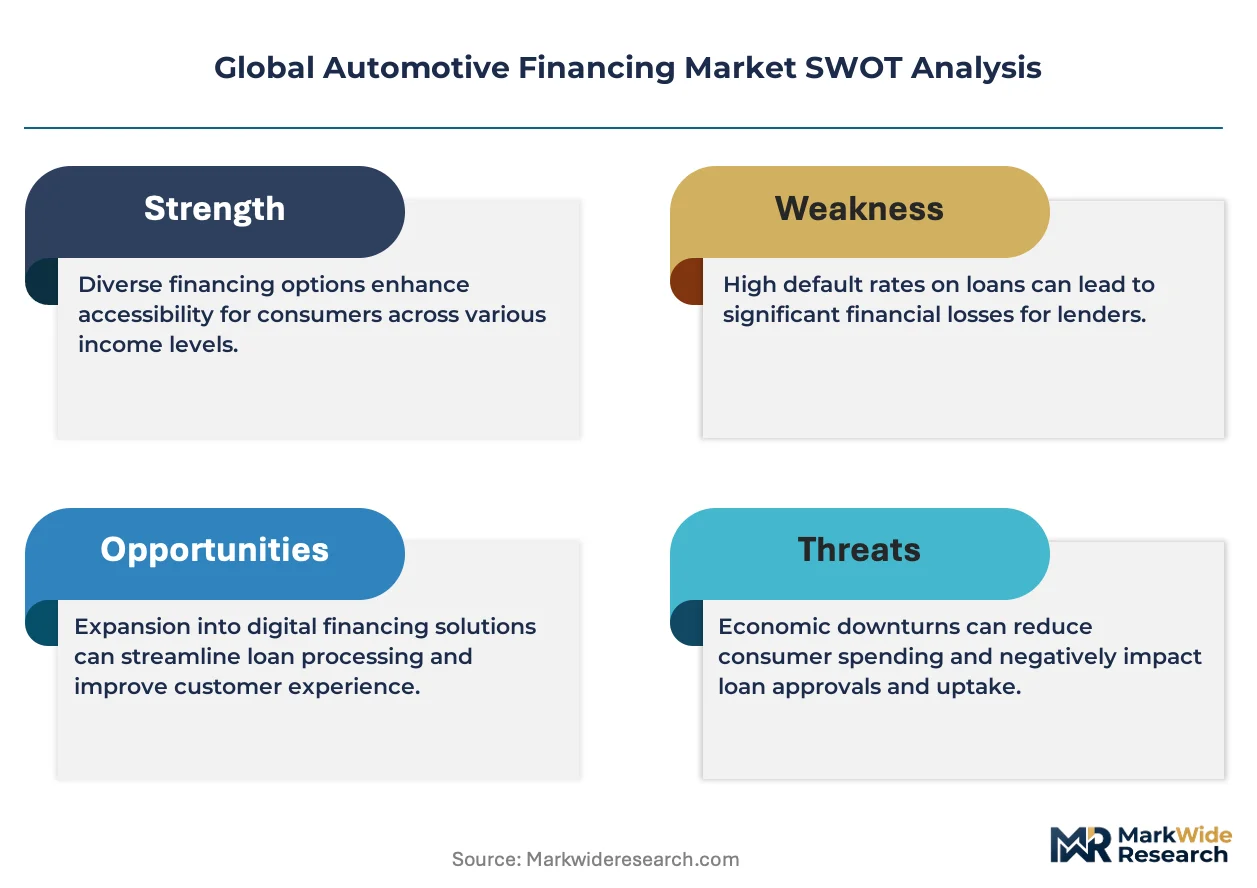
Residual value uncertainty for battery electric vehicles is forcing captive finance arms to rebuild underwriting models around cell chemistry degradation curves rather than traditional mileage-based depreciation schedules.
Growth Catalysts
- EU Green Deal zero-emission mandates:Fleet operators in Germany and the Netherlands are accelerating lease rollovers into battery electric vehicles to avoid penalties, expanding the addressable credit pool for captive lenders.
- Vehicle subscription platforms:Digital-native entrants are bundling insurance, maintenance, and charging into single monthly payments, attracting urban consumers who reject long-term ownership.
- China's NEV credit trading system:Domestic automakers must finance production-scale battery electric output to generate compliance credits, channeling capital into captive leasing infrastructure.
Market Restraints
- Lithium carbonate price volatility:Input cost swings of 40% within single quarters compress residual value confidence and force frequent repricing of lease contracts.
- Concentrated battery cell supply:Korean and Chinese manufacturers control 80% of global cell capacity, exposing European and North American originators to collateral valuation risk if supply disruptions occur.
- Truth in Lending Act disclosure friction:US regulators require granular battery degradation disclosures that lengthen origination workflows and increase compliance overhead.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Domestic production incentives are drawing assembly investment that will require localized captive finance arms to serve price-sensitive first-time buyers.
- Vehicle-to-grid integration:Bidirectional charging hardware creates new collateral value streams, enabling lenders to structure loans where battery capacity serves as revenue-generating grid assets.
- California's Advanced Clean Trucks regulation:Commercial fleet electrification mandates in the US state are opening specialized credit products for medium-duty electric vehicle procurement.
Industry Challenges
- Data science talent scarcity:Underwriting teams lack sufficient expertise in battery health prediction algorithms, delaying deployment of dynamic residual value models.
- Legacy core system integration:Mainframe-based loan servicing platforms at established lenders cannot process real-time telematics feeds for usage-based pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Financing Market |
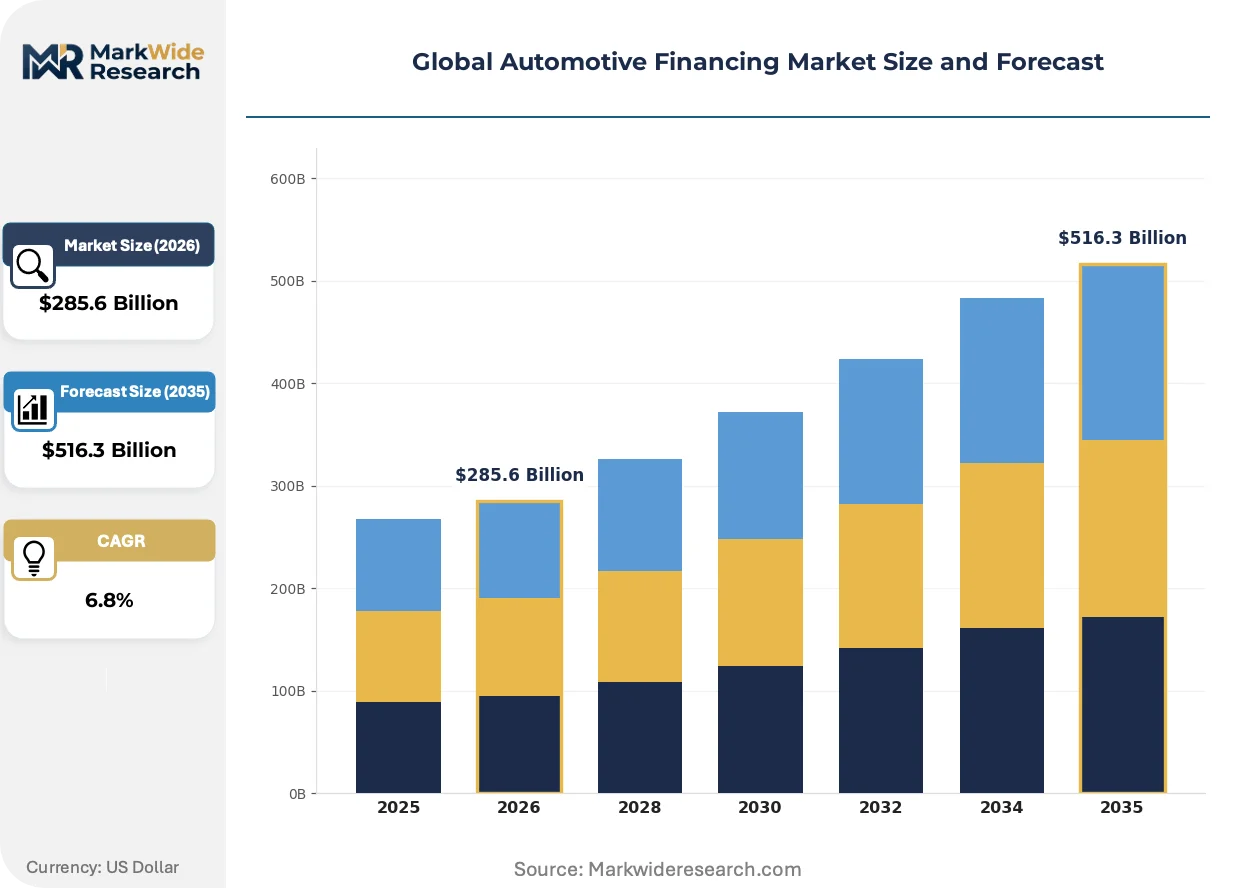
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $516.3 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Lease, Loan, Line of Credit, Cash Payment Customer Type: Individual Buyers, Dealerships, Fleet Operators, Corporate Buyers Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Installment Structure: Fixed Rate, Variable Rate, Balloon Payment, Payment Plans |
| Companies Covered | Toyota Financial Services, Volkswagen Financial Services, Ford Motor Credit Company, Ally Financial, Bank of America, GM Financial, Capital One Auto Finance, Daimler Financial Services, JPMorgan Chase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Financing Market Strategic Shifts & Innovations
Digital origination platforms are compressing decision timelines from days to minutes while embedding alternative data sources that bypass traditional credit bureau dependencies.
Blockchain-based smart contracts for vehicle title transfer and lien perfection are virtualizing collateral registration processes. Captive finance arms in Singapore and Switzerland are piloting distributed ledger systems that automate ownership verification. This architecture is virtualizing the notarization and county-recorder intermediaries that historically added friction to cross-border fleet transactions.
The EU AI Act's risk classification framework is compelling automotive lenders to document algorithmic decision logic for credit scoring models. Originators operating across the eurozone must now maintain explainability logs that satisfy EBA supervisory expectations. German captive lenders have responded by segregating high-risk automated decisions for human-in-the-loop review.
Fleet procurement departments are consolidating vendor relationships around full-service mobility providers rather than discrete vehicle lessors. Corporate buyers in the United Kingdom and France now prioritize single-contract solutions covering charging infrastructure, energy management, and vehicle allocation. This concentration is compressing the addressable market for standalone finance providers who cannot bundle adjacent services.
Global Automotive Financing Market Segmentation
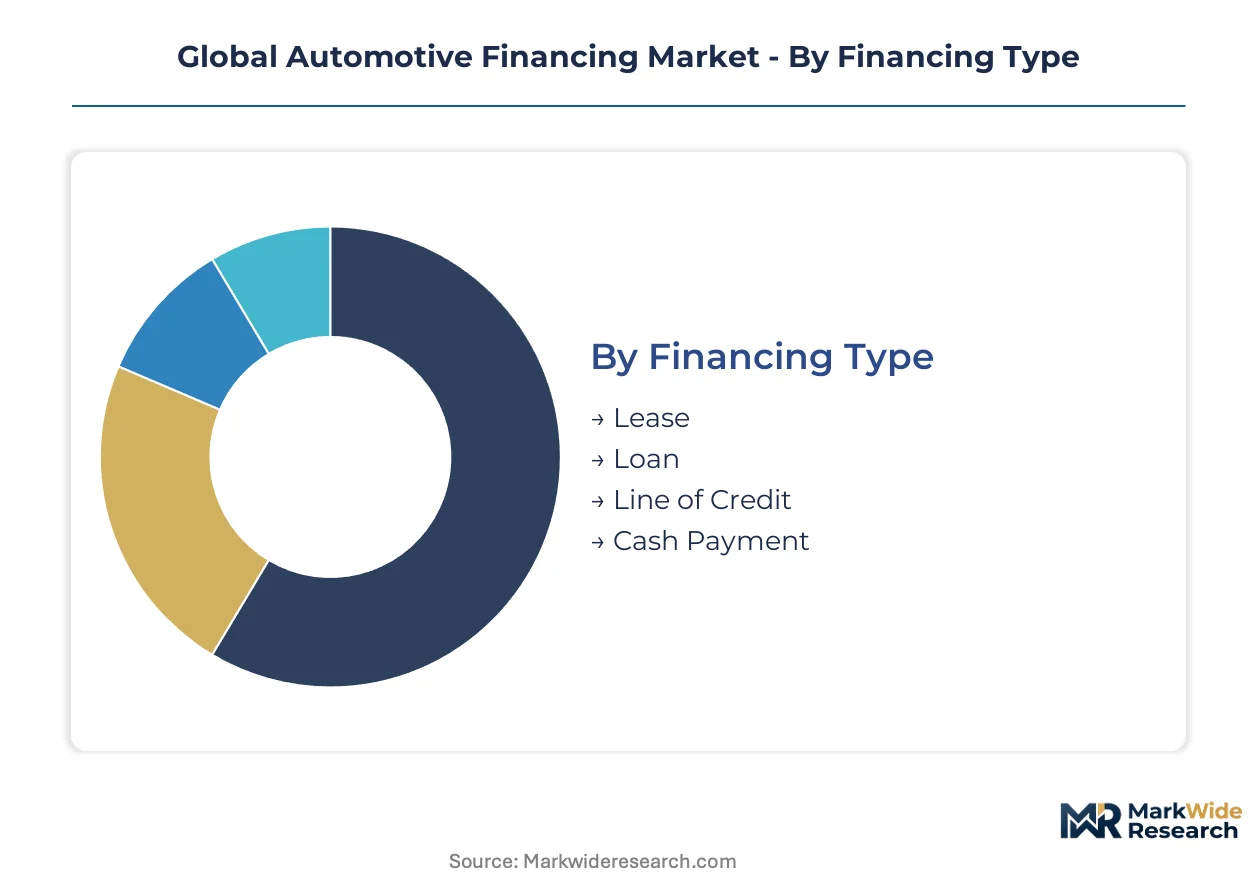
Automotive financing segmentation reveals how capital flows diverge across transaction structures, buyer profiles, and vehicle technologies. Each dimension carries distinct risk-return profiles that reshape underwriting priorities for originators worldwide.
Financing Type:
Mature structures dominate volume while emerging instruments capture regulatory tailwinds and shifting ownership preferences.
- Lease:Structured contracts transfer residual value risk to originators while granting usage rights to lessees for fixed terms. European fleet operators in Germany and the Netherlands are accelerating lease rollovers into battery electric vehicles to comply with EU Green Deal zero-emission mandates, expanding captive lender addressable pools.
- Loan:Fixed-term installment contracts convey full ownership upon final payment, with collateral securing the obligation. Individual buyers in China favor loans from domestic automaker captive finance arms scaling EV-specific infrastructure to serve price-sensitive consumers.
- Line of Credit:Revolving facilities enable flexible drawdowns against vehicle collateral for working capital or acquisition timing. Dealership inventory financing in North America relies on these structures to manage seasonal demand fluctuations.
- Cash Payment:Full upfront settlement eliminates credit intermediation entirely. Corporate buyers with strong balance sheets deploy this option to avoid interest carry in high-rate environments.
Loan structures handle the majority of throughput; lease products are expanding most quickly on share as electrification mandates reshape fleet procurement.
Customer Type:
Cost tier stratification separates high-volume standardized processing from bespoke relationship-managed accounts requiring customized covenant structures.
- Individual Buyers:Retail consumers seeking personal vehicle acquisition through standardized credit scoring and rapid digital underwriting. Digital-native platforms in Singapore are embedding alternative data sources to bypass traditional bureau dependencies for this segment.
- Dealerships:Intermediary channel partners requiring floorplan financing and consumer credit facilitation. US banking regulators including the Federal Reserve shape this segment's liquidity through interest rate policy transmission.
- Fleet Operators:Multi-unit commercial buyers prioritizing total cost of ownership and residual value certainty. California's Advanced Clean Trucks regulation is opening specialized credit products for medium-duty electric vehicle procurement among this customer type.
- Corporate Buyers:Enterprise entities consolidating mobility spend around full-service providers rather than discrete lessors. UK and French procurement departments now prioritize single-contract solutions covering charging infrastructure and vehicle allocation.
Individual buyers generate the highest transaction count; fleet operators command the steepest expansion trajectory as electrification mandates tighten.
Vehicle Type:
Application-driven demand concentrates in established categories while technology transitions create new margin pools requiring specialized collateral expertise.
- Passenger Cars:Light-duty personal transportation vehicles comprising the historical core of automotive credit. Lease structures among passenger cars command dominant volume share in premium segments across developed markets.
- Commercial Vehicles:Medium and heavy-duty assets serving logistics, construction, and vocational applications. Balloon payment arrangements for commercial vehicles remain structurally mature in European markets where residual value risk sits with fleet operators.
- Motorcycles:Two and three-wheeled vehicles with distinct depreciation curves and collateral recovery profiles. India's PLI scheme for automotive manufacturing is drawing assembly investment that will require localized captive finance arms to serve first-time buyers in this segment.
- Electric Vehicles:Battery-powered platforms requiring novel underwriting around cell chemistry degradation rather than mileage-based schedules. Fixed-rate installment loans for electric vehicles represent the fastest-expanding margin pool as battery cost curves improve collateral valuation confidence.
Passenger cars anchor current volume; electric vehicles are climbing the fastest on share as residual value models stabilize.
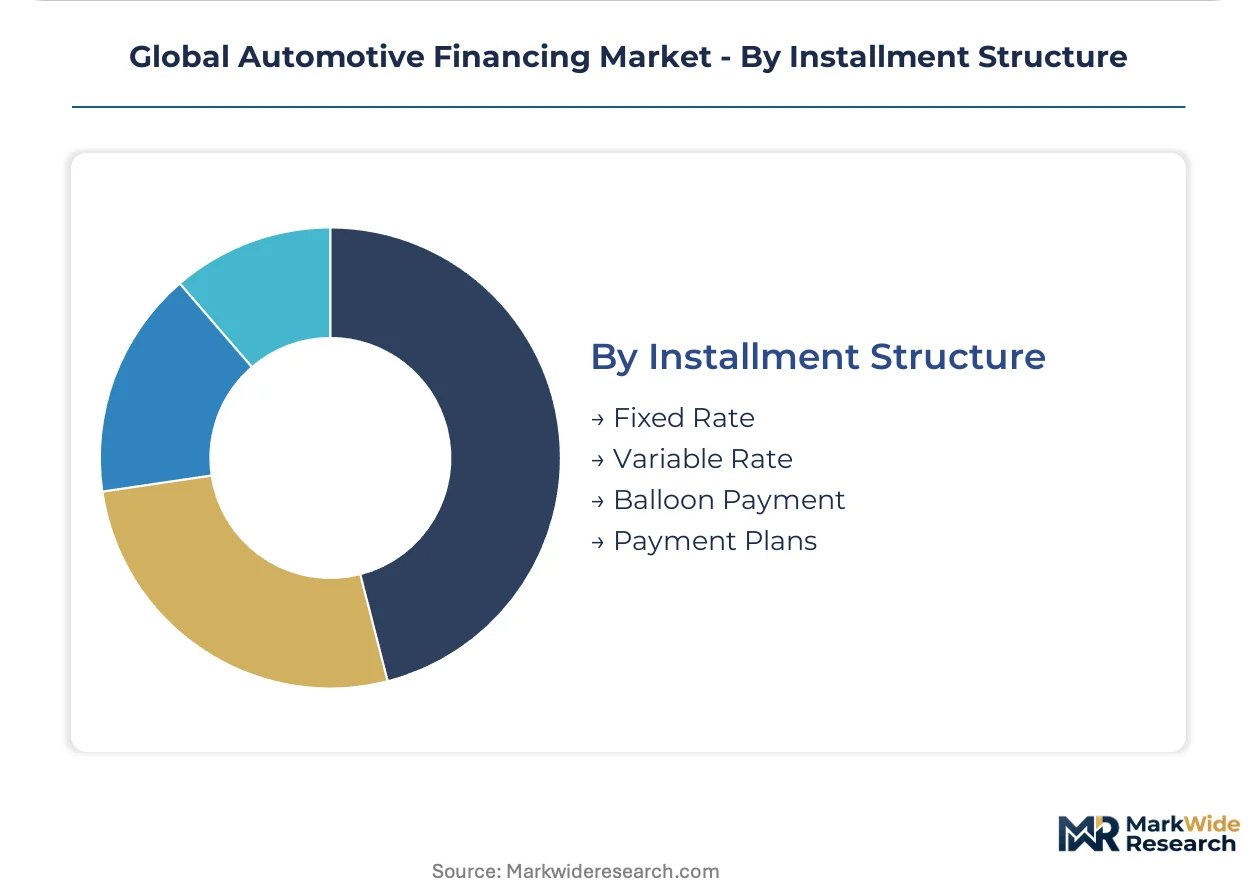
Installment Structure:
Margin profiles vary across interest rate risk allocation and payment timing flexibility, with regulatory disclosure requirements adding compliance overhead to certain structures.
- Fixed Rate:Locked interest obligations protecting borrowers from central bank trajectory shifts. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure standards that lengthen origination workflows for these products.
- Variable Rate:Benchmark-indexed obligations transferring rate risk to borrowers. ECB monetary policy directly alters wholesale funding costs for captive lenders offering these structures across the eurozone.
- Balloon Payment:Structures deferring substantial principal to term conclusion, lowering periodic obligations. Fleet operators favor these arrangements to match cash flows with asset revenue generation cycles.
- Payment Plans:Flexible schedules accommodating irregular income patterns or seasonal business cycles. Vehicle subscription platforms are bundling insurance, maintenance, and charging into single monthly payments under this rubric.
Fixed rate structures handle the majority of origination volume; payment plans are gaining share fastest as urban consumers reject long-term ownership commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive finance arms cluster in manufacturing hubs where automakers anchor lending infrastructure close to assembly operations. China, Germany, the United States, Japan, and India concentrate the majority of originator headquarters and digital underwriting platforms.
China
Domestic automakers scale EV leasing infrastructure to serve price-sensitive consumers entering personal mobility. The NEV credit trading system compels manufacturers to finance battery electric production at scale. Shanghai and Shenzhen host captive finance digital platforms processing millions of micro-loans annually.
Germany
EU Green Deal zero-emission mandates accelerate fleet lease rollovers into battery electric vehicles across industrial logistics. EBA stress-testing frameworks alter wholesale funding costs for eurozone captive lenders. Stuttgart and Munich anchor Volkswagen and Daimler financial services headquarters with direct-to-consumer digital platforms.
United States
California's Advanced Clean Trucks regulation opens specialized credit products for medium-duty electric vehicle procurement among commercial fleets. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure standards that lengthen origination workflows. Detroit retains captive finance concentration for legacy automakers while Texas hosts Ally Financial's used-vehicle refinancing operations.
Japan
Toyota Financial Services leverages its captive model to sustain low-cost leasing programs across Asian markets. METI industrial policy supports export financing for regional vehicle distribution. Tokyo and Nagoya concentrate originator technology development for telematics-integrated underwriting systems.
India
The PLI scheme for automotive manufacturing draws assembly investment requiring localized captive finance arms for first-time buyers. RBI monetary policy transmission affects retail auto loan pricing across tier-2 and tier-3 cities. Maharashtra and Gujarat host emerging finance company operations tied to two-wheeler and passenger vehicle production clusters.
Global Automotive Financing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in residual value modeling and battery health analytics. The market structures around captive finance arms owned by major automakers, independent consumer lenders, and banking conglomerates with dedicated auto divisions. Three archetypes dominate: manufacturer-captive originators with integrated lease-to-assembly pipelines, independent digital lenders specializing in used-vehicle refinancing, and universal banks leveraging balance sheet scale for competitive rate positioning. Competitive moves concentrate on M&A to acquire telematics data capabilities and strategic partnerships with charging infrastructure providers to bundle mobility services.
Among Japan-based captive specialists, Toyota Financial Services exemplifies the manufacturer-integrated archetype with regional leasing dominance. Volkswagen Financial Services and Ford Motor Credit Company occupy positions within the European and North American captive tiers respectively, each representing the automaker-owned model where origination aligns with vehicle sales velocity. Ally Financial anchors the independent lender segment with digital-first underwriting specialization.
| Leading Market Players |
|---|
| Toyota Financial Services |
| Volkswagen Financial Services |
| Ford Motor Credit Company |
| Ally Financial |
| Bank of America |
| GM Financial |
| Capital One Auto Finance |
| Daimler Financial Services |
| JPMorgan Chase |
| Others |
Cost & Logistics Intelligence
Shanghai's captive finance digital platforms anchor the world's largest EV leasing infrastructure, channeling battery cost curve improvements into competitive rate positioning that compresses margins for European and North American originators. Their scale economics in cell chemistry procurement and residual value modeling create pricing power that downstream fleet operators and individual buyers cannot easily circumvent.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European automotive financing, separating premium zero-emission lease products from standard internal-combustion installment loans and economy-tier used-vehicle refinancing. Certification level under EU AI Act risk classification frameworks and brand premium from established captive arms drive price differentiation, while lithium carbonate price volatility intensifies cost compression in EV-specific products. Fleet operators exhibit the highest price sensitivity due to total cost of ownership scrutiny, whereas individual premium segment buyers show least sensitivity when bundled charging and maintenance services are included.
Supply Chain Analysis
Extended payment terms from Korean and Chinese battery cell manufacturers to European and North American originators have become critical supply-chain finance facilities stabilizing working capital through input cost swings. Manufacturing concentration in China, South Korea, and Japan feeds global cell capacity, with lithium carbonate, nickel sulfate, and cobalt hydroxide as anchor raw material dependencies. Single-source vulnerability around cathode active material supply creates structural risk, while distribution runs through captive finance arms integrated with OEM assembly clusters rather than independent wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive financing faces substitution pressure from mobility-as-a-service platforms that bundle vehicle access without traditional credit intermediation, forcing originators to defend their core position against disintermediation.
For Market Incumbents: Entrench residual value expertise through backward integration into battery health analytics and telematics data capabilities, countering the threat from digital-native subscription platforms. Secure charging infrastructure partnerships to bundle mobility services that standalone finance providers cannot replicate, while deepening cell chemistry forecasting capabilities to maintain underwriting precision against emerging algorithmic competitors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors where localized captive finance arms remain underdeveloped for two-wheeler and entry-level passenger vehicle segments. Target price-sensitive first-time buyers in tier-2 and tier-3 cities underserved by established originators, deploying alternative data-driven underwriting that bypasses traditional credit bureau dependencies. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy automakers spinning off financial services divisions to focus on core manufacturing, particularly those with stranded ICE-era residual value models requiring transformation. Monitor battery second-life valuation methodologies as the inflection indicator for long-term viability across the projection horizon, assessing whether collateral value streams from vehicle-to-grid integration materialize as projected.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cell chemistry access that anchors residual value confidence for EV lease underwriting. |
| Software-Defined Vehicle Investment | Enables real-time telematics integration for dynamic usage-based pricing models. |
| Charging Infrastructure Partnership | Creates bundled mobility offerings that corporate procurement departments now prioritize. |
| Geographic Manufacturing Footprint | Aligns captive finance arms with PLI scheme incentives in India and dual carbon policy in China. |
| Platform Standardization | Reduces origination costs across EU Green Deal compliance mandates and California ACT regulations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC asset-backed securitization filings, ECB monetary policy transmissions, and vehicle registration databases. Interviews with captive finance risk officers, OEM platform engineers, dealership operations managers, and fleet procurement directors informed underwriting model assessments. Secondary validation drew from IHS Markit production data, Truth in Lending Act enforcement records, and NEV credit trading system disclosures. Bottom-up lease portfolio analysis and top-down central bank rate trajectory modeling provided triangulation across the analysis window.
Forecast inputs include propulsion architecture transitions, residual value confidence intervals, and regulatory compliance cost curves across the modeling period. Segmentation dimensions span financing type, customer tier, vehicle technology, and regional production cluster. CAGRs were derived from scenario-weighted projections of electrification penetration and interest rate normalization. Battery cost curve trajectories and charging infrastructure deployment pace served as industry-specific forecast inputs.
Stress conditions across lithium carbonate price bands, ECB rate trajectories, and EU AI Act implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cell chemistry degradation curves and telematics adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Europe Car Loan Market