
 E-Scooter Financing Market | 2026-2036
E-Scooter Financing Market Size, Share, and Industry Trends Forecast 2026-2036
E-Scooter Financing Market Foresight
The EU Green Deal is pivoting urban mobility procurement across European capitals toward electrified last-mile transport. Ola Electric leverages its integrated mobile-app platform to bundle vehicle sales with subscription financing in Indian metro corridors. Ather Energy differentiates through captive lease products tied to proprietary charging infrastructure. NIU Technologies anchors its European expansion through retail-store partnerships with localized installment schemes.
E-scooter financing encompasses credit instruments and structured payment vehicles that enable consumer or fleet acquisition of electric two-wheelers, typically spanning battery capacity thresholds of 2-4 kWh and motor ratings between 2-6 kW. Lease structures dominate institutional fleet deployment where asset depreciation schedules align with municipal procurement cycles, while installment payment products capture individual buyers through mobile-app onboarding with automated credit scoring. Subscription models represent the fastest-growing segment as they bundle maintenance plans and battery swap access into recurring revenue streams.
India's RBI governs non-banking financial company licensing for digital lenders such as Klarna and Affirm when they partner with domestic OEMs, while the EU AI Act imposes algorithmic transparency requirements on automated credit decisions for cross-border financing platforms. The F-Gas Regulation indirectly shapes battery thermal management standards that influence insurance underwriting and residual value calculations in European lease contracts. Stakeholders must monitor how central bank rate trajectories reshape consumer monthly payment affordability against backdrop of OEM captive finance arms gaining share from independent lenders.
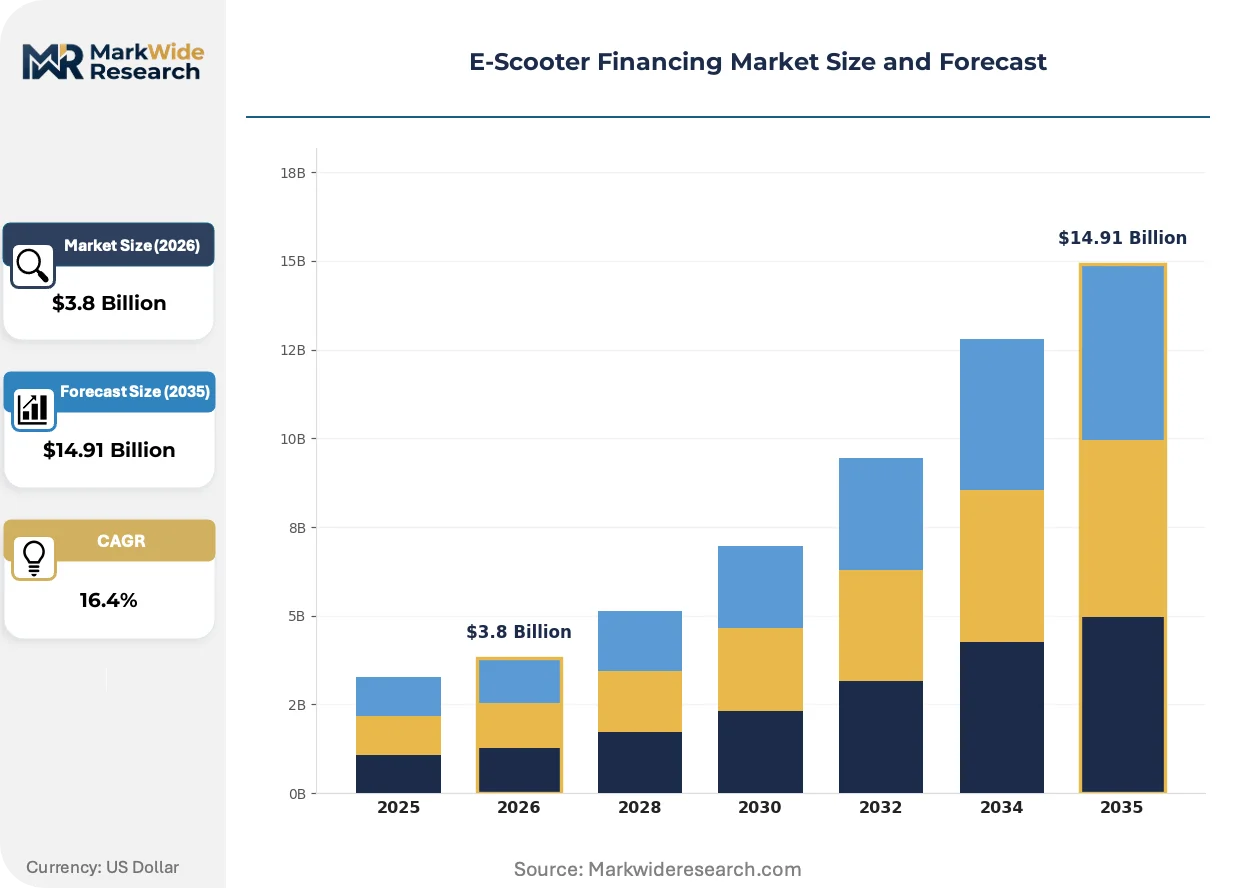
Market Dynamics
Battery-as-a-service leasing models are compressing upfront acquisition costs and shifting residual value risk from consumers to OEM captive finance arms, fundamentally restructuring how electric two-wheelers reach urban commuters.
Growth Catalysts
- EU Green Deal procurement mandates:Municipal fleets across European capitals must electrify last-mile transport, creating guaranteed demand pools for financed e-scooter deployment.
- Congestion pricing zones:London, Paris, and Singapore impose daily charges on internal combustion vehicles, pushing commuters toward subscription-financed electric alternatives.
- Automated credit scoring:Mobile-app onboarding with algorithmic underwriting reduces origination friction and expands addressable borrower pools beyond traditional credit profiles.
Market Restraints
- Lithium carbonate price volatility:Battery pack costs fluctuate with raw material markets, complicating lease residual value calculations and insurance underwriting.
- Charging infrastructure gaps:Inadequate grid density in secondary Indian cities limits subscription model viability outside metro corridors.
- F-Gas Regulation compliance costs:European thermal management standards raise battery system engineering expenses, pressuring lease rate competitiveness.
Strategic Opportunities
- Indonesian archipelago expansion:Island economies with high two-wheeler penetration and limited banking infrastructure present white space for mobile-first financing.
- Corporate mobility-as-a-benefit:Employers in Germany and the Netherlands subsidize e-scooter subscriptions as tax-advantaged commuter perks.
- Interoperable battery swap networks:Standardized form factors across OEMs would unlock cross-brand subscription portability and reduce customer lock-in concerns.
Industry Challenges
- Embedded software talent scarcity:Firmware engineers capable of integrating telematics with automated underwriting pipelines command premium compensation.
- Algorithmic audit compliance:The EU AI Act mandates explainability documentation for credit decisions, extending model validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Scooter Financing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Lease, Loan, Installment Payment, Subscription Consumer Segment: Students, Professionals, Eco-conscious Users, Urban Commuters Platform Type: Online Marketplace, Retail Store, Mobile App, Direct Sales Support Service: Maintenance Plans, Insurance, Customer Support, Payment Management |
| Companies Covered | Affirm, Klarna, Katapult, TVS Motor Company, Bajaj Auto Ltd., Ola Electric, Ather Energy, Yadea Technology Group, NIU Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Scooter Financing Market Shifts & Advancements
Telematics integration is collapsing the distinction between asset financing and mobility service provisioning, enabling real-time usage-based pricing and predictive maintenance bundling.
Embedded IoT hardware is unifying vehicle connectivity with payment infrastructure. Fleet operators in Singapore and Barcelona deploy always-connected scooters that transmit ride data directly to financing platforms. This architecture compresses default detection cycles from months to hours, allowing dynamic interest rate adjustments based on actual utilization patterns rather than static credit scores.
The EU AI Act imposes algorithmic transparency requirements on automated credit decisions for cross-border financing platforms. Lenders operating in multiple European jurisdictions must maintain auditable decision trails and human override capabilities. German and French regulators are interpreting these provisions most strictly, creating compliance complexity for digital-native lenders seeking continental scale.
Subscription bundling is displacing outright purchase preference among urban millennials. Individual buyers in Indian metro corridors increasingly favor all-inclusive monthly plans covering maintenance, insurance, and battery swaps over installment loans with residual ownership risk. This behavioral pivot concentrates demand with OEMs possessing captive service infrastructure rather than independent finance providers.
E-Scooter Financing Market Segmentation
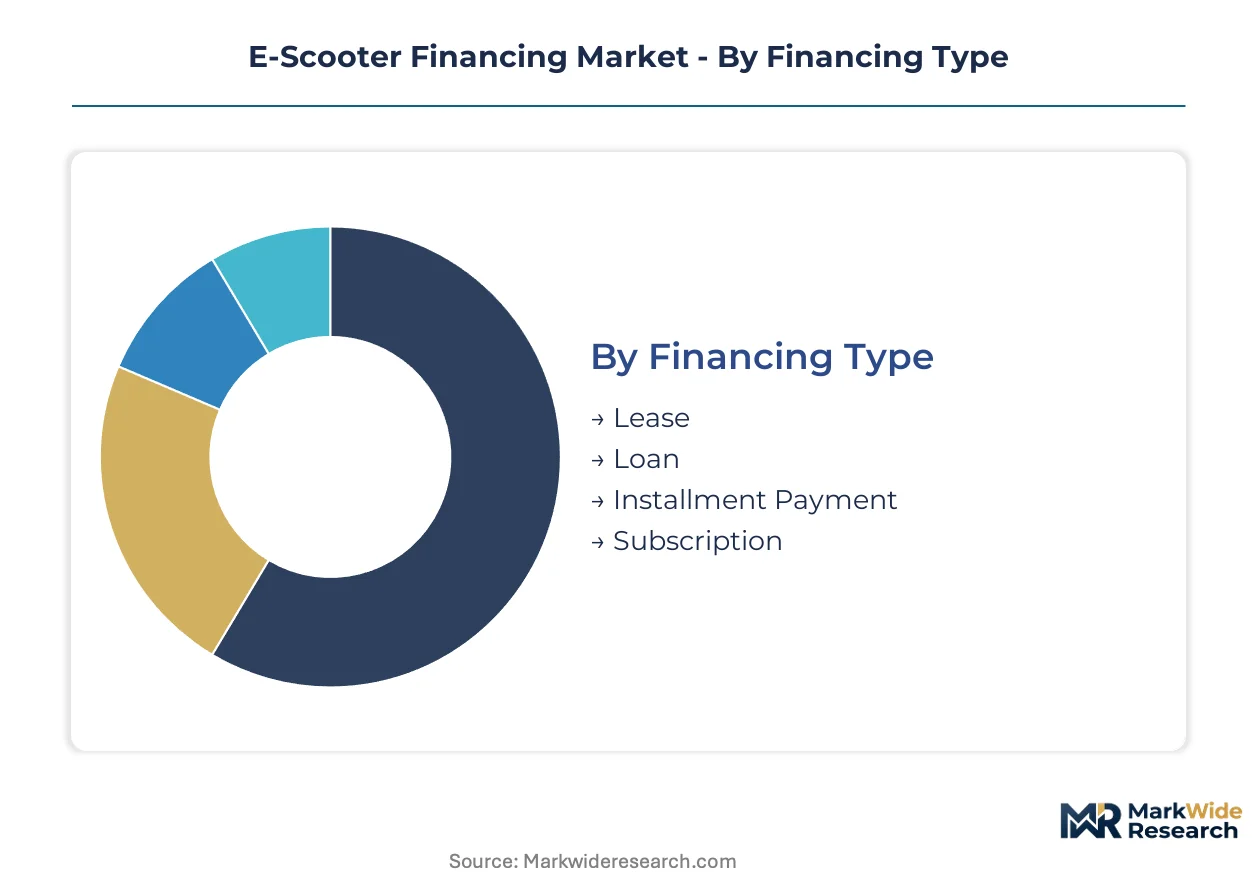
Financing modality selection directly shapes customer acquisition costs and lifetime value for e-scooter providers. Each segment category reflects distinct risk-return profiles that influence underwriting automation and service bundling strategies across urban mobility corridors.
Financing Type:
Upfront capital commitment thresholds determine which financing vehicles attract which buyer profiles.
- Lease:Structured agreements transfer residual value risk to captive finance arms while preserving fleet flexibility for municipal procurement cycles. London and Paris municipal tenders favor lease structures that align depreciation schedules with contract durations.
- Subscription:All-inclusive monthly bundles covering maintenance, insurance, and battery swaps are capturing urban millennials who reject ownership risk. Indian metro corridors show strongest concentration where Ola Electric and Ather Energy bundle charging infrastructure access.
- Loan:Traditional installment products with fixed amortization schedules appeal to credit-established buyers seeking asset ownership.
- Installment Payment:Short-term structured payments without formal credit bureau reporting expand addressable pools among thin-file borrowers.
Lease leads on scale; subscription leads on momentum.
Consumer Segment:
Mobility behavior patterns and price sensitivity vary sharply across demographic cohorts.
- Urban Commuters:Daily trip reliability requirements drive preference for subscription models with guaranteed battery swap access. Singapore congestion pricing enforcement pushes this segment toward financed electric alternatives fastest.
- Professionals:Employer-subsidized mobility benefits in Germany and the Netherlands create tax-advantaged demand pools with lower default risk profiles.
- Students:Budget constraints and limited credit histories favor micro-installment products with parental guarantee structures.
- Eco-conscious Users:Sustainability preference premiums support higher monthly payments when carbon impact transparency is embedded in financing terms.
Urban commuters concentrate volume; professionals concentrate margin.
Platform Type:
Distribution channel selection determines origination friction and customer lifetime value capture.
- Mobile App:Automated credit scoring and digital onboarding compress approval cycles to minutes. Indian digital lenders leverage RBI-licensed NBFC partnerships to embed financing directly into OEM purchase flows.
- Retail Store:Physical touchpoints enable test rides and documentation assistance for less digitally fluent buyers. NIU Technologies anchors European expansion through localized installment schemes at partner locations.
- Online Marketplace:Comparison shopping interfaces aggregate multiple lender offers but increase customer acquisition costs through platform fees.
- Direct Sales:OEM-controlled channels maximize margin retention and service bundling attach rates.
Mobile app dominates origination velocity; retail store dominates conversion in secondary cities.
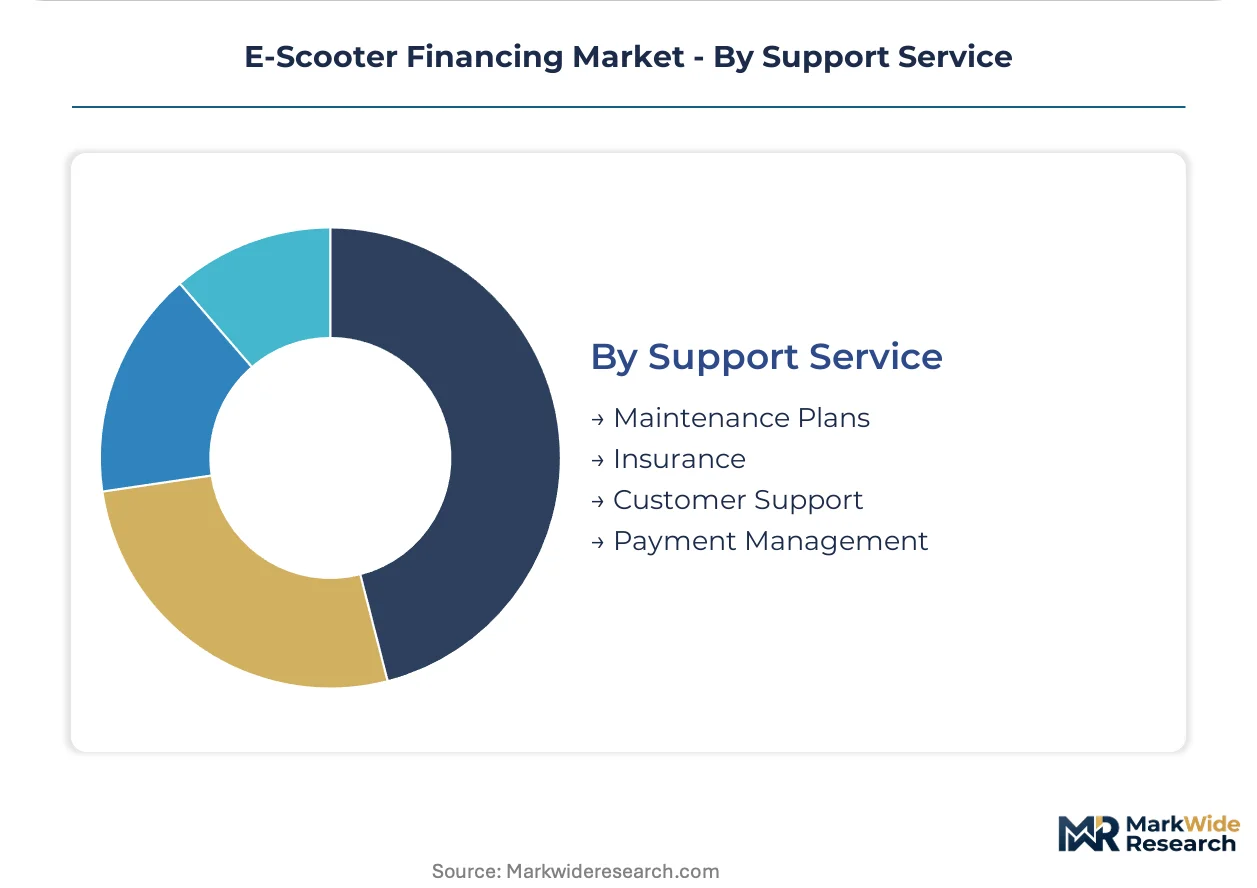
Support Service:
Ancillary service bundling differentiates commodity financing and reduces churn.
- Maintenance Plans:Predictive service scheduling based on telematics data lowers total cost of ownership and supports residual value guarantees.
- Insurance:Embedded coverage products address theft and accident risks that otherwise deter financing uptake among risk-averse segments.
- Payment Management:Flexible due-date adjustments and skip-a-month features reduce delinquency rates among gig-economy income earners.
- Customer Support:Multilingual helplines and chatbot interfaces influence satisfaction scores and repeat purchase intent.
Maintenance plans drive retention; insurance unlocks financing for risk-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The e-scooter financing industry traces its commercial roots to Chinese manufacturing clusters that scaled electric two-wheeler production through the 2010s, with financing models later migrating to India and Europe as urban electrification policies accelerated adoption.
India
Metro corridor congestion and fuel price volatility drive commuter demand toward battery-as-a-service subscriptions. RBI licensing requirements for NBFC partnerships govern how digital lenders embed financing into OEM purchase flows. Bangalore and Mumbai concentrate captive finance arm development where Ola Electric and Ather Energy bundle charging infrastructure with subscription products.
China
Domestic e-scooter saturation has shifted financing focus toward export-oriented fleet leasing and Southeast Asian market expansion. MIIT battery safety standards and GB certification requirements shape residual value calculations for cross-border lease structures. The Yangtze River Delta manufacturing belt anchors production of telematics-integrated scooters that feed financing platforms across Asia-Pacific.
Germany
Employer-subsidized mobility benefits create tax-advantaged demand pools with lower default risk profiles than retail financing. KBA type-approval processes and EU AI Act algorithmic transparency requirements extend model validation timelines for automated credit decisions. Berlin and Hamburg municipal procurement cycles favor lease structures aligned with depreciation schedules for fleet electrification mandates.
Singapore
Congestion pricing enforcement and limited parking availability push commuters toward subscription-financed electric alternatives fastest among Asian cities. LTA vehicle approval frameworks and strict safety inspection regimes influence insurance underwriting and lease rate competitiveness. The city-state's dense urban core enables battery swap network viability that supports all-inclusive monthly bundles.
United States
Thin-file borrower expansion and gig-economy income volatility drive demand for alternative credit scoring in installment products. CFPB oversight of buy-now-pay-later providers and state-level usury caps constrain pricing flexibility for digital-native lenders. California and New York metro areas concentrate fintech-OEM partnerships experimenting with usage-based financing tied to telematics data.
E-Scooter Financing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling depth and captive infrastructure control. The market structures around three tiers: OEM-integrated finance arms with proprietary charging networks, independent fintech platforms with algorithmic underwriting scale, and legacy two-wheeler manufacturers extending installment products through dealer networks. Consolidation pressure runs through strategic partnerships between battery swap operators and financing platforms, alongside vertical integration moves by vehicle manufacturers into captive leasing.
Within the fintech platform tier, Affirm and Klarna exemplify algorithmic underwriting specialists that partner with domestic OEMs under RBI NBFC licensing frameworks in India. Among legacy two-wheeler manufacturers with finance extensions, TVS Motor Company and Bajaj Auto Ltd. occupy positions bridging dealer-network installment products toward subscription model experimentation. These five entities represent the dominant competitive archetypes without exhausting the market's structural diversity.
| Leading Market Players |
|---|
| Affirm |
| Klarna |
| Katapult |
| TVS Motor Company |
| Bajaj Auto Ltd. |
| Ola Electric |
| Ather Energy |
| Yadea Technology Group |
| NIU Technologies |
| Others |
Supply & Pricing Matrix
A sharp bifurcation between subscription-financed premium tiers and installment-driven economy tiers reshapes both pricing power and sourcing strategies across the e-scooter financing value chain. Premium subscription bundles command pricing leverage through captive charging infrastructure and battery-swap guarantees, while economy installment products compete on origination efficiency and thin-file credit automation.
Pricing Analysis
Subscription-based pricing with bundled maintenance and battery access dominates the premium urban commuter segment, separating Ola Electric and Ather Energy's captive offerings from independent fintech installment products. Price differentiation rests on charging network density and telematics integration depth rather than hardware specifications alone. Cost compression in economy tiers intensifies as lithium carbonate volatility squeezes lease residual value margins. Students and gig-economy workers show highest price sensitivity, while employer-subsidized professionals in Germany tolerate premium monthly rates.
Supply Chain Analysis
India's PLI scheme and local-content mandates for battery cell production are reshaping sourcing patterns for financing platforms dependent on domestic OEM partnerships. Manufacturing concentrates in China's Yangtze River Delta, India's Bangalore-Chennai corridor, and Vietnam's emerging two-wheeler assembly zones. Lithium-ion cells, permanent magnet motors, and telematics control units constitute critical input dependencies. Single-source vulnerability in battery cell supply creates underwriting risk for long-dated lease contracts. Distribution runs through OEM-integrated mobile apps in metro corridors and retail store partnerships in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-scooter financing functions as a stable compounder where urban electrification policy creates predictable demand expansion across municipal procurement and commuter subscription segments.
For Market Incumbents: To counter fintech algorithmic underwriting speed, deepen captive infrastructure moats through proprietary battery-swap network expansion in Indian and Southeast Asian metro corridors. Prioritize telematics-integrated risk scoring that compresses default detection cycles below independent lender capabilities. Lock municipal lease contracts through depreciation-aligned tender structures in EU Green Deal procurement cycles. For New Entrants and Emerging Players: Algorithmic credit scoring for thin-file gig-economy workers offers the most penetrable wedge in Indonesian archipelago markets and secondary Indian cities lacking banking infrastructure. Target employer-subsidized mobility benefits in the Netherlands and Germany where tax advantages lower customer acquisition costs. Deploy mobile-first onboarding with localized language interfaces to bypass incumbent retail store networks. For Investors and Strategic Acquirers: Consolidation pressure builds where battery-swap operators lack financing platform integration and OEM captive arms seek geographic expansion capabilities. Frame five-to-ten-year viability around subscription revenue predictability and residual value risk management infrastructure. Watch algorithmic audit compliance costs under EU AI Act implementation as margin compression signal for cross-border digital lenders.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swap Network Expansion | Captive infrastructure locks subscription customers through guaranteed swap access in dense urban cores. |
| Telematics-Integrated Underwriting | Real-time ride data enables dynamic pricing and predictive default detection beyond static credit scores. |
| Employer Mobility Benefit Partnerships | Tax-advantaged corporate programs in Germany and Netherlands create lower-risk origination channels. |
| Algorithmic Compliance Investment | EU AI Act audit trail capabilities become competitive barrier for cross-border financing scale. |
| Secondary City Retail Penetration | Physical touchpoints unlock installment conversion where mobile-app literacy lags metro corridors. |
Research Methodology
Direct dialogue with captive finance executives at Ola Electric and Ather Energy, fintech platform risk officers, RBI regulatory consultants, and EU mobility procurement directors grounded the qualitative foundation. Secondary validation drew from RBI NBFC licensing circulars, EU AI Act implementation guidance, LTA vehicle approval frameworks, and municipal tender documents from London, Paris, and Singapore. Bottom-up subscription volume modeling and top-down financing penetration rates triangulated market sizing across the analysis window.
Segment-level projections spanning lease, subscription, loan, and installment modalities integrated with consumer archetype penetration curves and platform-type origination velocity assumptions. CAGRs derived from battery cost trajectory modeling, congestion pricing policy adoption timelines, and telematics hardware deployment curves. Charging infrastructure density thresholds and algorithmic credit decision automation rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price volatility, central bank rate trajectories, and EU AI Act enforcement variance across member states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
Loan Servicing Software Market