
 Truck Financial Leasing Market | 2026-2036
Truck Financial Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Financial Leasing Market Insights
Market Context with Strategic Players
The capital-intensity divergence between captive finance arms and independent lessors is rotating competitive advantage toward balance-sheet scale. PACCAR Financial leverages its manufacturer-captive structure to sustain below-market residual risk pricing across North American dealer networks. Ryder System anchors its position through full-service fleet management integration, while Bank of America Corporation competes via diversified commercial lending platforms that extend credit to mid-market freight operators.
Technical Definition and Structural Segments
Truck financial leasing constitutes a capital equipment financing mechanism where lessors retain asset ownership while lessees obtain use rights through fixed or variable payment schedules, typically structured around residual value guarantees and mileage thresholds. The instrument serves commercial freight operators seeking to preserve liquidity, manage balance-sheet leverage, and transfer obsolescence risk for Class 3-8 vehicles. Finance lease structures dominate transaction volume among large freight carriers pursuing ownership pathways, while operating leases attract logistics providers prioritizing fleet refresh cycles and maintenance bundling. Heavy duty trucks command the deepest residual value pools, though specialized trucks in refrigerated and flatbed configurations differentiate margin capture for lessors with appraisal expertise.
Regulatory Frame and Forward-Looking Close
The EPA and NHTSA coordinate greenhouse gas emissions standards and fuel economy mandates that compress truck replacement cycles, indirectly stimulating lease origination as operators seek compliant assets without ownership commitment. The Federal Reserve's interest rate posture shapes lease pricing spreads and residual value assumptions across the credit spectrum. Stakeholders must monitor how CARB's Advanced Clean Trucks rule propagates to other state jurisdictions and whether captive finance arms absorb regulatory compliance costs or pass them through lease rate adjustments.
Market Dynamics
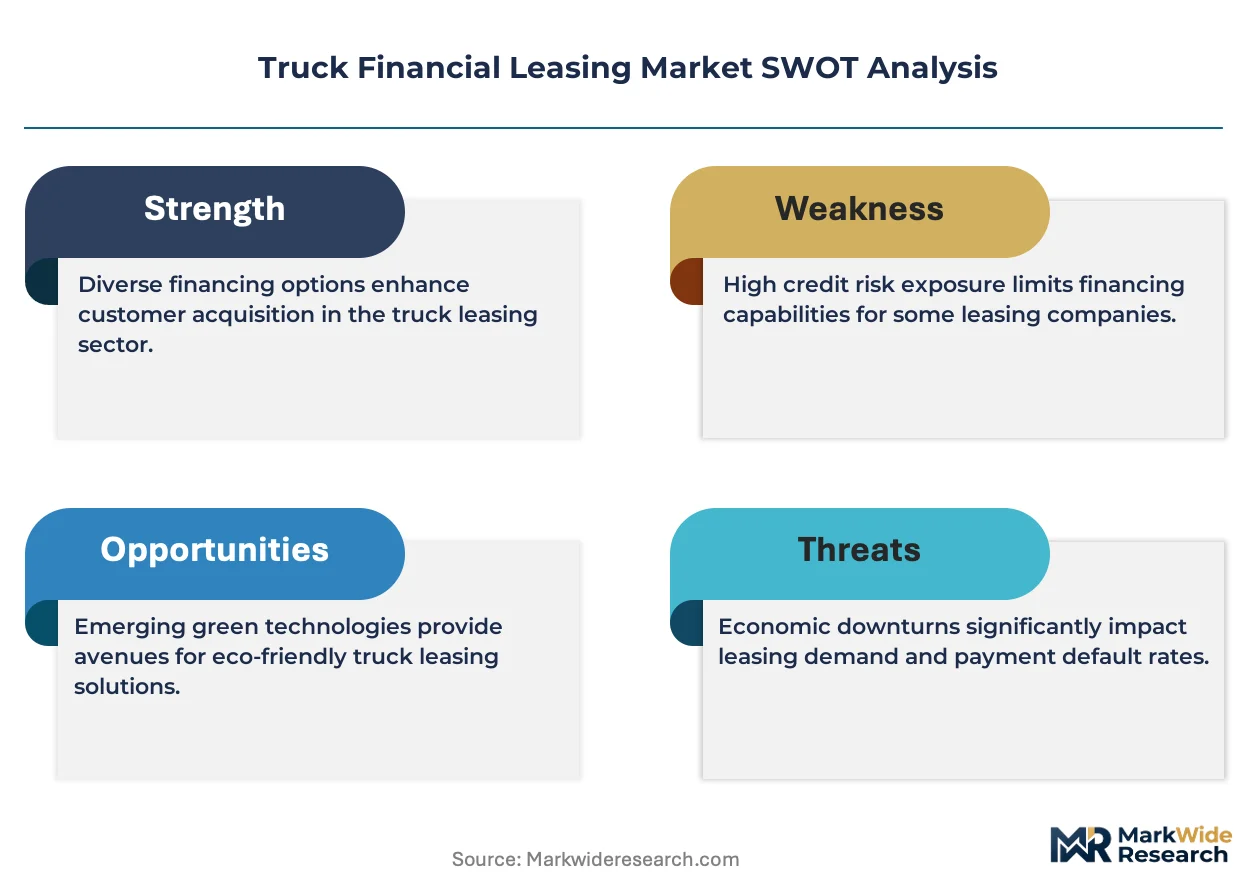
Residual value volatility in Class 8 sleeper cabs is compressing lease tenors and forcing lessors to embed mileage-adjustment clauses that transfer depreciation risk back to freight operators.
Growth Catalysts
- EPA Phase 3 Standards:The rule tightens carbon dioxide limits for heavy-duty vehicles starting model year 2027. Fleet operators facing forced obsolescence of pre-compliant assets prefer operating leases to avoid stranded-equity risk.
- Midwest distribution hub expansion:E-commerce fulfillment centers around Columbus, Indianapolis, and Kansas City require flexible fleet scaling. Regional lessors capture origination volume through short-term lease structures matched to seasonal demand spikes.
- Telematics integration:Real-time engine diagnostics and predictive maintenance algorithms reduce unplanned downtime. Lessors bundle sensor hardware into lease rates, creating sticky service relationships with small-fleet owner-operators.
Market Restraints
- Steel and aluminum input volatility:Cab and chassis manufacturing costs fluctuate with commodity indices. Lessors with fixed-rate lease backlogs absorb margin compression when raw material prices spike without contract pass-through mechanisms.
- Residual value model uncertainty:Battery-electric truck depreciation curves lack historical data. Captive finance arms face balance-sheet risk if remarketing values for electric Class 8 tractors fall below guaranteed residual thresholds.
- CARB Advanced Clean Trucks rule:California's mandate for zero-emission vehicle sales percentages creates compliance complexity for interstate operators. Lease structures must accommodate geographic restrictions that limit asset deployment flexibility.
Strategic Opportunities
- Refrigerated trailer electrification:Transport refrigeration unit battery packs enable cold-chain operators to meet emissions rules without full tractor replacement. Lessors can structure equipment-only leases for reefer units decoupled from powertrain financing.
- Texas freight corridor density:The I-35 and I-10 intersection anchors cross-border trade with Mexico. Bilingual servicing networks and peso-denominated lease payment options penetrate underbanked regional carriers.
- Section 179 accelerated depreciation:The US tax code provision allows immediate expensing of qualifying equipment purchases. Finance lease structures that transfer ownership at term end let lessees capture deduction benefits while preserving lender-of-record relationships.
Industry Challenges
- Diesel technician shortage:Maintenance bundling in full-service leases requires skilled labor pools that freight-dependent regions lack. Lessors face service-level penalties when repair backlogs extend vehicle downtime beyond contract thresholds.
- Interoperability gaps in telematics platforms:Proprietary data formats from engine manufacturers prevent unified fleet management dashboards. Lessees operating mixed-brand trucks under single lessor contracts encounter reporting fragmentation that undermines efficiency claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Financial Leasing Market |
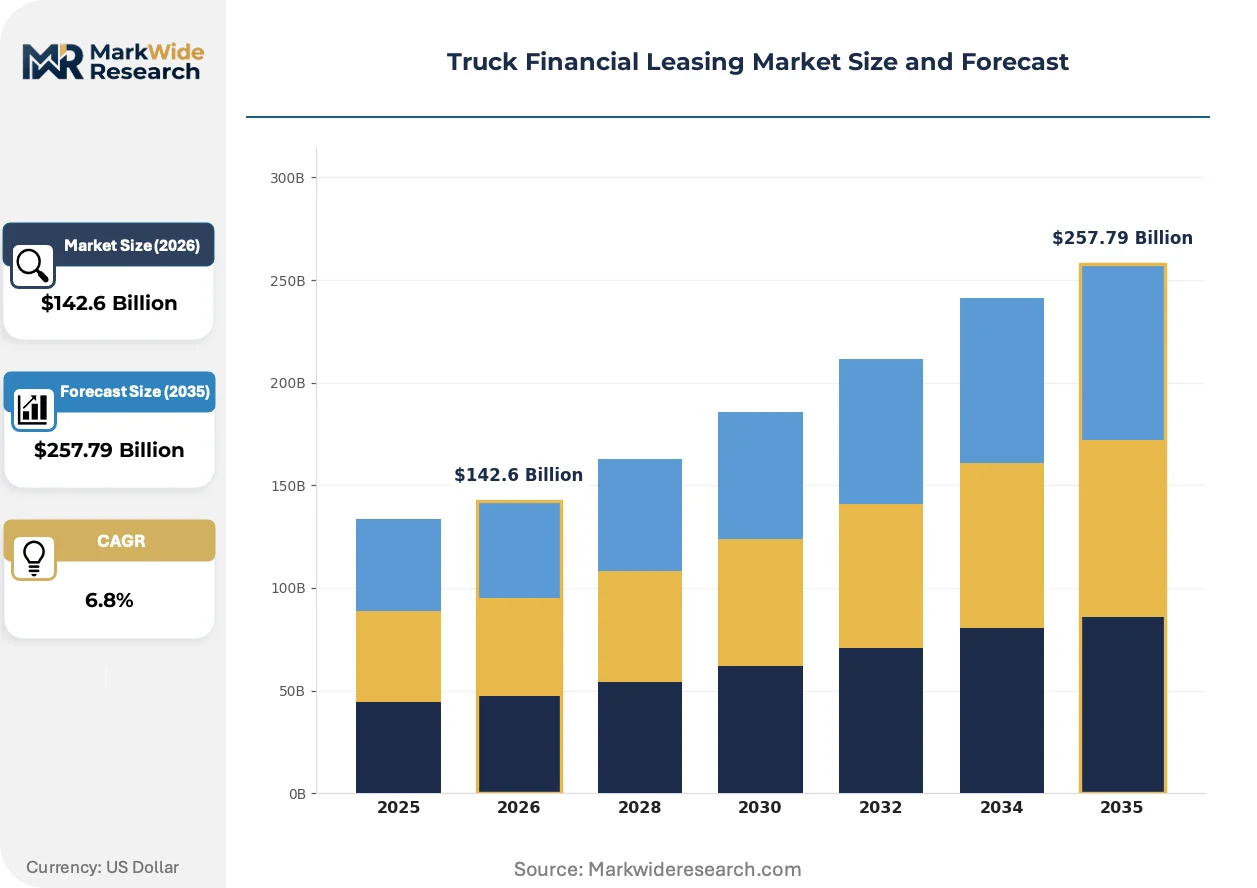
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lease Type: Operating Lease, Finance Lease, Sale and Leaseback, Closed-End Lease End User: Logistics Providers, Freight Carriers, Construction Companies, Independent Truckers Truck Type: Light Duty Trucks, Medium Duty Trucks, Heavy Duty Trucks, Specialized Trucks Contract Duration: Short-Term, Medium-Term, Long-Term, Flexible Term |
| Companies Covered | Ally Financial Inc., Bank of America Corporation, Penske Truck Leasing, Ryder System, PACCAR Financial, Daimler Truck Financial Services, Volvo Financial Services, Toyota Financial Services, JPMorgan Chase Commercial Vehicle Finance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Financial Leasing Market Trends and Innovations
Telematics-enabled usage-based pricing is collapsing the traditional fixed-payment lease model, creating real-time cost alignment between asset utilization and capital charges that legacy contract structures cannot match.
Battery-electric powertrains are displacing diesel-electric hybrid configurations in Class 8 regional haul applications. Grocery and beverage distributors with predictable return-to-base routes are adopting electric tractors at the fastest clip. This displacement is compressing residual value forecasts for internal combustion assets and accelerating lessor portfolio rebalancing toward zero-emission equipment.
EPA and NHTSA coordinated rulemaking on greenhouse gas emissions and fuel economy standards is tightening truck replacement cycles. The regulatory pressure forces fleet managers to retire assets earlier than historical economic life assumptions. Heavy-duty segments serving California and the fourteen states adopting CARB standards face the most acute compliance timelines and are migrating toward shorter-term operating leases.
Freight procurement through digital load-matching platforms is fragmenting shipper-carrier relationships. Small fleet operators now secure spot-market capacity through smartphone applications rather than long-term contracts. This behavioral shift concentrates in the spot-van markets of the Southeast and Midwest, where lease originators must structure payment flexibility around income volatility that annual-mileage guarantees cannot accommodate.
Truck Financial Leasing Market Segmentation
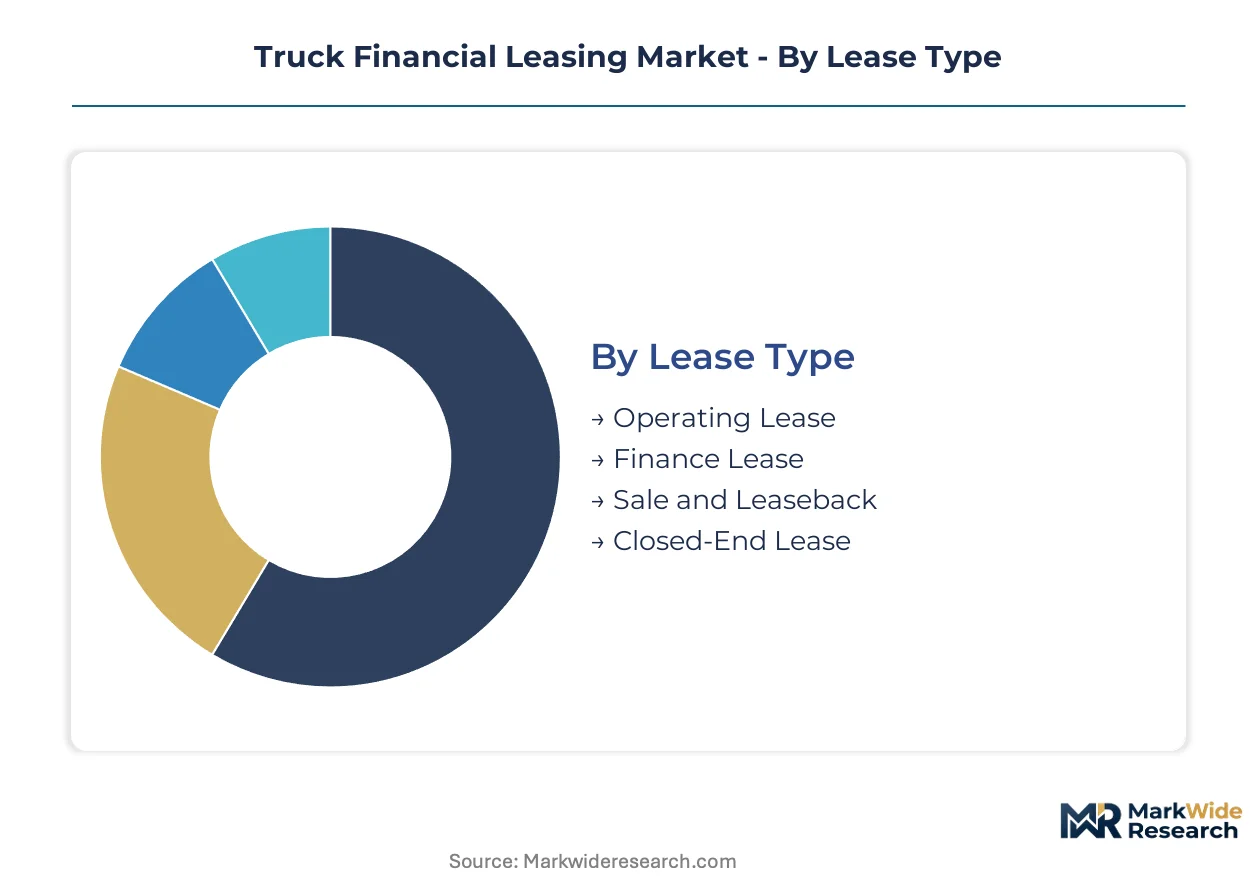
Lease structure selection determines balance-sheet treatment and tax positioning for commercial fleet operators. Truck classification and contract duration interact with EPA emissions compliance timelines to shape residual value risk allocation between lessors and lessees.
Lease Type:
EPA Phase 3 standards and CARB's Advanced Clean Trucks rule are bifurcating lease demand toward structures that transfer regulatory obsolescence risk away from fleet operators.
- Operating Lease:Lessors retain ownership and residual value exposure while lessees obtain use rights without balance-sheet capitalization. Logistics providers across the Texas freight corridor favor this structure to preserve working capital and accelerate fleet refresh cycles ahead of emissions mandates.
- Finance Lease:Transfers substantially all ownership risks and rewards to the lessee, typically with a nominal purchase option at term end. Large freight carriers in the Midwest distribution hub cluster deploy this instrument to capture Section 179 depreciation benefits while maintaining lender relationships.
- Sale and Leaseback:Operators monetize owned fleet assets to unlock liquidity, then lease back the same equipment under fixed payment schedules. Construction companies facing equipment-intensive project cycles utilize this structure to reallocate capital toward labor and materials procurement.
- Closed-End Lease:Fixed residual value guarantees eliminate lessee exposure to remarket volatility at contract conclusion. Independent truckers with limited balance-sheet capacity prefer the payment predictability this structure provides against fluctuating spot-market rates.
Operating leases handle the majority of throughput; sale and leaseback structures are expanding most quickly as asset-heavy operators seek liquidity extraction.
End User:
Working capital intensity and route predictability determine which user categories prioritize maintenance bundling versus ownership pathways.
- Logistics Providers:Third-party fulfillment and last-mile delivery operators with seasonal volume spikes require fleet elasticity. E-commerce fulfillment centers around Columbus and Indianapolis drive demand for short-term lease structures matched to peak shipping windows.
- Freight Carriers:Long-haul and regional trucking companies with dedicated contract lanes favor longer tenors and mileage-based pricing. Cross-border operators on the I-35 corridor face CARB compliance complexity that pushes leasing over ownership for California-accessible assets.
- Construction Companies:Project-based equipment needs with intermittent utilization patterns favor flexible-term structures. Heavy-duty vocational trucks for earthmoving and material transport concentrate lease demand in Texas and Gulf Coast infrastructure corridors.
- Independent Truckers:Owner-operators with limited credit access and volatile income streams require low-entry-cost lease products. Digital load-matching platforms have fragmented their revenue stability, forcing lessors to embed payment forbearance clauses.
Freight carriers dominate transaction volume; logistics providers are climbing the fastest on share as e-commerce fulfillment expands.
Truck Type:
Powertrain technology transitions and residual value uncertainty are reshaping segment concentration within lessor portfolios.
- Heavy Duty Trucks:Class 8 tractors and sleeper cabs command the deepest residual value pools and most sophisticated appraisal expertise. Battery-electric powertrains in regional haul applications are displacing diesel-electric hybrids, compressing depreciation forecasts for internal combustion assets.
- Specialized Trucks:Refrigerated, flatbed, and tanker configurations differentiate margin capture through equipment-specific knowledge. Transport refrigeration unit electrification enables cold-chain operators to meet emissions rules without full tractor replacement.
- Medium Duty Trucks:Class 4-7 vehicles serve urban delivery and final-mile applications with shorter route profiles. Predictable return-to-base patterns make this segment the entry point for electric powertrain adoption among grocery and beverage distributors.
- Light Duty Trucks:Class 1-3 vehicles support service trades and small-scale cargo transport with lower capital thresholds. Independent contractors and last-mile delivery platforms generate origination volume through high-turnover fleet refresh programs.
Heavy duty trucks anchor lessor balance sheets; specialized trucks are gaining share fastest through electrification-driven equipment differentiation.
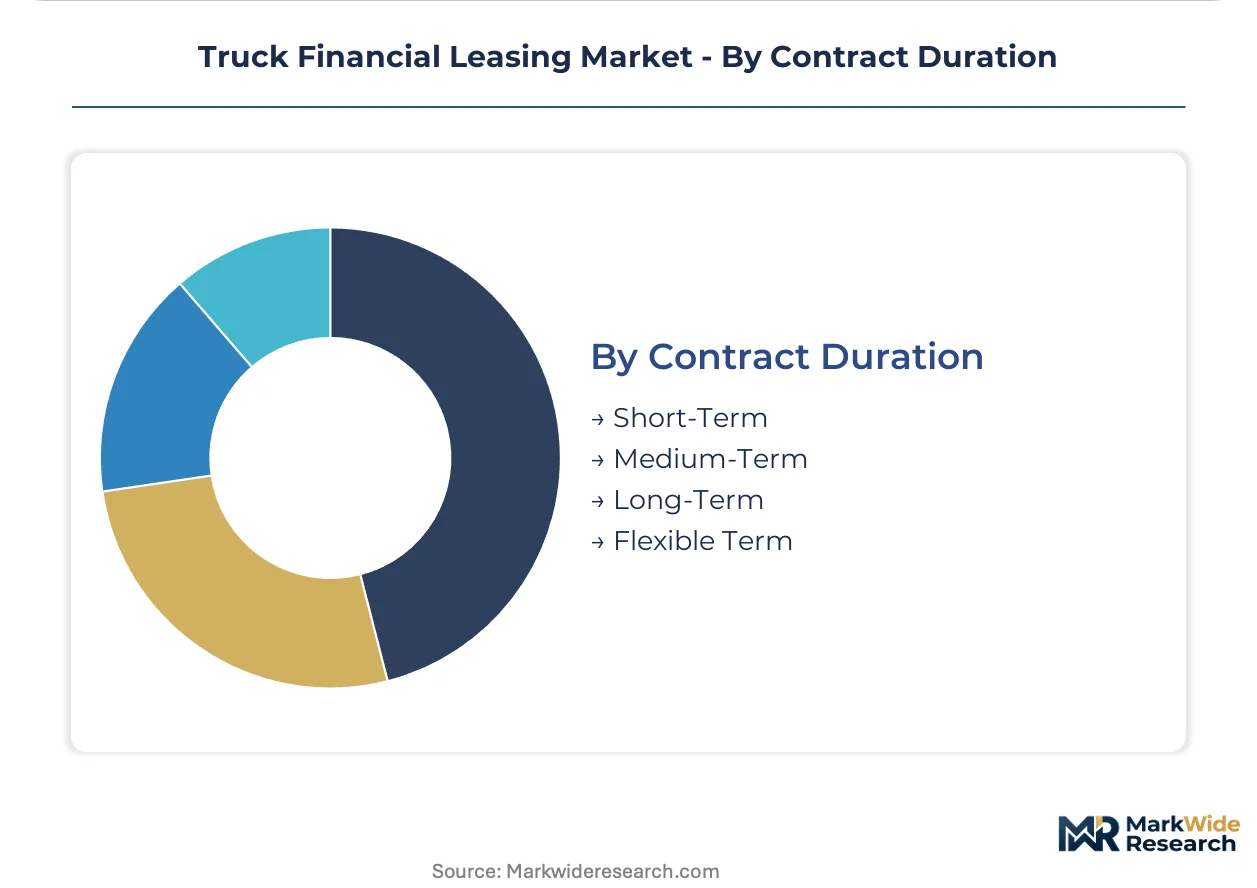
Contract Duration:
Regulatory compliance timelines and residual value volatility are compressing average lease tenors across all truck categories.
- Short-Term:Contracts under 24 months enable rapid fleet scaling for seasonal demand spikes and pilot programs for zero-emission equipment. Regional lessors around Kansas City capture volume through structures matched to e-commerce fulfillment seasonality.
- Medium-Term:Two-to-five year structures balance payment affordability against residual value forecasting horizon. This duration dominates finance lease originations where ownership transfer at term end aligns with depreciation capture strategies.
- Long-Term:Extended tenors beyond five years concentrate among large freight carriers with dedicated contract lanes and predictable utilization profiles. EPA emissions standards are shortening economic viability of assets under these contracts, forcing renegotiation clauses.
- Flexible Term:Mileage-adjusted or revenue-linked payment schedules accommodate income volatility for spot-market operators. Telematics integration enables real-time usage-based pricing that collapses traditional fixed-payment models.
Medium-term contracts handle the majority of origination volume; flexible term structures are expanding most quickly as digital freight platforms fragment shipper-carrier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among freight operators varies sharply by geography, with emerging market lessees demanding shorter tenors and lower entry costs while North American carriers prioritize residual value guarantees and bundled maintenance contracts.
United States
EPA Phase 3 standards and CARB's Advanced Clean Trucks rule are compressing replacement cycles for Class 8 tractors. The Texas freight corridor along I-35 and I-10 anchors cross-border lease origination with Mexico, while Midwest distribution hubs around Columbus and Indianapolis drive seasonal fleet scaling demand.
Germany
The KBA enforces stringent emissions compliance timelines that accelerate fleet refresh decisions among Mittelstand freight carriers. The Rhine-Ruhr logistics cluster concentrates operating lease demand from third-party fulfillment operators serving pan-European e-commerce routes.
China
MIIT's dual carbon goals and GB standards for heavy-duty vehicle emissions are reshaping powertrain procurement patterns. The Yangtze River Delta manufacturing belt generates concentrated demand for medium-duty electric trucks in urban delivery applications.
India
RBI's regulatory framework for non-banking financial companies governs lease origination to credit-constrained owner-operators. The Delhi-Mumbai Industrial Corridor and Gujarat freight nodes concentrate demand for flexible-term structures matched to spot-market income volatility.
Japan
METI's carbon neutrality roadmap for commercial vehicles is accelerating pilot programs for battery-electric Class 4-7 trucks. The Chubu region around Nagoya anchors captive finance arm origination to automotive parts logistics providers with predictable return-to-base routes.
Truck Financial Leasing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with manufacturer-captive finance arms leveraging residual risk pricing advantages against independent lessors competing through service bundling and geographic density. The market structure favors balance-sheet scale and telematics integration capabilities. Three archetypes dominate: captive finance subsidiaries of truck OEMs, diversified commercial banking platforms, and pure-play fleet management specialists. Competitive moves concentrate on geographic expansion into high-growth freight corridors and portfolio diversification toward zero-emission equipment financing.
Within the captive finance tier, PACCAR Financial and Daimler Truck Financial Services exemplify manufacturer-integrated structures that absorb residual value risk across North American dealer networks. Bank of America Corporation occupies a position among diversified commercial lending platforms extending credit to mid-market freight operators, while Ryder System anchors the fleet management specialist archetype through full-service lease integration. These three entities represent distinct competitive vectors: manufacturing control, balance-sheet scale, and operational service density.
| Leading Market Players |
|---|
| Ally Financial Inc. |
| Bank of America Corporation |
| Penske Truck Leasing |
| Ryder System |
| PACCAR Financial |
| Daimler Truck Financial Services |
| Volvo Financial Services |
| Toyota Financial Services |
| JPMorgan Chase Commercial Vehicle Finance |
| Others |
Pricing and Supply Chain Analysis
Residual value pooling across captive finance networks concentrates pricing power among manufacturer-integrated lessors with direct access to dealer remarketing channels. Scale economies in fleet management systems compress per-unit servicing costs, forcing independent lessors to compete through payment flexibility rather than rate leadership.
Pricing Analysis
After-sales revenue from maintenance bundling and telematics subscriptions drives lifetime value capture in full-service lease structures. Pricing stratifies across premium, standard, and economy tiers based on residual value guarantee depth and mileage threshold stringency. Cost compression in short-term operating leases is intensifying because regional lessors absorb downtime risk without corresponding rate adjustments. Independent truckers exhibit highest price sensitivity, while large freight carriers prioritize residual value certainty over rate minimization.
Supply Chain Analysis
Steel mill capacity in the United States, Mexico, and Germany anchors cab and chassis manufacturing cost structures. Aluminum extrusions and high-strength steel alloys draw from commodity indices with limited contract pass-through mechanisms in fixed-rate lease backlogs. Single-source vulnerability concentrates in semiconductor components for engine control modules and telematics hardware. Distribution runs through captive dealer networks for manufacturer-integrated lessors, while independent lessors rely on third-party remarketing auctions and wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light logistics platforms threaten traditional fleet leasing by substituting spot-market capacity for dedicated equipment commitments, forcing incumbents to defend through service integration and balance-sheet scale.
For Market Incumbents: Secure telematics data exclusivity through OEM partnership agreements to prevent platform disintermediation. Captive finance arms should deepen residual value pooling across electric powertrain portfolios to offset battery depreciation uncertainty. Vertical integration into predictive maintenance software preserves service bundling premiums against independent telematics providers.
For New Entrants and Emerging Players: Payment forbearance products for digital load-matched owner-operators represent the most penetrable white-space segment, as incumbent lessors structure around annual-mileage guarantees ill-suited to spot-market income volatility. Bilingual servicing networks along the Texas-Mexico freight corridor capture origination volume from underbanked regional carriers. Go-to-market execution should embed revenue-linked lease structures with real-time payment adjustment triggers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management specialists with maintenance bundling penetration above sixty percent. Long-term viability favors lessors with demonstrated residual value forecasting accuracy across multiple powertrain transitions. Acquisition targets should demonstrate geographic density in EPA Phase 3 compliance corridors. The signal to watch is CARB rule propagation velocity to adjacent state jurisdictions, which would accelerate portfolio rebalancing toward zero-emission equipment financing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Unified fleet dashboards reduce reporting fragmentation for mixed-brand operators under single lessor contracts. |
| Zero-Emission Equipment Financing | Battery-electric Class 8 tractor leasing addresses EPA Phase 3 compliance without ownership risk transfer. |
| Cross-Border Servicing Network | Bilingual operations along I-35 penetrate peso-denominated payment demand from Mexico-linked carriers. |
| Predictive Maintenance Bundling | Sensor-enabled downtime reduction justifies premium lease rates for small-fleet owner-operators. |
| Residual Value Pool Expansion | Manufacturer-captive structures absorb remarketing risk below independent lessor pricing floors. |
Research Methodology
Operator-level perspectives from fleet managers, captive finance executives, independent lessor underwriting heads, and telematics platform engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, EPA regulatory dockets, and commercial vehicle registration databases. Bottom-up lease origination modeling triangulated against top-down freight demand projections from logistics trade associations.
Sensitivity analysis tested residual value assumptions across diesel, hybrid, and battery-electric powertrain depreciation curves. Segmentation dimensions modeled include lease structure type, truck classification tier, contract duration band, end-user category, and geographic compliance corridor. CAGRs were derived from fitted growth curves across the projection horizon. Industry-specific forecast inputs incorporated EPA Phase 3 implementation timelines and CARB Advanced Clean Trucks rule adoption patterns.
Forecasts assume regulatory continuity in EPA and CARB regimes; material policy shifts would require re-modeling of replacement cycle assumptions and residual value guarantee pricing. Practitioners should keep alternative scenarios live as battery-electric truck remarketing data accumulates and interstate compliance complexity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Invoice Factoring Market