
 Florida Digital Lending Market | 2026-2036
Florida Digital Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Florida Digital Lending Market Insights
Cloud-native core banking infrastructure is repositioning legacy mainframe-dependent lenders toward real-time decisioning economics. Ally Financial Inc. leverages its digital-first auto lending platform to sustain margin advantages in direct-to-consumer channels. VyStar Credit Union anchors member acquisition through Jacksonville-centric mobile app penetration. TD Bank competes via its Southeast U.S. digital mortgage origination stack, while LendingPoint LLC specializes in near-prime personal loan algorithms that differentiate risk pricing from traditional FICO-centric models.
Florida digital lending encompasses algorithmic credit origination, automated income verification, and API-driven fund disbursement delivered through web and mobile interfaces, with typical decision timelines compressed from weeks to minutes via machine learning models trained on alternative data streams. Personal loans and small business loans command the largest current transaction volumes, though AI-based underwriting platforms capture disproportionate technology investment as lenders seek to reduce manual review costs. Mobile apps and online portals now dominate distribution, displacing branch-dependent origination as Florida's demographic shift toward tech-native millennials and Gen Z borrowers accelerates channel migration.
The Florida Office of Financial Regulation enforces state-specific licensing and disclosure mandates that shape platform compliance architecture, while the Consumer Financial Protection Bureau's federal oversight of fair lending algorithms constrains model development choices for multistate operators. The Florida Information Protection Act imposes data breach notification standards that elevate cybersecurity spending requirements for cloud-hosted lending infrastructure. Stakeholders must monitor evolving state-federal regulatory friction points around artificial intelligence transparency rules to anticipate compliance cost trajectories and competitive barriers to algorithmic lending expansion.
Market Dynamics
Cloud-native core banking infrastructure is compressing decision timelines from weeks to minutes, forcing legacy mainframe-dependent lenders toward real-time underwriting economics or irrelevance. The Florida Office of Financial Regulation's tightening compliance framework for automated platforms intensifies this structural pressure.
Growth Catalysts
- Florida Information Protection Act:Data breach notification standards elevate cybersecurity spending requirements, creating competitive moats for cloud-hosted infrastructure providers with pre-certified compliance architectures.
- Millennial and Gen Z borrower migration:Tech-native demographics across the Miami-Orlando corridor accelerate channel shift from branch-dependent origination toward mobile-first distribution platforms.
- Alternative data integration:Machine learning models trained on non-FICO streams enable near-prime risk pricing differentiation, expanding addressable borrower pools beyond traditional credit bureau coverage.
Market Restraints
- State-federal regulatory friction:The Consumer Financial Protection Bureau's fair lending algorithm oversight constrains model development choices for multistate operators seeking Florida market entry.
- Legacy core dependency:Mainframe-bound credit unions face integration complexity and talent scarcity when migrating to API-driven disbursement systems.
- Credit union transformation bottlenecks:Jacksonville-centric mobile app penetration lags Tampa Bay metro velocity, creating geographic capability gaps within Florida's fastest-growing digital lending corridor.
Strategic Opportunities
- Tampa Bay metro acceleration:Credit union digital transformation initiatives concentrate most intensely in this sub-region, creating white space for platform providers with Jacksonville-to-Miami expansion playbooks.
- Small business algorithmic origination:Near-prime personal loan underwriting expertise transfers to SMB lending, where automated income verification reduces manual review costs disproportionately.
- AI transparency rule preparation:Early compliance architecture for emerging artificial intelligence disclosure mandates positions operators ahead of Florida Office of Financial Regulation enforcement curves.
Industry Challenges
- Cloud infrastructure talent scarcity:Real-time decisioning economics require specialized machine learning operations expertise that concentrates in Miami and Orlando metro talent pools.
- Automated underwriting certification timelines:Florida Office of Financial Regulation licensing mandates extend platform launch schedules, compressing first-mover advantages for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Florida Digital Lending Market |
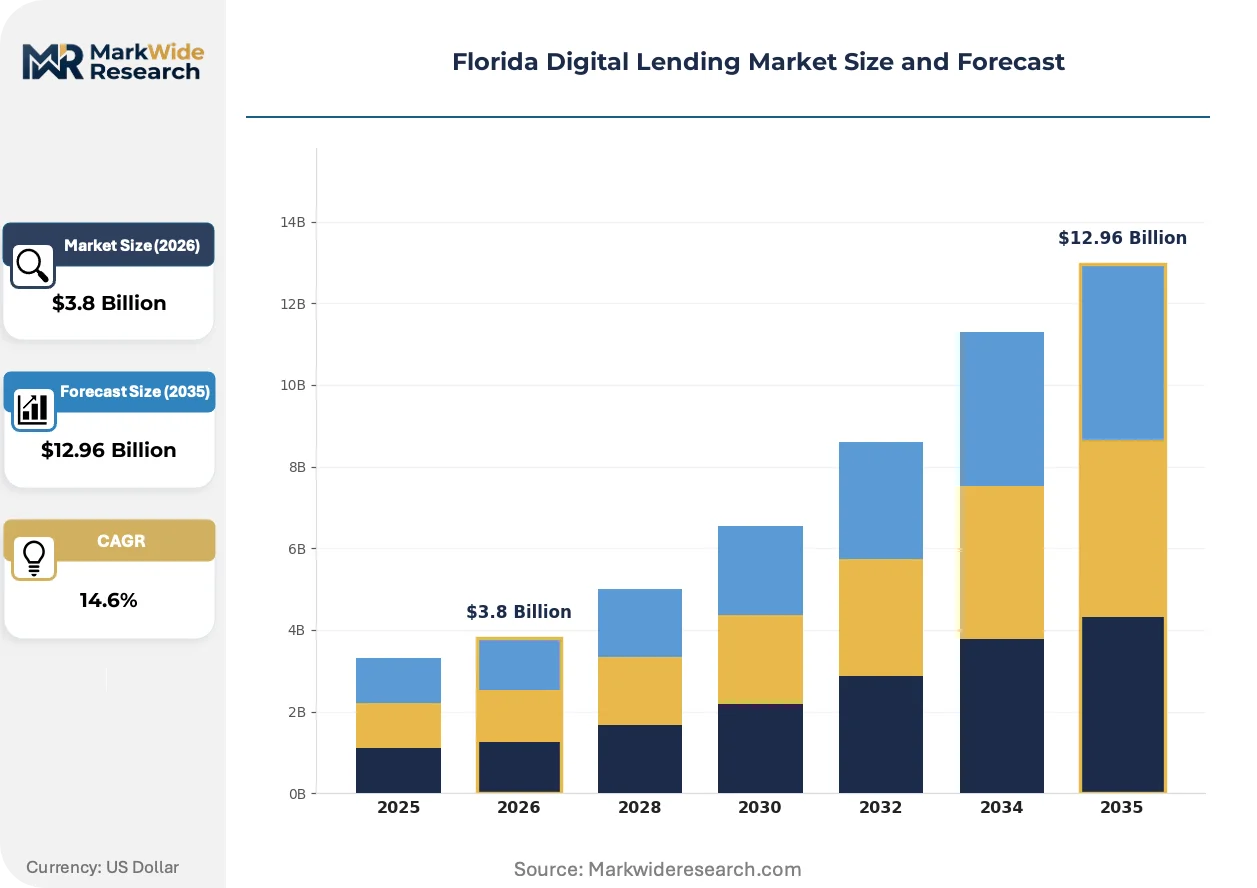
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Personal Loans, Mortgage Loans, Auto Loans, Small Business Loans, Student Loans Technology: AI-Based Underwriting, Blockchain, Machine Learning, Cloud Computing, Big Data Analytics End User: Individual Borrowers, Entrepreneurs, Real Estate Developers, Vehicle Buyers, Graduates Distribution Channel: Mobile Apps, Online Portals, Partner Networks, Direct Bank Websites, Financial Advisors |
| Companies Covered | Ally Financial Inc., VyStar Credit Union, TD Bank, Florida Credit Union, LendingPoint LLC, Navy Federal Credit Union, Suncoast Credit Union, Wells Fargo, Credible, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Florida Digital Lending Market Trends and Innovations
Algorithmic credit origination is actively compressing traditional underwriting timelines, with machine learning models displacing manual review at the point of borrower acquisition. Three interconnected developments define this transformation.
API-driven income verification is expanding into small business lending workflows, where automated bank account analysis replaces document-based proof-of-revenue submission. Miami-Orridor corridor SMB owners adopt these platforms fastest, compressing fund disbursement from days to hours and enabling working capital solutions that match cash flow velocity rather than static collateral requirements.
The Florida Office of Financial Regulation's digital lending oversight framework is tightening disclosure mandates for automated underwriting platforms. This industrial consequence elevates compliance architecture to competitive differentiator status, with multistate operators most affected as they reconcile Florida-specific requirements against Consumer Financial Protection Bureau fair lending algorithm constraints through dual-track model governance systems.
Borrower channel preference is fragmenting across generational lines, with branch-dependent origination collapsing among tech-native millennials while Gen Z demand concentrates exclusively in mobile-first interfaces. Credit unions across the Tampa Bay metro area respond through accelerated digital transformation initiatives, displacing in-person relationship banking with Jacksonville-centric mobile app penetration strategies that anchor member acquisition without physical infrastructure investment.
Florida Digital Lending Market Segmentation
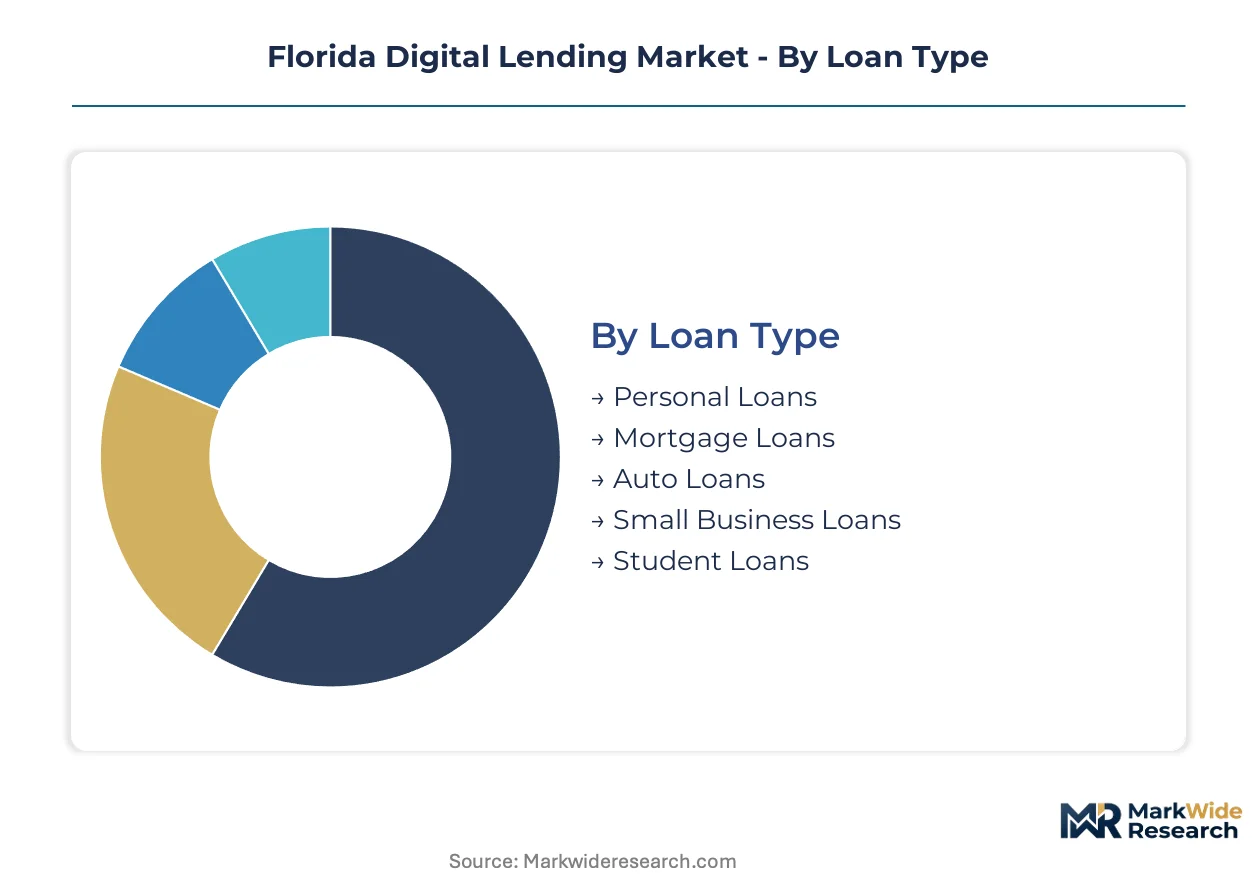
Florida's digital lending market fragments across loan purpose, technology stack, borrower profile, and acquisition channel. Each dimension carries distinct margin structures and regulatory exposure that shape platform economics and competitive positioning.
Loan Type:
Personal and small business products dominate transaction velocity, while mortgage and auto lending concentrate value per origination.
- Personal Loans:Unsecured credit products with algorithmic risk pricing based on alternative data streams. Demand concentrates most intensely among tech-native millennials across the Miami-Orlando corridor, where near-prime borrowers seek FICO-agnostic underwriting.
- Small Business Loans:Working capital and equipment financing delivered through automated income verification. Tampa Bay metro credit unions drive fastest adoption as legacy mainframe migration accelerates API-driven disbursement capabilities.
- Mortgage Loans:Digital origination with automated asset and income verification. TD Bank's Southeast U.S. stack anchors competitive positioning in this higher-ticket, longer-cycle segment.
- Auto Loans:Direct-to-consumer and dealer-integrated financing. Ally Financial's digital-first platform sustains margin advantages through real-time decisioning economics.
- Student Loans:Education financing with deferred repayment structures. Regulatory complexity under federal oversight constrains pure-play Florida operator entry.
Today's leader: Personal Loans. Tomorrow's challenger: Small Business Loans.
Technology:
Cloud infrastructure and machine learning operations talent scarcity in Jacksonville creates geographic capability gaps against Miami-Orlando concentration.
- AI-Based Underwriting:Neural networks trained on non-traditional data for real-time credit decisions. Florida Office of Financial Regulation tightening disclosure mandates elevates compliance architecture to competitive differentiator status.
- Machine Learning:Predictive models for default probability and fraud detection. LendingPoint LLC deploys near-prime algorithms that differentiate risk pricing from traditional FICO-centric approaches.
- Cloud Computing:Elastic infrastructure for loan origination platforms. Pre-certified compliance architectures under Florida Information Protection Act create competitive moats for hosted providers.
- Big Data Analytics:Aggregated borrower behavior analysis for product development. Credit unions leverage member transaction histories to anchor Jacksonville-centric mobile app penetration.
- Blockchain:Distributed ledger applications for loan documentation and secondary market transparency. Adoption lags other technologies due to regulatory uncertainty under state-federal oversight friction.
Machine Learning commands current investment intensity. AI-Based Underwriting faces steepest regulatory compliance trajectory.
End User:
Borrower sophistication and collateral availability segment risk pricing and channel preference.
- Individual Borrowers:Consumer credit demand spanning debt consolidation to emergency liquidity. Mobile-first interfaces displace branch-dependent origination as Gen Z preference concentrates exclusively in app-based acquisition.
- Entrepreneurs:Small business owners seeking working capital without traditional collateral. Automated bank account analysis replaces document-based proof-of-revenue across the Miami-Orlando corridor fastest.
- Real Estate Developers:Commercial construction and acquisition financing. Higher ticket sizes justify enhanced due diligence despite automated platform economics.
- Vehicle Buyers:Point-of-sale and direct auto financing. Direct-to-consumer channels gain share against dealer-integrated legacy arrangements.
- Graduates:Refinancing and new origination for education debt. Federal program complexity limits state-specific platform differentiation.
Individual Borrowers anchor volume. Entrepreneurs are climbing the fastest as SMB algorithmic origination transfers personal loan underwriting expertise.
Distribution Channel:
Channel economics shift decisively toward zero-marginal-cost digital acquisition.
- Mobile Apps:Native iOS and Android interfaces with biometric authentication. VyStar Credit Union anchors member acquisition through Jacksonville-centric penetration strategies without physical infrastructure.
- Online Portals:Web-based origination with document upload and e-signature. Tampa Bay metro credit union transformation initiatives concentrate most intensely in this sub-region.
- Partner Networks:Embedded finance through retail and service provider integrations. Auto dealers and home improvement contractors originate loans at point of need.
- Direct Bank Websites:Institution-branded platforms for existing customer cross-sell. Legacy mainframe-dependent lenders face integration complexity when migrating to API-driven systems.
- Financial Advisors:Human-mediated origination for complex or high-value transactions. Channel share collapses as automated underwriting compresses decision timelines from weeks to minutes.
Mobile Apps dominate acquisition economics. Partner Networks offer steepest expansion trajectory through embedded finance penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Miami-Orlando corridor anchors Florida's digital lending expansion, with Tampa Bay metro credit unions accelerating cloud-native transformation fastest among legacy institutions.
Southeast Florida
Miami-Dade and Broward counties concentrate fintech talent pools and venture capital deployment for algorithmic underwriting platforms. The Florida Office of Financial Regulation enforces state-specific licensing mandates that extend platform launch timelines for new entrants. Brickell and Wynwood districts host machine learning operations teams developing alternative data credit models for near-prime borrower segments.
Central Florida
Orlando's millennial-heavy workforce drives mobile-first personal loan demand through embedded finance partnerships with hospitality and service sector employers. Orange County's economic development incentives attract cloud infrastructure providers seeking Florida Information Protection Act pre-certified compliance architectures. The Lake Nona medical city cluster spurs healthcare worker-focused lending products with automated income verification.
Tampa Bay Metro
Pinellas and Hillsborough county credit unions lead statewide digital transformation velocity, displacing branch-dependent origination with API-driven disbursement systems. Tampa's regional banking hub status concentrates compliance architecture talent for automated underwriting platform governance. St. Petersburg fintech incubators accelerate small business algorithmic origination pilots targeting working capital gaps.
Northeast Florida
Jacksonville's Navy and logistics workforce sustains steady demand for auto and personal loan products through direct-to-consumer digital channels. Duval County credit unions lag Tampa Bay cloud migration pace, creating white space for platform providers with proven expansion playbooks. VyStar Credit Union anchors member acquisition through mobile app penetration without physical infrastructure investment.
Southwest Florida
Collier and Lee counties' retiree demographics constrain pure digital adoption, sustaining hybrid origination models with advisor-mediated complex transactions. Sarasota's wealth management concentration elevates high-ticket loan products requiring enhanced due diligence despite automated platform economics. Cape Coral's small business density drives working capital demand through automated bank account analysis replacing document-based revenue proof.
Florida Digital Lending Market Competitive Landscape
Global majors compete with regional champions across distribution channel economics, with national banks leveraging balance sheet scale against credit union member loyalty advantages and fintech algorithmic speed. Market structure fragments across three tiers: legacy institutions modernizing core infrastructure, digital-native lenders with alternative data expertise, and credit unions accelerating mobile transformation. Strategic archetypes include cloud-native direct lenders, hybrid bank-fintech partnerships, and member-owned cooperative platforms. Competitive intensity concentrates in M&A activity targeting underwriting technology capabilities and geographic expansion into underserved Florida sub-markets.
Within the credit union archetype, VyStar Credit Union and Suncoast Credit Union exemplify member-owned platforms prioritizing mobile-first acquisition over branch infrastructure, while Ally Financial Inc. represents the digital-native direct lender model with auto lending specialization. Navy Federal Credit Union occupies a unique position serving military-affiliated borrowers with federal charter advantages. TD Bank exemplifies the regional bank tier competing through Southeast U.S. digital mortgage origination stacks against national scale competitors.
| Leading Market Players |
|---|
| Ally Financial Inc. |
| VyStar Credit Union |
| TD Bank |
| Florida Credit Union |
| LendingPoint LLC |
| Navy Federal Credit Union |
| Suncoast Credit Union |
| Wells Fargo |
| Credible |
| Others |
Pricing and Supply Chain Analysis
Private-equity-backed fintech platforms anchor Florida's digital lending supply structure, compressing origination costs through cloud-native infrastructure while extracting pricing premiums via real-time underwriting capabilities that legacy mainframe-dependent credit unions cannot replicate.
Pricing Analysis
Cloud infrastructure and machine learning operations talent costs in Miami and Orlando metros pass through to platform origination fees, with three-tier pricing structure across premium, standard, and economy levels differentiating by decision speed and alternative data depth. Price differentiation hinges on API integration complexity and Florida Office of Financial Regulation compliance certification status, with uncertified operators facing margin compression from extended licensing timelines. Pricing pressure stems from Tampa Bay credit union digital transformation initiatives undercutting fintech premiums through member-owned cooperative economics. Small business borrowers exhibit highest price sensitivity, while real estate developers absorb premium tier costs for enhanced due diligence.
Supply Chain Analysis
Regional data centers in Miami, Orlando, and Tampa Bay form the hub-and-spoke distribution layer for algorithmic underwriting platforms, with cloud computing infrastructure drawing from Virginia, Texas, and California hyperscaler facilities. Machine learning model training relies on alternative data aggregators, credit bureau APIs, and bank account verification services. Single-source vulnerability concentrates in cloud infrastructure providers, where Florida Information Protection Act compliance certification creates switching friction. Distribution runs through mobile app stores and direct-to-consumer web portals, displacing branch-dependent origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Florida digital lending offers margin expansion through automated underwriting cost compression and near-prime borrower premium capture, with cloud-native infrastructure reducing per-loan origination expense below legacy mainframe economics.
For Market Incumbents: Extend API-driven disbursement capabilities into small business lending workflows before Tampa Bay credit union transformation initiatives capture working capital market share. Fortify Florida Office of Financial Regulation compliance architecture ahead of artificial intelligence transparency rule enforcement. Backward integration into alternative data aggregation reduces third-party API dependency and anchors pricing power.
For New Entrants and Emerging Players: Begin with Jacksonville-centric mobile app penetration targeting Navy and logistics workforce segments where VyStar Credit Union's geographic concentration leaves acquisition white space. Automated income verification for near-prime personal loans transfers to SMB lending with minimal model retraining. Embedded finance partnerships with hospitality employers across Orlando's service economy offer lowest customer acquisition cost.
For Investors and Strategic Acquirers: Regional banks with Southeast U.S. digital mortgage stacks are the most active acquirer in this space, seeking algorithmic underwriting capabilities to offset branch infrastructure depreciation. Long-term viability rests on dual-track model governance reconciling state and federal regulatory frameworks. Monitor Florida Office of Financial Regulation enforcement curve acceleration as inflection indicator for compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Real-time decisioning economics displace legacy mainframe cost structures across Tampa Bay credit unions. |
| AI Transparency Compliance Architecture | Pre-built disclosure systems position operators ahead of Florida Office of Financial Regulation enforcement curves. |
| Alternative Data Partnership | Non-FICO stream integration expands addressable borrower pools beyond traditional credit bureau coverage. |
| Embedded Finance Integration | Point-of-need origination through hospitality and healthcare employers captures Orlando millennial demand. |
| Geographic Expansion Playbook | Proven Jacksonville-to-Miami deployment templates exploit credit union transformation velocity gaps. |
Research Methodology
Multiple input streams — executive interviews with digital lending platform CTOs, regulatory affairs specialists at the Florida Office of Financial Regulation, credit union digital transformation officers, and alternative data aggregator product leads — were reconciled against SEC 10-K filings, cloud infrastructure provider compliance disclosures, and Florida Information Protection Act enforcement records. Bottom-up transaction volume modeling and top-down macroeconomic triangulation validated segment-level projections.
Historical origination velocity cross-referenced against panel input from machine learning operations specialists and mobile app penetration strategists anchored growth assumptions across the projection horizon. Segmentation dimensions modeled encompass loan purpose, technology stack sophistication, borrower credit tier, and acquisition channel economics. CAGRs derived from elasticity analysis of cloud infrastructure adoption curves and regulatory compliance cost trajectories, with alternative data integration penetration serving as primary demand-side input.
Caveats apply where Florida Office of Financial Regulation artificial intelligence disclosure mandates or Consumer Financial Protection Bureau fair lending algorithm constraints could materially shift the outlook for multistate operator economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Factoring Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Truck Financial Leasing Market